
 Global Industrial Automation Cable Market | 2026-2036
Global Industrial Automation Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Automation Cable Market Outlook
The shift from single-source to multi-source cable procurement is recalibrating how industrial buyers manage supply risk. Prysmian Group leverages its integrated optical fiber and copper capabilities to anchor European infrastructure projects. Belden specializes in precision-engineered data cables for deterministic Ethernet networks. Sumitomo Electric Industries extends its position through advanced polymer compounding for high-flex industrial environments.
Industrial automation cables are engineered conductors with specified insulation systems, shielding configurations, and temperature ratings designed to transmit power, control signals, and data in factory environments where electromagnetic interference, mechanical flexing, and chemical exposure degrade standard wiring. Control cables dominate volume demand in discrete manufacturing, while optical fiber technology within the Ethernet segment captures premium positioning as machine-to-machine bandwidth requirements escalate. Power cables serving oil and gas applications sustain higher margin pools due to flame-retardant and hydrocarbon-resistant specification tiers.
FDA, EPA, and OSHA standards in the United States impose material safety and workplace installation requirements that shape product certification pathways. REACH and RoHS frameworks in Europe restrict hazardous substances in cable jackets and insulation compounds, forcing reformulation investments. Stakeholders must monitor how IEC and ISO harmonization efforts around industrial Ethernet cabling standards will reshape interoperability requirements and testing protocols across supplier ecosystems.
Market Dynamics
Multi-source procurement strategies are restructuring supplier relationships across factory automation networks, compelling cable manufacturers to diversify production footprints and certification portfolios beyond legacy single-region dependencies.
Growth Catalysts
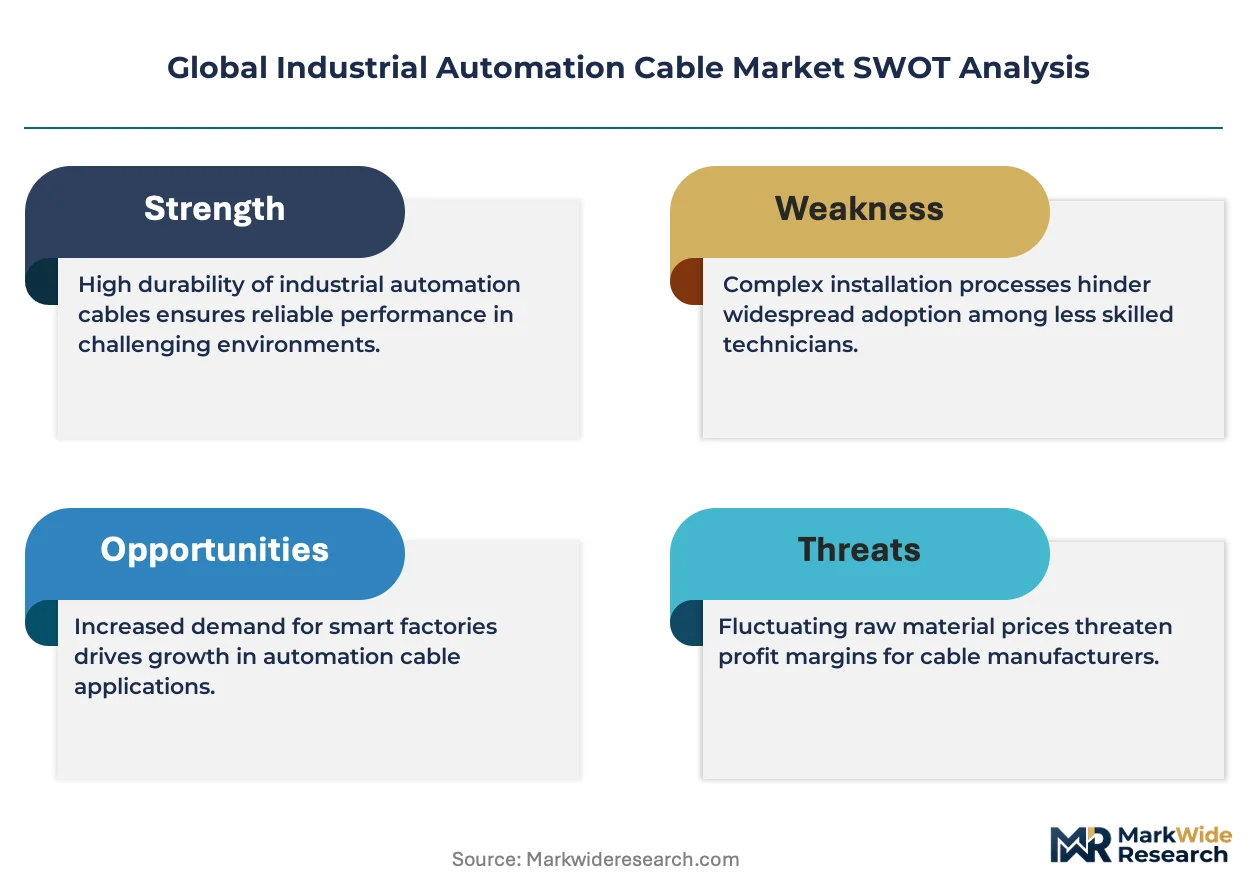
- REACH and RoHS compliance mandates:European ECHA enforcement is accelerating halogen-free compound reformulation across jacketing suppliers, creating specification premiums for compliant producers.
- Robotic workcell densification:Automotive assembly plants in Germany, China, and the United States are expanding high-flex cable procurement for six-axis articulated arms and collaborative robot installations.
- Machine-to-machine bandwidth escalation:Deterministic Ethernet protocols are displacing fieldbus architectures in discrete manufacturing, elevating demand for shielded twisted-pair and fiber-optic industrial cabling.
Market Restraints
- Copper and polymer feedstock volatility:LME copper price swings and specialty polymer supply tightness compress margin predictability for compound-dependent jacketing operations.
- Concentrated optical fiber preform supply:Vapor-phase axial deposition capacity clusters in Japan and the United States create bottleneck risk for fiber-intensive automation networks.
- Legacy fieldbus protocol persistence:Installed bases of PROFIBUS and DeviceNet architectures slow Ethernet migration timelines in brownfield manufacturing facilities.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentive structures for electronics and automotive sectors are attracting cable suppliers to establish localized compounding and extrusion capacity.
- Subsea and offshore petrochemical expansion:Hydrocarbon-resistant power cable specifications for Brazil's pre-salt fields and Saudi Arabia's Red Coast developments command premium positioning.
- Digital twin integration:Cable manufacturers embedding RFID and sensor diagnostics into jacketing are capturing predictive maintenance service contracts alongside hardware sales.
Industry Challenges
- Cross-disciplinary engineering talent scarcity:Compound chemists with simultaneous polymer science and electromagnetic compatibility expertise command compensation premiums that strain R&D staffing models.
- IEC 61158 interoperability certification timelines:Multi-protocol testing for industrial Ethernet variants extends product launch cycles and defers revenue recognition.
- Legacy M12 connector integration complexity:Retrofitting deterministic Ethernet signaling through existing connector geometries requires custom shielding redesigns that fragment SKU portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Automation Cable Market |
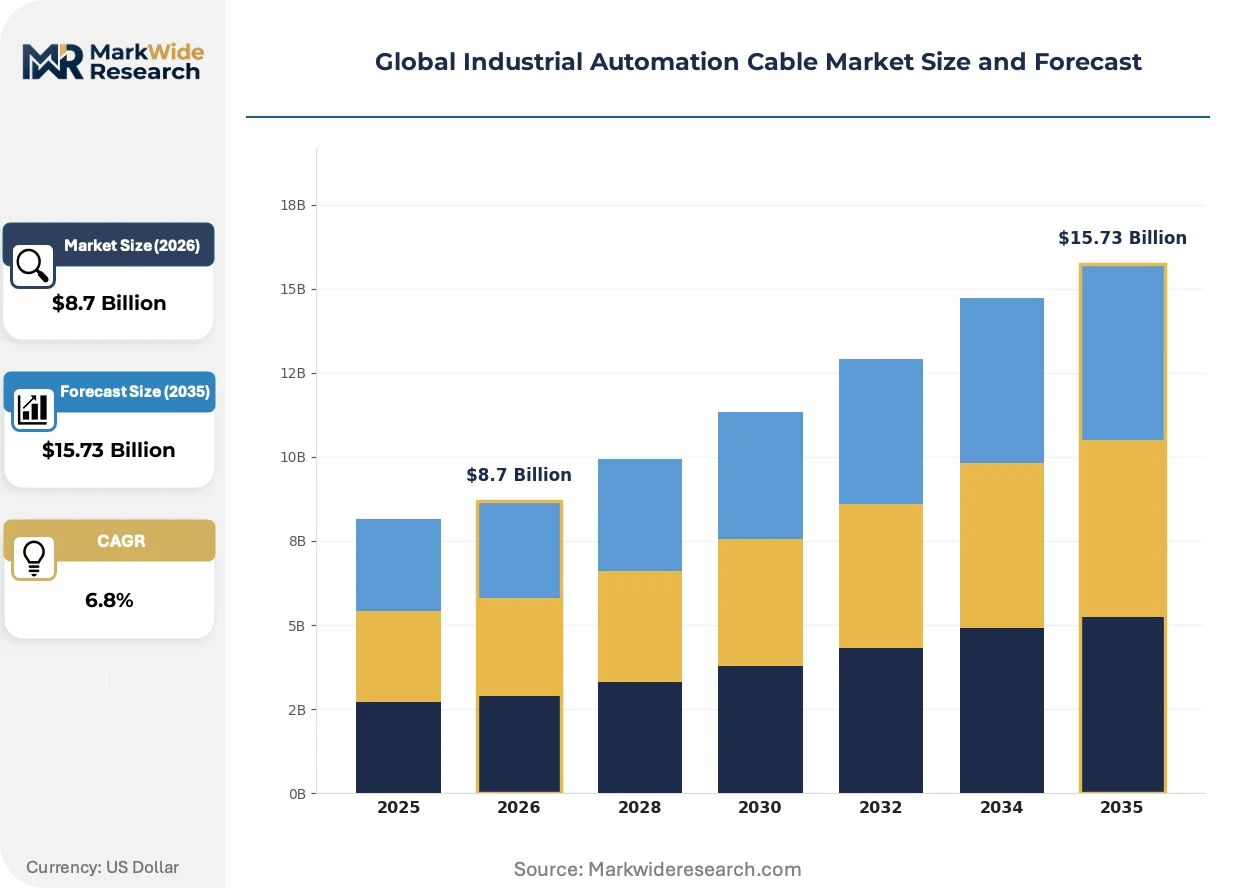
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Control Cables, Instrumentation Cables, Power Cables, Data Cables Application: Manufacturing, Automotive, Oil & Gas, Pharmaceuticals Technology: Ethernet, Fieldbus, Wireless, Optical Fiber End User: OEMs, System Integrators, Manufacturers, Industrial Plants |
| Companies Covered | Belden, Lorom Industrial, Prysmian Group, Sumitomo Electric Industries, Eland Cables, Nexans, HELU KABEL, Southwire Company, LEONI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Automation Cable Market Strategic Shifts
Deterministic networking requirements and sustainable material mandates are converging to redefine cable specification hierarchies, with performance differentiation migrating from conductor gauge to jacketing intelligence and embedded diagnostics.
Thermoplastic elastomer compounds with integrated flame-retardant mineral fillers are absorbing the functional requirements previously served by halogenated PVC jacketing in European automotive and rail applications. Tier-one suppliers in Germany and France are qualifying these materials for continuous flex ratings exceeding ten million cycles. The transition is compressing incumbent halogenated compound volumes while expanding premium positioning for bio-based polyamide alternatives.
ECHA's SCIP database obligations under the EU Waste Framework Directive are mandating supply-chain disclosure of Substances of Very High Concern throughout cable lifecycles. Manufacturers serving German industrial corridors must now document SVHC content in insulation systems down to 0.1% weight-by-weight thresholds. The compliance burden is accelerating consolidation among compounders with in-house toxicology and regulatory filing capabilities.
Buyers in China's Yangtze River Delta manufacturing belt are unbundling cable procurement from integrated automation system contracts, establishing direct sourcing relationships with specialized producers for high-flex and drag-chain applications. This disintermediation is compressing distributor margins while elevating technical specification authority among factory maintenance engineers versus system integrators. Japanese automotive transplants in Thailand and Indonesia are replicating this model, establishing regional cable qualification labs to accelerate vendor onboarding.
Global Industrial Automation Cable Market Segmentation
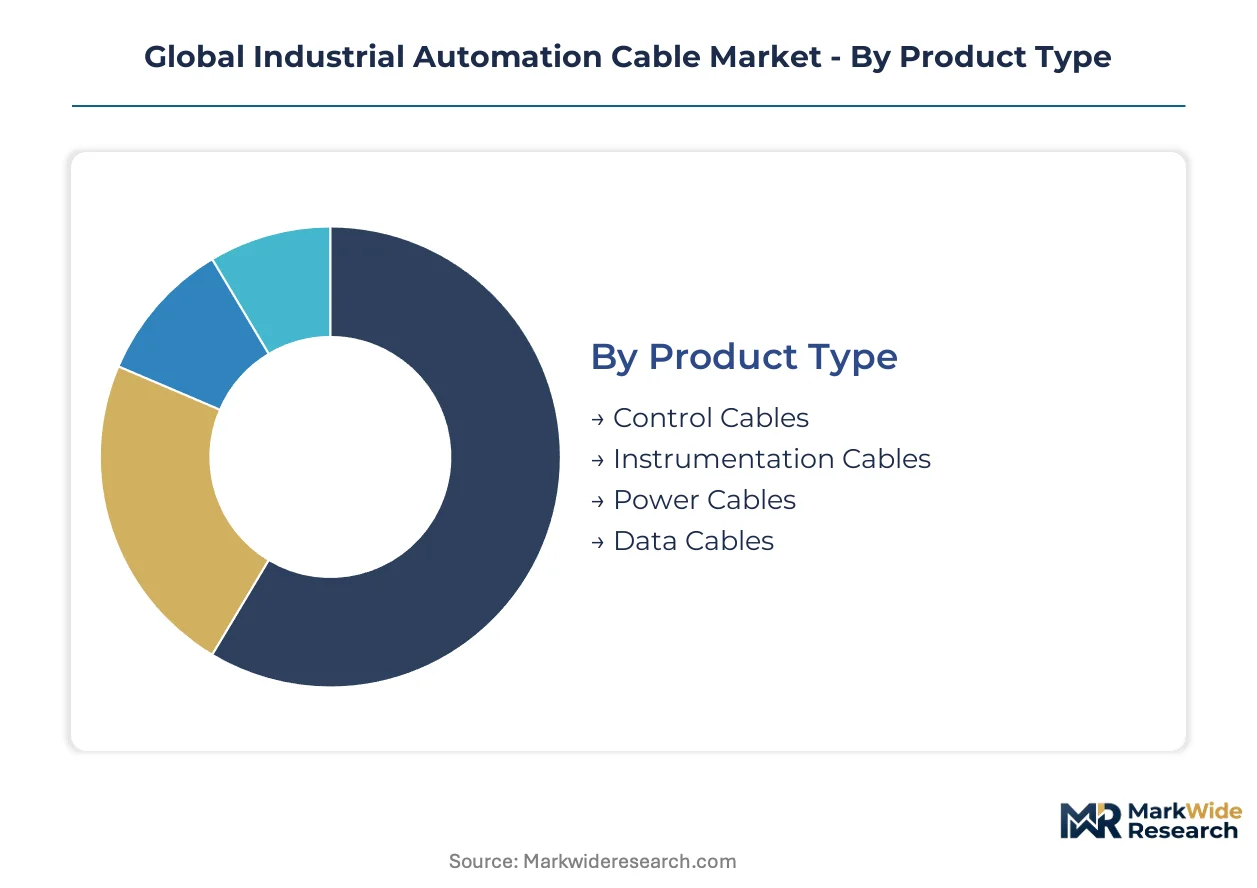
Cable specification hierarchies in factory automation diverge sharply based on whether conductors operate in standalone power distribution or embed within integrated control architectures. Segmentation reveals how insulation systems, shielding configurations, and bandwidth ratings align with distinct procurement workflows across discrete manufacturing, process industries, and hybrid facilities.
Product Type:
Integration depth varies substantially across product categories, with some cable families engineered for point-to-point power delivery while others embed sensor diagnostics and deterministic signaling within jacketing systems.
- Control Cables:Multi-conductor assemblies with PVC or TPE insulation rated for 300-600V signal transmission in relay logic and motor starter circuits. Discrete manufacturing facilities in Germany's industrial corridor deploy these for conveyor sequencing and pneumatic valve actuation where electromagnetic compatibility requirements remain moderate.
- Data Cables:Shielded twisted-pair and fiber-optic constructions engineered for deterministic Ethernet protocols with impedance tolerances of 100±15 ohms. Automotive assembly plants in China's Yangtze River Delta specify these for PROFINET and EtherCAT machine-to-machine communication where cycle times fall below 1 millisecond.
- Power Cables:Cross-linked polyethylene insulated conductors rated for 600V to 35kV distribution in heavy machinery and process equipment.
- Instrumentation Cables:Paired conductors with individual and overall shields for 4-20mA analog signal integrity in sensor loops.
Volume placements concentrate in Control Cables; the faster expansion belongs to Data Cables.
Application:
Cost tier stratification separates specification-intensive process industries from price-sensitive discrete manufacturing, with margin structures diverging based on certification requirements and replacement cycle length.
- Oil & Gas:Hydrocarbon-resistant and flame-retardant cable specifications for offshore platforms, refineries, and petrochemical complexes. Brazil's pre-salt developments and Saudi Arabia's Red Coast expansions command premium-grade power and control cable with mud-resistant jacketing and continuous flex ratings for topside processing equipment.
- Automotive:High-flex and torsion-rated cables for robotic welding, paint application, and final assembly operations. OEMs in the US Gulf Coast and Thailand's Eastern Economic Corridor specify these for six-axis articulated arms where motion cycles exceed ten million bends.
- Manufacturing:General-purpose control and power distribution for material handling, packaging, and assembly operations.
- Pharmaceuticals:FDA-compliant cable constructions with smooth jacketing surfaces for cleanroom washdown compatibility.
Revenue concentration sits with Oil & Gas; Automotive applications are climbing the fastest.
Technology:
Customer type alignment shapes procurement authority, with system integrators favoring legacy fieldbus compatibility while industrial plants with in-house engineering teams drive Ethernet migration.
- Ethernet:Industrial variants including PROFINET, EtherNet/IP, and EtherCAT with real-time determinism through prioritized frame forwarding. German automotive transplants in the United States specify shielded twisted-pair and fiber-optic constructions for synchronized motion control where jitter tolerance falls below 1 microsecond.
- Optical Fiber:Single-mode and multimode glass fiber for long-reach backbones and electromagnetic immunity in welding cells. Japan's vapor-phase axial deposition preform supply feeds cable extrusion for high-bandwidth machine vision and safety network applications.
- Fieldbus:Legacy PROFIBUS and DeviceNet architectures persisting in brownfield facilities with installed base constraints.
- Wireless:Industrial Wi-Fi and 5G private networks for mobile equipment and temporary installations.
Fieldbus retains volume dominance; Optical Fiber is gaining share fastest.
End User:
Supply concentration differs across procurement channels, with OEMs consolidating volumes through frame contracts while industrial plants fragment demand across maintenance-driven spot purchasing.
- System Integrators:Engineering firms specifying cable bundles within turnkey automation projects. China's Yangtze River Delta manufacturing belt shows disintermediation pressure as factory maintenance engineers establish direct sourcing relationships with specialized cable producers.
- Industrial Plants:End-user facilities with captive procurement teams managing MRO inventory and capital project specifications. REACH and RoHS compliance mandates from ECHA drive reformulation investments for halogen-free jacketing in European-owned facilities across multiple geographies.
- OEMs:Original equipment manufacturers embedding cables in machinery prior to shipment.
- Manufacturers:Mid-sized production facilities with hybrid sourcing through distributors and direct channels.
Procurement volume pools with Industrial Plants; System Integrators show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate supply from Chile and Peru underpins raw-material security for cable manufacturers serving industrial automation demand across multiple continents.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg are expanding high-flex cable procurement for robotic welding cells. ECHA enforcement of REACH Article 33 SCIP database obligations forces compounders to document SVHC content down to 0.1% weight-by-weight. Stuttgart's industrial corridor hosts qualification labs where tier-one suppliers test halogen-free thermoplastic elastomer compounds for continuous flex ratings exceeding ten million cycles.
China
Factories in the Yangtze River Delta manufacturing belt are unbundling cable procurement from integrated automation contracts to source directly from specialized producers. MIIT's GB standards for industrial Ethernet cabling accelerate deterministic protocol adoption across machine tool builders. Suzhou and Wuxi host extrusion facilities supplying drag-chain-rated cables to automotive transplants expanding six-axis articulated arm deployments.
United States
OSHA electrical safety standards and NEC installation codes shape certification pathways for cables serving Gulf Coast petrochemical complexes. The US Gulf Coast hub sustains premium demand for flame-retardant power cables with hydrocarbon-resistant jacketing for offshore platform topside equipment. Houston-area distributors maintain inventory pools for maintenance-driven spot purchasing by refinery operators.
Japan
Vapor-phase axial deposition preform capacity clusters feed fiber-optic cable extrusion for high-bandwidth machine vision networks. METI's industrial competitiveness policies support advanced polymer compounding R&D for high-flex industrial environments. Nagoya's Chubu region anchors production of shielded twisted-pair constructions for synchronized motion control applications.
India
PLI scheme incentives for electronics and automotive manufacturing attract cable suppliers to establish localized compounding capacity. BIS certification requirements for electrical cables create compliance barriers that favor domestic producers with in-house testing laboratories. Maharashtra's Pune-Nashik industrial belt hosts qualification programs where Japanese automotive transplants validate regional cable vendors.
Global Industrial Automation Cable Market Competitive Environment
Capacity expansion dominates the current landscape as compounders add extrusion lines to serve geographically dispersed automation clusters. The vendor base organizes into three tiers: integrated conglomerates with optical fiber and copper capabilities, specialized precision-engineered data cable producers, and regional extrusion specialists serving maintenance-driven spot demand. Strategic archetypes include halogen-free compound innovators, deterministic Ethernet certification leaders, and high-flex lifecycle testing specialists. Geographic expansion and portfolio diversification represent the dominant competitive moves as manufacturers seek to reduce single-region dependencies.
Among European-integrated cable producers, Prysmian Group and Nexans occupy positions spanning infrastructure-scale power distribution through precision industrial automation segments. Belden exemplifies the specialist archetype focused on deterministic Ethernet network applications. Sumitomo Electric Industries anchors the advanced polymer compounding tier for high-flex industrial environments. Japanese and German producers collectively represent the quality-certification leadership segment where IEC 61158 interoperability testing extends product launch timelines.
| Leading Market Players |
|---|
| Belden |
| Lorom Industrial |
| Prysmian Group |
| Sumitomo Electric Industries |
| Eland Cables |
| Nexans |
| HELU KABEL |
| Southwire Company |
| LEONI |
| Others |
Value Chain & Pricing Dynamics
Backward integration into specialty polymer compounding anchors pricing power for European and Japanese cable manufacturers serving REACH-compliant automotive and rail contracts. Captive control over halogen-free thermoplastic elastomer formulations allows tier-one suppliers to extract specification premiums while insulating margin pools from LME copper volatility and third-party compounder markups.
Pricing Analysis
Warranty and lifecycle testing bundling separates premium-tier producers from commodity extruders in industrial automation cable procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by flex-cycle certification and deterministic Ethernet protocol compliance. Pricing pressure stems from unbundled procurement in China's Yangtze River Delta, where factory maintenance engineers negotiate direct contracts and compress distributor margins. System integrators demonstrate highest price sensitivity due to fixed project budgets, while oil and gas operators absorb premium positioning for hydrocarbon-resistant specifications.
Supply Chain Analysis
Dual-sourcing mandates from automotive OEMs in Germany, China, and the United States compel cable manufacturers to qualify secondary compounders and extrusion partners across multiple geographies. Raw material flows draw from Chilean copper concentrate, Japanese vapor-phase axial deposition preforms, and German specialty polymer feedstocks. Single-source vulnerability clusters in optical fiber preform capacity threaten fiber-intensive automation network deployments. Distribution runs through regional distributors serving maintenance-driven spot purchasing alongside direct frame contracts with OEMs and system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where ECHA SCIP database obligations and REACH Article 33 enforcement erect barrier-to-entry moats favoring compounders with in-house toxicology and regulatory filing capabilities.
For Market Incumbents: Cement qualification leadership by expanding Stuttgart and Nagoya testing lab capacity for halogen-free compound validation exceeding ten million flex cycles. Deepen backward integration into specialty polymer production to defend margin pools from feedstock volatility. Prioritize IEC 61158 multi-protocol certification investment to capture deterministic Ethernet migration timelines ahead of brownfield fieldbus replacement cycles.
For New Entrants and Emerging Players: Regional automotive transplants in Thailand and Indonesia represent underserved buyer archetypes establishing localized cable qualification labs to accelerate vendor onboarding. Target India's PLI scheme beneficiaries in Maharashtra's Pune-Nashik industrial belt with BIS-certified halogen-free constructions. Pursue qualification partnerships with Japanese automotive OEMs seeking secondary sourcing alternatives to incumbent German and Japanese suppliers.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated conglomerates seeking deterministic Ethernet certification assets and regional extrusion footprint. Long-term viability favors compounders with captive halogen-free formulation capabilities and SCIP database compliance infrastructure. Watch ECHA enforcement intensity against SVHC disclosure violations as inflection indicator for consolidation acceleration among sub-scale regional players.
| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Compound Capacity Expansion | ECHA REACH enforcement accelerates specification premiums for compliant European automotive and rail suppliers. |
| Deterministic Ethernet Certification Investment | IEC 61158 interoperability testing extends product launch cycles and defers revenue recognition for unprepared competitors. |
| Regional Extrusion Footprint Diversification | India's PLI scheme attracts localized compounding capacity to serve electronics and automotive manufacturing incentives. |
| Embedded Diagnostics Integration | RFID and sensor-enabled jacketing captures predictive maintenance service contracts alongside hardware sales. |
| Subsea Power Cable Qualification | Brazil's pre-salt and Saudi Arabia's Red Coast developments command premium hydrocarbon-resistant specifications. |
Study Parameters
Document review covered ECHA regulatory filings, IEC standardization committee records, and MIIT GB standard publications, complemented by interviews with plant engineers at German automotive OEMs, procurement leads at Chinese machine tool builders, cable compound technical directors, and aftermarket service heads at Gulf Coast petrochemical operators. Secondary validation drew from customs trade data, SEC 10-K disclosures by listed cable manufacturers, and industry association reports. Bottom-up demand modeling triangulated against top-down market sizing across the analysis window.
Cross-referencing historical capacity expansion patterns against panel input from compound R&D directors shaped the analytical framework. Segmentation dimensions modeled include product type integration depth, application cost tier stratification, technology protocol architecture, and end-user procurement channel authority. CAGRs were derived from installed base replacement cycle analysis and Ethernet migration trajectory assessment. Forecast inputs incorporated robotic workcell densification rates and REACH compliance cost pass-through elasticity.
Revisions become necessary when ECHA enforcement intensity exceeds baseline assumptions, copper price volatility disrupts compounder margin structures, or optical fiber preform supply bottlenecks constrain fiber-intensive network deployment. Deviation in any of these triggers would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Flat Flexible Cables Market
Cables
Coaxial Cable Market
Cables
Electric Submersible Cables (ESP) Market
Cables
Europe Cable Joints Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Submarine Cable System Market
Cables
EDM Wires Market
Cables
Middle East Cable Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Global Low Voltage Cable Market
Cables
North America HVAC Cables Market
Cables
Global Cable Gland Market
Cables
Wire and Cable Materials Market
Cables
Cable Detector Market
Cables
Class 1E Electric Cables Market
Cables
Cable Accessories Market