
 Global Low Voltage Cable Market | 2026-2036
Global Low Voltage Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Global Low Voltage Cable Market Foresight
Modular bundled cable configurations is rebalancing procurement patterns across utility and construction verticals as buyers seek reduced installation labor and faster commissioning. Prysmian Group leverages its integrated compound-to-cable manufacturing footprint to control material quality and delivery timelines. Nexans anchors its position through specialized subsea and harsh-environment low voltage portfolios. Southwire Company competes on regional manufacturing density and distributor channel coverage across North American infrastructure projects.
Low voltage cable encompasses insulated conductors rated below 1 kV AC or 1.5 kV DC, typically employing copper or aluminum cores with PVC, XLPE, or EPR insulation extruded through continuous vulcanization lines to deliver safe power transmission in buildings, industrial plants, and distribution networks. Thermoplastic jacketing dominates volume in residential and commercial electrical wiring due to lower material cost and processing speed, while thermoset insulation captures premium margin pools in data center and manufacturing plant applications where thermal endurance and fire resistance justify higher unit pricing. Underground installation commands structural priority in urban grid upgrades across mature economies, though aerial deployment persists in rural electrification and emerging market expansion where trenching costs prove prohibitive.
The EU Green Deal and REACH chemical frameworks constrain halogenated compound formulations, pushing compounders toward low-smoke zero-halogen alternatives that alter raw material procurement and extrusion equipment requirements. China's GB standards and SAMR certification protocols enforce conductor purity and dimensional tolerances that filter import eligibility and shape domestic supplier consolidation. India's BIS marking mandates and CEA technical standards for distribution infrastructure create compliance thresholds that favor established manufacturers with testing laboratory partnerships. Stakeholders must monitor regulatory divergence between halogen-free material mandates in Europe, performance-based standards in North America, and cost-optimized specifications in Asia to align product platforms with diverging certification requirements.
Market Dynamics
Modular bundled cable configurations are rebalancing procurement patterns across utility and construction verticals as buyers seek reduced installation labor and faster commissioning timelines.
Growth Catalysts
- EU Green Deal implementation:Building efficiency mandates across Germany, France, and Italy are tightening copper and aluminum conductor specifications, forcing wholesale infrastructure upgrades in commercial and residential stock.
- Hyperscale data center construction:Operators in Virginia, Singapore, and Frankfurt are scaling low voltage infrastructure for server farm expansion, creating concentrated demand for fire-resistant thermoset insulation.
- China's eastern coastal manufacturing corridors:Grid modernization and industrial automation projects are accelerating cable procurement in Jiangsu, Zhejiang, and Guangdong provinces.
Market Restraints
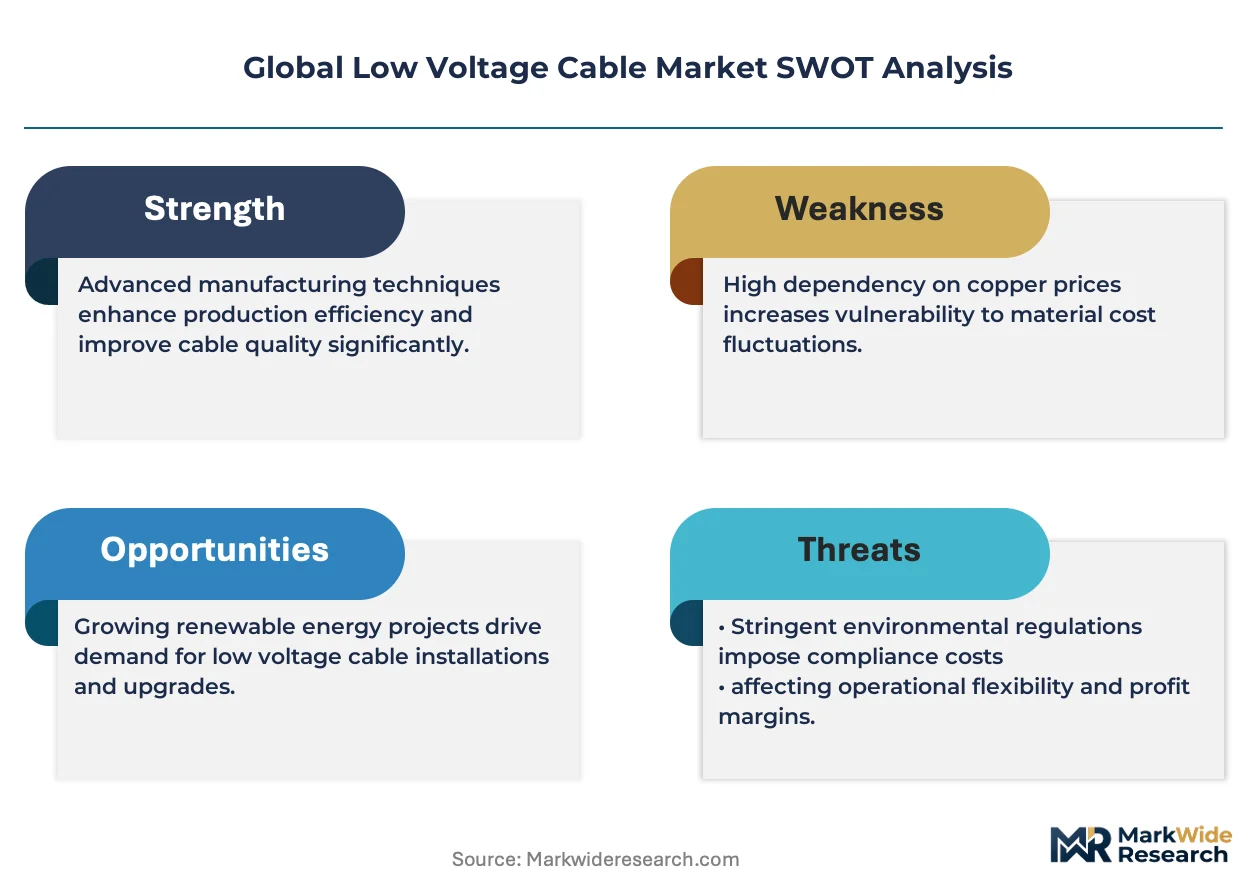
- Copper price volatility:London Metal Exchange pricing swings directly compress manufacturer margins and destabilize project budgeting for utility buyers.
- Halogenated compound phase-outs:REACH chemical frameworks in Europe constrain PVC and halogenated formulations, forcing compounders toward costlier low-smoke zero-halogen alternatives.
- Subsea cable supply concentration:Specialized harsh-environment manufacturing capacity clusters with limited European and Asian producers, creating bottleneck risk for offshore wind interconnects.
Strategic Opportunities
- India's distribution infrastructure:BIS marking mandates and CEA technical standards favor established manufacturers with testing laboratory partnerships, creating protected market access for compliant entrants.
- Digital twin integration:Convergence of cable monitoring sensors with building management systems enables predictive maintenance contracts and recurring revenue streams.
- Prefabricated electrical skids:Modular data center builders are bypassing traditional distributor channels to source bundled cable assemblies directly from manufacturers.
Industry Challenges
- Extrusion technician scarcity:Continuous vulcanization line operation requires specialized polymer processing expertise that aging workforces in Germany and Japan cannot replenish.
- Multi-jurisdiction certification timelines:GB standards, SAMR protocols, and BIS markings demand parallel testing tracks that extend product launch cycles by 8-14 months.
- Legacy thermoplastic inventory obsolescence:Buyers migrating to thermoset insulation for thermal endurance are stranding distributor stocks of PVC-jacketed residential wiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Low Voltage Cable Market |
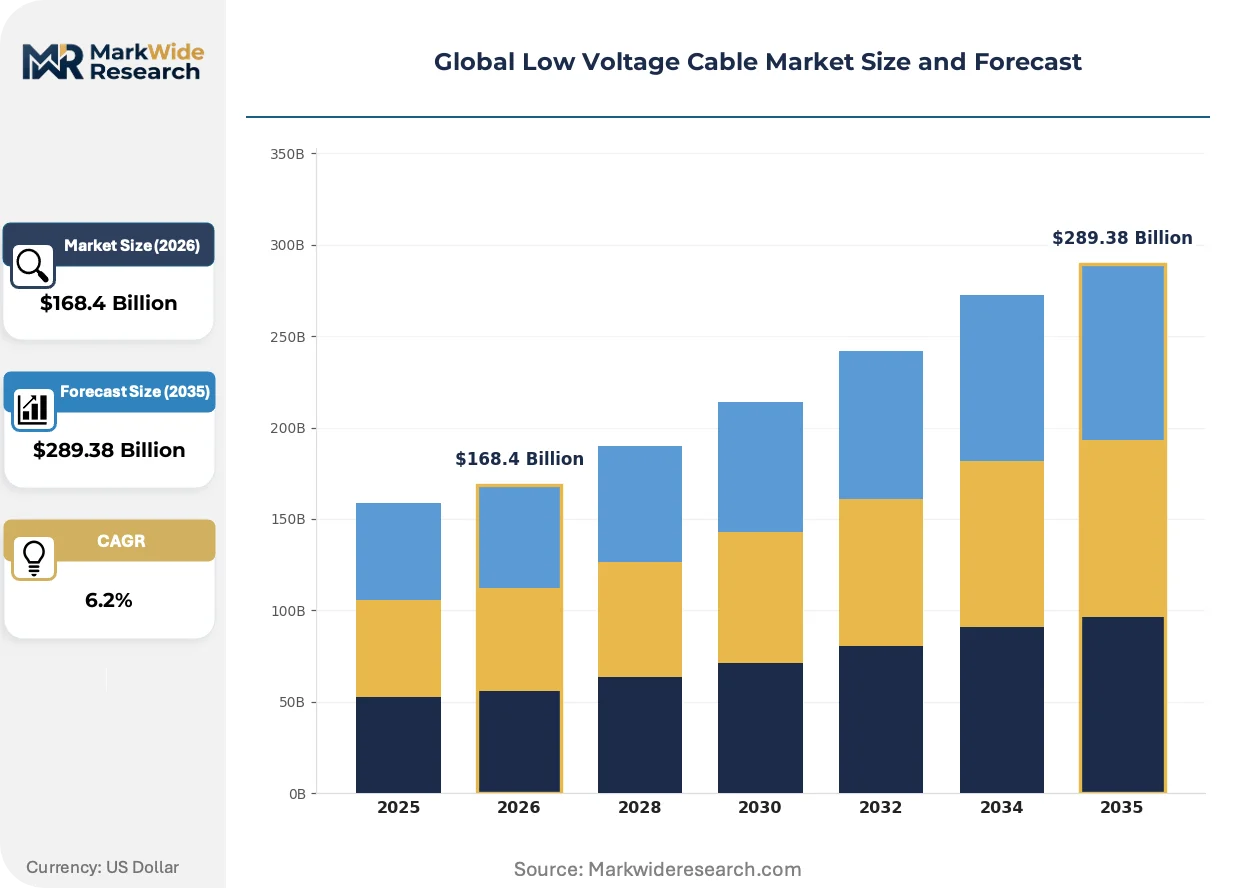
| Market Size in 2026 | $168.4 Billion |
| Market Size in 2035 | $289.38 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Thermoset, Control Cable, Coaxial Cable, Submersible Cable Application: Power Distribution, Telecommunication, Control Systems, Electrical Wiring, Signaling Installation Type: Underground, Aerial, Direct Burial, Tray, Duct End User: Construction Companies, Energy Providers, Data Centers, Manufacturing Plants, Utilities |
| Companies Covered | Prysmian Group, Nexans, NKT A/S, Southwire Company, Sumitomo Electric Industries, ABB, LS Cable & System, Encore Wire Corporation, Finolex Cables, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Low Voltage Cable Market Shifts & Advancements
Extrusion chemistry and installation economics are reshaping competitive positioning across insulation classes and procurement channels.
Cross-linked polyethylene (XLPE) insulation is overtaking thermoplastic alternatives in premium building wire segments. Data center operators and manufacturing plant engineers specify XLPE for thermal endurance above 90°C and enhanced fire resistance. This material transition is compressing PVC volume in commercial construction while expanding margin pools for compounders with captive peroxide curing capacity.
REACH chemical frameworks and EU Green Deal building codes are forcing halogenated compound abandonment across European markets. Compounders are reformulating toward low-smoke zero-halogen alternatives that alter raw material procurement and require modified extrusion equipment. German and French cable manufacturers are absorbing capital costs for twin-screw compounding lines to maintain CE marking eligibility.
Direct manufacturer engagement is displacing traditional electrical distributor intermediation in large infrastructure projects. Data center developers and utility-scale solar EPCs in Texas, Rajasthan, and Queensland are negotiating frame contracts for modular bundled cable configurations. This channel compression concentrates volume with integrated compound-to-cable producers capable of certifying conductor purity and dimensional tolerances under single-source accountability.
Global Low Voltage Cable Market Segmentation
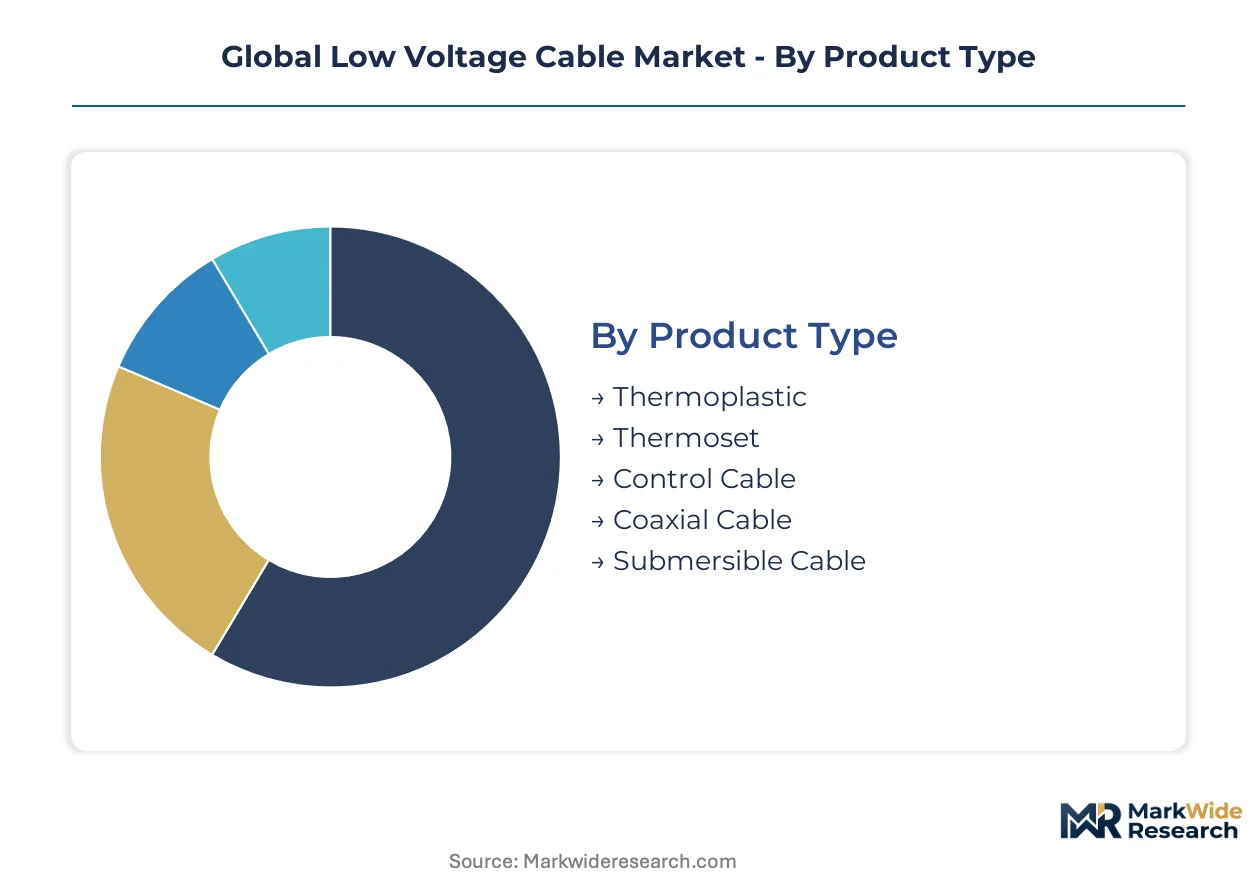
Low voltage cable procurement diverges sharply across insulation chemistry, deployment environment, and buyer sophistication. Specification choices cascade through installation labor costs, fire safety certification, and long-term thermal performance.
Product Type:
Thermoplastic and thermoset insulation chemistries anchor divergent cost-performance tradeoffs across building codes and industrial specifications.
- Thermoplastic:PVC and PE compounds extrude rapidly at lower temperatures, dominating residential and commercial wiring volumes where cost minimization outweighs thermal endurance requirements. REACH chemical constraints in Germany and France are forcing compounders toward calcium-zinc stabilizer systems that alter processing parameters.
- Thermoset:XLPE and EPR formulations cross-link through peroxide or silane curing, delivering 90°C+ continuous operation for data center busways and manufacturing plant power distribution. Virginia hyperscale operators specify thermoset exclusively for fire-resistant trunking.
- Control Cable:Multi-conductor assemblies with shielded pairs transmit instrumentation signals between PLCs and field devices in Jiangsu automation corridors.
- Coaxial Cable:Central conductor with dielectric and braided shield construction carries RF signals in legacy telecommunications infrastructure.
- Submersible Cable:EPR-insulated constructions with lead or thermoplastic sheaths withstand hydrostatic pressure in borehole pumps and wastewater lift stations.
Mature deployment sits with thermoplastic in residential stock. Newer deployment is concentrated in thermoset for thermal-critical infrastructure.
Application:
Functional purpose determines conductor sizing, insulation thickness, and regulatory certification tracks.
- Power Distribution:Three-phase and single-phase feeders route electricity from substations to panelboards, with aluminum conductors gaining share in utility-scale solar EPCs across Rajasthan and Queensland.
- Telecommunication:Twisted-pair and fiber-optic hybrid cables support 5G fronthaul and enterprise LAN backbones in Singapore's digital infrastructure buildout.
- Control Systems:Low-capacitance shielded pairs minimize electromagnetic interference between sensors and automation controllers in Zhejiang manufacturing plants.
- Electrical Wiring:Branch circuit conductors deliver final distribution to outlets and lighting in commercial and residential construction.
- Signaling:Fire alarm, security, and emergency communication cables require specialized flame propagation ratings under NFPA and EN standards.
Volume concentrates in power distribution. Margin expansion is climbing the fastest in control systems for industrial automation.
Installation Type:
Deployment mechanics dictate mechanical protection requirements and labor productivity.
- Underground:Direct-buried or conduit-drawn constructions with water-blocking compounds dominate urban grid upgrades in Frankfurt and Milan where aerial rights-of-way are exhausted.
- Aerial:Messenger-supported or self-supporting designs persist in rural electrification across India and Brazil where trenching costs exceed pole line construction.
- Direct Burial:Armored or unarmored cables with enhanced crush resistance serve residential service entrances and irrigation systems.
- Tray:Open wiring methods in industrial facilities require sunlight-resistant and oil-resistant jacketing for cable ladder routing.
- Duct:Pull-string installations through concrete encasement enable future capacity expansion in data center campuses.
Urban density is pushing underground deployment. Aerial methods retain cost advantage in terrain-constrained geographies.
End User:
Buyer procurement sophistication spans commodity spot purchasing to engineered frame contracts.
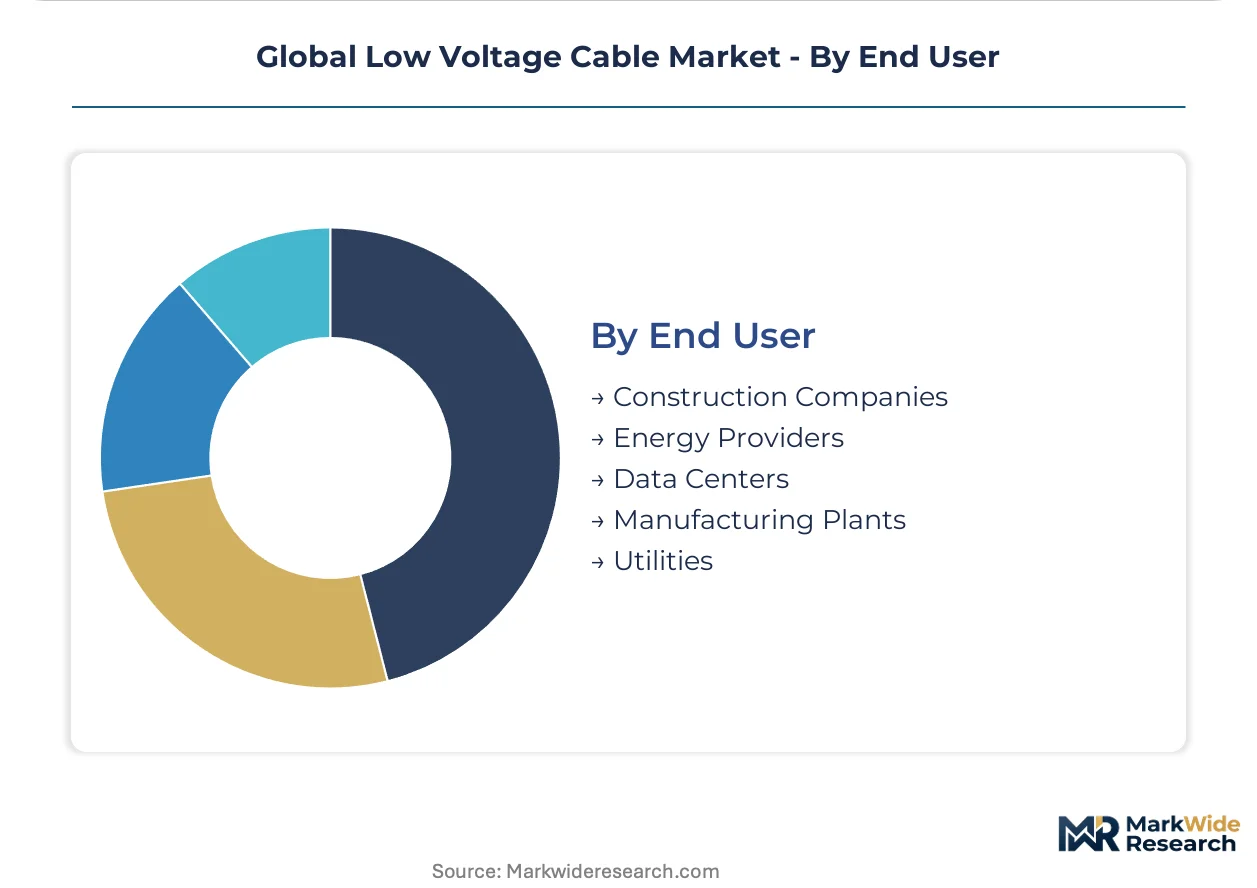
- Construction Companies:General contractors and electrical subcontractors source through distributor channels with price-sensitive PVC specifications for residential and light commercial projects.
- Energy Providers:Utility procurement departments negotiate multi-year agreements for distribution feeder replacement programs with conductor purity certifications.
- Data Centers:Hyperscale operators and colocation developers bypass intermediaries to specify thermoset bundled assemblies with digital twin compatibility requirements.
- Manufacturing Plants:Automotive and electronics OEMs in Guangdong demand MTBF documentation and vendor-managed inventory for continuous production lines.
- Utilities:Transmission and distribution operators prioritize supply security and storm recovery logistics over unit cost minimization.
Procurement consolidation is most advanced with data centers. Fragmented purchasing persists with construction companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virginia's data center tax incentive zones concentrate hyperscale infrastructure investment, pulling low voltage cable procurement toward thermoset specifications for fire-resistant power distribution.
United States
Loudoun County and Northern Virginia host the world's densest hyperscale server farm concentration, with Dominion Energy reporting multi-gigawatt load growth through 2028. FERC interconnection queues and state renewable portfolio standards accelerate underground distribution upgrades. Texas ERCOT grid expansion and Arizona semiconductor fabs drive secondary demand clusters for industrial automation cabling.
Germany
The EU Green Deal's building efficiency mandates force wholesale electrical infrastructure replacement across commercial and residential stock. ECHA REACH frameworks constrain halogenated compound formulations, pushing compounders toward low-smoke zero-halogen alternatives. Frankfurt's data center corridor and Bavarian automotive manufacturing plants specify XLPE insulation for thermal endurance above 90°C.
China
Jiangsu, Zhejiang, and Guangdong provinces anchor grid modernization and industrial automation procurement. GB standards and SAMR certification protocols enforce conductor purity and dimensional tolerances that filter import eligibility. Yangtze River Delta manufacturing corridors accelerate cable procurement for smart factory deployments and distributed energy integration.
India
BIS marking mandates and CEA technical standards for distribution infrastructure create compliance thresholds favoring established manufacturers. Rajasthan and Gujarat utility-scale solar EPCs negotiate aluminum conductor frame contracts for cost-optimized installations. Maharashtra's industrial corridors and Delhi-NCR data center developments drive premium thermoset demand.
Singapore
Tuas data center precinct and digital infrastructure buildout concentrate low voltage procurement for 5G fronthaul and enterprise LAN backbones. The Energy Market Authority's grid reliability standards enforce cable certification protocols. Jurong Island petrochemical complexes and port electrification projects sustain industrial-grade specification demand.
Global Low Voltage Cable Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across insulation chemistry and installation configuration segments. Market structure tilts toward consolidation at the compound-to-cable integrated tier, with fragmented competition among regional distributors and specialty fabricators. Three archetypes dominate: integrated material-cable producers controlling quality and delivery timelines; subsea and harsh-environment specialists commanding premium margin pools; and regional manufacturers competing on distributor channel density. Dominant competitive moves include backward integration into compound manufacturing and direct frame contract negotiation with hyperscale data center developers.
Among integrated European producers, Prysmian Group and Nexans occupy positions representing the compound-to-cable archetype, while Southwire Company exemplifies regional manufacturing density strategies across North American infrastructure projects. These three anchors illustrate divergent paths: captive material control versus specialized environment portfolios versus distributor channel coverage.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| NKT A/S |
| Southwire Company |
| Sumitomo Electric Industries |
| ABB |
| LS Cable & System |
| Encore Wire Corporation |
| Finolex Cables |
| Others |
Supply & Pricing Matrix
Copper cathode costs from London Metal Exchange pricing cascade through three-tier pricing structures across premium, standard, and economy levels, with German and Chinese compounders absorbing volatility differently based on their captive smelter access and long-term offtake positions.
Pricing Analysis
Margin tightening in thermoplastic PVC tiers reflects REACH-driven reformulation costs and calcium-zinc stabilizer premiums. Three-tier pricing separates XLPE thermoset specifications from commodity building wire from economy-grade aluminum conductors. Price differentiation hinges on GB standards certification grade and peroxide curing capacity ownership. Data center buyers in Virginia and Singapore show lowest price sensitivity, while Indian construction contractors driving Rajasthan solar EPCs negotiate aggressively on aluminum conductor unit economics.
Supply Chain Analysis
Extrusion technician scarcity in Germany and Japan constrains continuous vulcanization line expansion despite Yangtze River Delta capacity growth. Manufacturing gravity centers on China, Germany, and the United States for integrated compound-to-cable production. Raw material procurement draws from Chilean copper concentrate, Saudi petrochemical feedstocks, and domestic Chinese PVC resin. Single-source vulnerability concentrates in specialized subsea EPR compounding capacity clustered with limited European producers. Distribution runs through electrical distributor networks in construction verticals, with direct manufacturer engagement displacing intermediaries in hyperscale data center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The low voltage cable market sits in a material-transition phase as XLPE thermoset specifications displace legacy PVC thermoplastic inventory across fire-critical infrastructure deployments.
For Market Incumbents: Deploy backward integration into copper smelting and compound manufacturing to defend against London Metal Exchange volatility and REACH chemical framework compliance costs. Prysmian Group and Nexans anchor positions through captive peroxide curing capacity; challengers must match this upstream control or cede margin to integrated leaders. Channel consolidation in North American distributor networks presents acquisition targets for regional density expansion. For New Entrants and Emerging Players: The premium-to-economy price gap in Indian BIS-certified distribution cable opens white-space opportunity for compliant mid-tier producers. Target Rajasthan and Gujarat utility-scale solar EPCs with aluminum conductor frame contracts undercutting established European import pricing. Bypass distributor markups through direct engagement with state electricity board procurement officers leveraging CEA technical standard partnerships. For Investors and Strategic Acquirers: Frame contract announcements from Virginia hyperscale data center developers are the leading indicator that thermoset demand acceleration is structurally durable. Long-term viability rests on compound-to-cable integration depth rather than pure assembly capacity. Acquisition targets should show SAMR certification in China, testing laboratory partnerships in India, and peroxide curing line ownership. Watch for German and French extrusion technician training program launches as supply constraint resolution signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Smelting | Captive concentrate processing insulates Prysmian and Nexans from London Metal Exchange volatility cycles. |
| Low-Smoke Zero-Halogen Compound Transition | REACH compliance in Germany and France requires twin-screw compounding line capital deployment for CE marking retention. |
| Direct Frame Contract Negotiation | Hyperscale data center developers in Virginia and Singapore bypass distributor channels for bundled cable assemblies. |
| Testing Laboratory Partnership Expansion | BIS marking and CEA compliance in India favor established manufacturers with accredited certification tracks. |
| Digital Twin Sensor Integration | Cable monitoring convergence with building management systems enables predictive maintenance recurring revenue streams. |
Research Methodology
Independent corroboration across cable compounder technical directors, utility procurement officers, and data center construction managers underwrites the qualitative findings in this study. Primary fieldwork engaged extrusion line operators, electrical distributor category buyers, and EPC contractor project managers across Virginia, Frankfurt, and Jiangsu manufacturing corridors. Secondary validation drew from ECHA REACH substance registrations, GB standards publication records, SEC 10-K filings from listed cable producers, and customs trade data for copper concentrate and PVC resin flows. Bottom-up volume modeling from individual plant capacities and top-down demand segmentation from end-use verticals were reconciled through iterative triangulation.
Historical reference periods spanning pre-pandemic baselines through recent supply chain disruption quarters anchored the forecast window calibration. The analytical framework modeled segmentation across insulation chemistry, installation environment, end-user procurement sophistication, and regional regulatory cluster intensity. CAGRs were derived from installed base replacement cycles, grid modernization program announcements, and hyperscale data center pipeline tracking. Industry-specific forecast inputs included FERC interconnection queue data for Virginia load growth and EU Green Deal building retrofit mandate implementation timelines.
Inputs from ECHA substance databases and SAMR certification registries were available through the study window; gaps in real-time Chinese distributor inventory data introduce uncertainty bands around near-term pricing trajectory assumptions. Forecasts reflect documented assumptions on copper price regime persistence and REACH enforcement intensity. Regulatory acceleration in halogenated compound phase-outs or sudden London Metal Exchange dislocation represent revision triggers. A small set of compounder capacity announcements and hyperscale data center construction starts warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Tray Market
Cables
Cable Lugs Market
Cables
Hybrid Cables Market
Cables
Low Voltage Cable Accessories Market
Cables
Usb Data Cable Market
Cables
Global Wires and Cables Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Cable Fault Locator Market
Cables
Asia Pacific MV and HV Underground Cables and Accessories Market
Cables
UK Cables Market
Cables
Latin America Wire and Cable Market
Cables
Europe Wire and Cable Market
Cables
Cable Racks Market
Cables
GCC Cable Accessories Market
Cables
India Wire and Cable Market
Cables
Cable Assembly Market