
 Global Optical Network Hardware Market | 2026-2036
Global Optical Network Hardware Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Network Hardware Market Foresight
CE marking under the EU Radio Equipment Directive is redrawing competitive access for optical transceiver suppliers serving European data centers. Nokia Corporation leverages its Bell Labs R&D pipeline to sustain technology leadership in coherent optics. Cisco Systems Inc. anchors enterprise demand through integrated routing-and-optical platforms. Huawei Technologies Co. competes aggressively on manufacturing scale, though geopolitical restrictions limit its addressable markets in North America and parts of Europe.
Optical network hardware encompasses physical-layer equipment that encodes, amplifies, switches, and transports data as light signals across fiber infrastructure, typically operating at wavelengths between 1260 and 1625 nanometers with power budgets measured in decibels. Its primary purpose is to expand transmission capacity and extend reach without electrical regeneration in telecom, cloud, and enterprise networks. Optical transceivers generate the largest revenue pool among product types, driven by 400G and 800G port upgrades in hyperscale data centers. Dense Wavelength Division Multiplexing leads technology adoption, while Coarse Wavelength Division Multiplexing retains share in cost-sensitive metro access builds. Cloud networking applications are expanding fastest, pulling demand from Internet Service Providers and Cloud Service Providers simultaneously.
The FCC in the United States enforces equipment authorization rules that gate market entry for optical hardware, while the EU AI Act and GDPR impose data sovereignty requirements that favor domestically certified fiber infrastructure. China's MIIT sets GB standards for optical transmission equipment that shape product specifications for vendors manufacturing within its jurisdiction. Stakeholders must monitor how divergent national certification timelines affect inventory planning and whether emerging spectrum regulations in India and Brazil create parallel compliance burdens.
Market Dynamics
Coherent optical transmission technology is compressing power consumption per bit while extending unamplified reach, fundamentally restructuring capital allocation across telecom and cloud infrastructure buildouts.
Growth Catalysts
- EU AI Act compliance mandates:Data sovereignty requirements under the EU AI Act and GDPR are compelling hyperscale operators to deploy certified, high-capacity fiber infrastructure within European jurisdictions, accelerating amplifier and transceiver procurement cycles.
- AI-driven cloud workload expansion:Cloud service providers are scaling optical backhaul capacity to support machine learning training clusters that demand terabit-scale interconnects between data centers.
- India national broadband deployment:The BharatNet project combined with private 5G network rollouts is concentrating demand for optical transceivers and erbium-doped fiber amplifiers in South Asian supply chains.
Market Restraints
- Indium phosphide supply concentration:Foundry capacity for indium phosphide photonic integrated circuits remains geographically concentrated in East Asian manufacturing zones, creating input cost volatility for coherent transceiver production.
- FCC equipment authorization timelines:Extended review periods for optical hardware certification under FCC Part 15 and Part 68 rules are gating market entry for non-domestic suppliers serving United States data center operators.
- Pluggable coherent optics substitution:Disaggregated pluggable modules are displacing traditional embedded optical systems in metro applications, compressing margins for chassis-based platform vendors.
Strategic Opportunities
- Brazil spectrum liberalization:Emerging regulatory frameworks for open fiber access in Brazilian metro markets are creating whitespace for wavelength-selective switch vendors to establish early positioning.
- Silicon photonics convergence:The integration of silicon photonics with CMOS electronics is enabling cost-optimized 800G transceiver production for cost-sensitive enterprise edge deployments.
- Japan METI green procurement incentives:Carbon footprint disclosure requirements under METI guidelines are favoring suppliers with documented low-energy optical amplification technologies in public network tenders.
Industry Challenges
- Coherent DSP engineering talent scarcity:The specialized skill set required for 7nm and 5nm digital signal processor design for optical engines is concentrating within a limited pool of semiconductor design houses.
- Multi-vendor interoperability certification:Proprietary implementation of Open ROADM standards is forcing network operators to maintain parallel testing labs, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Network Hardware Market |
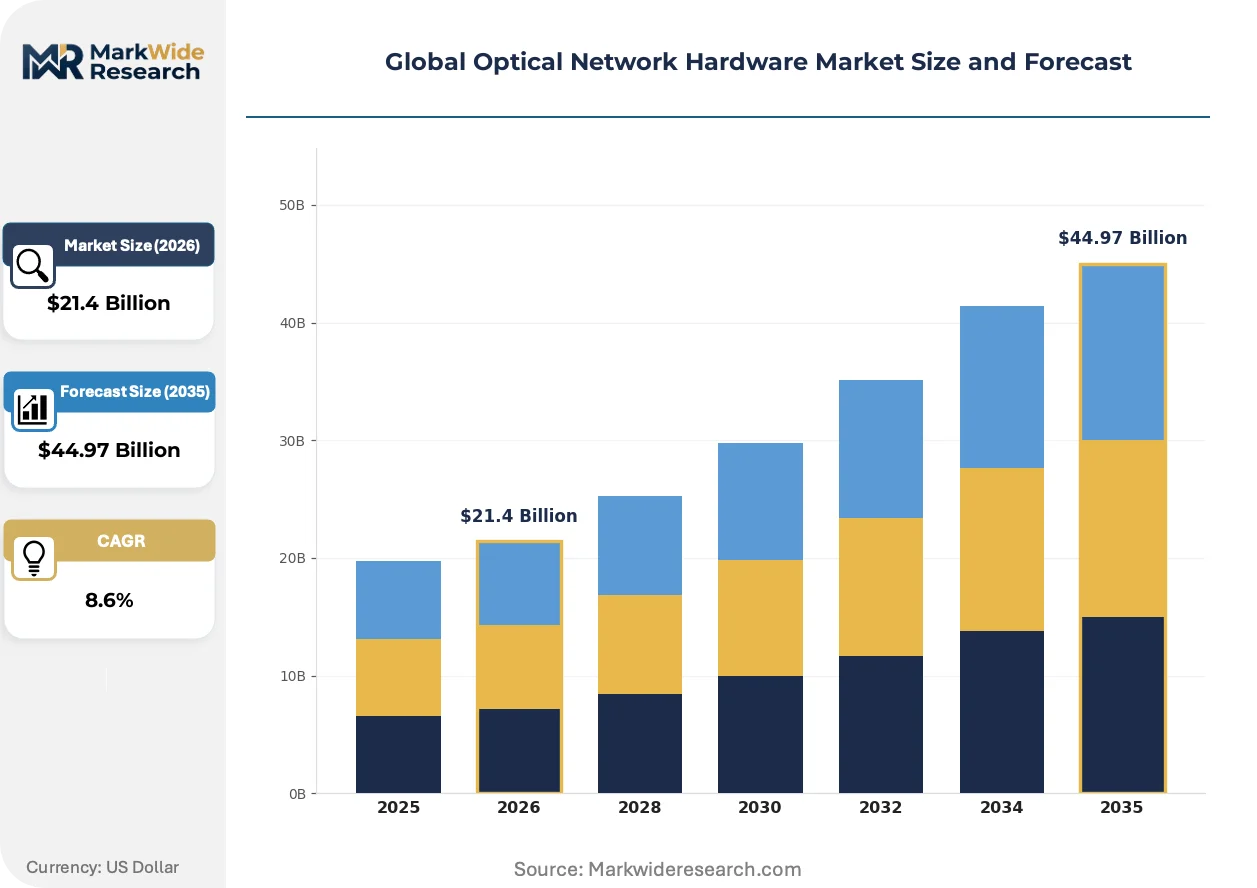
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $44.97 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Transceivers, Optical Amplifiers, Optical Switches, Fiber Optic Cables, Optical Multiplexers Technology: Wavelength Division Multiplexing, Dense Wavelength Division Multiplexing, Coarse Wavelength Division Multiplexing, Optical Time Division Multiplexing, Optical Packet Switching Application: Telecommunication, Data Centers, Military Communications, Broadcasting, Cloud Networking End User: Internet Service Providers, Cloud Service Providers, Defense Agencies, Media Companies, Research Institutions |
| Companies Covered | Nokia Corporation, ZTE Corporation, Huawei Technologies Co., Corning Incorporated, Fujitsu Limited, Cisco Systems Inc., Infinera Corporation, Adtran Networks SE, Ciena Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Network Hardware Market Shifts & Advancements
Optical network hardware is undergoing a platform shift from discrete component architectures to integrated photonic engines, compressing development cycles and reshaping supplier relationships across the value chain.
Linear drive optics is displacing traditional retimed transceiver architectures in hyperscale data center interconnects. Cloud operators at the largest scale are adopting linear pluggable optics for intra-campus links up to 2 kilometers. This displacement is collapsing the power budget for optical-to-electrical conversion and forcing DSP vendors to reposition toward linear amplification silicon.
REACH substance restrictions are expanding coverage to include additional flame retardants and plasticizers used in optical cable jacketing and transceiver housings. European manufacturers are reformulating material specifications to maintain CE marking eligibility under evolving ECHA guidance. The restriction is most acute for vendors supplying outdoor-rated fiber cables to German and French telecom infrastructure projects.
Buying committees at cloud service providers are consolidating optical procurement decisions into centralized infrastructure engineering teams, displacing the previous model where individual data center operators maintained separate vendor relationships. This consolidation is compressing supplier negotiation leverage and favoring vendors with direct enterprise sales engineering presence in Northern Virginia and Frankfurt.
Global Optical Network Hardware Market Segmentation
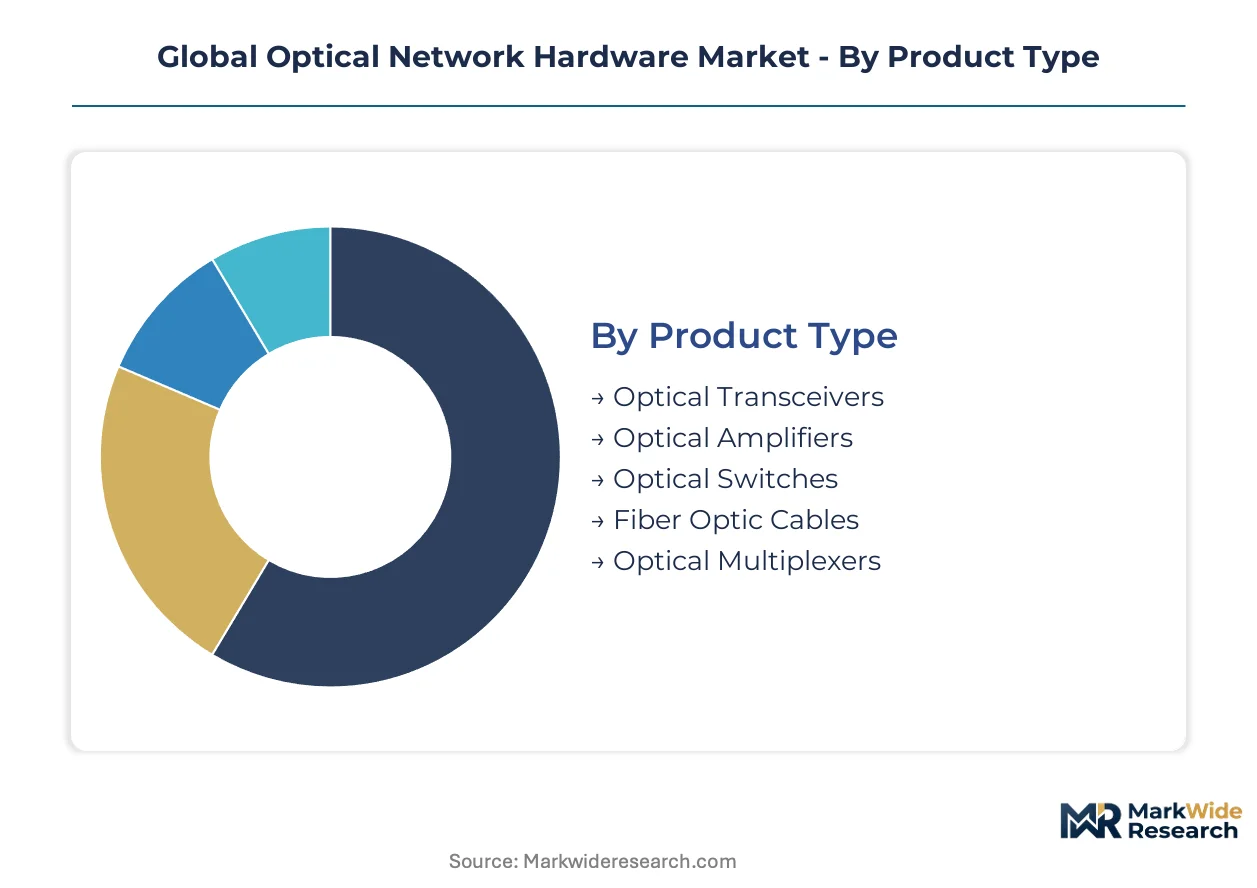
Optical network hardware segments fracture along wavelength economics, deployment scale, and customer procurement sophistication. Substitution pressures vary sharply: pluggable coherent optics displace chassis-based systems in some verticals while fiber amplification remains irreplaceable for long-haul reach.
Product Type:
Pluggable coherent modules exert the strongest substitution pressure on legacy embedded optical systems, compressing margins for chassis-based platforms while amplifying demand for discrete amplification and cabling components.
- Optical Transceivers:These electro-optical modules convert electrical signals to optical wavelengths and back, with form factors ranging from QSFP-DD to OSFP driving 400G and 800G port densities. Cloud service providers in Northern Virginia and Frankfurt are consolidating procurement for these modules to feed AI training cluster interconnects requiring terabit-scale backhaul between facilities.
- Optical Amplifiers:Erbium-doped fiber amplifiers and Raman amplification systems regenerate optical signals without electrical conversion, extending unamplified transmission reach. India's BharatNet project and private 5G rollouts are concentrating procurement for these components in South Asian supply chains where fiber infrastructure spans challenging terrain.
- Optical Switches:Wavelength-selective and optical circuit switches route light paths without opto-electrical conversion, enabling dynamic bandwidth allocation in metro cores.
- Fiber Optic Cables:Single-mode and multimode fiber bundles with specialized jacketing for aerial, underground, and submarine deployments carry the physical light signals across infrastructure.
- Optical Multiplexers:Passive and active multiplexing devices combine multiple wavelength channels onto single fiber pairs, optimizing spectral efficiency in capacity-constrained routes.
Optical transceivers retain volume leadership; optical amplifiers hold the steepest expansion curve as coherent reach extension demands intensify.
Technology:
Cost tier stratification separates premium coherent engines from commodity passive multiplexing, with silicon photonics convergence collapsing price points at the 800G edge while indium phosphide retains lock on longest-reach applications.
- Wavelength Division Multiplexing:Foundational technology enabling multiple optical channels on single fiber pairs through spectral separation.
- Dense Wavelength Division Multiplexing:DWDM compresses channel spacing to 0.8nm or tighter, achieving 80+ wavelengths per fiber in long-haul and submarine networks. Cloud networking applications in hyperscale data centers are pulling DWDM demand fastest as machine learning clusters demand massive east-west bandwidth between compute islands.
- Coarse Wavelength Division Multiplexing:CWDM operates with 20nm channel spacing using uncooled lasers, slashing cost for metro access and enterprise edge builds where reach requirements stay under 80 kilometers. Cost-sensitive municipal fiber projects in Brazil and India favor this technology for last-mile aggregation.
- Optical Time Division Multiplexing:OTDM interleaves optical pulses at sub-wavelength granularity, finding niche application in ultra-high-speed research networks.
- Optical Packet Switching:OPS enables direct optical-layer packet forwarding without electronic buffering, remaining experimental for most production networks.
DWDM commands the revenue concentration; CWDM is climbing the fastest as emerging market fiber builds prioritize cost-optimized access layers.
Application:
Customer type fragmentation splits procurement between regulated telecom incumbents with legacy infrastructure and cloud operators building greenfield AI-optimized networks from photonic layer upward.
- Telecommunication:Incumbent carriers deploy optical hardware for subscriber aggregation, metro transport, and inter-city backhaul with stringent five-nines reliability requirements.
- Data Centers:Hyperscale facilities require optical interconnects for spine-leaf architectures and campus-scale fiber plants, with reach requirements typically under 10 kilometers.
- Military Communications:Defense agencies specify ruggedized optical systems with anti-jam and low-probability-of-intercept characteristics for tactical and strategic networks.
- Broadcasting:Media distribution networks rely on optical transport for uncompressed video contribution and primary distribution with microsecond-level latency tolerances.
- Cloud Networking:Cloud service providers are scaling optical capacity fastest to support distributed machine learning training across geographically separated data centers, with this application expanding most quickly as AI workload placement drives inter-facility bandwidth demand.
Telecommunication retains installed base dominance; cloud networking is gaining share fastest as AI infrastructure investment accelerates.
End User:
Procurement consolidation among the largest cloud operators is reshaping supplier relationships, with centralized infrastructure engineering teams displacing distributed data center purchasing authority.
- Internet Service Providers:ISPs deploy optical hardware for residential and business broadband aggregation, with procurement cycles tied to subscriber growth and regulatory universal service obligations.
- Cloud Service Providers:Amazon Web Services, Microsoft Azure, and Google Cloud Platform operate the largest optical procurement budgets, specifying custom transceiver form factors and driving 800G adoption timelines through direct supplier engineering collaboration.
- Defense Agencies:National security organizations source optical systems through classified procurement channels with domestic content requirements under ITAR and similar frameworks.
- Media Companies:Broadcasters and streaming platforms invest in optical transport for content delivery network backbone expansion and live event contribution.
- Research Institutions:Universities and national laboratories deploy experimental optical networks for high-energy physics data transfer and distributed computing grids.
Cloud service providers anchor procurement volume; defense agencies maintain the most specialized specification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud service providers in Northern Virginia and Frankfurt concentrate procurement authority for optical transceivers feeding AI training clusters. This buyer archetype is expanding certified fiber infrastructure across three continents to satisfy data sovereignty mandates.
United States
Hyperscale data center construction in Loudoun County and Prince William County drives 800G transceiver demand for campus-scale interconnects. FCC equipment authorization under Part 15 and Part 68 rules gates market entry for optical hardware suppliers. Northern Virginia's fiber corridor now anchors the largest concentration of cloud networking procurement budgets worldwide.
Germany
CE marking requirements under the EU Radio Equipment Directive reshape competitive access for transceiver vendors serving Frankfurt and Düsseldorf data center clusters. The EU AI Act and GDPR compliance timelines accelerate investment in certified high-capacity fiber infrastructure. Bavaria's industrial automation sector pulls CWDM deployments for cost-sensitive manufacturing edge networks.
India
The BharatNet project combined with private 5G rollouts concentrates demand for erbium-doped fiber amplifiers and optical transceivers. TRAI spectrum allocation frameworks and CEA power grid standards shape deployment specifications for rural fiber infrastructure. Tamil Nadu and Karnataka host emerging optical component assembly operations serving South Asian supply chains.
China
MIIT GB standards for optical transmission equipment shape product specifications for coherent transceiver manufacturing. Domestic cloud operators and state-owned carriers deploy DWDM systems for inter-city backhaul and submarine cable landing stations. The Yangtze River Delta maintains foundry concentration for indium phosphide photonic integrated circuits.
Brazil
ANVISA-equivalent spectrum liberalization frameworks for open fiber access create whitespace for wavelength-selective switch vendors in São Paulo and Rio de Janeiro metro markets. Municipal fiber projects favor CWDM technology for last-mile aggregation where reach requirements stay under 80 kilometers. Cost-sensitive procurement patterns distinguish Brazilian demand from North American hyperscale specifications.
Global Optical Network Hardware Market Competitive Landscape
Player mix skews toward integrated platform vendors with coherent optics R&D pipelines and specialized component suppliers with silicon photonics capabilities. The market structure concentrates around three tiers: chassis-based system vendors, pluggable module specialists, and discrete component fabricators. Strategic archetypes include R&D-driven technology leaders, manufacturing-scale cost optimizers, and regulatory-compliant regional specialists. Competitive moves center on coherent DSP licensing partnerships and silicon photonics foundry alliances.
Among diversified telecommunications equipment vendors, Nokia Corporation, Huawei Technologies Co., and Cisco Systems Inc. occupy positions representing distinct strategic vectors. Nokia Corporation exemplifies the R&D-intensive archetype leveraging fundamental research capabilities. Huawei Technologies Co. represents manufacturing-scale competition within geopolitically constrained addressable markets. Cisco Systems Inc. anchors enterprise demand through integrated platform positioning. These three entities collectively illustrate how vendor strategies diverge across regulatory, technology, and customer segmentation dimensions.
| Leading Market Players |
|---|
| Nokia Corporation |
| ZTE Corporation |
| Huawei Technologies Co. |
| Corning Incorporated |
| Fujitsu Limited |
| Cisco Systems Inc. |
| Infinera Corporation |
| Adtran Networks SE |
| Ciena Corporation |
| Others |
Supply & Pricing Matrix
FCC equipment authorization under Part 15 and Part 68 rules gates both supplier qualification and price differentiation simultaneously, compressing margins for non-domestic vendors while granting domestic incumbents pricing power through certification moats. This regulatory architecture feeds directly into procurement contract structures and inventory strategies across the optical hardware value chain.
Pricing Analysis
Cost-plus contracts with indium phosphide wafer price indexation dominate long-haul transceiver procurement, tethering final equipment pricing to foundry input volatility. Three-tier pricing structure across premium coherent, standard pluggable, and economy CWDM levels separates vendors by DSP sophistication and reach performance. Price compression runs through the pluggable coherent tier as silicon photonics displaces indium phosphide in metro applications. Cloud service providers exhibit lowest price sensitivity due to volume consolidation, while municipal fiber projects in Brazil and India drive hardest bargain on unit economics.
Supply Chain Analysis
Strategic stockpiling of indium phosphide wafers and erbium-doped fiber components prevails over just-in-time approaches given foundry concentration risks in Taiwan and Japan. Manufacturing gravity centers on China's Yangtze River Delta for passive components, South Korea for silicon photonics, and the United States for coherent DSP design. Raw material dependencies span rare earth elements for fiber amplification, high-purity silica for waveguide fabrication, and specialty gases for epitaxial growth. Single-source vulnerability in III-V semiconductor foundries threatens supply continuity. Distribution runs through direct OEM relationships with hyperscalers and tiered distributor networks for enterprise channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The optical network hardware market is cycling through an AI infrastructure investment upswing, with capital expenditure patterns at cloud service providers indicating sustained procurement momentum for coherent transceivers and amplification systems.
For Market Incumbents: Fortify coherent DSP engineering capabilities through captive hiring or acquisition of specialized design houses, as talent scarcity constrains product roadmap velocity. Deepen backward integration into silicon photonics foundry partnerships to secure cost-optimized 800G supply for hyperscale procurement cycles. Defend against pluggable coherent substitution by embedding amplification and switching functions into integrated chassis platforms that cloud operators cannot easily disaggregate. For New Entrants and Emerging Players: Lead with silicon photonics-based 800G transceivers targeting cost-sensitive enterprise edge deployments where incumbents maintain premium positioning. Brazil's open fiber access regulatory whitespace offers the most penetrable geographic entry point for wavelength-selective switch vendors seeking initial customer referenceability. Pursue direct engineering collaboration with mid-tier cloud operators outside the Northern Virginia-Frankfurt procurement axis to bypass consolidated buying committee gatekeeping. For Investors and Strategic Acquirers: EU AI Act compliance timelines reshape the acquisition landscape by favoring targets with established CE marking pathways and European manufacturing footprints over pure-play Asian cost optimizers. Long-term viability hinges on exposure to AI-driven cloud workload expansion rather than cyclical telecom capital expenditure. Target acquisition archetypes include silicon photonics specialists with CMOS-compatible process technology and coherent DSP design houses with 7nm or 5nm tape-out experience. Watch indium phosphide foundry utilization rates as the signal indicating whether supply constraints will sustain pricing power or collapse margins through overcapacity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Partnership | Enables cost-optimized 800G transceiver production for hyperscale cloud procurement cycles. |
| Coherent DSP Licensing Agreement | Accelerates time-to-market for pluggable optics vendors lacking in-house digital signal processing capabilities. |
| CE Marking Pathway Investment | Secures competitive access to Frankfurt and Düsseldorf data center clusters under EU AI Act compliance mandates. |
| Backward Integration into III-V Foundry | Captures indium phosphide wafer supply for longest-reach coherent engines amid foundry concentration risk. |
| Open ROADM Interoperability Certification | Reduces multi-vendor testing burden for network operators deploying disaggregated optical line systems. |
Research Methodology
Initial hypotheses were tested against primary input from optical network hardware procurement executives at cloud service providers, coherent DSP engineering directors, and fiber infrastructure project managers at national broadband authorities, then refined through secondary validation. Primary fieldwork encompassed structured interviews with supply chain planners at transceiver manufacturers, regulatory affairs leads navigating FCC and CE marking pathways, and network architects at Tier 1 internet service providers. Secondary sources included FCC equipment authorization databases, EU Radio Equipment Directive guidance documents, MIIT GB standard filings, and hyperscaler capital expenditure disclosures. Bottom-up demand modeling across product types and technologies was triangulated against top-down market sizing derived from carrier procurement budget analysis.
Variance in projected outcomes decomposes across technology substitution rates, regulatory certification timeline shifts, and cloud service provider capital allocation decisions. The analytical framework segments volume and value across product type, technology, application, and end user dimensions, with additional granularity on wavelength economics and deployment scale. CAGRs were derived from fitted growth curves applied to base-year estimates validated against disclosed procurement volumes. Industry-specific forecast inputs encompass coherent reach extension roadmaps, silicon photonics yield improvement trajectories, and national broadband deployment schedules.
The analysis sits within stated boundaries; outcomes outside sustained AI infrastructure investment cycles or absent major regulatory harmonization would require recalibration. Forecasts reflect documented assumptions regarding cloud service provider procurement consolidation patterns and foundry capacity expansion timelines. Revision becomes warranted when indium phosphide supply concentration or FCC authorization backlogs cross thresholds that materially alter vendor competitive positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Laser Diode Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
ROADM WSS Component Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market
Optical Components
CMP Polishing Machine Market
Optical Components
Diode Laser Module Market
Optical Components
Optical Cross Connect Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
CVD Sic Ring Market