
 UK Cables Market | 2026-2036
UK Cables Market Size, Share, and Industry Trends Forecast 2026-2036
UK Cables Market Insights
Modular cable bundling for offshore wind arrays is rebalancing procurement patterns among UK utilities. Prysmian Cables & Systems Ltd leverages its subsea manufacturing footprint to anchor large-diameter power cable supply for North Sea projects. Tratos UK Ltd specializes in fire-resistant building wire, competing on British Standards certification breadth. Nexans sustains R&D intensity in HVDC submarine technology, differentiating through in-house production of insulation compounds.
UK cables are electrically conductive assemblies—typically copper or aluminum conductors sheathed in XLPE, PVC, or rubber insulation—engineered to transmit power, control signals, or data across industrial, commercial, and infrastructure networks. Manufacturing involves continuous extrusion of insulation layers around drawn conductors, followed by armoring or jacketing for mechanical and environmental protection. Power cables command the largest value pool given grid reinforcement and interconnector investments, while fiber optic cables represent the fastest-expanding segment as Openreach and hyperscalers densify backhaul networks. Copper conductor material still dominates premium installations, though aluminum gains ground in cost-sensitive overhead distribution where weight reduction matters.
BEIS building safety regulations and Ofgem RIIO price controls shape product standards and market access for UK cable suppliers. The UK's net-zero strategy and CSRD-aligned corporate reporting obligations are forcing facility managers and utilities to document embodied carbon in cable procurement decisions. Stakeholders must monitor how forthcoming amendments to the Building Regulations Part B and the Electricity Safety, Quality and Continuity Regulations alter fire-performance and grid-connection specifications for new installations.
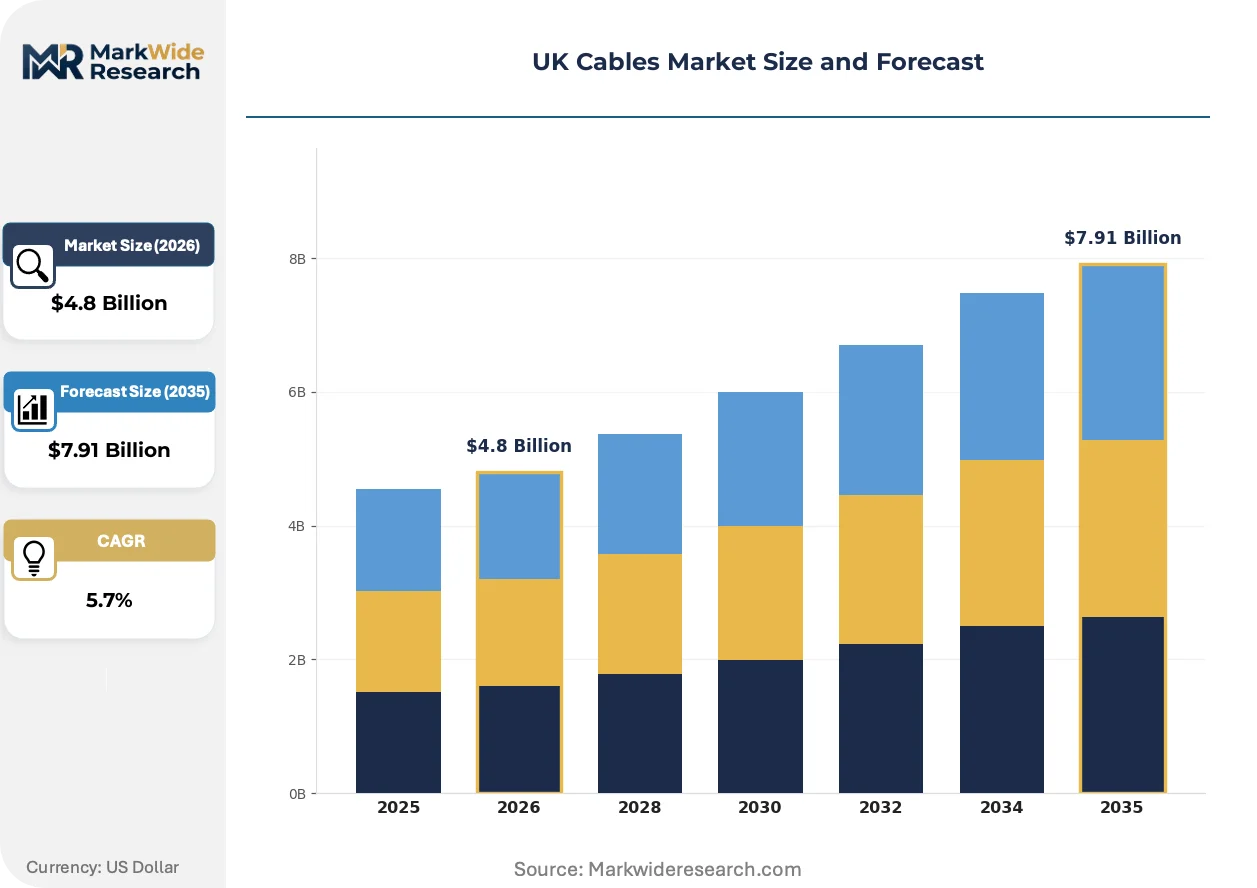
Market Dynamics
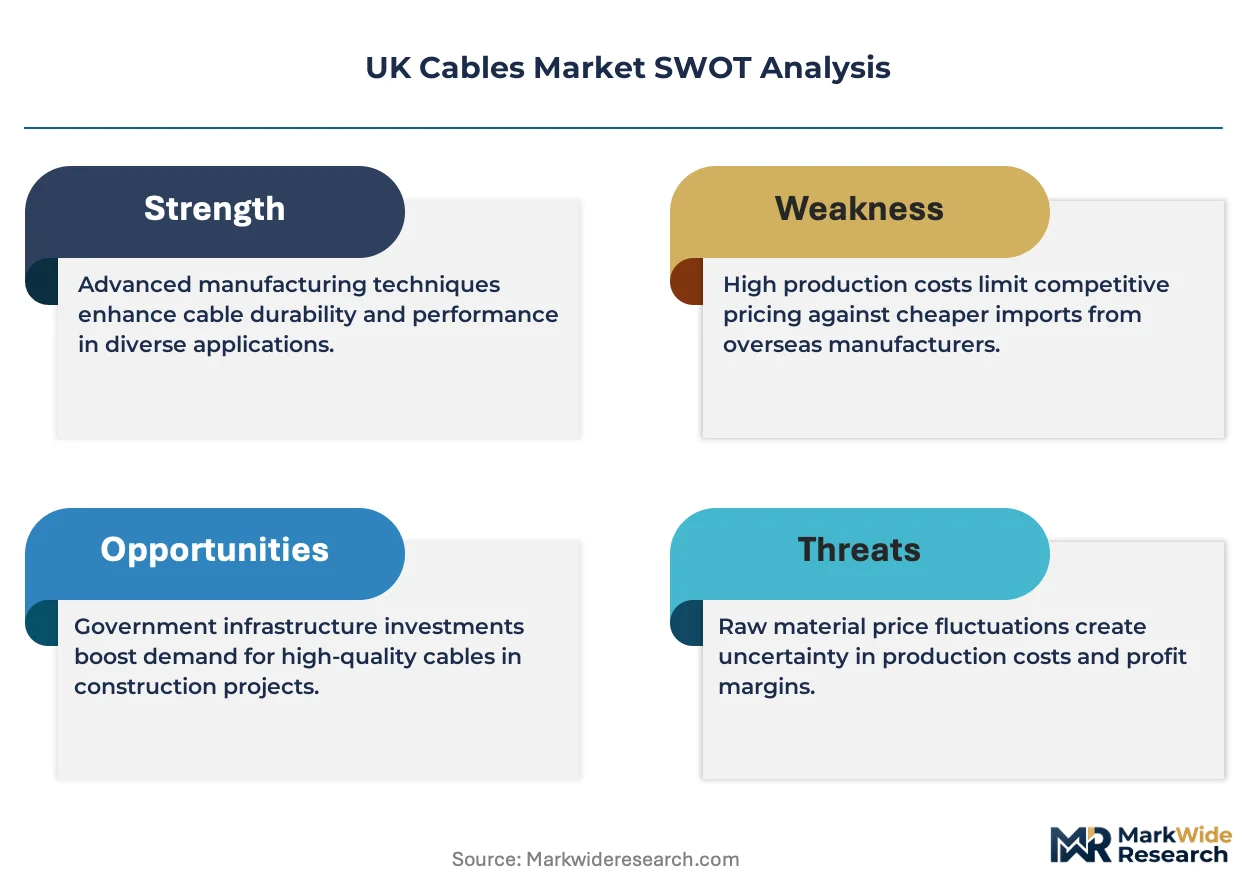
Offshore wind farm developers are consolidating procurement around subsea power transmission systems, forcing cable manufacturers to reconfigure production footprints and certification portfolios around North Sea project timelines.
Growth Catalysts
- Scotland's offshore wind clusters:Developers are accelerating array cabling contracts for floating wind platforms in the Celtic Sea and Moray Firth, creating dedicated demand for dynamic high-voltage submarine cables.
- BEIS net-zero grid mandates:Building safety regulations and RIIO price controls are tightening fire-performance standards for building wire, forcing upgrades across England's commercial real estate stock.
- Data center corridor densification:Hyperscalers are expanding fiber backhaul networks around London and Slough, pulling premium optical cable volumes from Openreach and wholesale infrastructure providers.
Market Restraints
- Copper price volatility:LME copper fluctuations are compressing margin visibility for power cable manufacturers dependent on conductor material hedging strategies.
- Subsea manufacturing concentration:Large-diameter HVDC cable production concentrates among a handful of European facilities, creating bottleneck risk for UK offshore wind connection timelines.
- XLPE compound supply constraints:Specialized insulation material availability is limiting output scaling for extra-high-voltage land cable orders.
Strategic Opportunities
- Wales and southwest England tidal arrays:Emerging marine energy projects present untapped demand for dynamic subsea cabling systems resistant to saltwater fatigue cycles.
- CSRD-aligned embodied carbon tracking:Corporate sustainability reporting obligations are creating premium pricing power for suppliers with verified low-carbon material certifications.
- Smart grid sensor integration:Convergence of power conductors with distributed fiber sensing is opening bundled product categories for distribution network operators.
Industry Challenges
- Subsea installation vessel availability:Specialized cable-lay ship scheduling constraints are extending project commissioning windows for offshore wind developers.
- Fire-safety certification timelines:British Standards Institution testing backlogs for low-smoke zero-halogen compounds are delaying building wire product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Cables Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Power Cables, Control Cables, Communication Cables, Instrumentation Cables, Fiber Optic Cables Material: Copper, Aluminum, PVC, XLPE, PE, Rubber Application: Energy Generation, Telecommunication Networks, Transportation Systems, Data Centers, Marine Installations End User: Utility Providers, Telecommunications Operators, Transport Authorities, Data Facility Managers, Shipyards |
| Companies Covered | Prysmian Cables & Systems Ltd, Tratos UK Ltd, Nexans, NKT A/S, Belden Inc, Fujikura Ltd, Amnack Ltd, Tyco Electronics UK Ltd, British Cables Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Cables Market Trends and Innovations
Material science advances and procurement model compression are reshaping how UK utilities and infrastructure developers specify, source, and deploy cable systems across voltage classes and environmental exposures.
Cross-linked polyethylene (XLPE) insulation compounded with tree-retardant additives is electrifying medium-voltage distribution networks previously served by paper-insulated legacy cables. Distribution network operators in England's urban corridors are specifying extruded dielectric systems for reduced maintenance cycles and fault tolerance. This material transition is electrifying procurement specifications at National Grid and regional DNOs, compressing demand for fluid-filled cable technologies.
Ofgem's RIIO-ED2 price control framework is mandating network resilience investments with explicit output metrics for customer interruption duration. The regulation forces distribution operators to prioritize fault-tolerant cable architectures and automated switching systems over lowest-first-cost procurement. Northern Powergrid and UK Power Networks are responding with accelerated undergrounding programs in flood-prone sub-regions.
Consolidated procurement by offshore wind farm consortia is displacing fragmented project-by-project cable purchasing. Developers like Orsted and SSE are negotiating multi-project framework agreements with subsea cable manufacturers, compressing supplier margins while securing installation slot priority. This buyer concentration is most visible in Scotland's East Coast cluster, where array cabling and export cable contracts are bundling across adjacent lease areas.
UK Cables Market Segmentation
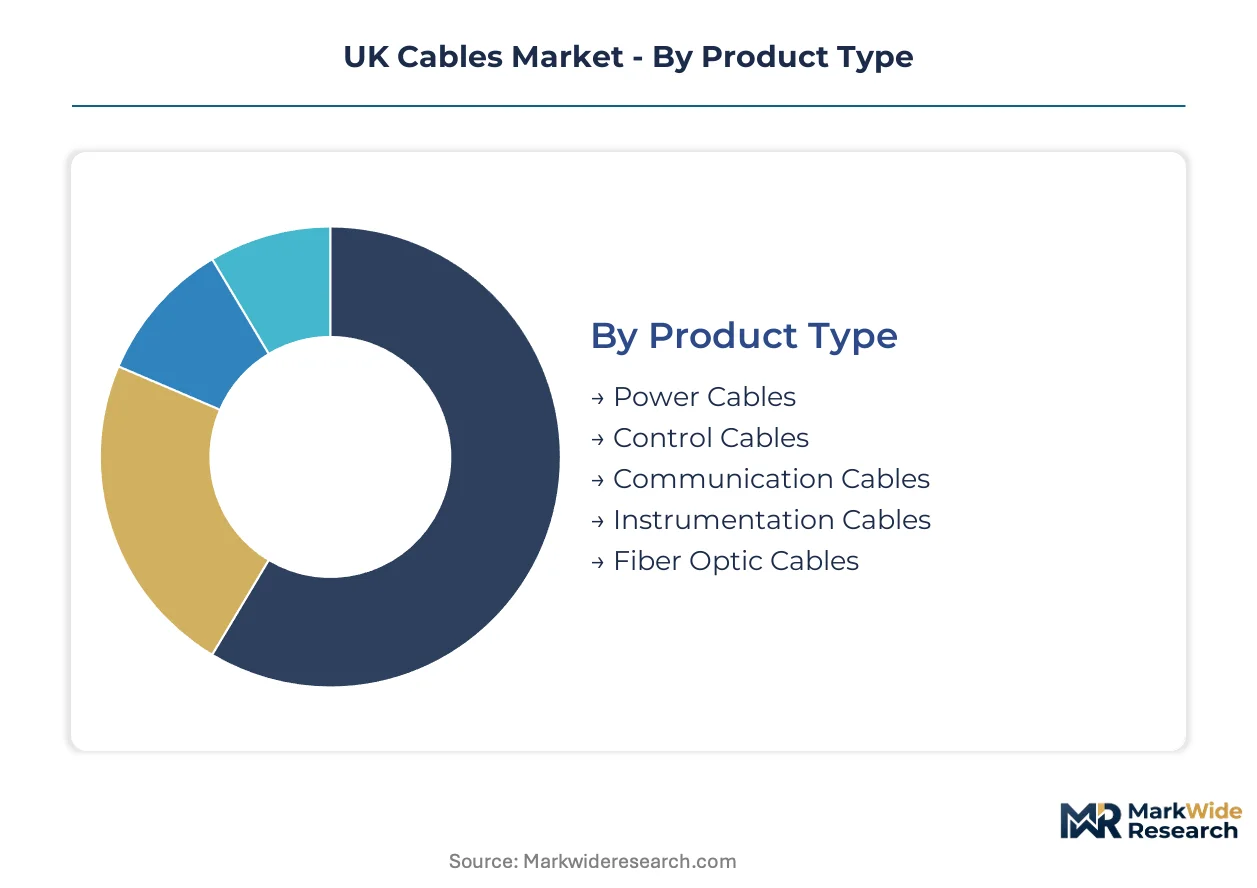
Segmentation in the UK cables market reveals how procurement priorities diverge across voltage classes, material specifications, and end-use environments. Upgrade cycles for grid infrastructure and building safety compliance create distinct demand profiles that reshape supplier positioning.
Product Type:
Replacement timelines for legacy paper-insulated systems are compressing procurement decisions around extruded dielectric technologies.
- Power Cables:High-voltage conductors with XLPE or EPR insulation engineered for transmission and distribution networks. Demand concentrates in Scotland's offshore wind export corridors where National Grid interconnectors require 220kV+ submarine capacity.
- Fiber Optic Cables:Glass fiber assemblies sheathed in protective polymer jackets for data transmission. Openreach's full-fiber rollout and hyperscaler backhaul expansion around Slough are pulling premium single-mode volumes.
- Control Cables:Multi-conductor assemblies with screened pairs for industrial automation signal transmission.
- Communication Cables:Twisted-pair copper constructions for legacy voice and data networks in commercial buildings.
- Instrumentation Cables:Low-capacitance screened conductors for process control in petrochemical and pharmaceutical facilities.
Power cables sit at the top of the volume ranking, with fiber optic cables climbing the fastest.
Material:
Cost differentials between conductor metals and insulation compounds are rebalancing specifications across overhead and underground installations.
- Copper:High-conductivity annealed copper for premium power and signal applications requiring low resistive loss. Distribution network operators in England's urban corridors specify copper for fault-tolerant underground circuits under RIIO-ED2 resilience mandates.
- XLPE:Cross-linked polyethylene insulation compounded with tree-retardant additives for medium-voltage distribution. The material is displacing fluid-filled paper cables in National Grid's 33kV urban reinforcement programs.
- Aluminum:Lightweight conductor material gaining share in cost-sensitive overhead distribution where weight reduction matters.
- PVC:General-purpose thermoplastic insulation for building wire in commercial and residential installations.
- PE:Polyethylene sheathing for moisture-resistant outdoor and subsea cable protection.
- Rubber:Flexible elastomeric insulation for mobile equipment and temporary power applications.
Copper dominates premium installations, though aluminum gains ground fastest in overhead distribution segments.
Application:
Project timelines for infrastructure decarbonization are synchronizing cable procurement across generation, transmission, and digital asset classes.
- Energy Generation:Subsea and land-based cable systems for power evacuation from offshore wind, nuclear, and grid-scale solar. Scotland's floating wind platforms in the Celtic Sea are accelerating dynamic array cable demand.
- Data Centers:High-fiber-count and high-ampacity power feeds for hyperscale computing facilities. London and Slough corridor expansions by Amazon Web Services and Microsoft are densifying both optical and medium-voltage cable pulls.
- Telecommunication Networks:Openreach and alternative network providers' full-fiber infrastructure.
- Transportation Systems:Signalling power and communications for rail electrification and EV charging networks.
- Marine Installations:Dynamic subsea cabling for tidal arrays and port electrification in Wales and southwest England.
Energy generation commands the largest procurement volumes, with data center applications expanding most quickly.
End User:
Buyer consolidation and framework contracting are compressing supplier margins while shifting technical specification authority.
- Utility Providers:National Grid and regional distribution network operators procuring transmission and distribution infrastructure. Ofgem's RIIO-ED2 price controls are forcing undergrounding investments in flood-prone sub-regions.
- Data Facility Managers:Hyperscale and colocation operators specifying high-density fiber and redundant power architectures. Sustainability reporting obligations under CSRD are adding embodied carbon documentation requirements to procurement.
- Telecommunications Operators:Openreach and wholesale infrastructure providers densifying backhaul networks.
- Transport Authorities:Network Rail and local authorities specifying rail electrification and EV charging cable systems.
- Shipyards:Marine engineering contractors procuring dynamic subsea cable for offshore wind installation support.
Utility providers represent the deepest procurement volumes, with data facility managers gaining share fastest in premium cable categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The UK cable industry traces its industrial lineage to Victorian telegraph networks and post-war national grid construction, with contemporary demand concentrating in offshore wind corridors and metropolitan data hubs.
Scotland
Floating wind platforms in the Celtic Sea and Moray Firth are accelerating dynamic array cable procurement. Ofgem's RIIO-ED2 price controls mandate network resilience investments across Scottish distribution networks. Aberdeen and the East Coast cluster host bundled cabling contracts spanning adjacent offshore lease areas.
England
Data center corridor densification around London and Slough is pulling premium fiber and medium-voltage power cable volumes. BEIS building safety regulations under Part B are tightening fire-performance standards for commercial real estate wire upgrades. The Midlands manufacturing belt supplies armored distribution cables for urban undergrounding programs.
Wales
Emerging tidal energy arrays in the Severn Estuary and Irish Sea are generating demand for fatigue-resistant subsea cabling systems. The Welsh Government's marine energy roadmap prioritizes port electrification and coastal infrastructure. Swansea Bay and Holyhead anchor marine installation support vessel activity.
Southwest England
Grid reinforcement for nuclear power evacuation at Hinkley Point C is driving high-voltage land cable orders. Ofgem interconnector approvals for European links are tightening XLPE compound specifications. Bristol and Plymouth serve as logistics hubs for subsea cable staging and testing.
UK Cables Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive subsea manufacturing capabilities. A concentrated tier of European cable groups dominates high-voltage submarine contracts through integrated production of insulation compounds and metallic armoring. Two strategic archetypes define positioning: full-system integrators controlling extrusion-to-installation value chains, and material specialists competing on British Standards certification breadth. Dominant competitive moves include multi-project framework contracting with offshore wind consortia and backward integration into specialized polymer compounding.
Among UK-registered entities, Prysmian Cables & Systems Ltd and Tratos UK Ltd represent contrasting archetypes within the supplier base. Prysmian exemplifies the integrated subsea specialist with manufacturing footprint aligned to North Sea project timelines. Tratos occupies a position emphasizing fire-resistant building wire certification breadth. Nexans, operating through UK commercial structures, anchors the HVDC technology tier with in-house insulation compound production capabilities.
| Leading Market Players |
|---|
| Prysmian Cables & Systems Ltd |
| Tratos UK Ltd |
| Nexans |
| NKT A/S |
| Belden Inc |
| Fujikura Ltd |
| Amnack Ltd |
| Tyco Electronics UK Ltd |
| British Cables Company |
| Others |
Pricing and Supply Chain Analysis
BEIS net-zero grid mandates and CSRD-aligned embodied carbon reporting are gating qualified supply access and premium-tier pricing power for UK cable manufacturers serving utility and data center procurement teams. Buyers with documented low-carbon material certifications command pricing premiums while suppliers without verified supply chain transparency face margin compression in framework contract negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes UK cable procurement, with certification grade and volume scale as primary differentiation drivers. Premium tiers capture British Standards Institution fire-performance certifications and HVDC submarine qualifications, while economy segments serve cost-sensitive overhead distribution. Pricing pressure stems from consolidated offshore wind framework contracting that compresses supplier margins. Data facility managers exhibit lowest price sensitivity due to CSRD compliance premiums, whereas regional distribution network operators prioritize total cost of ownership under RIIO-ED2 output metrics.
Supply Chain Analysis
Copper cathode supply rests on Chilean mining operations and German metal trading houses, with XLPE insulation compound production concentrated in Belgian and Dutch specialty chemical facilities. Raw material dependencies span LME-traded conductor metals, tree-retardant polymer additives, and low-smoke zero-halogen flame retardants. Single-source vulnerability concentrates in large-diameter HVDC cable manufacturing where European extrusion capacity limits UK offshore wind connection timelines. Distribution runs through direct framework agreements with utility procurement consortia and tier-one electrical wholesalers serving commercial construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK cable market margin expansion hinges on premium-tier shift toward low-carbon certified products and cost-down capture from XLPE material transition displacing fluid-filled legacy systems.
For Market Incumbents: Lock in multi-project framework agreements with offshore wind consortia before vessel installation slots tighten further. Prysmian and Nexans should deepen backward integration into specialized polymer compounding to defend margin position against XLPE supply constraints threatening output scaling. Certification investment in dynamic array cable fatigue resistance for Celtic Sea floating platforms creates switching costs against emerging marine energy entrants. For New Entrants and Emerging Players: Regional electrical wholesalers represent the most accessible channel partner type for penetrating England's commercial real estate wire upgrade cycle under Part B fire-safety mandates. Wales and southwest England tidal arrays offer white-space demand for fatigue-resistant subsea cabling with limited incumbent specialization. Target data center facility managers with CSRD-aligned embodied carbon documentation services as a differentiated go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for fire-resistant building wire specialists because BEIS regulatory tightening fragments certification authority across British Standards Institution testing backlogs. Mid-tier manufacturers with captive low-smoke zero-halogen compound production offer acquisition appeal. Watch Ofgem RIIO-ED2 undergrounding program acceleration as inflection indicator for distribution cable volume inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive XLPE supply insulates Prysmian and Nexans from material bottlenecks constraining HVDC output scaling. |
| Multi-Project Framework Contracting | Orsted and SSE procurement consolidation secures installation slot priority while compressing supplier margins across adjacent lease areas. |
| CSRD-Aligned Carbon Certification | Verified low-carbon material documentation commands premium pricing from data facility managers under corporate sustainability reporting obligations. |
| Dynamic Array Cable R&D Investment | Fatigue-resistant subsea systems address Celtic Sea floating wind platform specifications displacing conventional static cable architectures. |
| Fire-Safety Certification Acceleration | British Standards Institution testing backlog clearance enables faster product launches for Part B building wire compliance deadlines. |
Research Methodology
Bottom-up utility and data center procurement modeling reconciled against top-down cable manufacturing capacity tracking forms the analytical core of this study. Primary interviews with distribution network operator planning officers, offshore wind project developers, data facility procurement managers, electrical wholesale channel heads, and British Standards Institution certification engineers combined with secondary validation from Ofgem RIIO-ED2 regulatory filings, BEIS building safety consultations, National Grid interconnection databases, and European cable association trade statistics.
Input-output matrices map conductor material flows through insulation extrusion, armoring, and jacketing stages across voltage class and application segments over the projection horizon. Segmentation dimensions include product type, conductor material, insulation compound, end-use environment, and buyer archetype. CAGRs derive from installed base replacement cycles, grid reinforcement program timelines, and offshore wind lease area auction schedules. Forecast inputs incorporate copper price volatility bands and subsea installation vessel availability constraints.
Revisions become necessary when Ofgem regulatory amendments, BEIS building safety standard updates, or subsea manufacturing capacity expansions materialize differently than modeled assumptions. Forecasts reflect documented procurement patterns and project development pipelines rather than speculative demand creation. A small set of named triggers—copper LME price regime shifts, floating wind platform technology maturation, and CSRD reporting obligation enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Cable Material Market
Cables
Cable Management Accessories Market
Cables
Submarine Cable System Market
Cables
Medium Voltage Cables Accessories Market
Cables
Hybrid Cables Market
Cables
Military Fiber Optic Cables Market
Cables
Cable Racks Market
Cables
Cable Carrier Market
Cables
Usb Data Cable Market
Cables
High-Speed Interconnects Market
Cables
Patch Cable Market
Cables
Audio and Video Cables Market
Cables
Cable Tray Market
Cables
Wire and Cable Label Market
Cables
Single Core Cables Market
Cables
Low Voltage Cable Accessories Market