
 Cable Tray Market | 2026-2036
Cable Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Tray Market Intelligence
Project finance models tied to data center infrastructure rollouts is reconfiguring competitive access for cable tray suppliers, lowering capital barriers for new entrants in high-growth corridors. Schneider Electric leverages its integrated electrical infrastructure platform to bundle cable management with switchgear and power distribution units. Panduit anchors its position through specialized fiber routing solutions that dominate hyperscale facility specifications. Eaton Corporation competes on industrial-grade ladder tray systems engineered for oil, gas, and heavy manufacturing environments.
A cable tray is a rigid structural system used to support insulated electrical cables used for power distribution, control, and communication, typically fabricated from steel, aluminum, or fiberglass-reinforced polymers with load ratings spanning light-duty to extra-heavy-duty classifications per NEMA VE 1 and IEC 61537 standards. Ladder tray and wire mesh configurations command the largest volume share due to their ventilation advantages and ease of cable pulling in commercial and industrial installations. Aluminum material grades represent the fastest-expanding segment as facilities prioritize corrosion resistance and reduced structural dead load in multi-story deployments. Steel retains margin concentration in heavy industrial applications where seismic qualification and extreme load capacity justify premium pricing.
IEC 61537 governs cable tray construction and testing protocols across European and Asia-Pacific markets, while NEMA VE 1 shapes product standards in North American commercial and industrial procurement. The US National Electrical Code and EU CPR (Construction Products Regulation) both mandate fire performance classifications that filter non-compliant suppliers from tender pools. Stakeholders must monitor evolving data center efficiency certifications and local content requirements that increasingly determine specification eligibility in public infrastructure tenders.
Market Dynamics
Data center power density requirements above 50 kW per rack are forcing cable tray specifications toward aluminum alloys with enhanced thermal dissipation and seismic qualification, compressing traditional steel-heavy procurement patterns across hyperscale construction pipelines.
Growth Catalysts
- India's PLI scheme for electronic manufacturing:Domestic data center buildouts in Mumbai and Chennai require IEC 61537-certified cable management systems for power distribution infrastructure.
- NEMA VE 1 load rating upgrades:Heavy industrial facilities in the US Gulf Coast specify extra-heavy-duty ladder trays for oil and gas processing environments.
- Wire mesh ventilation technology:Hyperscale cloud providers prioritize open-bottom configurations to reduce cable bundling temperatures in high-density server halls.
Market Restraints
- Aluminum ingot price volatility:Smelter capacity constraints in China's Yunnan province transmit cost shocks downstream to tray fabricators.
- Galvanized steel supply concentration:Hot-dip coating facilities cluster in Hebei province, creating single-point vulnerability for corrosion-resistant product lines.
- Fiber routing substitution:Pre-terminated optical cable assemblies reduce tray fill requirements in hyperscale facilities with all-fiber backbones.
Strategic Opportunities
- Vietnam's northern industrial corridor:Samsung and Foxconn supplier parks require extensive cable management for semiconductor fabrication expansion.
- EU Green Deal embodied carbon tracking:Low-carbon aluminum sourcing becomes a tender differentiator for public infrastructure projects.
- Digital twin integration:BIM-compliant tray systems with embedded RFID tags enable predictive maintenance in smart factory deployments.
Industry Challenges
- Multi-standard certification timelines:Manufacturers face 14-18 month approval cycles to secure simultaneous NEMA VE 1 and IEC 61537 qualification for global project bids.
- Seismic engineering talent scarcity:Qualified structural engineers capable of ASCE 7-22 compliant tray anchoring design command premium compensation in high-growth construction markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Tray Market |
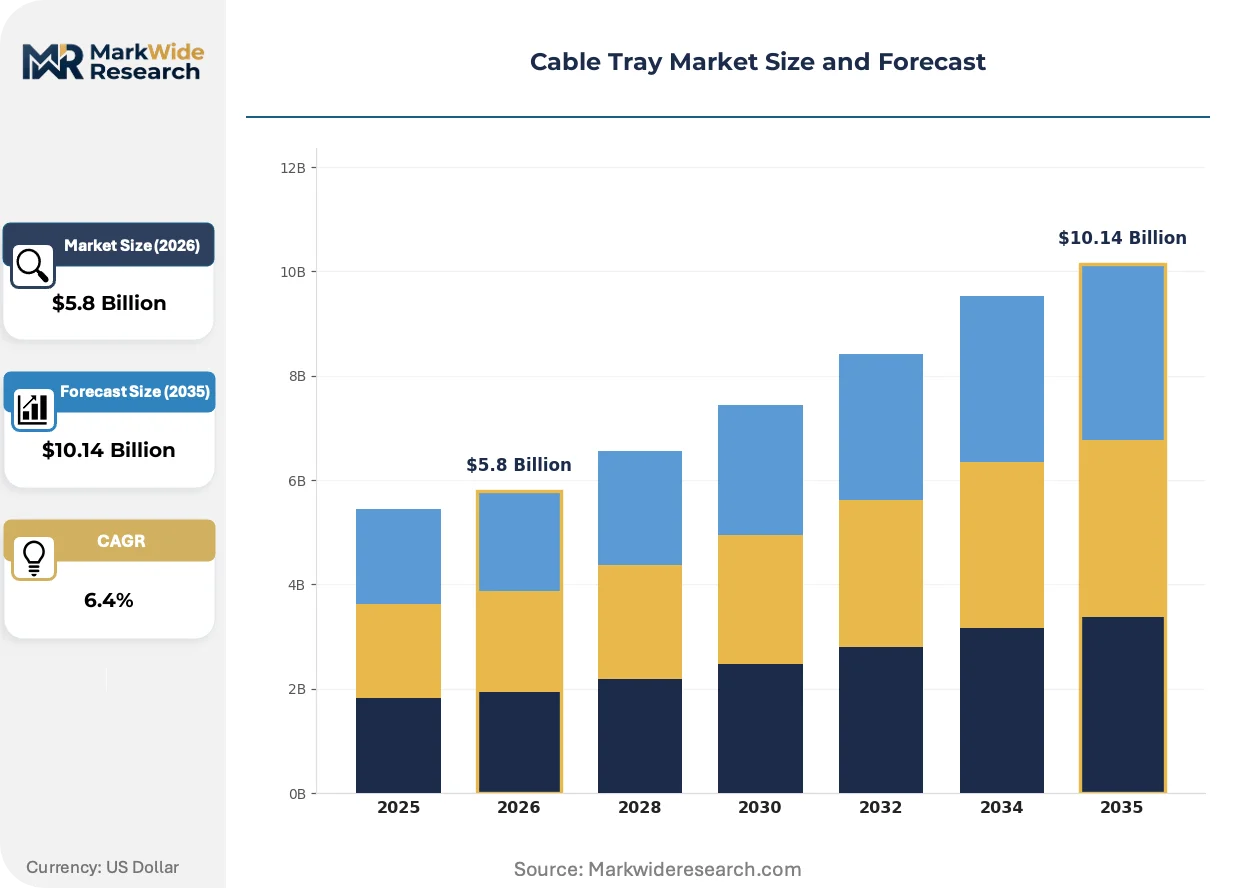
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ladder Tray, Solid Bottom Tray, Wire Mesh Tray, Perforated Tray Material: Steel, Aluminum, PVC, Fiberglass Application: Industrial, Commercial, Residential, Data Centers Installation Type: Floor Mounted, Ceiling Mounted, Wall Mounted, Hanging |
| Companies Covered | Schneider Electric, Panduit, Legrand, Rittal, Hubbell, Atkore International Group, Eaton Corporation, Southwire, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Tray Market Strategic Shifts & Innovations
Modular pre-fabrication methods are compressing installation timelines for complex electrical infrastructure, forcing tray suppliers to redesign product geometries for field-assembly efficiency rather than pure material optimization.
Corrosion-resistant aluminum-magnesium alloys with powder-coated finishes are collapsing the historical steel-aluminum cost gap in coastal and chemical processing environments. Data center operators in Singapore and Rotterdam now specify these grades for sub-floodplain installations without the galvanic maintenance burden. The shift is collapsing premium pricing power for traditional hot-dip galvanized systems in corrosive atmospheres.
The EU Construction Products Regulation fire performance classifications now mandate EN 13501-4 testing for cable tray flame spread and smoke density. Industrial facilities in Germany and Poland must source trays with documented reaction-to-fire ratings, filtering uncertified Asian suppliers from public tender pools. Manufacturers are responding with intumescent coating investments and third-party notified body partnerships.
Hyperscale buyers now bundle cable management procurement with switchgear and busway contracts, compressing vendor count per electrical infrastructure package. Engineering-procurement-construction firms in Northern Virginia and Frankfurt favor integrated suppliers capable of BIM-coordinated delivery schedules. This consolidation is most visible in data center clusters where single-source accountability reduces interface risk during commissioning phases.
Cable Tray Market Segmentation
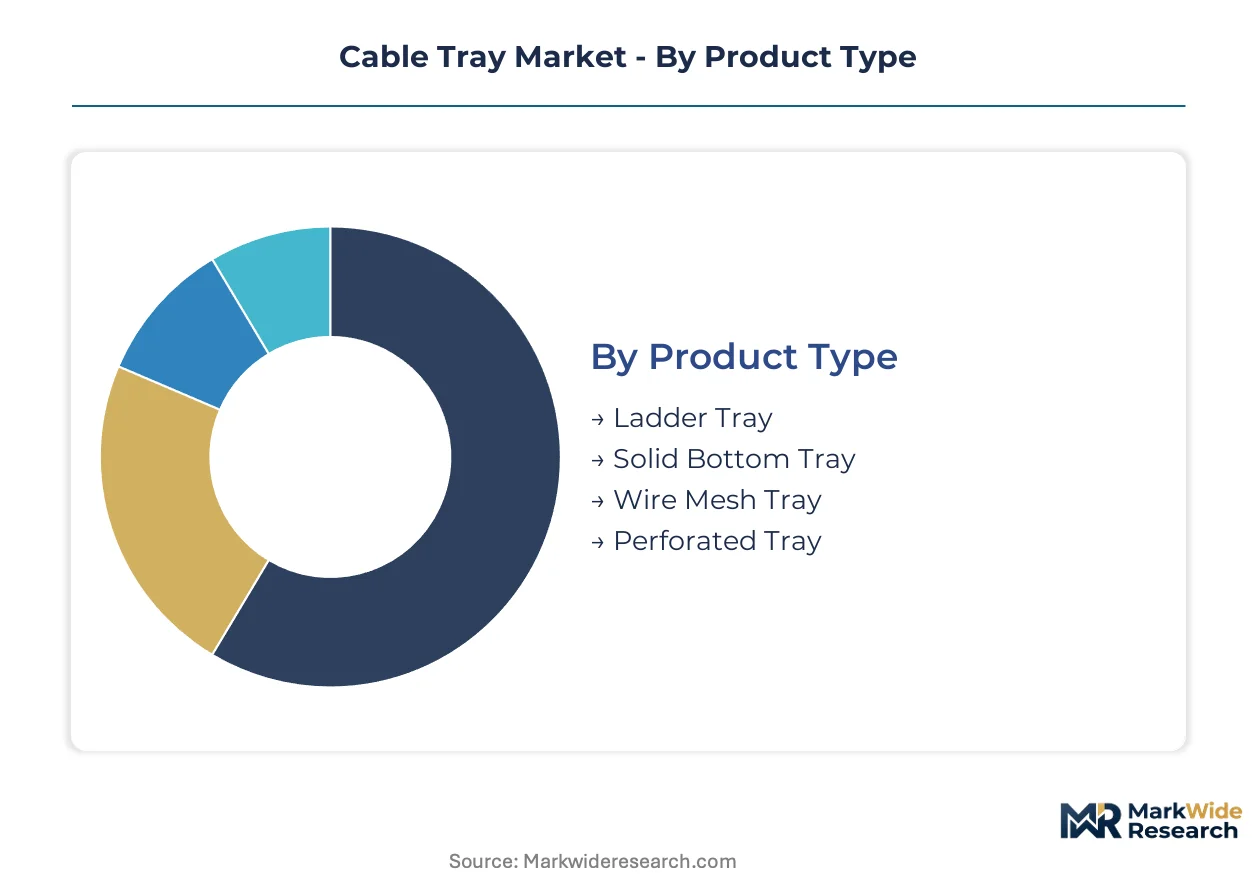
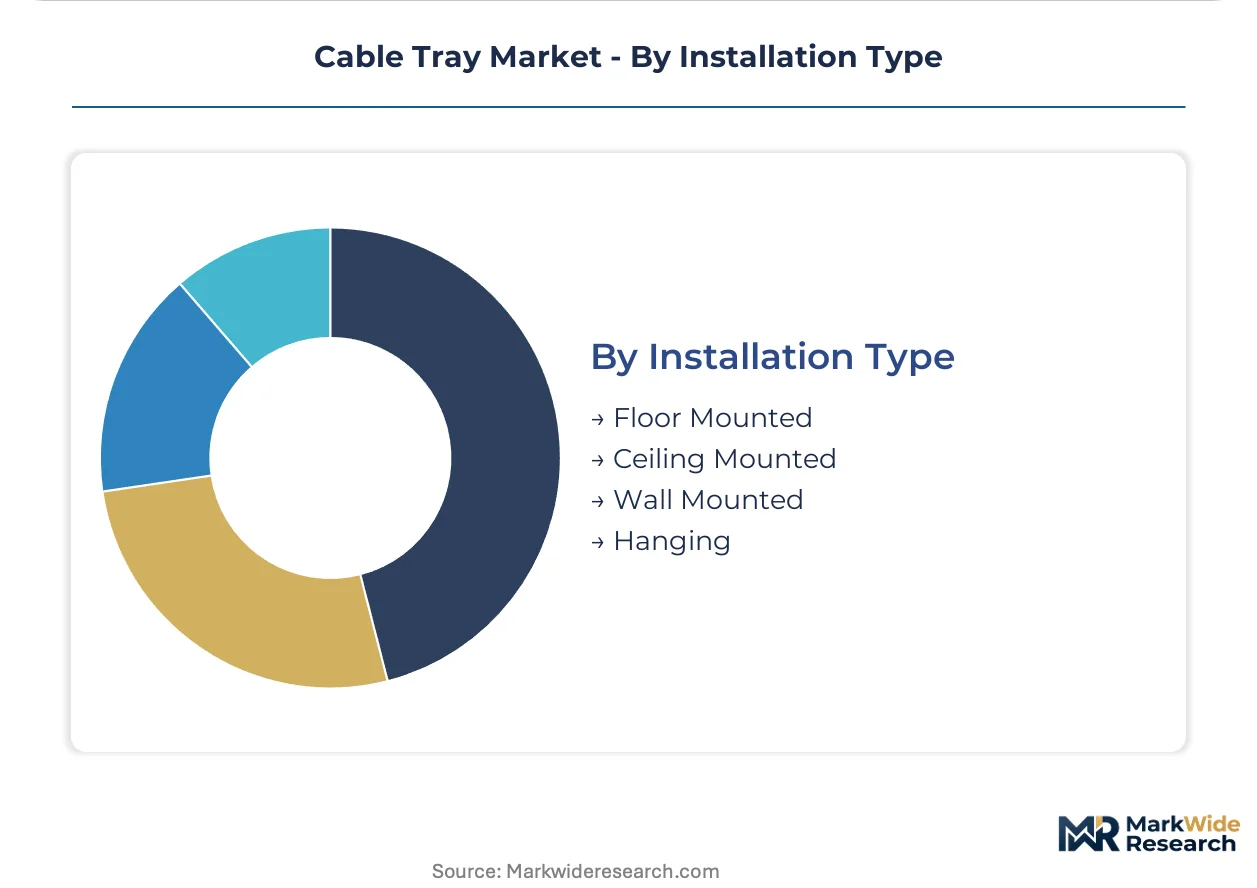
Cable tray specification patterns diverge sharply across installation environments, with material selection and structural geometry directly tied to load requirements, corrosion exposure, and thermal management priorities. Understanding these segment boundaries reveals where procurement budgets concentrate and where specification standards are tightening fastest.
Product Type:
Mature configurations dominate commercial infrastructure, while emerging geometries gain traction in hyperscale and hazardous environment deployments.
- Ladder Tray:Fabricated from welded rungs and side rails, this open configuration delivers maximum ventilation for power cables in heavy industrial settings. Oil and gas facilities along the US Gulf Coast specify NEMA VE 1 extra-heavy-duty ladder trays for offshore platform electrical distribution, driven by seismic qualification requirements and extreme load capacity needs.
- Wire Mesh Tray:Zinc-plated or stainless steel wire construction enables rapid field modification and superior airflow in data center environments. Hyperscale facilities in Northern Virginia and Frankfurt specify open-bottom mesh configurations to reduce cable bundling temperatures in high-density server halls exceeding 50 kW per rack.
- Solid Bottom Tray:Continuous sheet metal base provides electromagnetic interference shielding for sensitive control circuits in manufacturing automation.
- Perforated Tray:Punched-hole pattern balances ventilation with structural rigidity for commercial building electrical risers.
Ladder tray retains volume leadership across heavy industrial procurement; wire mesh holds the steepest expansion curve in data center construction pipelines.
Material:
Cost tiers separate commodity metals from engineered alloys and polymer composites, with corrosion resistance and dead load reduction driving premium specification.
- Steel:Hot-dip galvanized carbon steel remains the baseline for heavy-duty applications requiring seismic qualification and extreme mechanical strength. Chemical processing plants in Germany's Ruhr industrial belt specify steel ladder trays with intumescent coatings to meet EU CPR fire performance classifications under EN 13501-4 testing protocols.
- Aluminum:Extruded aluminum-magnesium alloys with powder-coated finishes collapse the historical steel-aluminum cost gap in coastal installations. Data center operators in Singapore and Rotterdam now specify these grades for sub-floodplain deployments without galvanic maintenance burdens, prioritizing corrosion resistance and reduced structural dead load in multi-story facilities.
- PVC:Thermoplastic construction serves light commercial and corrosive chemical environments where metallic corrosion is prohibitive.
- Fiberglass:Pultruded glass-reinforced polymer delivers dielectric isolation and chemical resistance for electrical substations and wastewater treatment facilities.
Steel commands the largest installed base in heavy industrial verticals; aluminum gains share fastest in data center and coastal infrastructure specifications.
Application:
End-use concentration patterns reflect diverging load density, code compliance, and lifecycle cost calculations across facility types.
- Industrial:Heavy manufacturing, oil and gas, and mining operations require extra-heavy-duty configurations with seismic anchoring per ASCE 7-22 standards. US Gulf Coast petrochemical complexes drive specification toward hot-dip galvanized steel with enhanced load ratings for cable weights exceeding 50 pounds per linear foot.
- Data Centers:Hyperscale cloud and colocation facilities prioritize aluminum wire mesh for thermal dissipation and rapid deployment. India's PLI scheme for electronic manufacturing accelerates domestic data center buildouts in Mumbai and Chennai requiring IEC 61537-certified cable management systems.
- Commercial:Office buildings and retail infrastructure specify perforated and solid-bottom trays for power and low-voltage distribution.
- Residential:Multi-family housing and light commercial construction utilize economy-grade PVC and light-gauge steel configurations.
Industrial applications retain the highest average selling prices; data center deployment represents the fastest-climbing specification volume.
Installation Type:
Mounting geometry responds to facility structural constraints, maintenance access requirements, and seismic zone engineering demands.
- Ceiling Mounted:Suspended rod or trapeze installations dominate commercial and industrial facilities with high-bay clearances. Vietnam's northern industrial corridor semiconductor fabrication plants specify ceiling-mounted aluminum mesh systems to maximize floor space for cleanroom equipment.
- Floor Mounted:Pedestal-supported tray runs serve data center raised-floor environments and heavy industrial cable tunnels where overhead suspension is impractical.
- Wall Mounted:Bracket-fixed configurations address space-constrained electrical rooms and vertical riser shafts in urban commercial buildings.
- Hanging:Chain or cable-suspended systems provide adjustable elevation for temporary installations and facilities with frequent layout changes.
Ceiling-mounted systems retain the largest specification volume across commercial and industrial construction; floor-mounted deployment expands most quickly in hyperscale data center standardized designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal a structural deficit in North American and European cable tray markets, with fabrication capacity concentrated in China's eastern manufacturing corridor and India's western industrial belt. Domestic producers in high-growth demand centers face raw material dependency on imported aluminum ingot and hot-dip galvanized steel coil.
China
Data center construction in Shanghai and Beijing drives specification toward IEC 61537-certified aluminum wire mesh configurations. MIIT's dual carbon goals pressure smelters in Yunnan province to curtail capacity, transmitting aluminum price volatility to downstream fabricators. The Yangtze River Delta hosts the densest concentration of cable tray manufacturing, serving both domestic hyperscale cloud buildouts and export markets across Southeast Asia.
United States
Hyperscale data center clusters in Northern Virginia and Dallas-Fort Worth specify NEMA VE 1 extra-heavy-duty ladder trays for power densities exceeding 50 kW per rack. OSHA electrical safety standards and ASCE 7-22 seismic codes filter non-compliant suppliers from federal infrastructure tenders. The Gulf Coast petrochemical corridor sustains demand for hot-dip galvanized steel configurations in corrosive offshore environments.
India
Domestic data center buildouts in Mumbai and Chennai accelerate under the PLI scheme for electronic manufacturing, requiring IEC 61537-certified cable management systems. CEA electrical infrastructure mandates and BIS quality certifications shape procurement eligibility for public sector tenders. Gujarat's industrial corridor hosts emerging fabrication capacity serving semiconductor supplier parks and pharmaceutical manufacturing expansion.
Germany
Chemical processing plants in the Ruhr industrial belt specify steel ladder trays with intumescent coatings to meet EU CPR fire performance classifications under EN 13501-4 testing. The EU Green Deal's embodied carbon tracking requirements favor low-carbon aluminum sourcing for public infrastructure projects. Bavaria's automotive manufacturing clusters drive demand for EMI-shielded solid-bottom trays in automation-intensive assembly environments.
Singapore
Data center operators specify aluminum-magnesium alloys with powder-coated finishes for sub-floodplain installations, prioritizing corrosion resistance and reduced structural dead load. The country's national building regulator mandates stringent fire safety and seismic resilience standards for tropical high-humidity deployments. The Jurong industrial estate concentrates demand for wire mesh ventilation technology in high-density server halls serving regional cloud infrastructure.
Cable Tray Market Key Industry Players
On the supply side, the industry is consolidating around integrated electrical infrastructure platforms and specialized cable management fabricators. Tiered competitive positioning separates multinational conglomerates with bundled switchgear-tray offerings from mid-cap regional specialists and commodity-grade local producers. Two strategic archetypes dominate: integrated platform suppliers leveraging project-scale procurement bundling, and niche specialists capturing hyperscale facility specifications through fiber routing expertise. Capacity expansion in Vietnam and Mexico and strategic partnerships with engineering-procurement-construction firms represent the dominant competitive vectors.
Among integrated platform suppliers, Schneider Electric exemplifies the bundled infrastructure archetype, while Panduit occupies a specialist position in fiber-centric cable management. Eaton Corporation represents the industrial-grade ladder tray segment engineered for heavy manufacturing and oil and gas environments. These three anchors illustrate the competitive tension between scale-driven integration and specification-driven specialization across divergent end-use verticals.
| Leading Market Players |
|---|
| Schneider Electric |
| Panduit |
| Legrand |
| Rittal |
| Hubbell |
| Atkore International Group |
| Eaton Corporation |
| Southwire |
| ABB |
| Others |
Cost & Logistics Intelligence
Hebei province's hot-dip galvanizing cluster anchors corrosion-resistant steel supply, concentrating pricing power among integrated coil-coaters serving NEMA VE 1-certified fabricators while transmitting energy cost shocks downstream to tray manufacturers competing on heavy industrial specifications.
Pricing Analysis
Industrial OEM buyers anchor project-based contract pricing with volume-scaled discounts tied to IEC 61537 and NEMA VE 1 certification tiers. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels separates specification eligibility in public infrastructure tenders. Cost compression in aluminum-magnesium alloy grades is intensifying because Yunnan smelter curtailments under MIIT dual carbon goals constrain ingot availability. Hyperscale data center procurement teams exhibit lowest price sensitivity, prioritizing seismic qualification and BIM coordination over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate procurement between Hebei coating facilities and Yangtze River Delta fabricators, with supply-chain finance facilities bridging working capital gaps for mid-tier producers. Manufacturing concentrates in China, India, and Vietnam, with raw material flows drawing from Australian bauxite, Indonesian nickel, and domestic Chinese steel coil. Single-source vulnerability clusters in Yunnan aluminum smelting and Hebei galvanizing capacity. Distribution runs through engineering-procurement-construction firms bundling cable management with switchgear and busway contracts in Northern Virginia and Frankfurt data center clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent cable tray manufacturers face substitution pressure from pre-terminated optical cable assemblies reducing tray fill requirements in hyperscale facilities with all-fiber backbones, demanding proactive positioning to defend specification share.
For Market Incumbents: Pre-empt fiber substitution by embedding RFID-enabled digital twin compatibility and intumescent coating investments for EU CPR EN 13501-4 compliance. Backward integration into low-carbon aluminum sourcing secures tender differentiation under EU Green Deal embodied carbon tracking. Certification investment in simultaneous NEMA VE 1 and IEC 61537 qualification compresses 14-18 month approval cycles for global project bids. For New Entrants and Emerging Players: Pursue Vietnam's northern industrial corridor where Samsung and Foxconn supplier parks require extensive cable management for semiconductor fabrication expansion. Target aluminum wire mesh specifications in India's PLI-accelerated Mumbai and Chennai data center buildouts. Position through BIM-compliant tray systems with embedded RFID tags enabling predictive maintenance in smart factory deployments. For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure-software convergence play because digital twin integration and predictive maintenance capabilities separate premium specification capture from commodity fabrication. Acquisition targets cluster around mid-cap regional specialists with IEC 61537 certification and established EPC firm relationships in data center corridors. Monitor hyperscale procurement bundling intensity as inflection indicator for integrated platform supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous NEMA VE 1 and IEC 61537 qualification unlocks global hyperscale and industrial tender pools. |
| Low-Carbon Aluminum Sourcing | EU Green Deal embodied carbon tracking favors verified low-carbon ingot for public infrastructure specifications. |
| Digital Twin Integration | BIM-compliant tray systems with embedded RFID tags enable predictive maintenance in smart factory deployments. |
| Regional Capacity Expansion | Vietnam and Mexico fabrication footprint captures supplier park demand from Samsung and Foxconn ecosystems. |
| Intumescent Coating Partnership | Third-party notified body collaboration satisfies EU CPR EN 13501-4 fire performance mandates filtering uncertified Asian suppliers. |
Research Approach
The analysis maps ladder tray, wire mesh, solid bottom, and perforated configurations, each validated through plant engineers at heavy industrial facilities, procurement leads at hyperscale data center operators, EPC contractors, and aftermarket service heads. Primary interviews with cable management specification consultants and electrical infrastructure directors at engineering firms combined with secondary validation from customs trade data, SEC filings of integrated electrical infrastructure suppliers, NEMA VE 1 certification registries, and IEC 61537 test report databases. Bottom-up installation volume estimates and top-down construction spending allocation triangulate market sizing across the projection horizon.
Assumptions held fixed include prevailing NEMA VE 1 and IEC 61537 certification requirements, while aluminum ingot price volatility and data center power density trajectories varied across sensitivity scenarios. Segmentation modeling spans product type, material grade, application vertical, and installation geometry, with CAGRs derived from construction spending elasticity and specification substitution patterns. Industry-specific forecast inputs incorporate MIIT dual carbon policy implementation intensity and PLI scheme disbursement timelines for Indian electronic manufacturing.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated platform suppliers or fiber-optic infrastructure providers would shift outcomes. Macroeconomic deviation in construction lending rates, regulatory acceleration in fire performance mandates, or technological breakthrough in wireless power transmission would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Water Leak Sensing Cable Market
Cables
Global Wires and Cables Market
Cables
Military Cable Market
Cables
North America Patch Cable Market
Cables
North America Coaxial Cable Market
Cables
Mineral Insulated (MI) Cable Market
Cables
Radio Frequency Cables Market
Cables
Downhole Cables Market
Cables
Cable Testing Market
Cables
Global Cable Blowing Equipment Market
Cables
Submarine Cabling Systems Market
Cables
India Optic Fiber Cable and Accessories Market
Cables
LED Cable Market
Cables
Europe Cable Accessories Market
Cables
Control Cable Market
Cables
Underground Cable Market