
 Vacuum Interrupter Market | 2026-2036
Vacuum Interrupter Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Interrupter Market Intelligence
Copper-chrome contact material substitution is fragmenting traditional vacuum interrupter manufacturing as ceramic-to-metal sealing advances enable higher breaking capacity designs. Eaton Corporation plc leverages backward integration into contact material production to secure supply continuity across North American utility contracts. Meidensha Corporation anchors its position through dedicated axial magnetic field R&D facilities in Japan. ABB Ltd competes on switchgear system integration, bundling vacuum interrupters with digital monitoring platforms.
A vacuum interrupter is a sealed vacuum chamber containing separable contacts that extinguishes electrical arcs without insulating gas, typically rated for 1 kV to 145 kV and operating at contact gaps below 12 mm to interrupt fault currents up to 100 kA. The device serves as the core switching element in circuit breakers and contactors where SF6 elimination has become critical for environmental compliance. Medium voltage interrupters dominate unit volumes due to distribution grid retrofit cycles across aging infrastructure in Europe and North America. Radial magnetic field technology leads in installed base but axial magnetic designs are capturing share in high-current renewable energy applications where contact erosion limits service life. The circuit breaker application channel concentrates margin pools because OEMs specify interrupters as captive components within integrated switchgear assemblies.
Utilities procurement teams now face overlapping compliance frameworks including IEC 62271-100 for high-voltage switchgear, IEEE C37.04 for rating structures, and EU F-Gas Regulation restrictions that accelerate SF6-to-vacuum transitions in European grids. China's GB standards and India's CEA technical specifications for substation equipment further fragment certification requirements for suppliers seeking multi-regional qualification. Stakeholders must monitor contact material cost trajectories and regional certification timelines when allocating manufacturing capacity across ceramic sealing and vacuum brazing process lines.
Market Dynamics
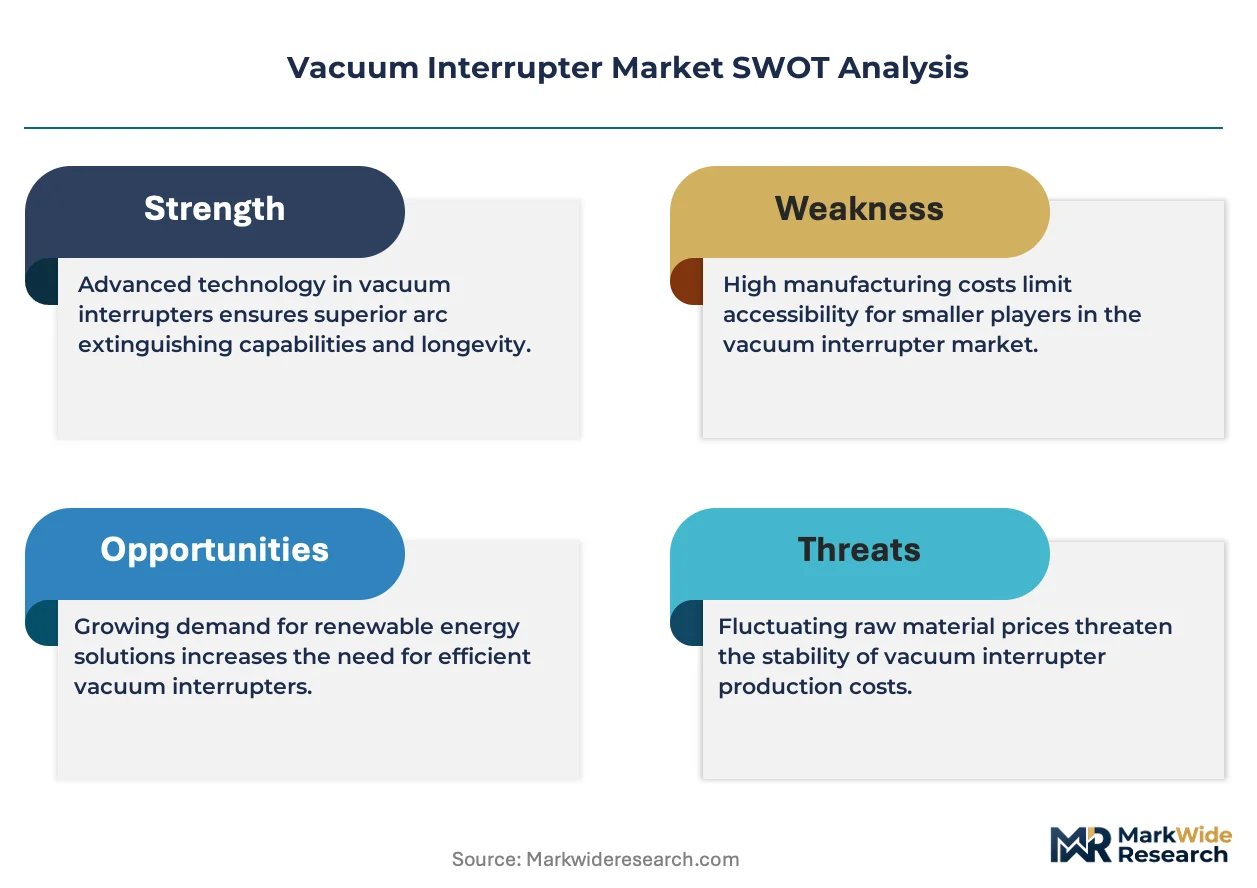
Copper-chrome contact material substitution and axial magnetic field technology maturation are fragmenting manufacturing footprints while compressing traditional radial magnetic field installed bases across utility procurement cycles.
Growth Catalysts
- IEC 62271-100 compliance mandates:European utilities accelerate SF6-to-vacuum transitions under EU F-Gas Regulation phase-down schedules, concentrating switchgear replacement demand in Germany and France.
- Renewable energy cluster expansion:Wind and solar interconnection projects in China and India drive high-current vacuum interrupter specifications for collector substations and inverter stations.
- Ceramic-to-metal sealing advances:Brazing process improvements enable 145 kV rated designs with sub-12 mm contact gaps, opening transmission-level applications previously reserved for gas-insulated alternatives.
Market Restraints
- Contact material cost volatility:Chrome price fluctuations and copper supply chain disruptions from Chilean and Peruvian mining operations squeeze margin structures for non-integrated manufacturers.
- Regional certification fragmentation:China's GB standards, India's CEA specifications, and IEEE C37.04 rating structures impose parallel qualification timelines that extend product launch cycles by 18-24 months.
- Technical service life limitations:Contact erosion rates in high-current renewable applications constrain axial magnetic field interrupter replacement intervals below traditional distribution grid expectations.
Strategic Opportunities
- Underpenetrated Indian transmission sector:National grid expansion under CEA technical specifications creates virgin demand for 72.5 kV and 145 kV vacuum interrupter classes in substation greenfield projects.
- Digital switchgear convergence:Integration with IEC 61850-compliant monitoring platforms enables predictive maintenance service contracts that capture recurring revenue streams from European utilities.
- US IRA manufacturing incentives:Domestic content requirements for federally funded grid modernization projects favor North American vacuum interrupter production capacity expansion.
Industry Challenges
- Vacuum brazing technician scarcity:Ceramic sealing expertise concentrates in Japanese and German industrial clusters, limiting workforce mobility for new manufacturing facility ramp-ups.
- Legacy SF6 infrastructure compatibility:Retrofit specifications for aging European substations require custom mechanical interface designs that fragment production runs and inflate engineering overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Interrupter Market |
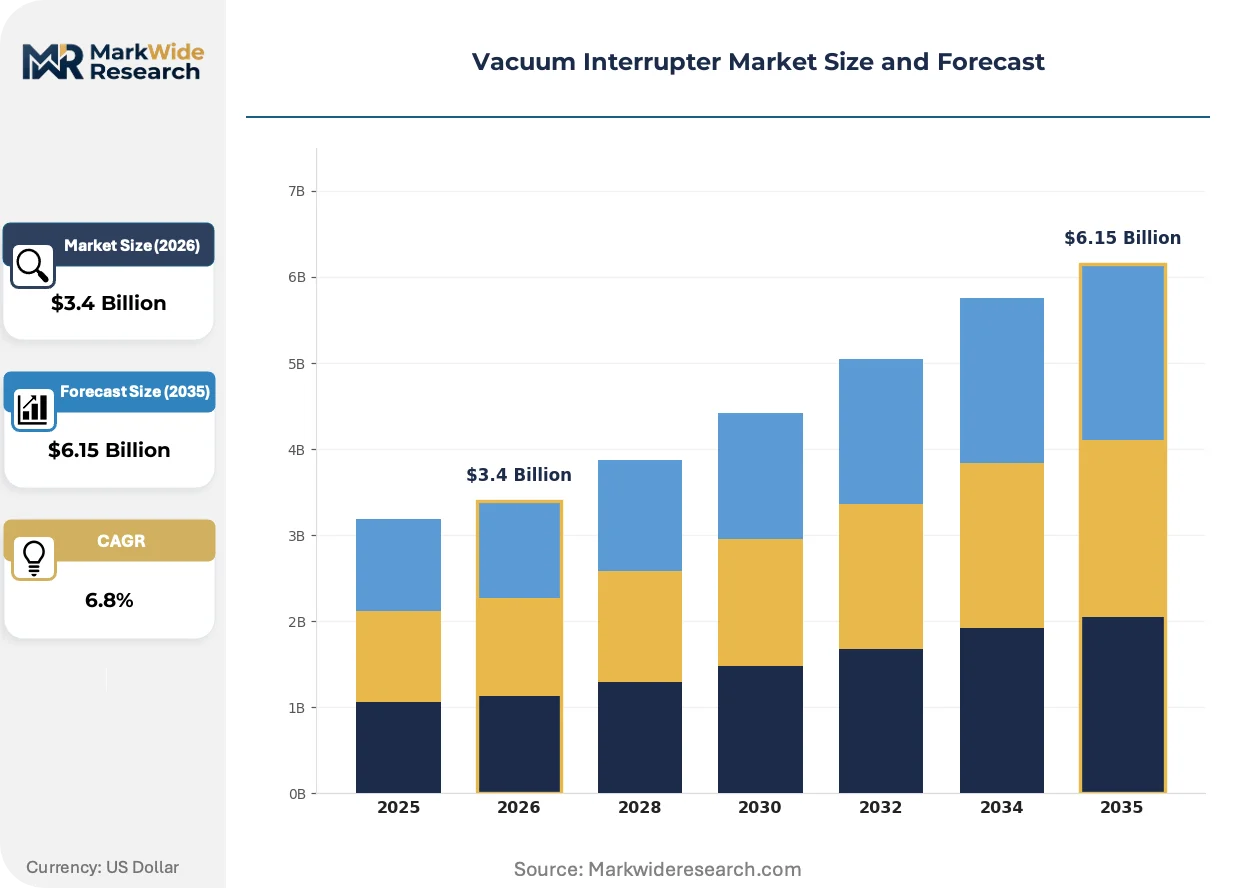
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage Technology: Axial Magnetic, Radial Magnetic, Double Break, Hybrid Application: Power Distribution, Substation Equipment, Switchgear, Circuit Breakers End User: Utilities, Industrial Plants, Power OEMs, Renewable Energy |
| Companies Covered | Eaton Corporation plc, Meidensha Corporation, ABB Ltd, LS Electric Co Ltd, General Electric, Mitsubishi Electric Corporation, Toshiba Corporation, Schneider Electric SE, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Interrupter Market Strategic Shifts & Innovations
Material science breakthroughs and regulatory phase-outs are compressing technology adoption cycles while reshaping how OEMs bundle switching components with digital infrastructure.
Axial magnetic field contact geometry is hybridizing traditional radial magnetic field dominance in high-current applications. Wind farm collector substations specify these designs for 63 kA interrupting duty cycles. The technology is hybridizing procurement patterns as utilities accept shorter service life trade-offs for superior arc control in renewable interconnection duty.
EU F-Gas Regulation restrictions on SF6 emissions are accelerating mandatory vacuum technology transitions in European high-voltage switchgear. The policy compresses incumbent gas-insulated equipment replacement timelines. German transmission operators now specify vacuum interrupters as default for new 145 kV substation installations.
Utility procurement teams now unbundle interrupter supply from integrated switchgear contracts. European and North American distribution cooperatives source vacuum interrupters separately from OEM assemblies to secure multi-source qualification. This pattern concentrates most visibly in German municipal utility purchasing frameworks where direct component procurement reduces switchgear total cost of ownership.
Vacuum Interrupter Market Segmentation
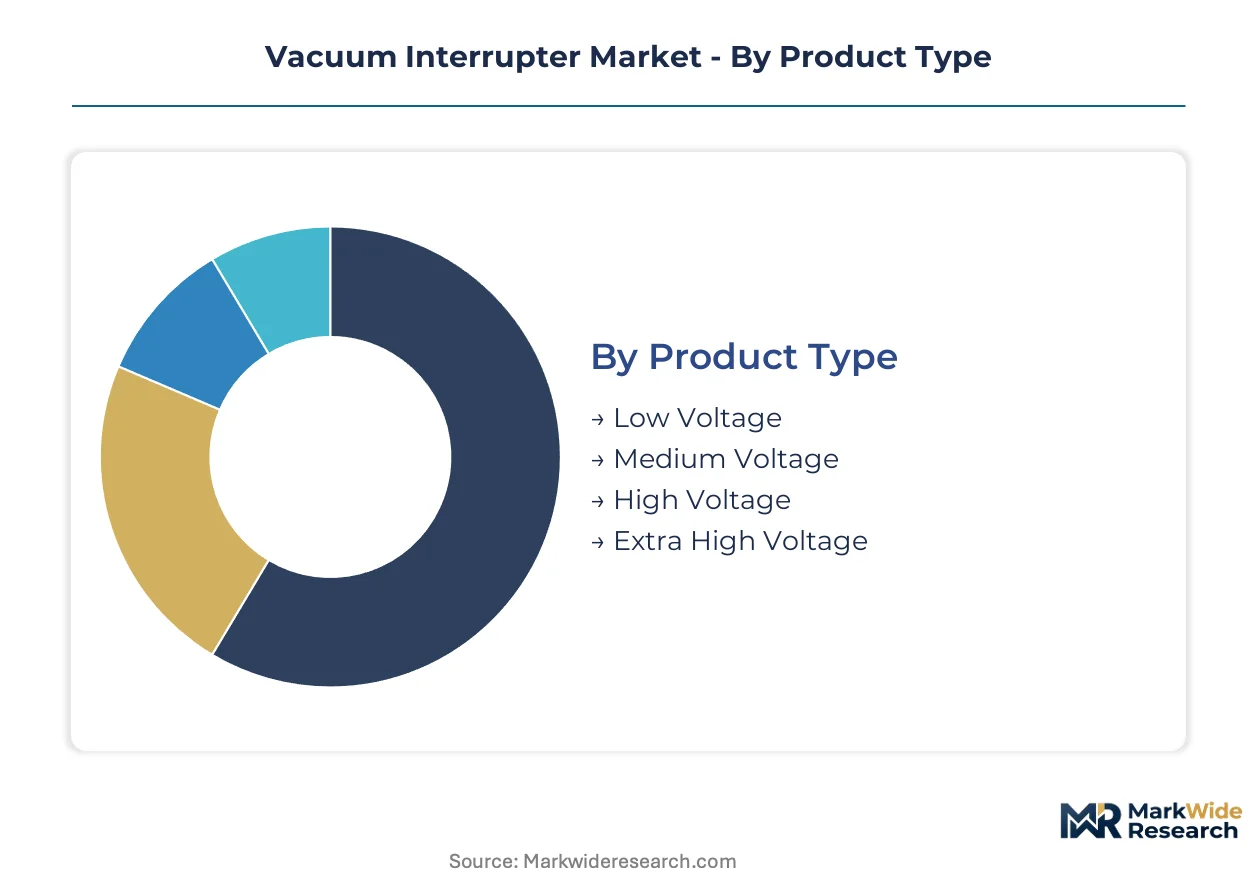
Vacuum interrupter procurement cycles vary dramatically across voltage classes and end-use sectors, with distribution utilities driving replacement volume while transmission operators specify longer-life designs. Understanding these turnover rhythms helps suppliers align capacity planning with actual demand pulses rather than aggregate growth figures.
Product Type:
Medium voltage interrupters turn over fastest due to distribution grid retrofit cycles, while extra high voltage units operate on decade-long replacement timelines tied to transmission asset management programs.
- Medium Voltage:Rated 1 kV to 52 kV, these interrupters dominate unit shipments across European and North American distribution infrastructure renewal programs. German municipal utilities and US rural electric cooperatives specify these for pole-mounted reclosers and pad-mounted switchgear where SF6 elimination has become procurement policy.
- High Voltage:Covering 52 kV to 145 kV ratings, this class is capturing share fastest in China's expanding ultra-high voltage transmission corridors and India's greenfield substation projects under CEA technical specifications. Ceramic-to-metal sealing advances now enable sub-12 mm contact gaps at these voltage levels.
- Low Voltage:Sub-1 kV designs serve industrial motor control and mining contactor applications with shorter procurement cycles than utility-specified equipment.
- Extra High Voltage:Above 145 kV applications remain limited by vacuum gap constraints, though R&D programs in Japan and Germany are pushing ceramic sealing boundaries for future 245 kV designs.
Medium voltage anchors the volume base while high voltage gains share at the steepest rate.
Technology:
Cost structures stratify sharply between mature radial magnetic designs and premium axial magnetic field geometries requiring precision-machined contact assemblies.
- Axial Magnetic:Contact geometry generates longitudinal magnetic fields that rotate arcs across the contact surface, reducing erosion rates in high-current renewable energy applications. Wind farm collector substations in China and India specify these for 63 kA interrupting duty, accepting shorter service life trade-offs for superior arc control.
- Radial Magnetic:Traditional transverse field designs maintain installed base dominance across distribution grid applications where 20-30 kA interrupting capacity suffices. European utilities specify these for cost-sensitive retrofit programs where proven reliability outweighs performance margins.
- Double Break:Dual-contact configurations achieve higher voltage ratings through series gap arrangement, finding niche application in compact switchgear designs where space constraints override cost considerations.
- Hybrid:Combined vacuum-SF6 or vacuum-air technologies address specific fault current limitation requirements in specialized industrial installations.
Radial magnetic technology retains the largest installed base while axial magnetic field designs are expanding most quickly in renewable interconnection specifications.
Application:
Customer procurement authority concentrates differently across equipment types, with circuit breaker OEMs exercising captive interrupter specification power while switchgear assemblers accept third-party component sourcing.
- Circuit Breakers:Vacuum interrupters serve as core switching elements in dead tank and live tank breaker designs where manufacturers specify captive components. This channel captures premium margin pools through integrated assembly contracts with utilities and industrial end-users.
- Switchgear:Metal-enclosed and metal-clad assemblies incorporate interrupters as modular components, enabling European and North American distribution cooperatives to source vacuum chambers separately from OEM switchgear to secure multi-source qualification.
- Power Distribution:Ring main units and sectionalizers deploy interrupters in automated feeder applications where frequent switching operations demand contact materials optimized for mechanical endurance rather than single-shot fault interruption.
- Substation Equipment:Transformer protection and bus coupler applications specify interrupters with extended electrical life ratings aligned with primary asset replacement cycles.
Circuit breaker applications concentrate margin capture while switchgear unbundling trends are climbing the fastest as procurement teams seek component-level supplier diversification.
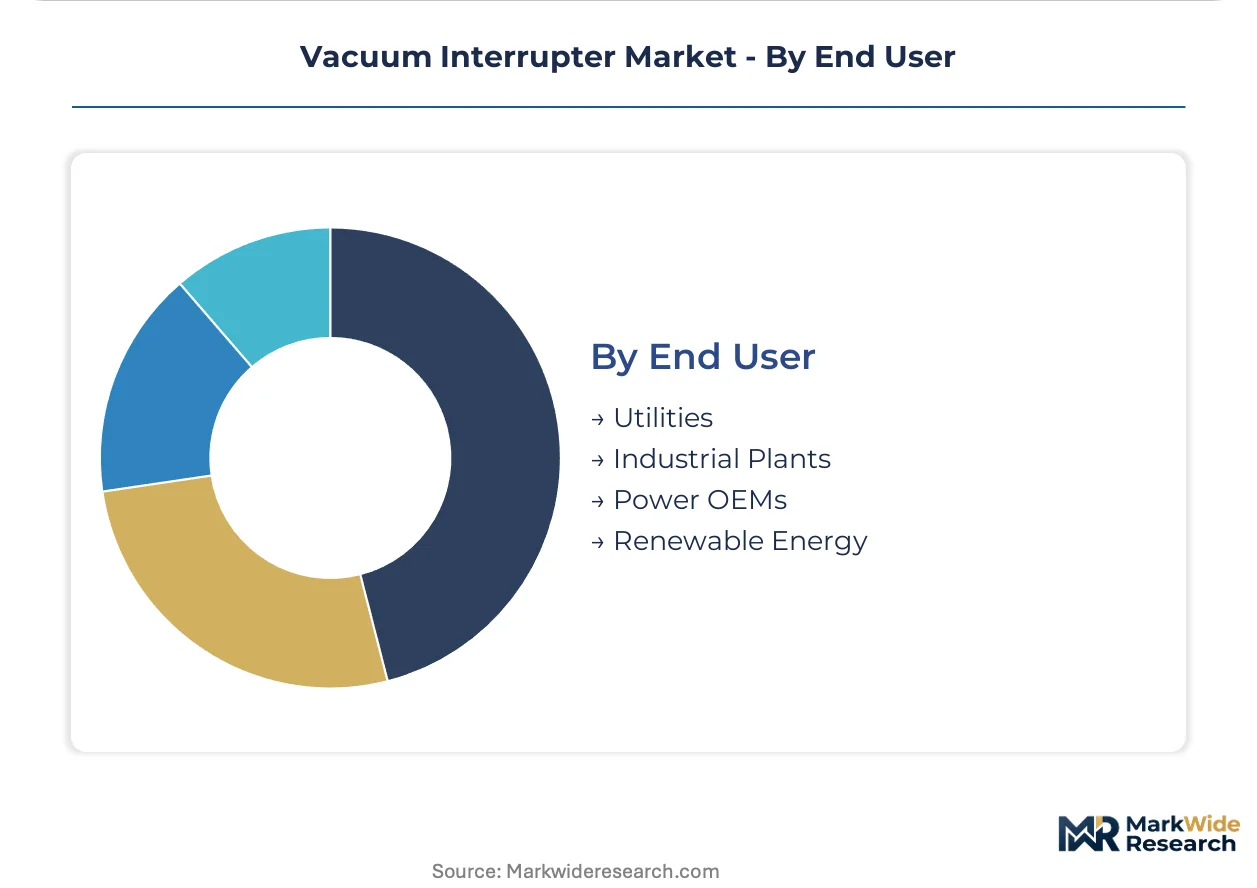
End User:
Customer sophistication and specification authority vary across utility, industrial, and renewable developer segments, with power OEMs intermediating technical requirements between component suppliers and final installations.
- Utilities:Grid operators in Germany, France, and Japan drive standardization through technical specifications that cascade to equipment suppliers. These customers prioritize lifecycle cost optimization and regulatory compliance over upfront capital expenditure.
- Renewable Energy:Wind and solar developers in China and India represent the steepest expansion trajectory, specifying high-current interrupters for collector substations and inverter stations where fault current characteristics differ fundamentally from conventional generation.
- Industrial Plants:Mining, steel, and chemical facilities procure interrupters for motor protection and process power distribution with procurement cycles tied to plant expansion schedules rather than grid infrastructure renewal.
- Power OEMs:Switchgear and breaker manufacturers exercise intermediate purchasing power, bundling interrupters into integrated equipment offerings while maintaining qualification relationships with multiple vacuum chamber suppliers.
Utility procurement anchors the revenue base while renewable energy developers are gaining share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German vacuum interrupter manufacturers export ceramic-sealed chambers to utility buyers across France, Poland, and Scandinavia under EU F-Gas Regulation compliance timelines. This trade corridor concentrates high-voltage specification authority in Düsseldorf and Munich engineering clusters while Asian producers feed renewable energy demand in China and India.
Germany
Transmission operators in North Rhine-Westphalia specify 145 kV vacuum interrupters as default for new substation installations under EU F-Gas Regulation phase-down mandates. The country's national energy regulator, Bundesnetzagentur, enforces SF6 emission reporting that accelerates gas-insulated switchgear replacement cycles. Siemens AG and ABB Ltd maintain captive production facilities in Bavaria and Hesse serving Central European utility procurement frameworks.
China
State Grid Corporation expands ultra-high voltage transmission corridors requiring 72.5 kV and 145 kV vacuum interrupter classes for collector substations and inverter stations. GB standards issued by the State Administration for Market Regulation fragment certification requirements for foreign suppliers seeking multi-regional qualification. Manufacturing gravity centers on Yangtze River Delta industrial zones where domestic producers scale ceramic-to-metal sealing capacity for wind farm interconnection projects.
India
National grid expansion under Central Electricity Authority technical specifications creates virgin demand for high-voltage vacuum interrupter classes in greenfield substation projects across Maharashtra and Gujarat. The Ministry of Power's renewable purchase obligations drive solar and wind interconnection specifications that differ from conventional generation fault current characteristics. LS Electric Co Ltd and domestic fabricators position production capacity near Mumbai-Pune industrial corridors to serve state transmission utility procurement cycles.
United States
Rural electric cooperatives and municipal utilities in Texas and California accelerate SF6-to-vacuum transitions in distribution infrastructure renewal programs. Federal Energy Regulatory Commission grid modernization incentives and Inflation Reduction Act domestic content requirements favor North American production capacity expansion. Eaton Corporation plc leverages backward integration into contact material production to secure supply continuity across utility contracts concentrated in Midwest and Southeast substation retrofit cycles.
Japan
Axial magnetic field R&D programs in Tokyo and Osaka industrial clusters advance contact geometry for high-current renewable energy applications. METI energy transition roadmaps prioritize vacuum technology for offshore wind interconnection and grid stabilization projects. Meidensha Corporation and Mitsubishi Electric Corporation anchor domestic manufacturing in Chubu and Kansai regions while exporting ceramic-sealed chambers to Southeast Asian transmission expansion programs.
Vacuum Interrupter Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented procurement authority structures. Integrated switchgear manufacturers exercise captive interrupter specification power in circuit breaker contracts, while independent vacuum chamber suppliers capture unbundled demand from European distribution cooperatives. Three archetypes dominate: vertically integrated electrical conglomerates with captive ceramic sealing facilities; mid-scale specialists focused on axial magnetic field geometries; and regional fabricators serving national certification requirements. Capacity expansion and strategic partnerships constitute the dominant competitive moves as suppliers align manufacturing footprints with IRA domestic content requirements and EU F-Gas Regulation compliance deadlines.
Within the integrated conglomerate tier, Eaton Corporation plc and ABB Ltd exemplify channel-control strategies through switchgear system integration and digital monitoring platform bundling. Meidensha Corporation occupies a specialist position anchored by dedicated axial magnetic field R&D facilities. Among Asia-Pacific producers, LS Electric Co Ltd and Mitsubishi Electric Corporation represent scale-driven fabrication archetypes serving renewable energy cluster expansion in China and India. These named entities illustrate how geographic origin and corporate structure map to competitive positioning without implying specific technology commitments or market share claims.
| Leading Market Players |
|---|
| Eaton Corporation plc |
| Meidensha Corporation |
| ABB Ltd |
| LS Electric Co Ltd |
| General Electric |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Schneider Electric SE |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Undercapacity in Japanese ceramic sealing facilities is driving dual sourcing mandates from European utilities while compressing margin structures for non-integrated manufacturers competing on axial magnetic field specifications.
Pricing Analysis
Cost-plus contracts indexed to LME copper and chrome price benchmarks dominate procurement frameworks for high-current vacuum interrupter classes. Three-tier pricing structure across premium axial magnetic, standard radial magnetic, and economy distribution-grade levels reflects certification complexity and contact material grade. Cost compression in the mid-tier segment is intensifying because Chinese producers are scaling ceramic-to-metal sealing capacity for domestic renewable energy projects. European distribution cooperatives exhibit highest price sensitivity due to unbundled component sourcing, while Japanese transmission operators prioritize contact erosion performance over capital expenditure.
Supply Chain Analysis
Export control regimes on vacuum brazing equipment and ceramic-to-metal sealing technology limit capacity transfer from Japanese and German industrial clusters to emerging manufacturing locations. Supply concentrates in Japan, Germany, and China, with raw material flows drawing from Chilean copper concentrate and South African chrome ore. Single-source vulnerability concentrates in vacuum brazing technician expertise anchored in Tokyo and Munich engineering centers. Distribution runs through captive OEM channels for circuit breaker applications and direct procurement frameworks for European utility switchgear unbundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vacuum interrupter demand sits in early-cycle expansion as EU F-Gas Regulation mandates accelerate SF6-to-vacuum transitions ahead of replacement timelines for installed gas-insulated switchgear.
For Market Incumbents: Entrench position through backward integration into copper-chrome contact material production and captive ceramic sealing capacity in Bavaria or Hesse to secure supply continuity against price volatility from Chilean mining disruptions. Defend margin structures by controlling specification authority in integrated circuit breaker contracts where OEMs bundle vacuum interrupters with digital monitoring platforms. For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated 72.5 kV and 145 kV transmission substation segment where CEA technical specifications create virgin demand for high-voltage classes. Target renewable energy developers in Maharashtra and Gujarat with axial magnetic field designs optimized for wind farm collector substation duty cycles, leveraging direct sales relationships bypassing established OEM channels. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among suppliers with IEC 61850-compliant digital monitoring platform integration that captures predictive maintenance service contracts from European utilities. Long-term viability over a multi-year horizon favors acquisition targets with axial magnetic field R&D programs and qualified positions under both IEC 62271-100 and IEEE C37.04 rating structures. Monitor chrome price volatility and Chinese GB standards certification timelines as inflection indicators for margin compression and market access constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Contact Materials | Eaton Corporation plc secures copper-chrome supply continuity against Chilean mining disruptions. |
| Axial Magnetic Field R&D Facility Investment | Meidensha Corporation anchors high-current renewable energy specification authority in Japan. |
| Digital Monitoring Platform Integration | ABB Ltd bundles vacuum interrupters with IEC 61850-compliant predictive maintenance services. |
| Domestic Capacity Expansion | North American producers capture IRA domestic content requirements for federally funded grid projects. |
| Multi-Regional Certification Qualification | Suppliers reduce 18-24 month launch cycles by parallel-tracking IEC, IEEE, GB, and CEA approvals. |
Research Approach
The analysis maps vacuum interrupter sub-sectors across voltage classes, contact material grades, and magnetic field geometries, each validated through utility procurement directors, switchgear OEM technical leads, and ceramic sealing process engineers. Primary interviews with Bundesnetzagentur grid planning officers, State Grid Corporation specification managers, and CEA substation equipment committees combined with secondary validation from IEC 62271-100 certification databases, IEEE C37.04 rating structure documentation, and EU F-Gas Regulation emission reporting. Bottom-up triangulation across manufacturing capacity announcements and top-down reconciliation against transmission infrastructure investment flows anchored volume and value estimates.
Assumptions held fixed across the projection horizon include EU F-Gas Regulation phase-down schedules, China's dual carbon policy trajectory, and India's renewable purchase obligation enforcement. Variables stress-tested encompass chrome price volatility bands, vacuum brazing technician availability constraints, and Chinese GB standards adoption timelines. Segmentation dimensions modeled span voltage rating tiers, magnetic field technology types, application channels, and end-user procurement authority structures. CAGRs derived from installed base replacement cycles, renewable energy interconnection project pipelines, and regional certification penetration curves.
Stress conditions across copper-chrome material cost trajectories, ceramic sealing yield rates, and regional certification timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions while acknowledging that unanticipated regulatory acceleration in SF6 phase-outs or breakthroughs in 245 kV vacuum gap designs could materially revise trajectory. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Middle East and Africa Electric Drives Market
Electrical Equipment
Ceiling Fans Market
Electrical Equipment
Electric Control Panel Market
Electrical Equipment
Ground Fault Circuit Interrupter Market
Electrical Equipment
Alligator Clips Market
Electrical Equipment
Vacuum Contactor Market
Electrical Equipment
Earth Leakage Circuit Breakers Market
Electrical Equipment
High Voltage Insulator Market
Electrical Equipment
Global Medium Voltage Electric Drives Market
Electrical Equipment
Electric Motors for Conveyor System Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Saudi Arabia Industrial Electrical Components Market
Electrical Equipment
Cable Distribution Cabinets Market
Electrical Equipment
Rotary and RF Rotary Joints Market
Electrical Equipment
Electric Enclosure Market