
 Global Solid State Lidar Sensor Market | 2026-2036
Global Solid State Lidar Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solid State Lidar Sensor Market Outlook
A capital-intensity divergence between photonic chip foundry investments and software-centric sensor fusion stacks is reorganizing competitive tiers. Luminar Technologies anchors its position through captive InGaAs receiver fabrication. Hesai Technology dominates high-volume automotive contracts with tier-one integrators. Cepton differentiates via frequency-modulated continuous wave architectures for highway-speed perception.
Solid-state lidar sensors replace mechanical spinning assemblies with semiconductor-based beam steering, typically employing optical phased arrays or MEMS mirrors to achieve sub-degree angular resolution across 200-meter ranges. The devices serve primarily as perception engines for autonomous navigation systems requiring real-time point-cloud generation. Three-dimensional lidar captures the dominant share of automotive design wins, while frequency-modulated continuous wave variants attract investment for their direct velocity-measurement capability and resilience to solar interference. UAV lidar occupies a specialized niche in precision agriculture and forestry canopy mapping, where weight constraints favor chip-scale integration.
The U.S. National Highway Traffic Safety Administration and the EU's Vehicle General Safety Regulation mandate specific object-detection performance for higher automation levels, directly specifying sensor redundancy requirements. China's Ministry of Industry and Information Technology issues GB standards for intelligent connected vehicles that incorporate lidar environmental perception benchmarks. Stakeholders must monitor which regulatory frameworks adopt explicit range-resolution minimums versus performance-based safety goals, as this distinction determines validation cost structures and design lock-in timelines.
Market Dynamics
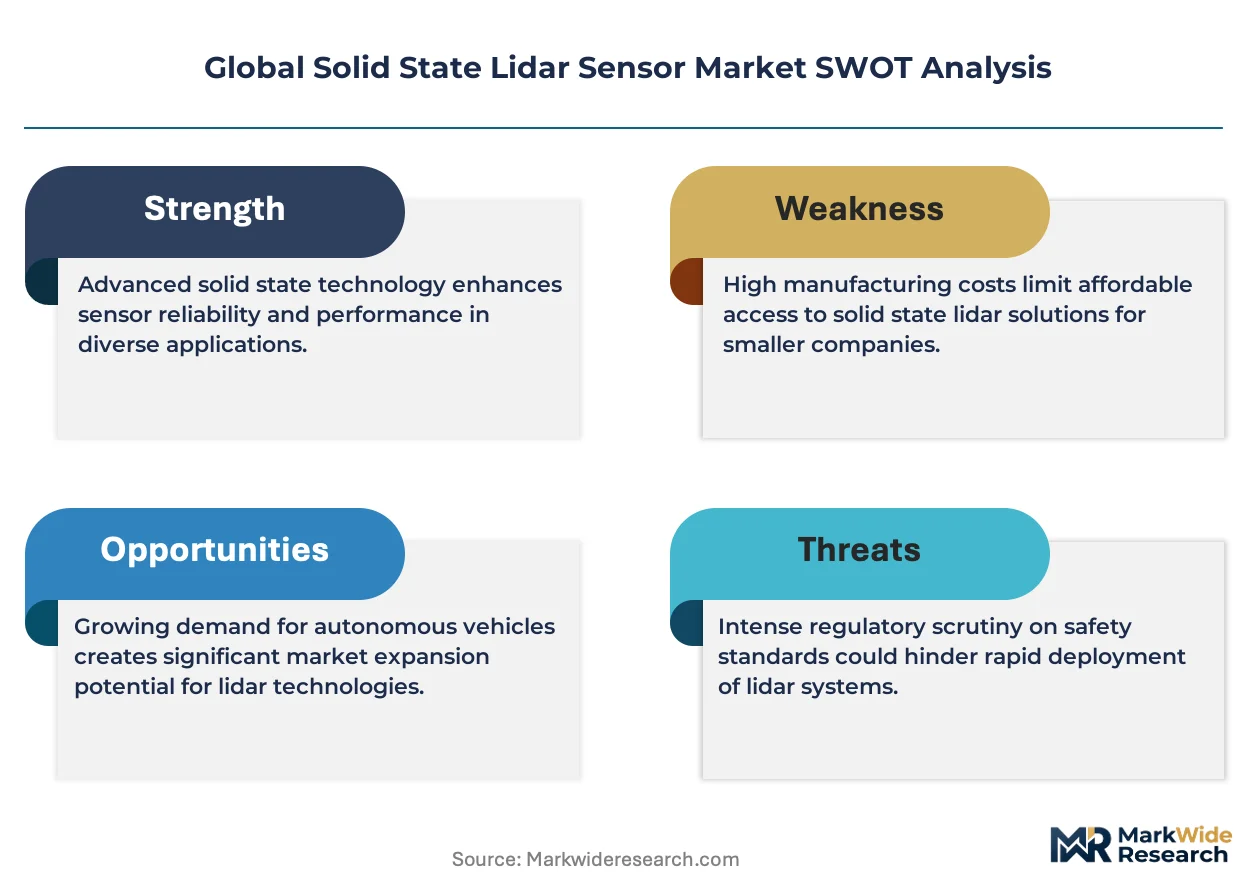
The capital intensity of photonic chip foundries is concentrating manufacturing capacity among a handful of semiconductor specialists, forcing lidar vendors to choose between captive fabrication investments and fabless dependence on external supply.
Growth Catalysts
- EU AI Act certification pathways:The regulation's conformity assessment procedures for safety-critical AI systems create procurement pull from automotive OEMs seeking pre-validated sensor architectures for Level 3+ automation.
- Frequency-modulated continuous wave architectures:Direct velocity measurement without Doppler ambiguity attracts highway-speed perception contracts from premium sedan programs requiring 250-meter detection ranges.
- China's MIIT GB standards:Mandatory environmental perception benchmarks for intelligent connected vehicles lock lidar into production vehicle specifications across NIO, Xpeng, and Li Auto lineups.
Market Restraints
- InGaAs receiver wafer supply:Foundry capacity for 1550nm-compatible avalanche photodiodes concentrates in Taiwan and the United States, exposing vendors to single-source risk during demand surges.
- Optical phased array yield rates:Semiconductor fabrication defects in silicon photonics waveguides constrain unit economics for chip-scale beam steering below mechanical alternatives.
- Camera-radar fusion cost floors:Tesla's vision-only autonomy stack demonstrates perception viability without lidar, pressuring pricing ceilings in mass-market vehicle segments.
Strategic Opportunities
- India's PLI scheme for automotive components:Production-linked incentives for advanced driver-assistance systems attract contract manufacturing investments serving domestic electric vehicle programs.
- UAV precision agriculture:Weight-constrained forestry and crop-mapping applications favor solid-state form factors over mechanical assemblies for canopy penetration and topographic survey.
- ISO 26262 functional safety convergence:ASIL-D certification alignment between lidar processing ASICs and vehicle domain controllers reduces integration validation cycles for tier-one suppliers.
Industry Challenges
- Silicon photonics talent scarcity:Foundry process engineers with expertise in integrated optical phased arrays command premium compensation, constraining R&D velocity at mid-scale vendors.
- Vehicle-type approval timelines:Germany's KBA certification procedures for sensor-equipped autonomous fleets extend design lock-in periods, compressing window for hardware iteration.
- Multi-sensor calibration complexity:Synchronization between solid-state lidar point clouds and camera image streams demands specialized systems integration capabilities scarce among traditional tier-one integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solid State Lidar Sensor Market |
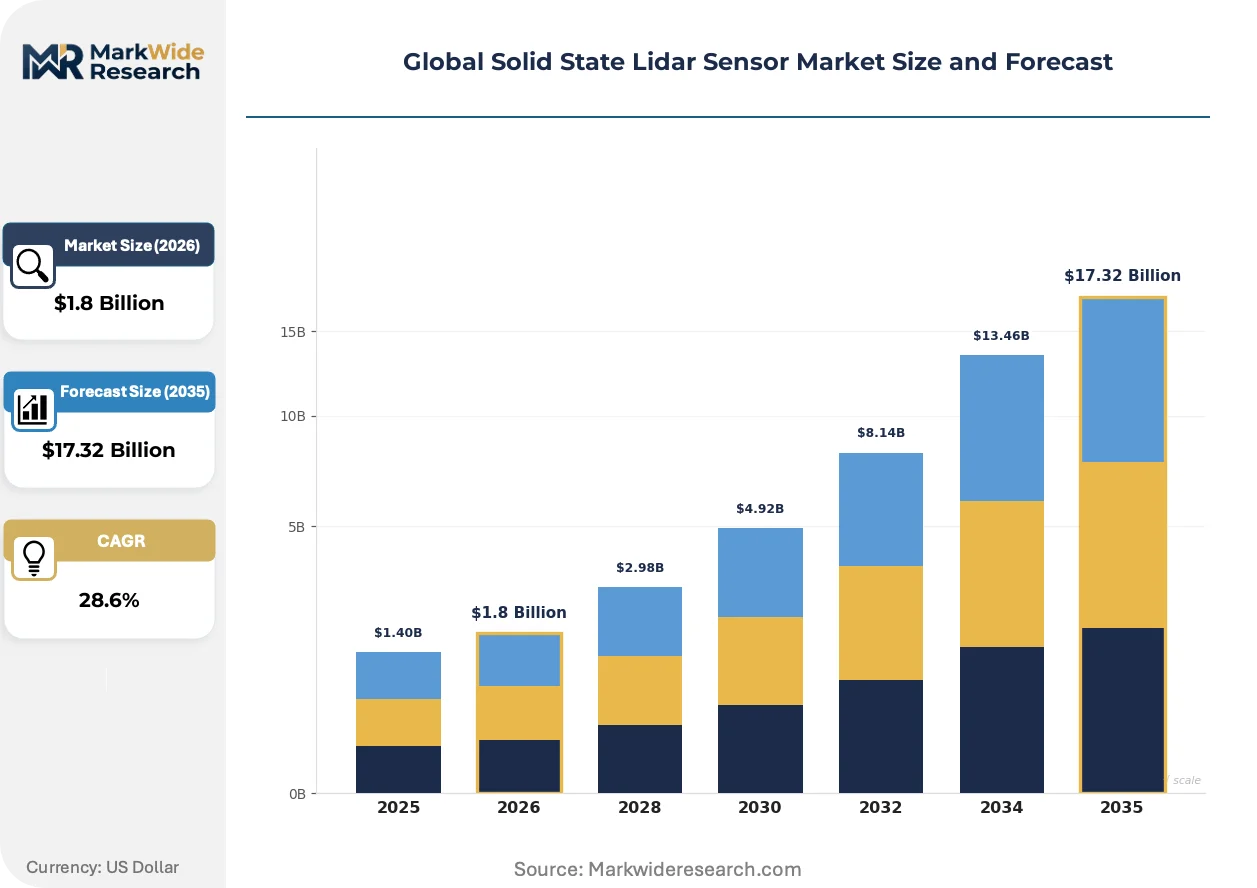
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.32 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Lidar, 3D Lidar, Automotive Lidar, UAV Lidar End User: Automotive, Aerospace, Robotics, Mapping Technology: Optical, Infrared, Time-of-Flight, Frequency Modulated Continuous Wave Application: Autonomous Vehicles, Surveying, Infrastructure, Environmental Monitoring |
| Companies Covered | Ouster, Luminar Technologies, Innoviz Technologies, Hesai Technology, Quanergy Systems, Aeva Technologies, RoboSense, Cepton, LeddarTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solid State Lidar Sensor Market Strategic Shifts
Beam steering architectures are splitting into two irreconcilable technical camps, with each path attracting distinct buyer segments and locking vendors into incompatible supply chain investments.
Optical phased arrays are bifurcating the high-volume automotive segment from defense and industrial applications. MEMS mirror vendors capture mainstream sedan contracts through proven reliability records. Chip-scale integration is compressing bill-of-materials costs below 500 dollars per unit for 2027 model year programs.
Germany's KBA vehicle-type approval rules now mandate redundant perception coverage for urban autonomous operation. OEMs must demonstrate sensor fault tolerance through documented failure-mode analyses. Highway-speed lidar specifications face the strictest validation requirements, pushing vendors toward dual-architecture designs combining solid-state coverage with mechanical long-range modules.
Fleet procurement contracts now dominate hardware volume planning at Waymo and Cruise. Direct OEM negotiations displace traditional tier-one distribution for autonomy-grade sensors. This channel consolidation is most visible in California and Arizona, where robotaxi deployment permits concentrate demand among three vertically integrated operators.
Global Solid State Lidar Sensor Market Segmentation
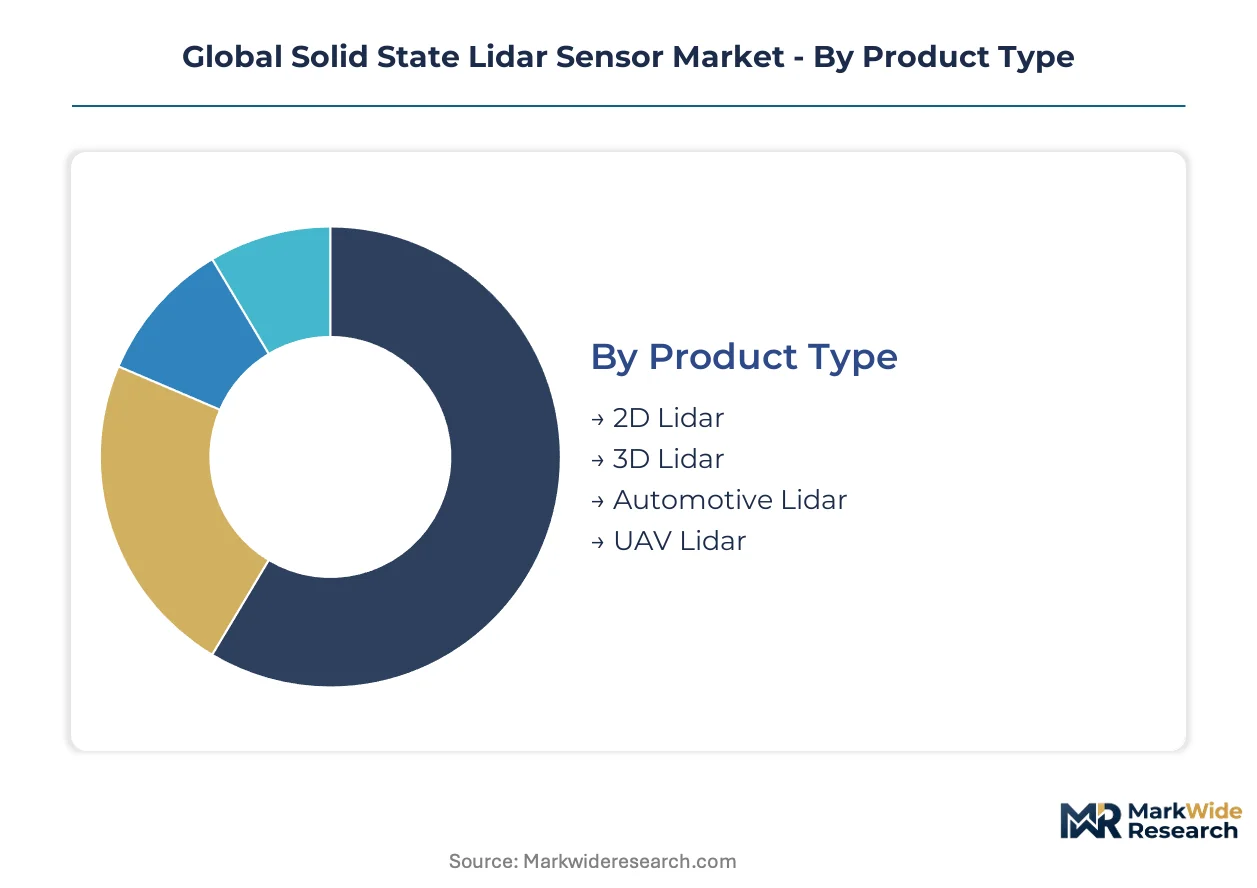
Solid-state lidar vendors navigate divergent performance requirements across automotive autonomy, precision agriculture, and industrial robotics. Segmentation reveals where chip-scale integration commands premium pricing versus where mechanical alternatives retain cost advantages. Procurement patterns cluster around regulatory validation tiers rather than raw technical specifications.
Product Type:
Domestic Chinese OEMs drive volume for 3D automotive variants, while European and North American exports concentrate in specialized UAV and 2D industrial configurations. Geographic demand dispersion shapes foundry allocation and beam-steering architecture selection.
- 3D Lidar:Dense point-cloud generation at 200-meter ranges supports Level 3+ automation perception stacks. NIO, Xpeng, and Li Auto integrate these units into production sedans under China's MIIT GB standards, locking in high-volume procurement contracts.
- Automotive Lidar:ASIL-D functional safety certification dominates OEM qualification timelines. Waymo and Cruise fleet procurement concentrates demand in California and Arizona, bypassing traditional tier-one distribution channels for autonomy-grade hardware.
- 2D Lidar:Simpler scanning patterns serve indoor robotics and warehouse automation with lower unit costs.
- UAV Lidar:Weight-constrained forestry and canopy-mapping applications favor chip-scale solid-state form factors over mechanical assemblies.
Automotive Lidar commands the established base. The steepest expansion runs through 3D Lidar.
End User:
Cost tiers separate validated automotive contracts from exploratory robotics deployments. Premium pricing attaches to safety-critical applications requiring ISO 26262 certification, while mapping and robotics segments absorb higher failure rates for lower per-unit expenditure.
- Automotive:Vehicle-type approval rules in Germany and the EU AI Act mandate redundant perception coverage for urban autonomous operation. OEMs demonstrate fault tolerance through documented failure-mode analyses, extending design lock-in periods.
- Robotics:Indoor navigation and warehouse automation tolerate shorter-range specifications with relaxed environmental sealing. Sensor fusion with cameras reduces lidar channel count, compressing bill-of-materials below automotive thresholds.
- Aerospace:Military and commercial aviation applications demand extended temperature ranges and vibration resistance.
- Mapping:Topographic survey and construction progress monitoring prioritize accuracy over real-time performance.
Automotive absorbs the dominant revenue share. Robotics is climbing the fastest as warehouse automation scales.
Technology:
Supply concentration in photonic chip foundries forces architecture lock-in decisions early in vendor development cycles. InGaAs receiver wafer availability and silicon photonics yield rates determine which technical camps attract investment.
- Frequency Modulated Continuous Wave:Direct velocity measurement without Doppler ambiguity attracts highway-speed perception contracts. Cepton and select vendors differentiate through 250-meter detection ranges for premium sedan programs.
- Optical:MEMS mirror implementations capture mainstream sedan contracts through proven reliability records and established automotive qualification pathways.
- Time-of-Flight:Pulsed laser architectures dominate cost-sensitive proximity applications with simpler signal processing requirements.
- Infrared:1550nm wavelength selection balances eye safety margins with atmospheric penetration for long-range detection.
Optical architectures hold the installed base. Frequency Modulated Continuous Wave is gaining share fastest among highway-speed specifications.
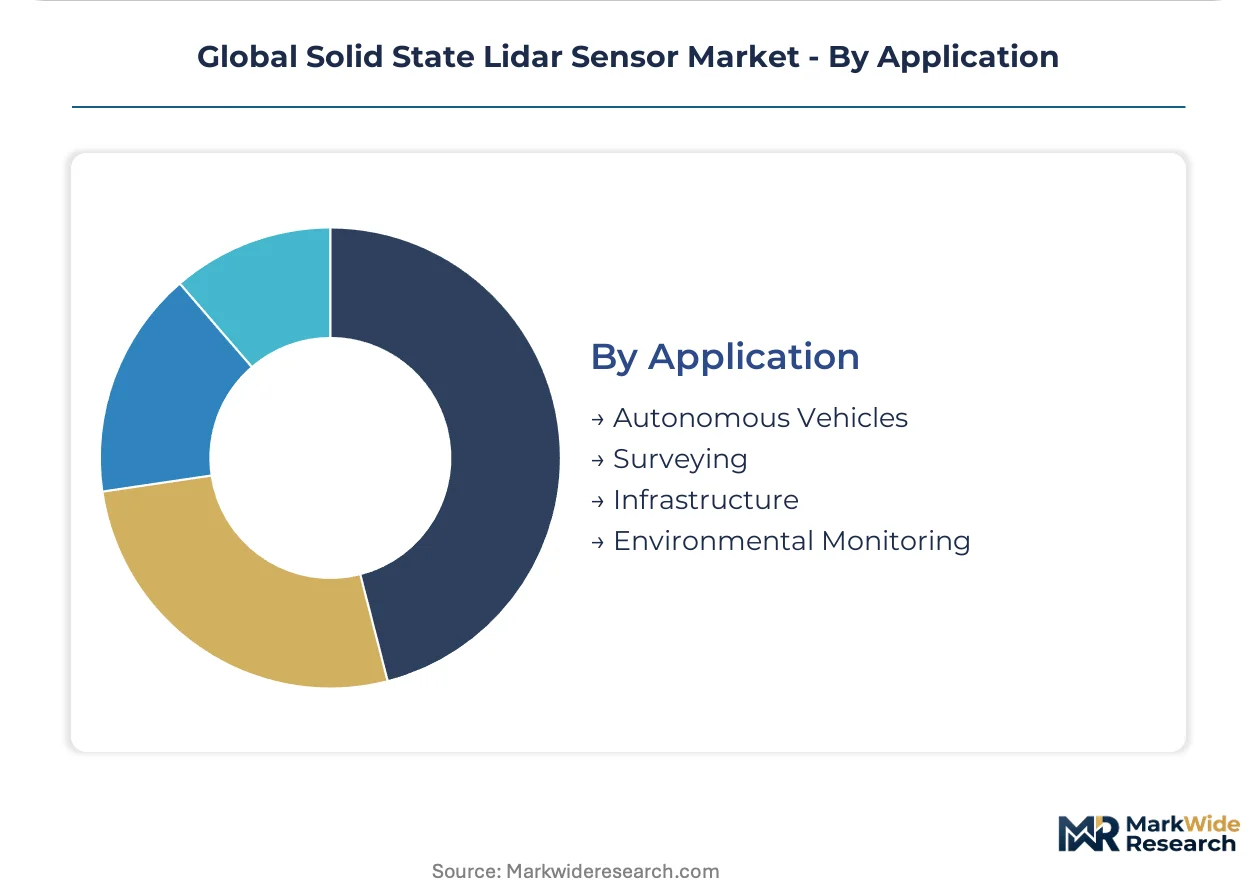
Application:
Customer type splits between fleet operators with direct procurement leverage and infrastructure agencies with extended tender cycles. Volume concentration among robotaxi deployables contrasts with fragmented environmental monitoring deployments.
- Autonomous Vehicles:NHTSA mandates and EU Vehicle General Safety Regulation specify object-detection performance for higher automation levels. Three vertically integrated operators in California and Arizona concentrate demand through direct OEM negotiations.
- Infrastructure:Smart city and tolling applications require weather-resistant enclosures with multi-year maintenance intervals. Government procurement cycles extend validation timelines beyond automotive norms.
- Surveying:Precision agriculture and construction progress monitoring favor integrated GNSS positioning.
- Environmental Monitoring:Air quality and emissions tracking applications integrate lidar with spectroscopic analysis for chemical identification.
Autonomous Vehicles anchors current revenue. Infrastructure represents the steepest expansion trajectory as smart city investment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Chinese OEM procurement contracts while German regulatory validation imposes cost premiums on European vendors. The United States commands premium fleet procurement rates through robotaxi deployment permits. Geographic asymmetries in certification timelines and foundry proximity reshape competitive positioning across manufacturing clusters.
United States
Waymo and Cruise fleet procurement drives volume concentration in California and Arizona markets. NHTSA mandates specify object-detection performance thresholds for higher automation levels. Silicon Valley photonics foundries and Detroit automotive engineering centers anchor domestic supply chain development.
China
NIO, Xpeng, and Li Auto integrate solid-state units into production sedan lineups under MIIT GB standards. The Ministry of Industry and Information Technology issues mandatory environmental perception benchmarks for intelligent connected vehicles. Yangtze River Delta manufacturing clusters host Hesai Technology and RoboSense production facilities serving domestic OEM demand.
Germany
Premium sedan programs from BMW and Mercedes-Benz source highway-speed perception systems requiring 250-meter detection ranges. KBA vehicle-type approval rules mandate redundant perception coverage and documented failure-mode analyses. Bavaria automotive engineering centers and Stuttgart supplier parks concentrate tier-one integration capabilities.
Japan
Toyota and Honda autonomous development programs prioritize MEMS mirror reliability records for mainstream vehicle integration. METI industrial policy supports domestic sensor component manufacturing through targeted R&D subsidies. Kanto region electronics clusters and Nagoya automotive corridors maintain precision manufacturing expertise.
South Korea
Hyundai Motor Group and Samsung automotive divisions pursue solid-state lidar integration for domestic electric vehicle platforms. MFDS-equivalent automotive safety standards align with international ISO 26262 functional safety frameworks. Seoul Capital Area semiconductor foundries supply photonic chip fabrication capacity for regional vendors.
Global Solid State Lidar Sensor Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the competitive spectrum. The vendor base splits between captive-fabrication specialists and fabless designers dependent on external foundry capacity. Three archetypes dominate: photonic chip foundry owners, tier-one automotive integrators, and pure-play beam-steering innovators. Competitive moves concentrate on strategic partnerships for ASIL-D certification alignment and geographic expansion into India's PLI scheme jurisdictions.
Within the captive-fabrication tier, Luminar Technologies exemplifies vertical control over InGaAs receiver production. Hesai Technology and Cepton occupy positions at the high-volume automotive contract end, representing divergent technical camps in beam-steering architecture selection. These three anchors illustrate how supply chain configuration determines pricing flexibility and design lock-in timelines across the competitive landscape.
| Leading Market Players |
|---|
| Ouster |
| Luminar Technologies |
| Innoviz Technologies |
| Hesai Technology |
| Quanergy Systems |
| Aeva Technologies |
| RoboSense |
| Cepton |
| LeddarTech |
| Others |
Value Chain & Pricing Dynamics
Photonic chip foundry scale economies concentrate receiver fabrication capacity in Taiwan and the United States, compressing unit economics for 1550nm avalanche photodiodes while inflating price floors for vendors locked into single-source arrangements. This concentration dynamic cascades through beam-steering architecture selection, where MEMS mirror vendors exploit established automotive qualification pathways to command premiums over optical phased array alternatives still wrestling with silicon photonics yield rates.
Pricing Analysis
Configured-to-order pricing for ASIL-D certified automotive units spreads 40-60% above standard industrial configurations lacking functional safety documentation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with highway-speed specifications attracting the widest premiums. Cost compression in mass-market automotive segments intensifies as Tesla's vision-only stack demonstrates perception viability without lidar, eroding pricing power for entry-tier units. Fleet procurement at Waymo and Cruise exhibits lowest price sensitivity, while warehouse robotics integrators absorb highest cost pressure.
Supply Chain Analysis
Taiwan and the United States anchor InGaAs receiver wafer fabrication, while South Korea and Japan supply MEMS mirror actuators and precision optical components. Raw material dependencies center on indium phosphide substrates, 1550nm laser diodes, and silicon-on-insulator wafers for photonic integration. Single-source vulnerability concentrates in Taiwan's foundry capacity for automotive-grade avalanche photodiodes, exposing vendors to allocation risk during demand surges. Distribution runs through direct OEM negotiations for autonomy-grade hardware, displacing traditional tier-one channels in California and Arizona robotaxi markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in solid-state lidar traces to Level 3+ automation mandates proliferating across German KBA rules, EU AI Act certification pathways, and China's MIIT GB standards, locking sensors into production vehicle specifications faster than cost curves can flatten.
For Market Incumbents: Fortify captive InGaAs fabrication capacity or secure multi-year wafer offtake agreements with Taiwan foundries to defend against fabless competitors exposed to allocation squeezes. Deepen ASIL-D certification alignment with vehicle domain controllers to extend design lock-in periods before hardware iteration windows compress under German vehicle-type approval timelines. For New Entrants and Emerging Players: After-sales calibration services for multi-sensor fusion stacks represent an underserviced layer where incumbent lidar vendors cede margin to systems integrators lacking specialized point-cloud synchronization expertise. India's PLI scheme for automotive components offers the most penetrable geographic entry point, with production-linked incentives attracting contract manufacturing investments serving domestic electric vehicle programs lacking established sensor supply relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors photonic chip foundry owners with backward integration into receiver fabrication, capturing margin expansion as 1550nm wavelength selection becomes standard for highway-speed perception. Watch for inflection in silicon photonics yield rates at commercial scale, signaling optical phased array viability against MEMS mirror reliability records.| Strategic Initiative | Industry Significance |
|---|---|
| Photonic Chip Foundry Capacity Expansion | Taiwan and U.S. fabrication investments secure InGaAs receiver supply for 1550nm automotive programs. |
| ASIL-D Functional Safety Certification | Alignment with ISO 26262 reduces integration validation cycles for tier-one automotive suppliers. |
| Direct OEM Fleet Procurement | Waymo and Cruise negotiations in California and Arizona bypass traditional distribution channels. |
| India PLI Scheme Manufacturing Entry | Production-linked incentives attract contract manufacturing for domestic electric vehicle sensor demand. |
| Frequency-Modulated Continuous Wave R&D | Cepton and select vendors differentiate through 250-meter highway-speed detection ranges. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with automotive platform engineers, tier-one supplier procurement leads, photonic foundry process engineers, and robotaxi fleet operations managers; and secondary validation through NHTSA autonomous vehicle filings, EU vehicle-type approval documentation, China MIIT GB standard releases, SEC 10-K disclosures from listed lidar vendors, and automotive production registration databases. Bottom-up unit shipment estimates by beam-steering architecture triangulated against top-down OEM procurement value assessments.
Across the analysis window, the forecasting framework modeled volume and value trajectories across product type, technology architecture, end-use application, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate blending weighted by procurement contract visibility. Industry-specific inputs incorporated vehicle autonomy level adoption curves, foundry capacity expansion schedules, and certification timeline differentials between German KBA, EU AI Act, and China MIIT pathways.
Underlying assumptions cover sustained capital expenditure in photonic chip fabrication, stable indium supply chains, and regulatory adoption of explicit range-resolution minimums rather than performance-based safety goals, with deviation risk concentrated in silicon photonics yield rate improvements and camera-radar fusion cost compression in mass-market segments. Recalibration cycles align with material shifts in vehicle-type approval timelines and foundry capacity allocation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Europe Touch Sensor Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Disposable Ph Sensors Market
Sensors and Controls
Middle East and Africa Lidar Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Clamp-On Ultrasonic Gas Flow Meter Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Automotive Cabin Air Quality Sensors Market