
 Data Center Wire and Cable Market | 2026-2036
Data Center Wire and Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Wire and Cable Market Insights
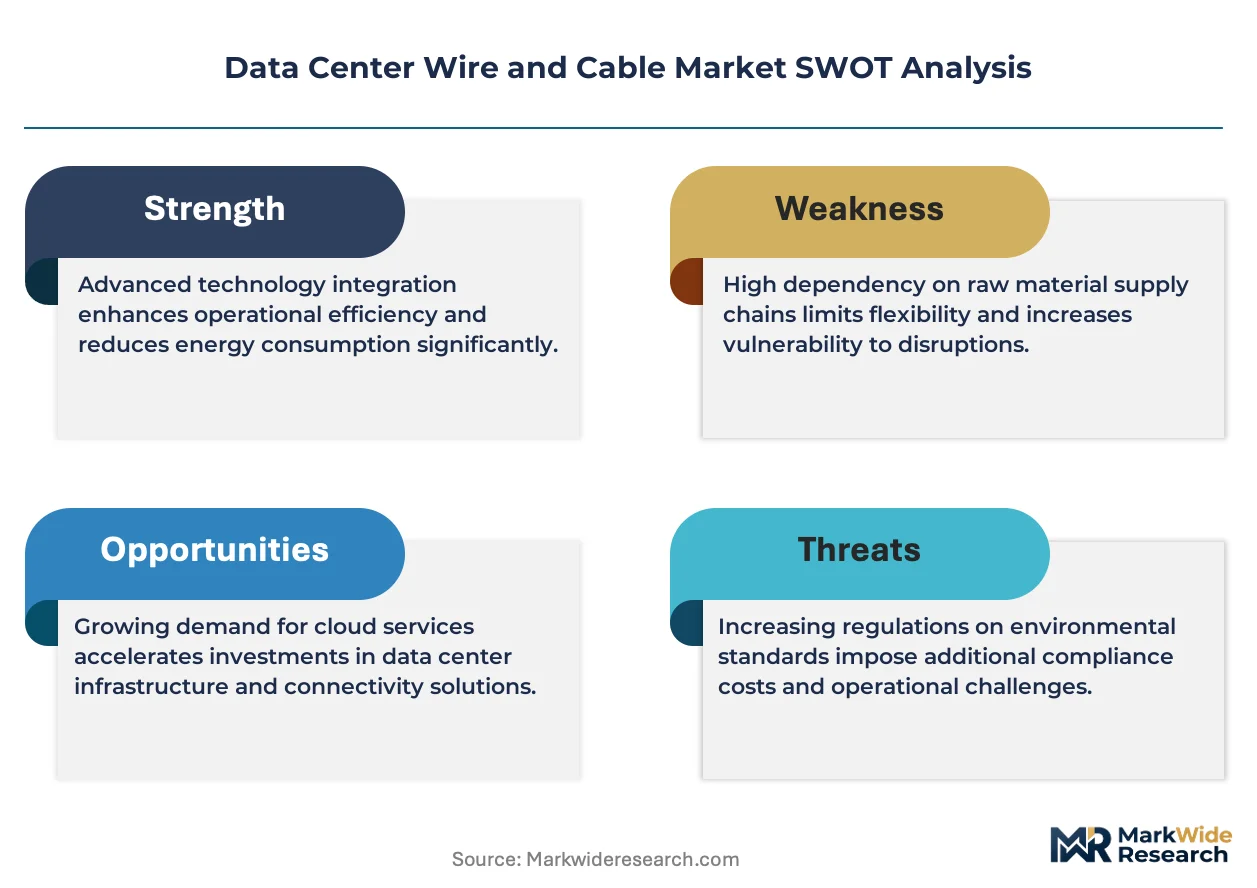
Halogen-free jacket compounds are expanding their share of new data center builds as operators target lower smoke density and reduced corrosive off-gassing under fire conditions. Prysmian Group leverages its integrated optical fiber and cable manufacturing footprint across Europe and North America to serve these specifications. CommScope Holding Company, Inc. sustains a broad copper and fiber portfolio that spans structured cabling through hyperscale interconnect. Belden Inc. specializes in precision signal transmission cables for high-density switching environments.
Data center wire and cable encompasses insulated conductors and optical fiber assemblies engineered for rated voltage, bandwidth, and flame-resistance performance within mission-critical digital infrastructure facilities. Copper conductors typically deploy oxygen-free copper with polyethylene or fluoropolymer dielectrics to minimize insertion loss across short-reach power and signal runs. Fiber optic cables lead product type demand as 400G and 800G optical transceivers displace direct attach copper in spine-leaf architectures. Power supply applications within the application dimension carry expanding copper gauge requirements as rack densities climb past 30 kilowatts per cabinet. Cloud service providers dominate end user procurement with consolidated purchasing programs that compress margin pools for second-tier suppliers.
NFPA 70 National Electrical Code and TIA-942-B standards govern cable flame ratings and telecommunications infrastructure pathways in US facilities, while EU Construction Products Regulation and CPR classification impose additional smoke and toxicity testing for European deployments. The FCC and FDA do not regulate data center cabling directly, though FCC Part 15 emissions compliance shapes shielding specifications for power and signal cables near active equipment. Stakeholders must monitor evolving ampacity derating requirements as liquid cooling adoption alters thermal profiles within cable trays and underfloor plenums.
Market Dynamics
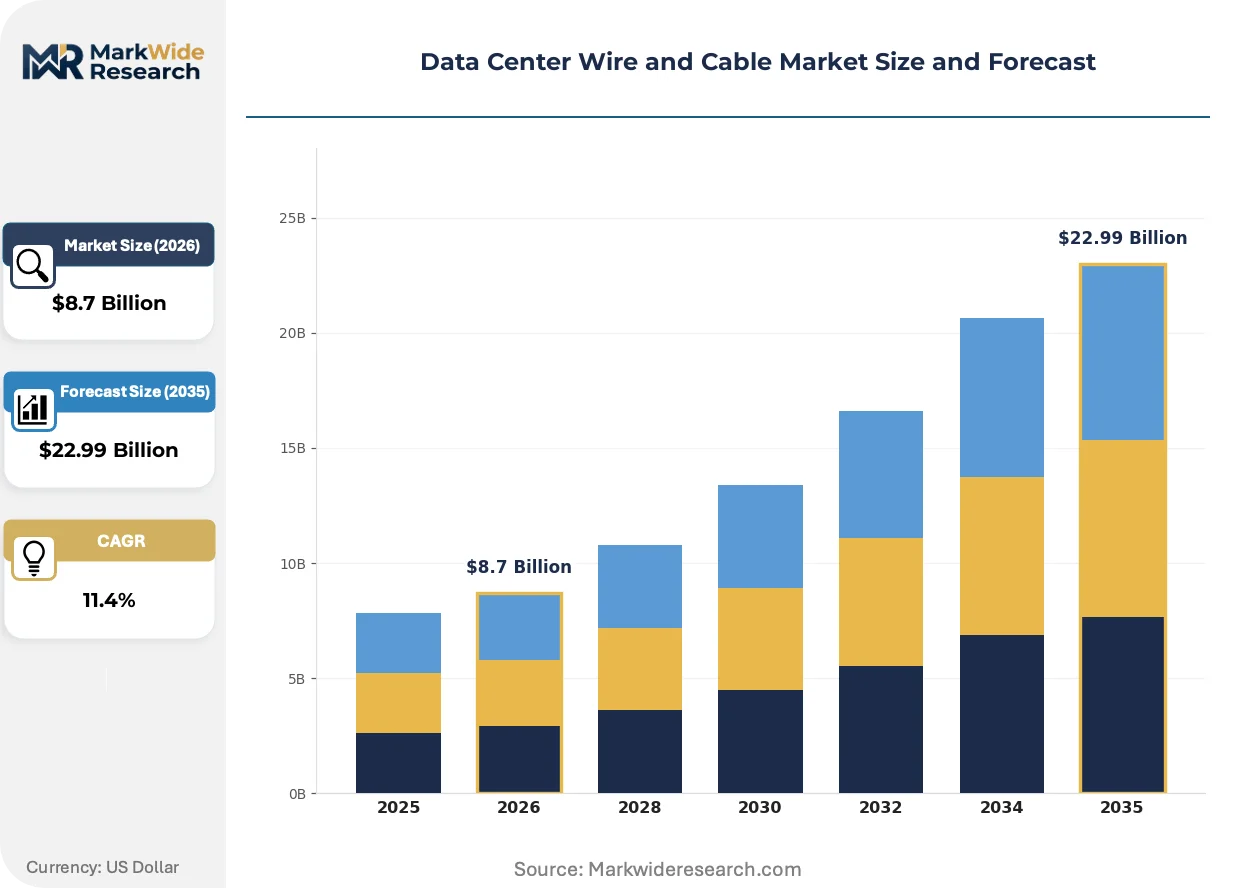
Hyperscale cloud operators are consolidating purchasing power while mandating halogen-free, low-smoke cable specifications under EU CSRD reporting rules and evolving NFPA 70 flame-rating requirements. This dual pressure is compressing supplier margins and forcing compound innovation.
Growth Catalysts
- EU Green Deal compliance mandates:Construction Products Regulation and CSRD disclosure rules are accelerating halogen-free jacket adoption across European data center builds. Operators face direct reporting pressure on embodied carbon and fire-safety materials.
- Spine-leaf architecture densification:400G and 800G optical transceiver deployment is automating fiber pull-through rates per rack. Cloud service providers are specifying higher fiber counts to reduce inter-rack latency.
- Liquid cooling thermal profiles:Direct-to-chip cooling systems are altering ampacity derating calculations in underfloor plenums. TIA-942-B pathway standards are being reinterpreted for wet environments.
Market Restraints
- Copper gauge cost volatility:Oxygen-free copper pricing swings directly compress margin on power distribution assemblies. Suppliers lack pass-through mechanisms with hyperscale procurement desks.
- Optical fiber supply concentration:Preform and draw-tower capacity clusters in China and Japan create geopolitical exposure for North American cable assemblers.
- Direct attach copper persistence:DAC remains cost-advantaged for sub-3-meter rack interconnects, delaying full fiber conversion in legacy facilities.
Strategic Opportunities
- India data center buildout:TRAI infrastructure guidelines and state-level data localization policies are driving greenfield campus development in Mumbai and Chennai. Halogen-free specifications remain underpenetrated relative to European norms.
- Edge compute micro-facilities:5G base station aggregation points and autonomous vehicle data lakes are creating sub-1-megawatt sites requiring specialized low-smoke, limited-combustible cable runs.
- CE marking automation:EU Construction Products Regulation digital certification workflows are reducing time-to-market for compliant cable families. CPR classification testing is streamlining through notified body harmonization.
Industry Challenges
- Compound formulation talent scarcity:Halogen-free, low-smoke jacket chemistries require polymer scientists with fluoropolymer and polyolefin crosslinking expertise. European and North American universities produce limited graduates in this specialty.
- NFPA 70-TIA-942-B harmonization delays:Divergent flame-rating nomenclature between electrical and telecommunications codes creates specification confusion for multi-tenant facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Wire and Cable Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Copper Cables, Fiber Optic Cables, Coaxial Cables, Patch Cords Application: Data Transfer, Networking, Power Supply, Signal Transmission End User: Telecommunication Companies, Cloud Service Providers, Enterprises, Colocation Facilities Installation Type: In-Rack, Underfloor, Overhead, Wall-Mounted |
| Companies Covered | CommScope Holding Company, Inc., Panduit Corporation, Prysmian Group, Southwire Company, LLC, TE Connectivity, Nexans, Corning Incorporated, Sumitomo Electric Industries, Ltd., Belden Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Wire and Cable Market Trends and Innovations
Automation of cable assembly and testing protocols is compressing delivery timelines while regulatory pressure on embodied carbon is reshaping material selection. Three forces are redefining competitive positioning.
Robotic fiber splicing and automated optical loss testing is automating quality assurance throughput for hyperscale orders. Cloud service providers are accepting pre-terminated, factory-tested assemblies to reduce field labor. This is compressing the viable supplier base to manufacturers with capital-intensive automation lines.
REACH substance restrictions and EU Green Deal carbon-border adjustments are tightening permissible additives in jacket compounds. Cable makers are reformulating with mineral fillers and non-halogenated flame retardants to maintain CPR Class B2ca ratings. European deployments are most affected, with procurement teams now requiring Environmental Product Declarations upstream.
Consolidated buying desks at cloud operators are unbundling installation services from cable supply contracts. Systems integrators are absorbing termination and testing scope that manufacturers previously bundled. This disintermediation is most visible in Northern Virginia and Singapore, where hyperscale campus density supports dedicated contractor ecosystems.
Data Center Wire and Cable Market Segmentation
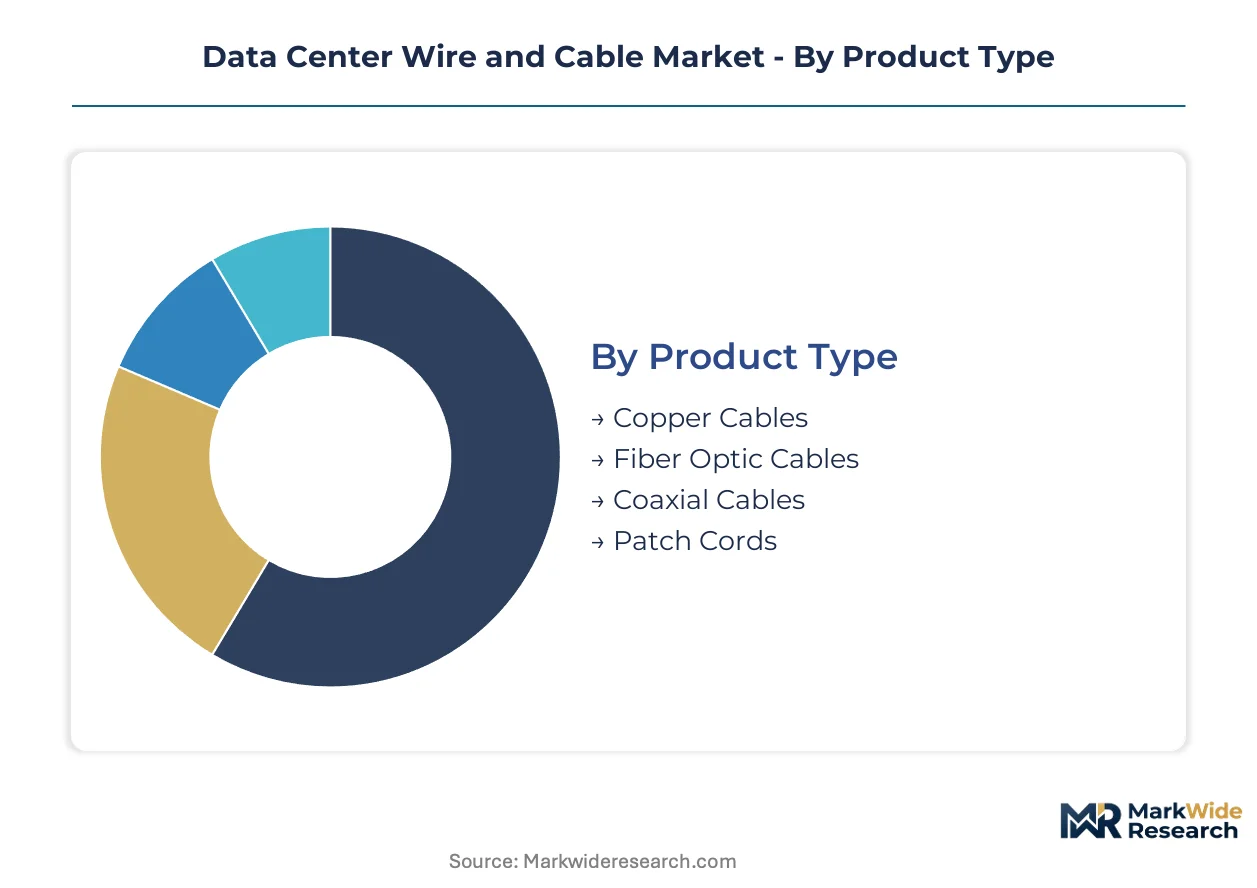
Data center wire and cable segmentation reflects divergent capital requirements across materials science, installation logistics, and customer procurement patterns. Each dimension carries distinct margin profiles and supplier qualification barriers that shape competitive positioning.
Product Type:
Capital intensity varies sharply across product categories, with fiber optic cable manufacturing demanding draw-tower and preform investments that copper extrusion lines do not require.
- Copper Cables:Oxygen-free copper conductors with polyethylene or fluoropolymer dielectrics serve short-reach power distribution and signal runs. Hyperscale campuses in Northern Virginia and Singapore specify heavy-gauge assemblies as rack densities exceed 30 kilowatts per cabinet.
- Fiber Optic Cables:Single-mode and multimode fiber assemblies with tight-buffered or loose-tube constructions carry 400G and 800G optical transceiver signals. Cloud service providers in Dublin are automating fiber pull-through rates to reduce spine-leaf latency.
- Coaxial Cables:Copper-clad aluminum center conductors with braided shielding address legacy RF and timing synchronization requirements.
- Patch Cords:Pre-terminated copper and fiber assemblies with factory-tested insertion loss specifications compress field labor timelines.
Fiber optic cables absorb the bulk of installed capacity; patch cords are expanding most quickly as pre-termination acceptance spreads.
Application:
Application segmentation tracks the physical layer functions that cables perform, with power supply carrying the most stringent ampacity and thermal derating calculations.
- Data Transfer:High-bandwidth fiber and copper links move storage traffic between compute nodes. Cloud service providers specify low-smoke zero-halogen jackets for EU CSRD compliance.
- Networking:Structured cabling systems with Category 8 copper and OS2 fiber support Ethernet protocols. Colocation facilities in Singapore prioritize CPR Class B2ca flame ratings.
- Power Supply:Heavy-gauge copper busways and feeder cables deliver 480V three-phase power to rack PDUs. Liquid cooling adoption is forcing TIA-942-B pathway reinterpretation for wet underfloor environments.
- Signal Transmission:Precision coaxial and twisted-pair cables carry timing, telemetry, and management traffic. Belden Inc. specializes in this specification tier for high-density switching fabrics.
Networking applications anchor current procurement volumes; power supply is climbing the fastest as rack densities reshape gauge requirements.
End User:
End user segmentation reveals concentrated purchasing power among cloud operators, with procurement desk consolidation compressing margin pools for second-tier suppliers.
- Cloud Service Providers:Hyperscale operators with consolidated buying desks mandate halogen-free specifications and factory-tested pre-termination. These buyers unbundle installation services from cable supply contracts.
- Telecommunication Companies:Carrier-neutral and wholesale operators specify carrier-grade fiber counts for metro and long-haul interconnection. TRAI infrastructure guidelines in India are accelerating greenfield procurement.
- Enterprises:Private data center operators with sub-10-megawatt facilities prioritize TIA-942-B compliance and NFPA 70 flame ratings over advanced low-smoke formulations.
- Colocation Facilities:Multi-tenant operators face specification confusion from divergent NFPA 70 and TIA-942-B nomenclature. Dublin and Northern Virginia campuses lead procurement scale.
Cloud service providers command the largest contract values; telecommunication companies are gaining share fastest as 5G edge aggregation expands.
Installation Type:
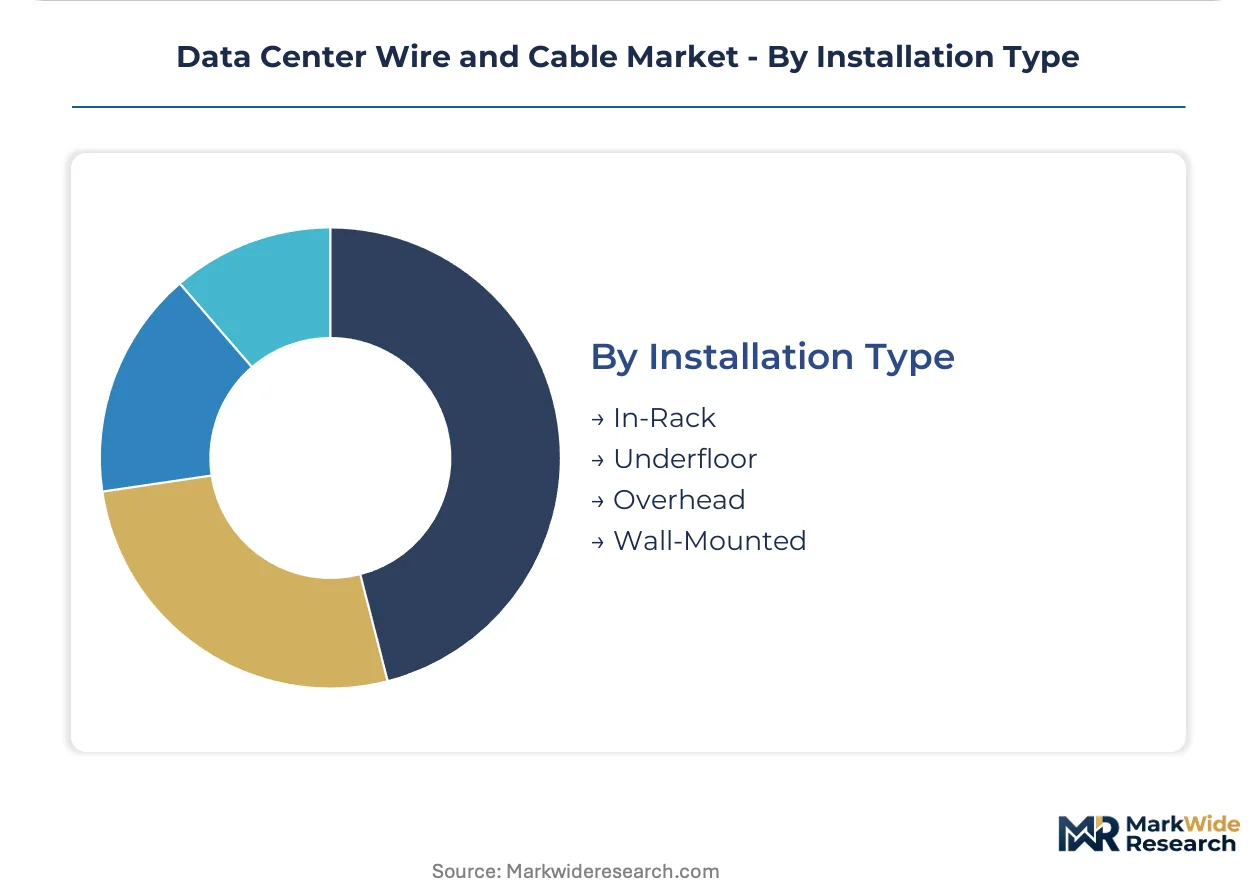
Installation segmentation determines pathway engineering and labor cost structures, with underfloor deployments requiring the most complex thermal and moisture management.
- In-Rack:Direct attach copper and fiber assemblies for sub-3-meter interconnects. DAC persistence in legacy facilities delays full fiber conversion.
- Underfloor:Plenum-rated cables in raised-floor environments face ampacity derating from liquid cooling thermal profiles. NFPA 70 flame-rating requirements govern US deployments.
- Overhead:Ladder rack and cable tray installations for spine-leaf fiber aggregation. Pre-terminated assemblies reduce aerial lift labor exposure.
- Wall-Mounted:Vertical riser and penetration sealing for edge compute micro-facilities. Low-smoke limited-combustible specifications apply.
Underfloor installations retain the largest installed base; overhead deployments are expanding most quickly as pre-termination acceptance grows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud procurement concentrates in three primary clusters: Northern Virginia, Dublin, and Singapore. These locations absorb disproportionate cable volumes as rack densities climb past 30 kilowatts per cabinet and fiber counts multiply for spine-leaf architectures.
United States
Cloud service providers in Northern Virginia and Dallas-Fort Worth drive heavy-gauge copper demand for 480V power distribution. NFPA 70 National Electrical Code governs flame ratings for underfloor plenum installations. The TIA-942-B standard shapes telecommunications pathway engineering across multi-tenant colocation campuses.
Ireland
Dublin's data center cluster faces CSRD disclosure pressure on embodied carbon and fire-safety materials. EU Construction Products Regulation mandates CPR Class B2ca ratings for cable jackets. Microsoft and Amazon Web Services automate fiber pull-through rates to reduce spine-leaf latency in their hyperscale facilities.
Singapore
Infocomm Media Development Authority licensing frameworks constrain data center power allocations, forcing efficiency gains through denser fiber architectures. Cloud operators specify halogen-free, low-smoke formulations for compliance with evolving fire-safety codes. Pre-terminated assemblies reduce field labor exposure in tropical humidity conditions.
Germany
Frankfurt's financial services and cloud hub drives carrier-grade fiber procurement for metro interconnection. REACH substance restrictions tighten permissible additives in jacket compounds. Mineral filler formulations from Prysmian Group serve CPR Class B2ca specifications without halogenated flame retardants.
India
TRAI infrastructure guidelines and state-level data localization policies accelerate greenfield campus development in Mumbai and Chennai. Halogen-free specifications remain underpenetrated relative to European norms. Telecommunication companies expand carrier-neutral fiber counts for 5G edge aggregation.
Data Center Wire and Cable Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated fiber-cable producers commanding premium positioning in hyperscale procurement. The supplier base compresses toward manufacturers with capital-intensive automation lines for pre-terminated assemblies. Three archetypes dominate: European cable conglomerates with integrated optical fiber manufacturing, North American connectivity specialists with broad copper-fiber portfolios, and Asian component fabricators with scale-driven cost structures. Competitive moves center on CE marking automation for EU market access and backward integration into halogen-free compound formulation.
Among integrated European producers, Prysmian Group exemplifies the fiber-cable conglomerate archetype with manufacturing footprints spanning multiple continents. CommScope Holding Company, Inc. and Belden Inc. represent North American specialists with structured cabling and precision signal transmission positioning respectively. These three anchors illustrate how geographic origin and product heritage shape qualification barriers for hyperscale procurement desks.
| Leading Market Players |
|---|
| CommScope Holding Company, Inc. |
| Panduit Corporation |
| Prysmian Group |
| Southwire Company, LLC |
| TE Connectivity |
| Nexans |
| Corning Incorporated |
| Sumitomo Electric Industries, Ltd. |
| Belden Inc. |
| Others |
Pricing and Supply Chain Analysis
Halogen-free certification tiers split the market into premium CPR Class B2ca-rated supply and commodity CMP/CMR alternatives, with this bifurcation locking pricing power to compound formulation capabilities while concentrating supply among European and North American manufacturers with in-house polymer science teams. Cloud procurement desks exploit this split through consolidated volume tenders that compress margins on standard-grade copper assemblies.
Pricing Analysis
Volume procurement concentrates among hyperscale buyers while margin capture accrues to fiber preform-integrated suppliers. Three-tier pricing structure across premium, standard, and economy levels tracks CPR flame rating, fiber count density, and factory pre-termination status. Cost compression in copper power distribution assemblies intensifies because oxygen-free copper lacks pass-through mechanisms with cloud buying desks. Colocation facilities exhibit highest price sensitivity; cloud operators with dedicated automation lines show lowest sensitivity to per-meter premiums.
Supply Chain Analysis
CPR Class B2ca and NFPA 70 plenum certifications gate supplier qualification, restricting viable manufacturing to facilities with notified body relationships and UL-listed compound libraries. Preform and draw-tower capacity clusters in China, Japan, and the United States anchor optical fiber supply. Jacket compounds draw from mineral filler suppliers, fluoropolymer resin producers, and non-halogenated flame retardant specialists. Single-source vulnerability concentrates in Chinese preform feedstock. Distribution runs through authorized distributor networks and direct hyperscale procurement desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Preform draw-tower capacity constraints prop pricing power for integrated fiber-cable manufacturers, as hyperscale fiber count requirements outpace qualified supplier expansion.
For Market Incumbents: Deploy backward integration into halogen-free compound formulation to defend margin position against commodity copper assemblers. Incumbents should consolidate CE marking automation workflows to reduce time-to-market for CPR-compliant families, while adding preform capacity in North America to mitigate geopolitical exposure from Chinese feedstock concentration. For New Entrants and Emerging Players: The premium-economy price gap in Indian data center builds creates entry opportunity for CPR-classified cable families against locally certified alternatives. New entrants should target Mumbai and Chennai greenfield campuses with halogen-free specifications underpenetrated relative to European norms, leveraging TRAI infrastructure guideline compliance as qualification shortcut. For Investors and Strategic Acquirers: Re-rating potential sits with integrated fiber-cable producers given CSRD disclosure pressure and carbon-border adjustment mechanics. Long-term viability favors manufacturers with captive preform supply and automated pre-termination lines. Watch hyperscale capital expenditure inflection signals for demand revision triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Halogen-Free Compounds | Captures margin from specialty polymer suppliers serving CPR Class B2ca formulations. |
| Preform Capacity Expansion | Reduces geopolitical exposure to Chinese and Japanese draw-tower concentration. |
| CE Marking Automation | Compresses notified body certification timelines for EU Green Deal compliance. |
| Pre-Termination Assembly Lines | Aligns with cloud procurement preference for factory-tested fiber assemblies. |
| India Greenfield Partnership | Positions for TRAI-mandated infrastructure buildout in Mumbai and Chennai clusters. |
Research Methodology
SEC 10-K filings, hyperscaler capital expenditure disclosures, and EU Construction Products Regulation certification databases formed the secondary backbone. Primary interviews with data center procurement directors, cable manufacturer product managers, and polymer compound specialists combined with secondary validation. Bottom-up and top-down triangulation cross-checked fiber count deployment rates against rack density projections.
Bottom-up modeling aggregated product-type volumes across copper, fiber, and patch cord segments, while top-down analysis calibrated aggregate market scale against hyperscale facility commissioning announcements. Segmentation dimensions included product type, application function, end-user procurement archetype, and installation environment across the analysis window. CAGRs derived from facility deployment timelines and fiber-per-rack densification curves.
Underlying measurement precision varies by segment; fiber optic cables carry tighter precision than copper power distribution due to standardized transceiver roadmaps. Forecasts reflect assumptions on liquid cooling adoption rates and CSRD reporting scope expansion. A model refresh is warranted upon material change in hyperscale capital expenditure commitment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Copper Stranded Wire Market
Cables
High Voltage Cables Market
Cables
Instrumentation Cables Market
Cables
Cable Management System Market
Cables
Military Fiber Optic Cables Market
Cables
North America Patch Cable Market
Cables
Mexico Wires and Cables Market
Cables
Usb Data Cable Market
Cables
South Africa Wire and Cable Market
Cables
Europe Cable Accessories Market
Cables
Underground Power Cable Partial Discharge and Fault Location Test Equipment Market
Cables
Cable Racks Market
Cables
Power and Signal Cables Market
Cables
Fiber Optic Cable Materials Market
Cables
UK Cables Market
Cables
Premise Cable Market