
 Surface Mount PLCC Leds Market | 2026-2036
Surface Mount PLCC Leds Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Mount PLCC Leds Market Analysis
EU Ecodesign requirements for energy-related products is hardening efficiency benchmarks for LED components sold across member states. Nichia Corporation leverages its phosphor technology leadership to sustain premium positioning in high-reliability automotive applications. Osram Opto Semiconductors anchors European supply chains through its Regensburg fabrication complex, while Broadcom Inc competes in datacom and consumer segments with specialized infrared PLCC offerings.
Surface Mount PLCC LEDs are compact, rectangular chip packages with J-lead gull-wing terminals designed for automated pick-and-place assembly on printed circuit boards, typically measuring 3.2 mm by 2.8 mm with thermal pads for enhanced heat dissipation; they serve as standardized light sources for illumination, indication, and optical signaling across industrial and commercial systems. RGB variants command widening adoption in automotive ambient lighting and display backlighting where color-mixing precision drives value. Standard-power packages occupy mature volume positions in indoor retrofit luminaires, while ultra-high brightness grades capture margin pools in outdoor signage and projector applications.
REACH substance restrictions and RoHS hazardous substance limits constrain phosphor chemistry and solder alloy selections for PLCC LED packages entering European markets. China's MIIT enforces GB standards for luminous efficacy and color rendering that shape product qualification for domestic and export-bound manufacturers. Japan's METI promotes JIS-compliant high-efficiency lighting through Top Runner programs that elevate baseline performance thresholds. Stakeholders must monitor evolving efficiency mandates and thermal management specifications as product differentiation shifts from lumen output toward spectral precision and module integration depth.
Market Dynamics
Automotive OEMs are consolidating PLCC LED specifications around thermal pad architectures and spectral precision requirements, compressing supplier qualification timelines while elevating entry barriers for non-integrated package manufacturers.
Growth Catalysts
- China's GB Standards:MIIT-enforced luminous efficacy mandates for solid-state lighting are forcing domestic and export-bound manufacturers to upgrade package thermal management and phosphor chemistry, accelerating replacement cycles in commercial retrofit segments.
- Automotive Interior Modules:RGB PLCC variants are capturing ambient lighting sockets in passenger vehicle cabins as Tier-1 suppliers consolidate around single-package color-mixing solutions for dashboard and door panel illumination.
- Shenzhen-Seoul Manufacturing Clusters:Concentrated backend packaging capacity across Guangdong Province and Gyeonggi-do enables rapid prototyping and volume scaling for mid-power illumination products serving pan-Asian electronics supply chains.
Market Restraints
- Phosphor Cost Volatility:Rare-earth element pricing for cerium-doped yttrium aluminum garnet phosphors creates margin compression for standard-power white LED packages, particularly affecting high-volume indoor retrofit suppliers.
- European Regulatory Friction:ECHA REACH substance restrictions and RoHS hazardous substance limits constrain solder alloy selections and phosphor formulations, extending product qualification timelines for packages entering EU member state markets.
- Chip-on-Board Substitution:Direct-attach LED arrays without leadframe packages are displacing PLCC formats in high-lumen outdoor signage applications where thermal density and lumen-per-dollar metrics dominate procurement criteria.
Strategic Opportunities
- Projector and Cinema Applications:Ultra-high brightness PLCC grades with enhanced thermal pads are penetrating digital cinema projection and high-end home theater segments where color gamut precision and lumen maintenance drive premium positioning.
- Japan's Top Runner Program:METI-promoted JIS-compliant high-efficiency lighting standards create certified product preference channels for manufacturers achieving elevated efficacy thresholds in commercial and industrial installations.
- Infrared Datacom Convergence:Specialized infrared PLCC offerings are integrating with optical transceiver modules for data center interconnects, bridging illumination and communication functions within single package footprints.
Industry Challenges
- Phosphor Deposition Expertise Gap:Precision dispensing and conformal coating of quantum dot and ceramic phosphor layers requires specialized process engineering talent concentrated among legacy Japanese and European compound semiconductor fabricators.
- Multi-Jurisdiction Certification Burden:Simultaneous compliance with China's GB standards, EU REACH/RoHS frameworks, and Japan's JIS specifications fragments product development resources and extends time-to-revenue for new package introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Mount PLCC Leds Market |
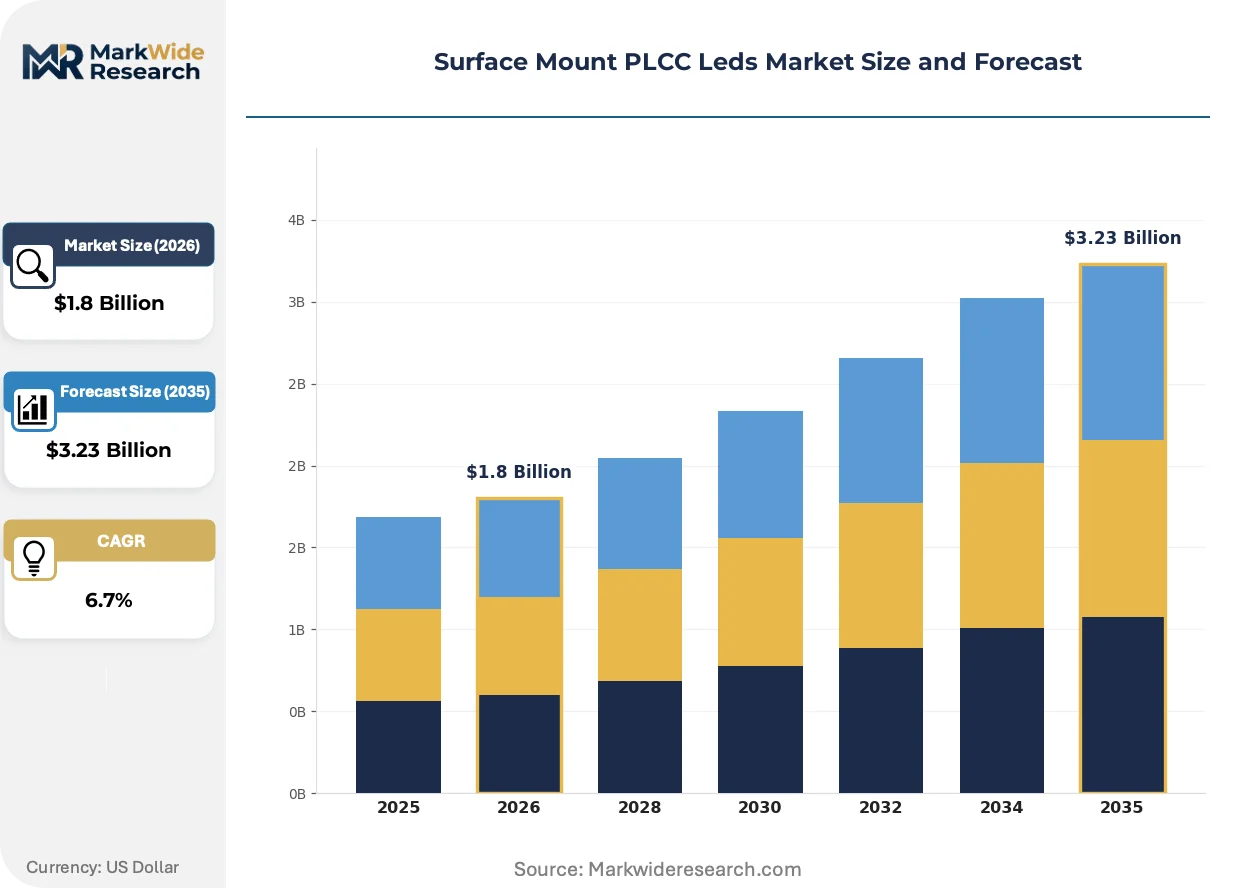
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Power, Standard, Ultra-High Brightness, RGB Application: Automotive Lighting, Indoor Lighting, Outdoor Signage, Consumer Electronics Technology: Chip-on-Board, Surface Mount Technology, Through-Hole Technology, Laser Diode End User: Manufacturers, Distributors, Retailers, Aftermarket Providers |
| Companies Covered | Toshiba Corporation, Broadcom Inc, Nichia Corporation, Osram Opto Semiconductors, Lumileds, Luxpia Co Ltd, KDG Electronics Co Ltd, Schiefer Lighting BV, Edison Opto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Mount PLCC Leds Market Emerging Trajectories
Spectral engineering and thermal architecture advances are redefining competitive differentiation in surface mount LED packaging, shifting value capture from raw lumen output toward precision color rendering and module integration depth.
Multi-channel RGB PLCC packages with independent anode control are modularizing automotive ambient lighting system design. Tier-1 cabin electronics suppliers are adopting these devices to reduce wiring harness complexity and enable software-defined color temperature adjustment. The technology is compressing traditional discrete LED cluster configurations into single-package solutions that simplify thermal management and optical mixing chamber geometry.
EU Ecodesign requirements for energy-related products are hardening efficiency benchmarks for LED components sold across member states. The regulatory pressure is accelerating phase-out of legacy package formats with inferior thermal resistance characteristics. High-reliability automotive and industrial illumination segments are responding with accelerated redesign cycles that prioritize packages with integrated thermal pads and ceramic substrates.
Automotive OEMs are consolidating supplier bases around vertically integrated package manufacturers capable of delivering spectral binning precision and traceable thermal performance data. Direct sourcing relationships are replacing traditional distribution channels for high-volume exterior lighting modules. This concentration is most visible in German and Japanese premium vehicle programs where headlamp and taillight subsystem suppliers face consolidated qualification requirements from BMW, Mercedes-Benz, and Toyota Motor Corporation procurement organizations.
Surface Mount PLCC Leds Market Segmentation
PLCC LED procurement decisions pivot on thermal performance thresholds and spectral precision requirements rather than lumen output alone. Package architecture selection directly determines qualification timelines for automotive and industrial applications where reliability data drives supplier consolidation.
Product Type:
Buyers segment primarily by thermal dissipation capacity and luminous intensity requirements, with cost-per-lumen secondary to reliability metrics in regulated end-uses.
- High Power:Ceramic substrate packages with copper thermal pads handle currents exceeding 350mA for automotive headlamp modules and industrial floodlighting. German and Japanese OEMs concentrate procurement here, driven by METI Top Runner efficacy mandates and EU Ecodesign efficiency benchmarks that disqualify lower-grade alternatives.
- RGB:Multi-die packages with independent anode control enable software-defined color mixing for vehicle cabin ambient lighting. Tier-1 automotive electronics suppliers in Gyeonggi-do and Shenzhen are consolidating around these devices to reduce wiring harness complexity and optical chamber size.
- Standard:Mid-power packages dominate commercial retrofit luminaire volumes where GB standards compliance suffices.
- Ultra-High Brightness:Enhanced thermal pad architectures serve digital cinema projection and high-end outdoor signage where color gamut precision commands premium positioning.
Volume sits with Standard packages; growth tilts toward RGB variants.
Application:
End-use differentiation tracks environmental exposure severity and regulatory jurisdiction density, with automotive and outdoor segments imposing the steepest qualification barriers.
- Automotive Lighting:Exterior modules demand AEC-Q101 reliability certification and spectral binning traceability for headlamp and taillight subsystems. BMW, Mercedes-Benz, and Toyota procurement organizations have consolidated supplier bases around vertically integrated manufacturers capable of delivering thermal performance data.
- Indoor Lighting:Commercial retrofit installations in China respond to MIIT-enforced GB efficacy standards that accelerate replacement cycles. Standard-power PLCC formats retain dominance here despite Chip-on-Board encroachment in high-lumen industrial bays.
- Outdoor Signage:Direct-attach LED arrays displace PLCC formats where thermal density and lumen-per-dollar metrics dominate procurement.
- Consumer Electronics:Indicator and backlighting applications favor compact 3.2mm by 2.8mm packages with simplified thermal management.
Automotive Lighting captures the steepest expansion trajectory; Indoor Lighting retains the largest installed base.
Technology:
Assembly method selection determines capital equipment requirements and supply chain geography, with surface mount dominance reflecting pan-Asian electronics manufacturing concentration.
- Surface Mount Technology:Automated pick-and-place compatibility with J-lead gull-wing terminals enables high-volume production across Shenzhen and Seoul packaging clusters. This format anchors consumer electronics and automotive interior module supply chains where reel-to-reel handling reduces assembly cost.
- Chip-on-Board:Direct die attachment without leadframe packages achieves superior thermal resistance for high-lumen outdoor and projector applications, displacing PLCC formats where lumen density outweighs assembly automation benefits.
- Through-Hole Technology:Legacy formats persist in industrial equipment repair channels requiring manual soldering compatibility.
- Laser Diode:Specialized infrared PLCC offerings integrate with optical transceiver modules for datacenter interconnects, bridging illumination and communication functions.
Surface Mount Technology commands current volume leadership; Chip-on-Board gains share fastest in thermally constrained applications.
End User:
Channel structure reflects certification burden distribution, with direct OEM relationships replacing traditional distribution for high-reliability segments.
- Manufacturers:Tier-1 lighting subsystem suppliers and automotive electronics integrators source directly from compound semiconductor fabricators to secure traceable thermal performance data and spectral binning precision. This channel concentrates procurement power among German, Japanese, and Korean vehicle programs.
- Distributors:Broadline electronics distributors serve mid-volume commercial retrofit and industrial maintenance segments where GB standards compliance suffices and qualification timelines compress.
- Retailers:Consumer-facing channels move standard-power packages for DIY replacement and small-scale installation.
- Aftermarket Providers:Vehicle repair and upgrade specialists access PLCC LEDs through specialized automotive lighting distributors with AEC-Q documentation.
Manufacturers direct the highest value transactions; Distributors handle the broadest SKU breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen anchors PLCC LED packaging capacity through dense backend assembly corridors serving automotive and consumer electronics supply chains. Guangdong Province clusters reel-to-reel surface mount operations alongside phosphor deposition specialists. Seoul-Gyeonggi-do manufacturing belts in South Korea concentrate RGB package innovation for vehicle cabin lighting modules.
China
MIIT-enforced GB standards for luminous efficacy accelerate replacement cycles in commercial retrofit installations. Domestic manufacturers upgrade thermal management architectures to meet tightening solid-state lighting mandates. Shenzhen packaging corridors scale mid-power PLCC volumes for pan-Asian electronics distribution.
South Korea
Tier-1 automotive electronics suppliers in Gyeonggi-do consolidate RGB PLCC procurement for dashboard and door panel ambient lighting. The national industrial policy supports high-efficiency lighting component exports through technology certification programs. Seoul capital area fabrication complexes specialize in multi-die color-mixing packages.
Japan
METI Top Runner programs elevate baseline efficacy thresholds for commercial and industrial LED installations. JIS-compliant manufacturers capture certified product preference channels through documented reliability performance. Nagoya and Osaka industrial zones concentrate phosphor chemistry expertise for high-reliability automotive applications.
Germany
ECHA REACH substance restrictions and RoHS hazardous substance limits constrain solder alloy selections for PLCC packages entering EU markets. Regensburg fabrication complexes anchor European supply chains for automotive exterior lighting modules. BMW and Mercedes-Benz procurement organizations consolidate supplier bases around vertically integrated compound semiconductor fabricators.
United States
NHTSA vehicle lighting safety standards shape headlamp and taillight subsystem specifications for domestic automotive programs. EPA energy efficiency guidelines influence commercial luminaire procurement in federal and state installations. Michigan and Ohio automotive corridors source traceable thermal performance data for exterior LED modules.
Surface Mount PLCC Leds Market Vendor Landscape
Premium-margin players sit above commodity-margin players across thermal architecture sophistication and spectral binning precision. Nichia Corporation and Osram Opto Semiconductors occupy the premium tier through phosphor technology leadership and automotive qualification depth. The vendor base stratifies into three archetypes: vertically integrated compound semiconductor fabricators, specialized packaging houses, and broadline optoelectronics suppliers. Competitive moves concentrate on backward integration into phosphor materials and strategic partnerships with Tier-1 automotive electronics integrators.
Among Japanese fabricators, Nichia Corporation exemplifies premium-tier positioning through ceramic substrate expertise. German-based Osram Opto Semiconductors anchors European supply chain security. Broadcom Inc represents the diversified optoelectronics archetype with specialized infrared offerings bridging illumination and datacom functions. These three entities occupy distinct competitive vectors without direct segment overlap.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Broadcom Inc |
| Nichia Corporation |
| Osram Opto Semiconductors |
| Lumileds |
| Luxpia Co Ltd |
| KDG Electronics Co Ltd |
| Schiefer Lighting BV |
| Edison Opto |
| Others |
Supply Flow & Price Mechanics
Automotive-grade thermal pad certification separates premium PLCC LED pricing from commodity indoor retrofit tiers, with AEC-Q101 qualification commanding three-tier pricing structure across premium, standard, and economy levels while concentrating procurement power among vertically integrated compound semiconductor fabricators in Germany and Japan.
Pricing Analysis
Value-based pricing anchored to spectral binning precision and lumen maintenance guarantees dominates automotive and projector segments, while standard-power packages trade on per-unit transactional terms. Price differentiation stems from thermal architecture sophistication and phosphor chemistry grade, with rare-earth element cost volatility compressing margins in high-volume white LED tiers. Pricing pressure intensifies in indoor retrofit channels as China's GB standards accelerate replacement cycles and domestic manufacturers scale mid-power volumes. Tier-1 automotive electronics buyers exhibit lowest price sensitivity, prioritizing traceable reliability data over per-unit cost.
Supply Chain Analysis
Certification gating through AEC-Q101 and JIS standards fragments supplier bases and extends qualification timelines for packages entering automotive channels. Manufacturing concentrates in China, South Korea, and Japan, with Shenzhen and Seoul-Gyeonggi-do packaging corridors feeding pan-Asian electronics distribution. Raw material dependencies include rare-earth phosphors, ceramic substrates, and copper thermal pad alloys. Single-source vulnerability in cerium-doped yttrium aluminum garnet phosphor supply creates exposure to commodity price swings. Distribution runs through direct OEM relationships for high-reliability segments and broadline electronics distributors for commercial retrofit volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PLCC LED market is becoming a vertical-integration race as manufacturers pursue captive phosphor chemistry capabilities to defend margin pools against rare-earth cost volatility and consolidate supplier qualification advantages.
For Market Incumbents: Cement spectral binning precision leadership through backward integration into phosphor materials and ceramic substrate fabrication. Defend against Chip-on-Board substitution in high-lumen outdoor applications by accelerating thermal pad architecture roadmaps. Prioritize AEC-Q101 certification depth to maintain procurement access to BMW, Mercedes-Benz, and Toyota exterior lighting programs.
For New Entrants and Emerging Players: Capture infrared PLCC white space in datacenter optical transceiver modules where illumination-communication convergence creates new socket opportunities. Target China's commercial retrofit segment under MIIT GB standards enforcement, where domestic qualification requirements favor local packaging houses with rapid thermal management upgrade capabilities. Pursue licensing partnerships with established phosphor deposition specialists to compress process engineering learning curves.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated compound semiconductor fabricators given automotive OEM supplier consolidation and direct sourcing relationship expansion. Long-term viability favors entities with demonstrated JIS, GB, and REACH/RoHS multi-jurisdiction certification infrastructure. Watch for inflection signals in rare-earth phosphor pricing volatility and METI Top Runner efficacy threshold adjustments.
| Strategic Initiative | Industry Significance |
|---|---|
| Phosphor Chemistry Backward Integration | Captive rare-earth processing insulates margins from cerium-doped yttrium aluminum garnet price swings. |
| AEC-Q101 Certification Acceleration | Automotive exterior lighting qualification opens direct sourcing channels with German and Japanese OEM procurement. |
| Multi-Jurisdiction Compliance Infrastructure | Simultaneous GB, REACH, and JIS capability compresses time-to-revenue for new package introductions. |
| RGB Multi-Die Package Innovation | Independent anode control architectures capture vehicle cabin ambient lighting socket consolidation. |
| Infrared Datacom Product Line Extension | Optical transceiver module integration bridges illumination and communication within single package footprints. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with automotive electronics procurement managers, phosphor chemistry R&D directors, Tier-1 lighting subsystem engineers, and compound semiconductor fabrication executives. Secondary sources included MIIT GB standard documentation, ECHA REACH substance restriction updates, METI Top Runner program specifications, and pan-Asian electronics trade flow databases. Bottom-up volume modeling triangulated against top-down market sizing across the projection horizon.
Segmentation-level granularity applied to thermal power class, application end-use, assembly technology, and geographic regulatory cluster throughout the modeling period. CAGRs derived from shipment volume trajectories and average selling price evolution by tier. Forecast inputs incorporated phosphor material cost indices, automotive LED content per vehicle trends, and solid-state lighting replacement cycle dynamics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare-earth element supply disruptions, automotive platform electrification timing, and Chip-on-Board thermal performance advances. A model refresh is warranted upon material change in China's GB efficacy mandate enforcement or METI Top Runner threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
India LED Lighting Market
LED
North America Commercial LED Lighting Market
LED
LED Power Supplies Market
LED
Global LED Phosphor Market
LED
Asia Pacific Indoor LED Lighting Market
LED
LED Chip Market
LED
Arrow LED Displays Market
LED
Africa LED and OLED Displays and Lighting Products Market
LED
China LED Market
LED
UV-C LED Market
LED
LED Panel Market
LED
LED Encapsulation Market
LED
Japan LED Market
LED
Thailand LED Market
LED
Global Outdoor LED Lighting Market
LED
Global Chip on Board (COB) Light Emitting Diode Market