
 Cable Fault Locator Market | 2026-2036
Cable Fault Locator Market Size, Share, and Industry Trends Forecast 2026-2036
Cable Fault Locator Market Analysis
Project finance for municipal grid upgrades is fragmenting the competitive landscape for cable fault locator procurement. Hubbell Incorporated leverages its entrenched utility relationships to sustain equipment placement across North American power networks. SebaKMT anchors European market presence through specialized high-voltage cable diagnostics. Megger competes on test equipment breadth, extending its portfolio from insulation resistance to time-domain reflectometry systems.
A cable fault locator detects discontinuities, impedance mismatches, and insulation degradation in electrical and fiber-optic cables through pulse-echo or bridge measurement techniques, typically resolving fault distances within one percent of cable length. The device serves critical infrastructure maintenance by minimizing outage duration and preventing catastrophic cable failures. OTDR technology dominates telecommunications applications where single-mode fiber precision requirements exceed analog methods. Digital architectures represent the fastest-growing technology segment as embedded processing enables automated waveform interpretation. Utility providers constitute the deepest end-user margin pool due to regulatory-mandated reliability standards and capital-intensive network footprints.
FCC equipment authorization rules shape electromagnetic compatibility requirements for U.S.-market cable fault locators, while IEEE 400 series standards define acceptable diagnostic test voltages for shielded power cables. IEC 60502 and related CENELEC harmonized standards govern European product compliance, directly influencing manufacturer design cycles and certification costs. Stakeholders must monitor evolving grid code harmonization between national regulators and international standards bodies to anticipate procurement specification shifts.
Market Dynamics
Underground cable network aging across North American utilities is accelerating fault detection equipment replacement cycles, while embedded digital processing architectures are compressing the performance gap between handheld field units and laboratory-grade diagnostic systems.
Growth Catalysts
- IEEE 400 Series Standards:Stricter diagnostic test voltage requirements for shielded power cables are mandating equipment upgrades across US utility fleets, forcing systematic replacement of analog bridge methods.
- Grid Modernization Capital Flows:Municipal bond issuances for underground infrastructure resilience are expanding procurement budgets for time-domain reflectometry systems in high-density urban networks.
- Fiber-Optic Backhaul Expansion:5G small cell densification is driving OTDR deployment into telecommunications contractor tool inventories, displacing optical power meter-based fault estimation.
Market Restraints
- Semiconductor Component Concentration:High-speed analog-to-digital converters and precision pulse generators face single-source dependency on East Asian foundry capacity, creating 16-24 week lead time volatility.
- Specialized Technician Scarcity:Waveform interpretation expertise for complex impedance signatures requires 18-36 month apprenticeship pipelines that utility workforce development programs cannot fill at replacement rates.
- Bridge Method Obsolescence Resistance:Mature Murray and Varley loop techniques retain installed base loyalty in cost-constrained rural cooperatives, delaying digital architecture penetration in price-sensitive segments.
Strategic Opportunities
- India Smart Grid Mission:Central Electricity Authority mandates for urban distribution automation are creating first-mover advantage for portable fault locator vendors establishing local calibration facilities.
- AI-Assisted Waveform Classification:Machine learning inference at the edge is converging with time-domain reflectometry hardware to enable technician-independent preliminary fault typing in low-experience markets.
- Rental Channel Development:Equipment-as-a-service models through specialized electrical contractor supply houses are penetrating mid-tier municipal maintenance departments with cyclical capital constraints.
Industry Challenges
- Multi-Standard Certification Burden:Simultaneous FCC Part 15 electromagnetic compliance, IEEE 400.2 insulation testing accreditation, and IEC 60502-2 harmonized approval extends product launch timelines by 8-14 months.
- Legacy System Integration Complexity:Digital fault locators must interface with 1980s-era utility asset management databases through proprietary serial protocols, requiring costly middleware development per customer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cable Fault Locator Market |
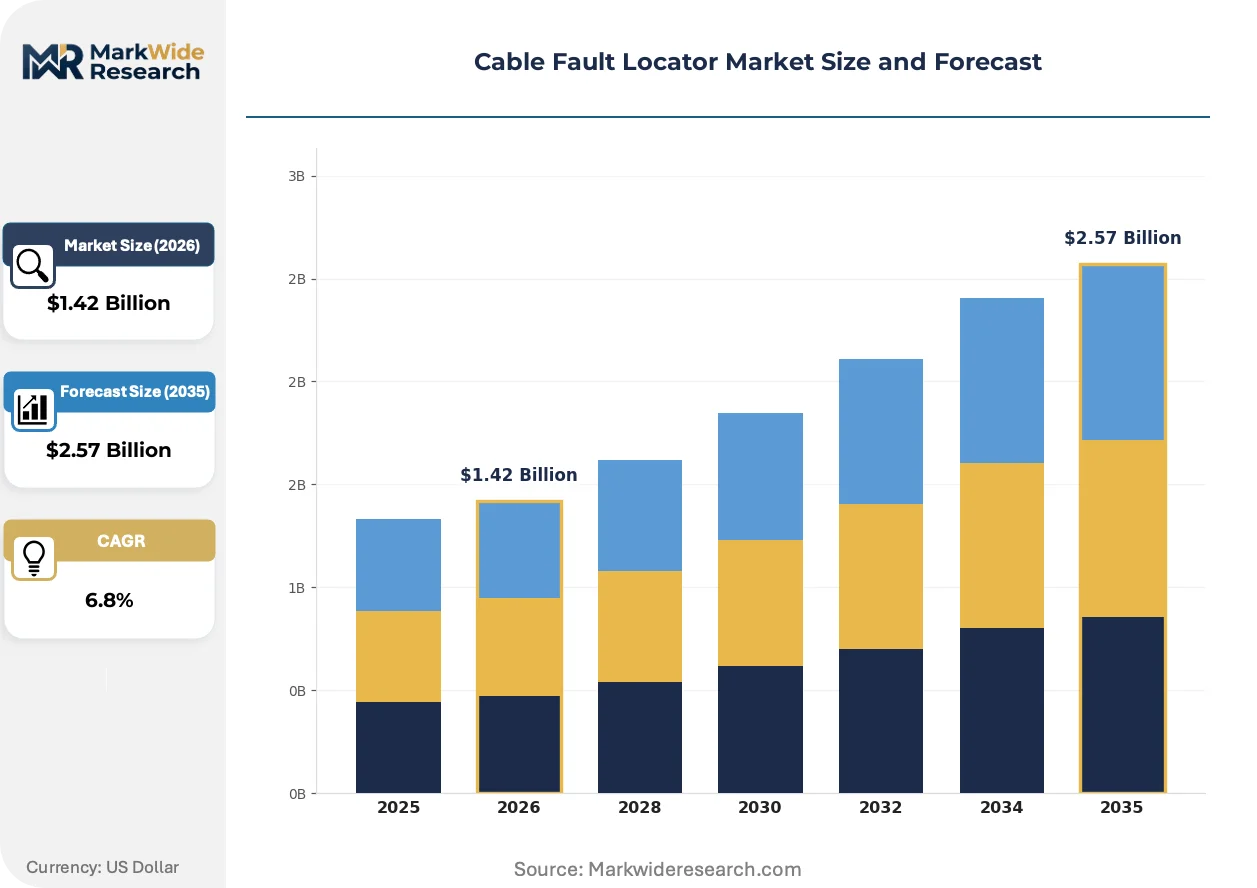
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Time Domain Reflectometer, Vehicle Maintenance, Leakage Testers, Wire Tracers Technology: OTDR, Analog, Digital, Hybrid End User: Telecommunications, Utility Providers, Automotive, Construction Application: Network Maintenance, Infrastructure Support, Troubleshooting, Circuit Testing |
| Companies Covered | Keysight Technologies, Hubbell Incorporated, 3M, HIOKI E.E. Corporation, SebaKMT, Fluke Corporation, BAUR GmbH, VIAVI Solutions Inc., Megger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cable Fault Locator Market Emerging Trajectories
Software-defined measurement architectures are dissolving the hardware boundary between cable fault location and broader grid condition monitoring, enabling platform consolidation that reshapes vendor competitive boundaries.
Time-domain reflectometry instrumentation is virtualizing core signal processing functions onto field-programmable gate arrays with embedded ARM cores, collapsing the cost structure of precision pulse-echo systems. US electric cooperatives and Canadian municipal utilities are adopting these reconfigurable platforms at twice the rate of analog predecessor replacements. This virtualization is compressing the price-performance frontier between mid-tier and premium equipment tiers, forcing incumbent suppliers to defend margin through firmware differentiation rather than hardware segmentation.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant leak detection integration into combined cable and thermal diagnostic platforms for underground transmission corridors. Industrial consequence includes mandatory sensor fusion requirements for new TSO procurement specifications in Germany and France. High-voltage underground cable maintenance contractors in the Benelux region are responding by consolidating tool inventories around multi-function units that satisfy both electrical fault location and environmental compliance documentation.
Buying committees at US investor-owned utilities are unbundling after-sales calibration and waveform analysis training from equipment purchase contracts, treating these as separately sourced professional services. Specialized regional calibration laboratories and independent training consultancies are displacing manufacturer-captive service organizations in the Midwest and Southeast markets. This unbundling is most visible in Texas and Florida, where deregulated market structures have eroded traditional single-vendor relationship lock-in that dominated vertically integrated utility procurement through the 2010s.
Cable Fault Locator Market Segmentation
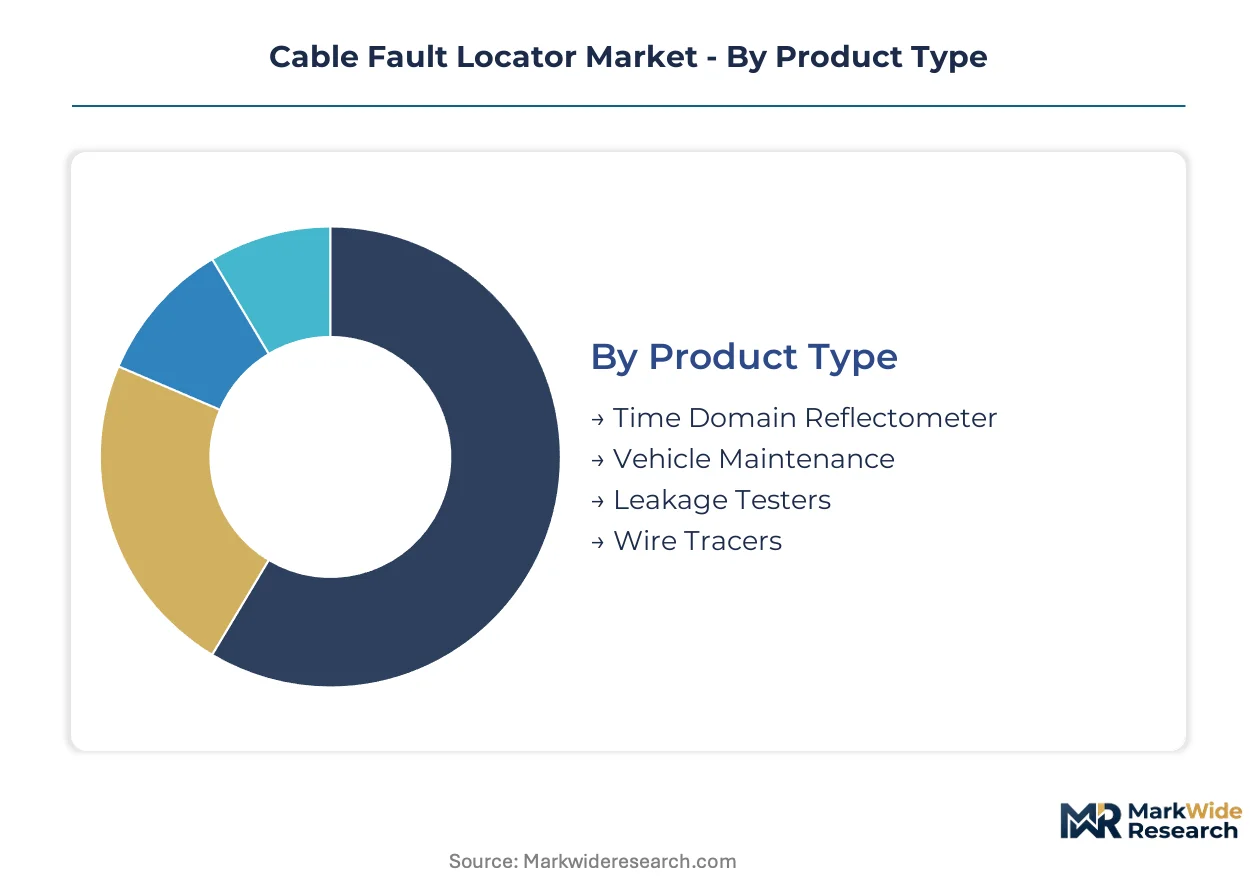
Cable fault locator segmentation reveals distinct procurement patterns across infrastructure types. Equipment specifications diverge sharply between telecommunications fiber networks and utility power distribution systems.
Product Type:
Use-case spectrum spans laboratory-grade precision instruments to handheld field diagnostics for rapid deployment.
- Time Domain Reflectometer:Pulse-echo architecture measures impedance discontinuities with sub-meter resolution in shielded power cables. Utility providers in the United States deploy these for underground distribution network maintenance mandated by IEEE 400 series standards.
- Vehicle Maintenance:Compact units diagnose automotive wiring harness faults and CAN bus integrity. Demand concentrates at commercial fleet operators and heavy equipment dealers requiring mobile electrical diagnostics.
- Leakage Testers:Quantify insulation resistance degradation in aged cable installations.
- Wire Tracers:Tone-based identification for non-energized conductor location in building electrical systems.
Established volume favors Time Domain Reflectometer; emerging adoption favors Vehicle Maintenance.
Technology:
Cost tier stratification separates premium digital architectures from legacy analog implementations.
- Digital:Embedded ARM processors automate waveform capture and fault classification algorithms. Digital architectures are gaining share fastest among municipal utilities replacing bridge-method equipment.
- OTDR:Optical Time Domain Reflectometry dominates single-mode fiber characterization for 5G backhaul and data center interconnects. Telecommunications contractors in urban markets specify OTDR for subscriber line certification.
- Analog:Murray and Varley loop techniques persist in cost-constrained rural cooperative fleets.
- Hybrid:Combines analog front-end sensitivity with digital signal processing backends.
Margin concentration sits with OTDR; replacement cycle acceleration favors Digital.
End User:
Customer type determines specification rigor and procurement channel selection.
- Utility Providers:Capital-intensive network footprints drive bulk procurement of IEEE 400.2 compliant diagnostic systems. Regulatory-mandated reliability standards in North America sustain replacement demand.
- Telecommunications:OTDR deployment accelerates with fiber-to-the-premises expansion and small cell densification programs.
- Automotive:Electric vehicle manufacturing quality control integrates cable fault detection into assembly line test stations.
- Construction:Electrical contractors require portable units for pre-commissioning verification of installed power and control cabling.
Procurement scale favors Utility Providers; specification evolution favors Telecommunications.
Application:
Maturity gradient separates scheduled preventive maintenance from reactive troubleshooting workflows.
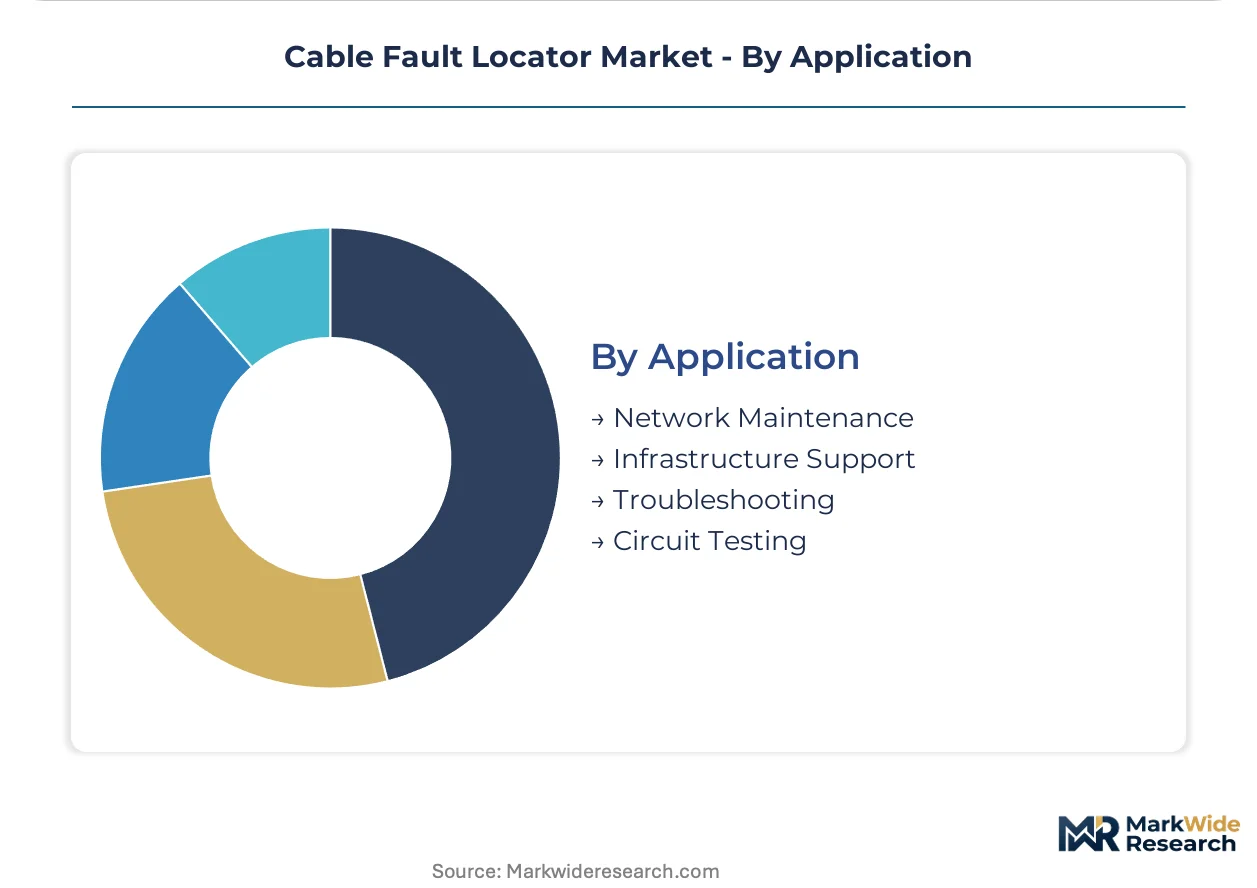
- Network Maintenance:Systematic inspection protocols for aging underground cable infrastructure. United States municipal utilities allocate capital budgets for time-domain reflectometry fleet expansion.
- Infrastructure Support:Grid modernization programs integrate fault locators with broader asset management platforms.
- Troubleshooting:Reactive deployment following customer outage reports or protection relay operations.
- Circuit Testing:Acceptance testing for newly installed medium-voltage distribution circuits.
Recurring revenue attachment favors Network Maintenance; incident-driven demand favors Troubleshooting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 2222 and state-level grid resilience bonds are redirecting utility capital toward underground cable diagnostics across multiple markets. Infrastructure aging curves diverge sharply between deregulated and vertically integrated jurisdictions.
United States
Investor-owned utilities in Texas and Florida are unbundling calibration services from equipment procurement contracts. IEEE 400.2 diagnostic voltage standards mandate systematic replacement of analog bridge methods across municipal fleets. The Midwest and Southeast markets host specialized regional calibration laboratories displacing manufacturer-captive service organizations.
Germany
Transmission system operators face mandatory sensor fusion requirements under EU F-Gas Regulation phase-down schedules for underground transmission corridors. The Benelux-adjacent industrial cluster consolidates tool inventories around multi-function diagnostic platforms. High-voltage maintenance contractors in North Rhine-Westphalia integrate refrigerant leak detection with cable fault location workflows.
China
State Grid Corporation's urban distribution automation mandates accelerate portable fault locator deployment in tier-one cities. MIIT electromagnetic compatibility certification shapes product design cycles for domestic manufacturers. The Yangtze River Delta manufacturing base supplies precision pulse generators to regional test equipment assemblers.
India
Central Electricity Authority mandates for smart grid urban distribution automation create first-mover positioning for portable fault locator vendors. BIS certification requirements for electrical test equipment extend product launch timelines for international suppliers. Maharashtra and Gujarat industrial corridors establish local calibration facilities to serve state electricity board procurement specifications.
Japan
TEPCO and regional utilities prioritize fiber-optic backhaul diagnostics for 5G small cell densification programs. METI industrial standards govern electromagnetic compatibility for telecommunications test equipment. The Kanto manufacturing cluster produces high-speed analog-to-digital converters supplying domestic and export cable fault locator assembly.
Cable Fault Locator Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement hierarchies. The vendor base stratifies between entrenched utility relationship holders and technology-focused entrants. Three archetypes dominate: diversified electrical equipment conglomerates, specialized cable diagnostics pure-plays, and telecommunications test equipment crossovers. Incumbents defend position through firmware differentiation rather than hardware segmentation, while challengers compress price-performance frontiers through FPGA virtualization.
Among diversified electrical equipment conglomerates, Hubbell Incorporated and 3M exemplify relationship-based channel control across North American utility procurement hierarchies. SebaKMT anchors the specialized cable diagnostics pure-play archetype with concentrated European market presence. Megger occupies a position spanning both utility and telecommunications verticals through test equipment breadth extending from insulation resistance to time-domain reflectometry systems.
| Leading Market Players |
|---|
| Keysight Technologies |
| Hubbell Incorporated |
| 3M |
| HIOKI E.E. Corporation |
| SebaKMT |
| Fluke Corporation |
| BAUR GmbH |
| VIAVI Solutions Inc. |
| Megger |
| Others |
Supply Flow & Price Mechanics
Undercapacity in East Asian semiconductor foundries is compressing component availability for precision pulse generators, forcing cable fault locator manufacturers to absorb cost escalation through supplier prepayment arrangements while passing selective increases to utility procurement committees.
Pricing Analysis
Certification level (IEEE 400.2/IEC 60502/CE marking) creates the primary spread between premium laboratory-grade systems and economy handheld units. Three-tier pricing structure across premium, standard, and economy levels dominates, with digital architectures commanding 40-60% premiums over analog bridge methods due to embedded processing costs. Cost compression in the mid-tier is intensifying because FPGA virtualization collapses hardware differentiation. Rural electric cooperatives exhibit highest price sensitivity, deferring replacement cycles; investor-owned utilities show lowest sensitivity, prioritizing IEEE compliance over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are proliferating through supply-chain finance facilities backed by Japanese trading houses, easing working capital strain for precision component assemblers. Manufacturing concentrates in China, Japan, and Germany, with high-speed analog-to-digital converters and field-programmable gate arrays drawing from Taiwan and South Korea foundry capacity. Single-source vulnerability in precision pulse generator ASICs creates exposure to geopolitical export controls. Distribution runs through specialized electrical test equipment distributors and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grid modernization capital cycles position this market for recovery, with municipal bond issuances for underground infrastructure resilience driving replacement demand across North American utility fleets.
For Market Incumbents: Insulate embedded customer relationships through captive calibration service contracts that lock in multi-year equipment refresh schedules. Acquire regional waveform analysis training consultancies in the Midwest and Southeast to preempt independent service unbundling. Vertical integration into FPGA firmware development centers in the Kanto manufacturing cluster defends margin against virtualization-driven price compression. For New Entrants and Emerging Players: Pursue rental channel partnerships with electrical contractor supply houses serving cyclical municipal maintenance departments in Texas and Florida. Target India's Maharashtra and Gujarat industrial corridors where Central Electricity Authority mandates for smart grid automation outpace established vendor calibration infrastructure. Lead with AI-assisted waveform classification as a technician-independent value proposition for low-experience emerging markets. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among specialized cable diagnostics pure-plays with entrenched European transmission system operator relationships. Long-term viability hinges on software-defined measurement platform consolidation that dissolves hardware boundaries with broader grid condition monitoring. Monitor FERC Order 2222 implementation velocity as the inflection signal for distributed energy resource integration spending that diverts utility capital from standalone cable diagnostics.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Waveform Classification | Machine learning inference at the edge enables technician-independent fault typing in low-experience markets. |
| Calibration Service Unbundling | Independent regional laboratories displace manufacturer-captive organizations in deregulated utility markets. |
| FPGA Virtualization Investment | Field-programmable gate arrays collapse cost structures between mid-tier and premium equipment tiers. |
| Multi-Function Sensor Fusion | EU F-Gas Regulation mandates combined cable and thermal diagnostic platforms for transmission corridors. |
| Rental Channel Development | Equipment-as-a-service models penetrate municipal departments with cyclical capital constraints. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of IEEE standards documentation, IEC certification databases, and municipal utility procurement records. Utility planning officers, cable maintenance supervisors, and test equipment procurement managers provided operational perspective. Secondary validation drew from FERC filings, EIA grid investment data, and CENELEC harmonized standards. Bottom-up equipment shipment analysis triangulates against top-down utility capital expenditure tracking.
Forecast inputs include IEEE 400 series adoption curves, municipal bond issuance velocity for grid resilience, and telecommunications fiber deployment schedules. Segmentation models span product architecture, technology tier, end-user vertical, and application workflow across the projection horizon. CAGRs derive from replacement cycle analysis and regulatory mandate implementation timelines. Equipment-as-a-service penetration and AI feature attach rates inform scenario-weighted outcomes.
Macroeconomic conditions sit as an overlay; deviation in municipal credit spreads, semiconductor foundry utilization, or utility rate case approvals would shift the trajectory. Forecasts reflect documented assumptions about standards harmonization and workforce apprenticeship pipeline recovery. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Medium Voltage Cables Accessories Market
Cables
US Cables Market
Cables
EPR Cable Market
Cables
Sensor Cable Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Multi-Core Land High Voltage Underground Cable Market
Cables
Insulated Wire and Cable Market
Cables
Submarine Communication Cables Market
Cables
Fire Resistance Cable Market
Cables
Electric Vehicle Unshielded HV Cables Market
Cables
Power Cable Accessories Market
Cables
Low Voltage Cable Accessories Market
Cables
Mineral Insulated (MI) Cable Market
Cables
GCC Cable Accessories Market
Cables
Instrumentation Cables Market
Cables
Ethernet Converters Market