
 AV Surge Protectors Market | 2026-2036
AV Surge Protectors Market Size, Share, and Industry Trends Forecast 2026-2036
AV Surge Protectors Market Analytics
Multi-source procurement for metal oxide varistor components is expanding as OEMs reduce dependence on single Asian suppliers. Schneider Electric leverages captive semiconductor fabrication to stabilize MOV lead times. Eaton anchors North American distribution through dedicated AV contractor channels. Siemens competes on IEC 61643-11 certification breadth across European cinema and broadcast installations.
AV surge protectors are electrical safety devices engineered to limit transient voltage spikes to safe levels, typically featuring clamping voltages between 330V and 400V and response times under one nanosecond to shield sensitive audio-visual equipment from lightning-induced or switching surges. Their primary commercial purpose centers on preventing signal degradation, equipment failure, and data loss in professional production environments where downtime carries substantial cost consequences. Rack-mounted configurations dominate margin pools in broadcast and live-event applications where space optimization and centralized power management command premium pricing. Metal oxide varistor technology leads unit volume due to cost-effectiveness in residential and standard commercial tiers, while transient voltage suppressor architectures capture specialized demand in high-frequency digital signal pathways where capacitance tolerance is critical.
UL 1449 fourth-edition standards enforced by the US product safety regulator mandate stricter surge-current testing and safer failure modes, directly elevating R&D thresholds for market access. CE marking under the EU's Low Voltage Directive and EMC Directive shapes cross-border trade patterns, with ECHA REACH compliance adding material disclosure burdens on MOV and GDT suppliers. IEC 61643 family standards from the international electrotechnical body provide the technical backbone for product interoperability across European and Asia-Pacific project specifications. Stakeholders must monitor evolving clamping-voltage thresholds and regional certification divergence when configuring product portfolios for multi-territory deployment.
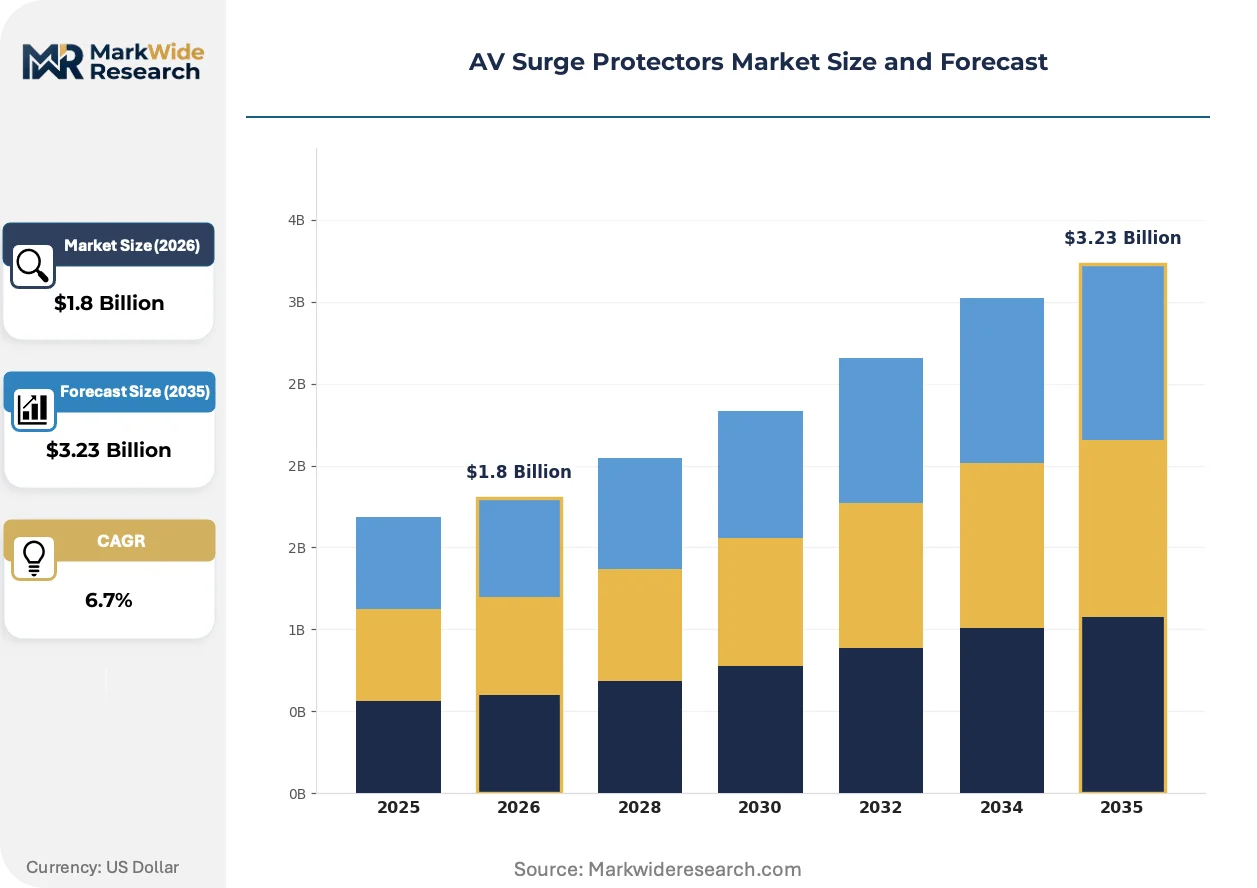
Market Dynamics
Broadcast and entertainment studios are consolidating power infrastructure around 4K and 8K production workflows, forcing surge protection architectures to accommodate higher-density rack configurations with stricter clamping voltage tolerances.
Growth Catalysts
- UL 1449 Fourth-Edition Enforcement:The US product safety regulator's stricter surge-current testing mandates are compelling facility upgrades across California post-production clusters and Texas live-event corridors.
- Metal Oxide Varistor Multi-Sourcing:OEM procurement teams are diversifying MOV component suppliers beyond single Asian sources to stabilize lead times for broadcast infrastructure rollouts.
- IEC 61643-11 Certification Breadth:European cinema and broadcast installations are specifying certified units for cross-border project interoperability, elevating technical documentation requirements.
Market Restraints
- MOV Input Cost Volatility:Zinc oxide and silver electrode prices fluctuate with commodity cycles, compressing margins on residential-tier units.
- Single-Source Semiconductor Dependence:Transient voltage suppressor diode fabrication concentrates in East Asian foundries, exposing TVS supply chains to geopolitical friction.
- Clamping Voltage Floor Constraints:Physical limits of gas discharge tube response speeds prevent sub-nanosecond protection for ultra-high-frequency digital pathways.
Strategic Opportunities
- India Broadcast Infrastructure:The country's national electrotechnical regulator is mandating surge protection for new transmission facilities under revised CEA wiring codes.
- Transient Voltage Suppressor Convergence:TVS architectures are merging with silicon carbide substrates to serve high-frequency digital signal pathways where capacitance tolerance is critical.
- Direct Contractor Channel Expansion:Specialized AV integrators are bypassing traditional electrical distributors to specify rack-mounted configurations with centralized power management.
Industry Challenges
- Certification Timeline Compression:UL 1449 fourth-edition retesting cycles and IEC 61643-11 documentation requirements are extending product launch windows by six to nine months.
- Legacy Facility Integration Complexity:Older broadcast plants with 240V single-phase distribution require custom step-down configurations that complicate standardized product deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AV Surge Protectors Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plug-in, Hardwired, Power Strip, Rack-mounted End User: Residential, Commercial, Industrial, Government Technology: Metal Oxide Varistor, Transient Voltage Suppressor, Gas Discharge Tube, Silicon Avalanche Diode Installation: Wall-mounted, Floor-mounted, Desktop, Ceiling-mounted |
| Companies Covered | Schneider Electric, ABB, Eaton, Siemens, Phoenix Contact, Littelfuse, Emerson Electric Co, DEHN, Belkin International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AV Surge Protectors Market Evolving Landscape
Surge protection architectures are bifurcating between commodity metal oxide varistor units and precision transient voltage suppressor systems, with certification requirements and signal fidelity demands determining technology selection.
Silicon carbide-based transient voltage suppressor arrays are expanding into broadcast routing switchers and camera control units where nanosecond response times protect 12G-SDI signal integrity. Major sports venue operators in Nevada and Florida are specifying these units for 4K replay systems. The technology is expanding into premium rack-mounted configurations that command higher margins than standard commercial tiers.
CE marking under the EU's Low Voltage Directive and EMC Directive is tightening electromagnetic compatibility thresholds for cinema projection equipment, forcing MOV suppliers to redesign filtering topologies. German and French integrators now require third-party test reports documenting conducted emissions compliance. European broadcast truck builders are absorbing these certification costs into project bids rather than product pricing.
Rental and staging companies are unbundling surge protection from power distribution packages, selling protection as a separate line item with damage liability carve-outs. This model is displacing all-inclusive power package pricing at music festivals and corporate events. The shift is most visible in California and Tennessee where production insurance underwriters are mandating documented protection levels.
AV Surge Protectors Market Segmentation
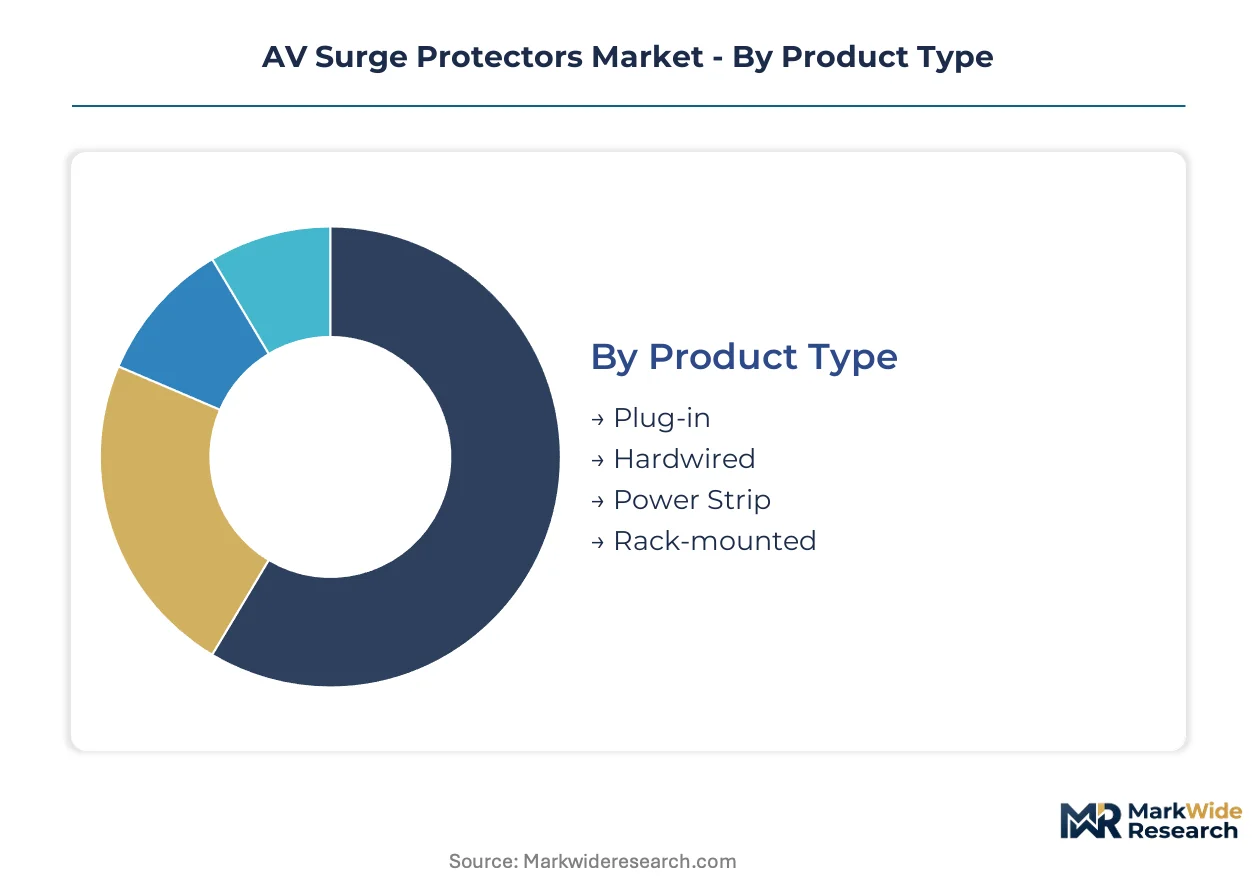
AV surge protector segmentation reflects divergent supply chain configurations across certification tiers and end-use complexity. Procurement patterns vary sharply between residential commodity channels and broadcast infrastructure projects requiring custom rack integration.
Product Type:
Supply concentration tilts toward rack-mounted configurations where captive semiconductor fabrication and dedicated contractor channels create defensive moats for incumbent OEMs.
- Rack-mounted:Units integrate centralized power management with 19-inch standard enclosure compatibility. California post-production clusters and Texas live-event infrastructure corridors specify these for 4K and 8K production workflows where space optimization commands premium positioning.
- Plug-in:Compact residential-grade units with standard NEMA 5-15 or IEC Type A interfaces. Mass-market distribution through electrical retailers concentrates procurement in United States big-box channels where price sensitivity dominates selection criteria.
- Hardwired:Permanently installed units requiring licensed electrician deployment. Commercial facility managers in Nevada sports venues specify these for permanent 4K replay system protection.
- Power Strip:Multi-outlet residential and light commercial configurations with basic surge suppression. Tennessee music festival rental companies unbundle these from power distribution packages with liability carve-outs.
Rack-mounted configurations absorb the bulk of installed capacity in professional broadcast environments; plug-in units are expanding most quickly through residential electrification retrofits.
End User:
Margin stratification across end-use tiers tracks certification burden and downtime cost exposure rather than unit volume alone.
- Commercial:Broadcast studios, cinema chains, and live-event venues requiring IEC 61643-11 or UL 1449 fourth-edition compliance. German and French integrators mandate third-party electromagnetic compatibility test reports for cinema projection equipment.
- Residential:Home theater and consumer electronics protection with basic MOV-based suppression. Florida residential construction absorbs units through electrician-specified new build installations.
- Industrial:Manufacturing floor AV monitoring and control systems with extended temperature tolerance requirements. Texas oilfield service companies deploy hardened units for remote camera surveillance networks.
- Government:Military, municipal, and educational procurement with bid-specified clamping voltage tolerances. India national electrotechnical regulator mandates surge protection for new transmission facilities under revised CEA wiring codes.
Commercial end-use absorbs the bulk of installed capacity; government procurement is climbing the fastest on infrastructure security mandates.
Technology:
Component sourcing geography directly shapes technology selection, with MOV multi-sourcing expanding while TVS diode fabrication remains concentrated in East Asian foundries.
- Metal Oxide Varistor:Zinc oxide ceramic discs with silver electrodes providing cost-effective clamping for standard commercial and residential tiers. Zinc commodity price volatility compresses margins on high-volume residential units.
- Transient Voltage Suppressor:Silicon-based avalanche diode arrays delivering sub-nanosecond response for high-frequency digital pathways. Silicon carbide substrate convergence serves 12G-SDI signal integrity in broadcast routing switchers.
- Gas Discharge Tube:Inert gas-filled spark gaps handling high-energy surges with microsecond response times. Physical response speed limits prevent deployment in ultra-high-frequency digital protection applications.
- Silicon Avalanche Diode:Precision voltage clamping for sensitive measurement and medical imaging equipment. Japanese broadcast truck builders specify these for portable production unit signal path protection.
Metal oxide varistor technology absorbs the bulk of installed capacity; transient voltage suppressor architectures are gaining share fastest on silicon carbide substrate advances.
Installation:
Installation modality selection reflects facility age and power distribution architecture rather than protection performance alone.
- Wall-mounted:Permanent electrical panel integration with hardwired connection. Older broadcast plants with 240V single-phase distribution require custom step-down configurations complicating standardized deployment.
- Floor-mounted:Mobile production and rental staging applications with caster-based relocation. California and Tennessee production insurance underwriters mandate documented protection levels for festival deployments.
- Desktop:Consumer and SOHO environments with localized equipment protection. United States remote work expansion drives replacement cycles for home office AV setups.
- Ceiling-mounted:Projector and display installations in cinema and corporate presentation environments. European cinema projection EMC Directive tightening forces MOV filtering topology redesigns for these applications.
Wall-mounted installations absorb the bulk of installed capacity; floor-mounted configurations are expanding most quickly on rental and staging market unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zinc oxide feedstock availability in East Asian foundries anchors TVS diode fabrication, while silver electrode sourcing concentrates in Mexican and Peruvian mining corridors. MOV ceramic production clusters in Germany and Japan supply European and North American assembly lines.
United States
California post-production studios and Texas live-event infrastructure corridors drive rack-mounted unit procurement for 4K and 8K workflows. UL 1449 fourth-edition enforcement by the US product safety regulator mandates stricter surge-current testing across facility upgrades. Nevada and Florida sports venues specify silicon carbide TVS arrays for 4K replay system protection.
Germany
Cinema chains and broadcast truck builders demand IEC 61643-11 certified units with third-party electromagnetic compatibility test reports. CE marking under the EU Low Voltage Directive and EMC Directive tightens filtering topology requirements for projection equipment. Bavarian and North Rhine-Westphalian integrators absorb certification costs into project bids rather than product pricing.
India
National transmission facility construction accelerates under revised CEA wiring codes mandating surge protection for new broadcast infrastructure. The central electrotechnical regulator's mandates align with government infrastructure security programs. Maharashtra and Karnataka post-production clusters specify rack-mounted configurations for regional content creation hubs.
Japan
Broadcast truck builders and portable production unit manufacturers specify precision silicon avalanche diodes for signal path protection. METI industrial standards shape component sourcing for high-frequency digital applications. Tokyo and Osaka metropolitan areas concentrate demand from commercial broadcasters upgrading to 12G-SDI infrastructure.
China
Domestic MOV component fabrication serves both internal assembly and export markets for standard commercial tiers. GB standards and MIIT regulations govern electromagnetic compatibility for cinema and broadcast equipment. Yangtze River Delta manufacturing clusters supply zinc oxide ceramic discs to global OEM procurement teams.
AV Surge Protectors Market Competitive Landscape
Global majors compete with regional champions across certification breadth and captive semiconductor fabrication capabilities. The vendor base stratifies into three tiers: integrated electrical conglomerates with captive MOV production, specialized surge protection houses with IEC 61643-11 documentation depth, and mass-market consumer electronics brands. Dominant competitive moves include backward integration into zinc oxide ceramic supply and dedicated AV contractor channel expansion bypassing traditional electrical distribution.
Among integrated electrical conglomerates, Schneider Electric and Eaton occupy positions anchored by captive fabrication and North American distribution infrastructure. Siemens exemplifies the European certification-focused archetype with IEC 61643-11 breadth across cinema and broadcast installations. These three represent the defensive moat structure where semiconductor control and regulatory documentation create barriers to commoditization.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Eaton |
| Siemens |
| Phoenix Contact |
| Littelfuse |
| Emerson Electric Co |
| DEHN |
| Belkin International |
| Others |
Value Network & Pricing Analysis
Captive semiconductor fabrication anchors both supply position and pricing power for integrated OEMs like Schneider Electric, insulating rack-mounted configurations from metal oxide varistor commodity swings while extracting premium positioning through controlled component availability.
Pricing Analysis
Warranty bundling separates professional broadcast tiers from residential commodity units, with California post-production clusters and Texas live-event corridors demanding damage liability carve-outs that inflate total cost of ownership. Three-tier pricing structure across premium, standard, and economy levels tracks certification burden, with UL 1449 fourth-edition and IEC 61643-11 compliance commanding substantial markups over uncertified alternatives. Cost compression in residential plug-in segments stems from zinc oxide feedstock volatility, while rack-mounted commercial buyers show minimal price sensitivity given downtime cost exposure. Rental and staging companies in Tennessee and California now unbundle protection entirely, selling surge suppression as standalone service lines with documented protection levels mandated by production insurance underwriters.
Supply Chain Analysis
Single-source vulnerability sits with East Asian foundries fabricating transient voltage suppressor diodes, exposing TVS supply chains to geopolitical friction while MOV ceramic production concentrates in Germany and Japan. Zinc oxide feedstock draws from Mexican and Peruvian mining corridors, with silver electrode sourcing tethered to the same geographic concentration. Commodity price volatility in zinc and silver inputs compresses margins on high-volume residential units. Distribution runs through dedicated AV contractor channels bypassing traditional electrical distributors for rack-mounted configurations, while mass-market plug-in units flow through big-box retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOV multi-sourcing constraints and captive semiconductor scarcity prop pricing power for integrated OEMs, creating durable margin pools for players controlling upstream component fabrication.
For Market Incumbents: Lock in MOV supply through backward integration or long-term offtake agreements with German and Japanese ceramic producers, insulating against zinc commodity swings. Deepen IEC 61643-11 documentation breadth to capture European cinema and broadcast truck builder procurement, where third-party electromagnetic compatibility test reports now gate project participation. Defend against silicon carbide TVS convergence by accelerating substrate R&D partnerships or acquisition of specialized diode architects. For New Entrants and Emerging Players: AV integrators represent the most penetrable channel partner type for bypassing incumbent electrical distributor lock-in, particularly in India's Maharashtra and Karnataka post-production clusters where CEA wiring code mandates are driving surge protection specification. Target government procurement in transmission facility construction, where infrastructure security programs are mandating protection levels with limited incumbent saturation. Pursue direct contractor relationships with Nevada and Florida sports venue operators specifying silicon carbide arrays for 4K replay systems. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated electrical conglomerates seeking captive semiconductor fabrication capabilities or IEC 61643-11 certification depth. Long-term viability favors players with upstream control over MOV ceramic supply or downstream lock-in through dedicated AV contractor channels. Watch silicon carbide substrate cost curves as inflection indicator for TVS architecture share gains against traditional MOV dominance.| Strategic Initiative | Industry Significance |
|---|---|
| MOV Multi-Sourcing Expansion | Diversification beyond single Asian suppliers stabilizes lead times for broadcast infrastructure rollouts. |
| IEC 61643-11 Certification Investment | Third-party documentation depth gates European cinema and broadcast truck builder procurement decisions. |
| Silicon Carbide TVS Convergence | Substrate advances enable nanosecond response for 12G-SDI signal integrity in broadcast routing switchers. |
| Direct Contractor Channel Expansion | Bypassing electrical distributors captures premium positioning in rack-mounted configuration specification. |
| India Broadcast Infrastructure Entry | CEA wiring code mandates for new transmission facilities create regulatory-driven demand acceleration. |
Research Methodology
Trade association filings, customs and import-export databases, and electrotechnical standard body publications formed the secondary backbone, supplemented by SEC 10-K disclosures from integrated electrical conglomerates. Primary interviews with broadcast engineering directors, AV integration firm procurement leads, cinema chain facility managers, and surge protection OEM product managers validated component sourcing patterns and certification timeline compression effects. Bottom-up unit shipment estimates by product type and technology tier were cross-checked against top-down market value reconstructions.
Historical trendline analysis across MOV and TVS technology adoption curves informed projection frameworks, with segmentation dimensions spanning product type, end-use tier, technology architecture, and installation modality. CAGRs were derived from fitted growth curves applied to base-year estimates, incorporating industry-specific inputs including UL 1449 fourth-edition enforcement timelines, India CEA wiring code implementation pacing, and silicon carbide substrate cost trajectory assumptions across the analysis window.
Caveats apply where zinc oxide commodity price spikes, East Asian foundry disruption, or regulatory divergence between UL 1449 and IEC 61643 clamping voltage thresholds could materially shift the outlook. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Devices & Electrical Systems
Workstation Market
Electronic Devices & Electrical Systems
Smart Wiring Devices Market
Electronic Devices & Electrical Systems
Video Decoder Market
Electronic Devices & Electrical Systems
Intelligent Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Instrument Clusters Market
Electronic Devices & Electrical Systems
Function Generator Market
Electronic Devices & Electrical Systems
Multi-Effects Processor Market
Electronic Devices & Electrical Systems
Rugged Handheld Electronic Devices Market
Electronic Devices & Electrical Systems
Digital Instrument Transformer Market
Electronic Devices & Electrical Systems
Global Hybrid Devices Market
Electronic Devices & Electrical Systems
Portable Charger Market
Electronic Devices & Electrical Systems
Electronic Weighing Machines Market
Electronic Devices & Electrical Systems
Electronic Latching System Market
Electronic Devices & Electrical Systems
Broadcasting Equipment Market
Electronic Devices & Electrical Systems
Printed Electronics Devices Market
Electronic Devices & Electrical Systems
Electrical and Electronic Computer-Aided Design (ECAD) Market