
 LED Cable Market | 2026-2036
LED Cable Market Size, Share, and Industry Trends Forecast 2026-2036
LED Cable Market Foresight
Asian copper conductor producers is rebalancing output toward specialty illumination-grade alloys as LED fixture OEMs consolidate supplier bases. Prysmian Group leverages its European cable heritage to dominate high-reliability commercial installations. Nexans anchors North American project pipelines through utility-scale lighting infrastructure partnerships. Sumitomo Electric specializes in thin-gauge flexible conductors for Japan's precision electronics sector.
LED cable denotes insulated conductor assemblies engineered to deliver low-voltage direct current to solid-state illumination sources, typically incorporating copper cores with PVC or silicone jacketing rated for 60°C to 105°C operating temperatures and designed to minimize voltage drop across extended linear runs. Flexible cables lead volume shipments due to their adaptability in architectural cove and cabinet installations where bending radius requirements exclude rigid alternatives. Smart control technology commands premium positioning as tunable white and RGB systems require multi-conductor configurations with integrated signal pathways for DALI and wireless protocol compatibility.
FCC electromagnetic emissions standards govern signal-integrated cable assemblies in the US, while REACH substance restrictions and CE marking obligations in Europe dictate halogen-free and low-smoke compound formulations for public space installations. China's GB standards and MIIT certifications shape export-ready product specifications for manufacturers serving domestic and overseas markets. Stakeholders must monitor evolving interoperability protocols between smart lighting platforms and cable-embedded control circuitry as system architectures consolidate around unified building management frameworks.
Market Dynamics
Smart building consolidation is compressing supplier tiers as facility managers demand cable assemblies that integrate power delivery with DALI-2 and wireless control protocols in single-source procurement packages.
Growth Catalysts
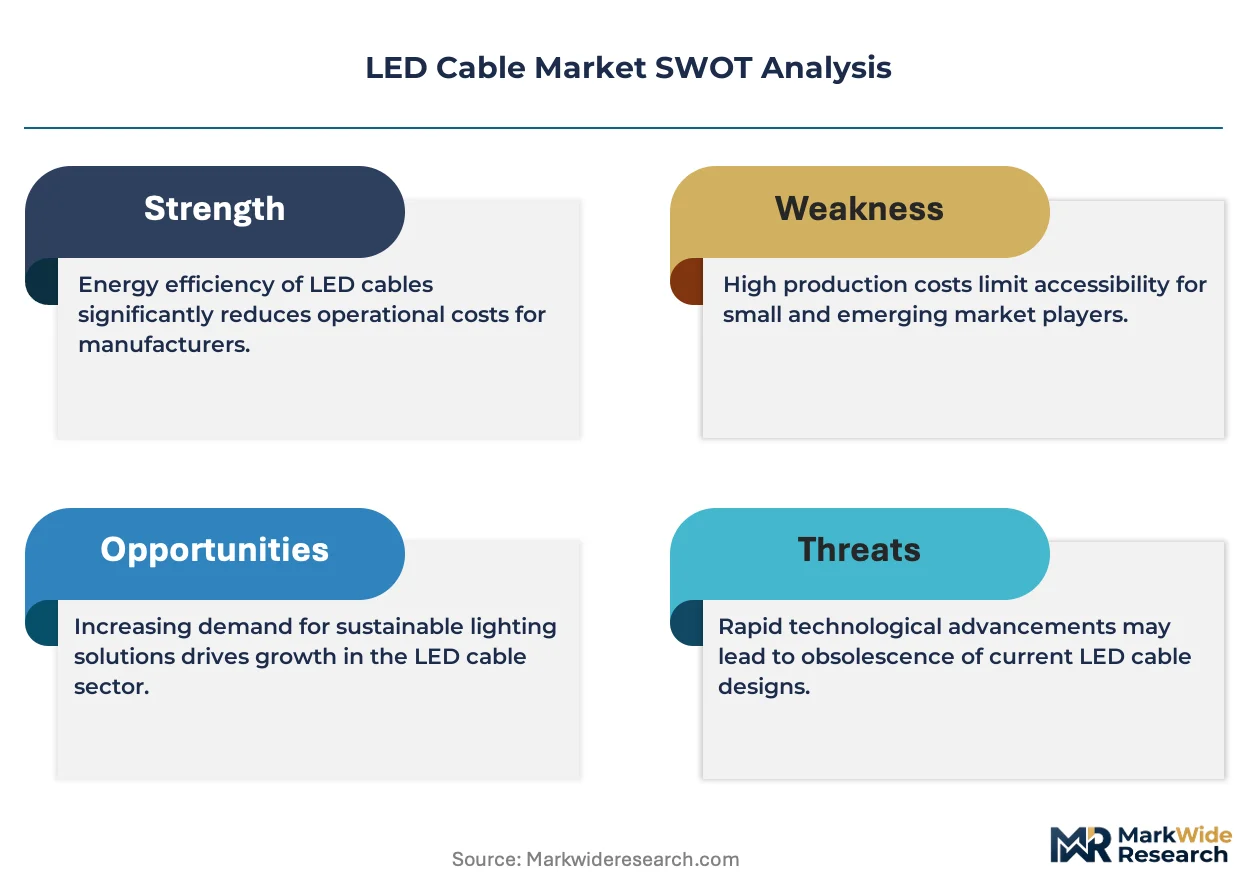
- Halogen-free compound mandates:REACH and RoHS restrictions in Europe are forcing reformulation of PVC jacketing toward low-smoke zero-halogen alternatives. German commercial real estate developers now specify LSZH as baseline for public infrastructure tenders.
- China domestic fixture production:MIIT-certified cable manufacturers in Guangdong and Jiangsu provinces supply captive demand from LED luminaire OEMs serving both local installation and export markets.
- Copper conductor specialization:Asian metallurgical producers are rebalancing capacity toward illumination-grade oxygen-free copper alloys that reduce resistive losses across extended linear LED runs.
Market Restraints
- Copper price volatility:LME copper futures swings above 8,000 USD per metric ton compress cable fabricator margins and complicate long-term project bidding.
- Regional supply concentration:Over 60 percent of flexible cable extrusion capacity clusters in East China, creating vulnerability to port congestion and regional power rationing.
- Silicone compound scarcity:Medical-grade silicone diversion during health emergencies constrains availability of high-temperature jacketing for industrial LED applications.
Strategic Opportunities
- India smart city infrastructure:Bureau of Indian Standards certification alignment with IEC 60502 creates entry pathway for halogen-free cable suppliers in municipal lighting retrofits.
- PoE lighting convergence:Integration of IEEE 802.3bt power-over-ethernet with LED cable assemblies opens specification opportunities in commercial office fit-outs.
- EU Green Deal procurement rules:Public sector tender scoring that weights embodied carbon favors cable producers with verified recycled copper content and regional manufacturing footprints.
Industry Challenges
- Interoperability testing bottlenecks:DALI-2 and wireless protocol certification delays at accredited laboratories extend product launch timelines by four to six months.
- Compound formulation R&D:Development of halogen-free sheathing that matches PVC flexibility at sub-zero temperatures demands specialized polymer science talent scarce outside major chemical conglomerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Cable Market |
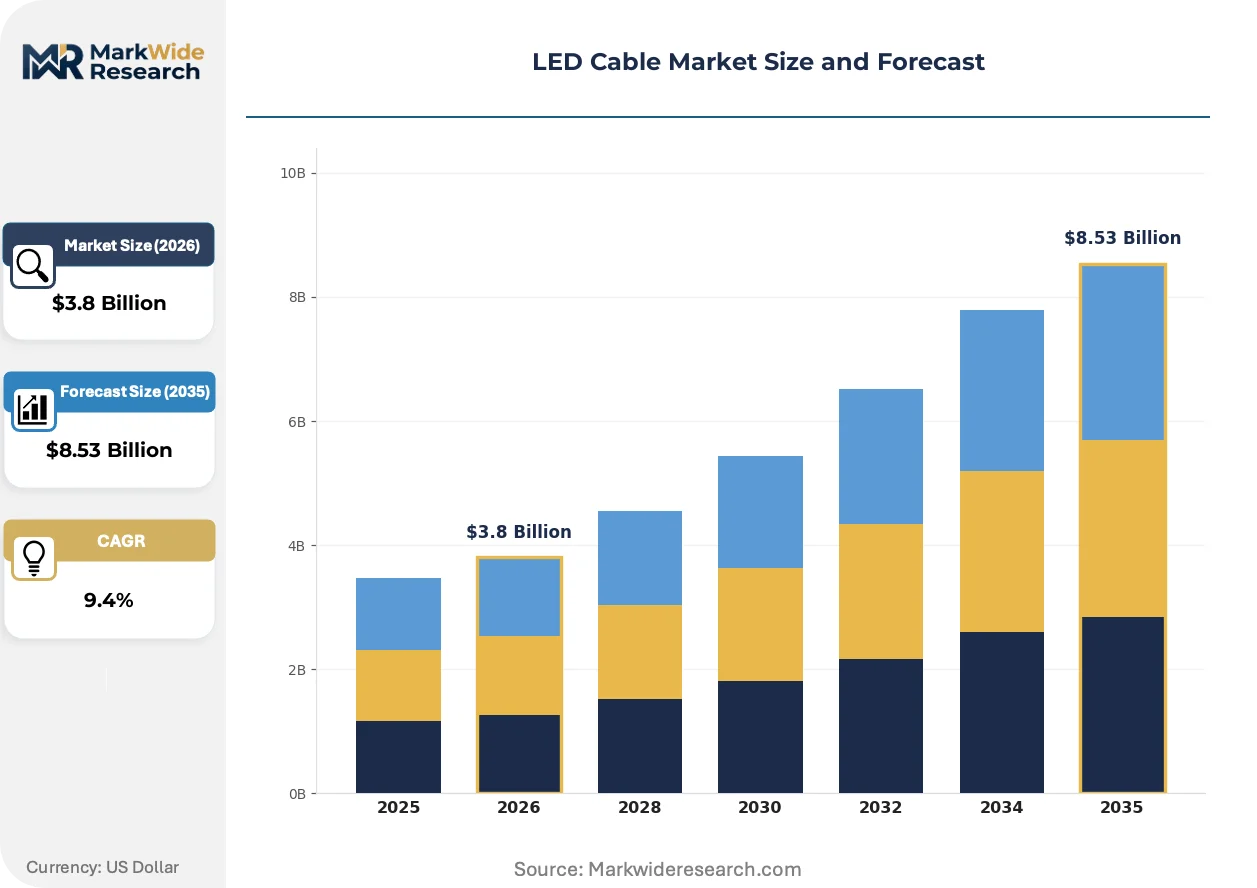
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Cables, Rigid Cables, Connector Cables, Strip Lights Technology: RGB, Tunable White, Smart Control, Linear Application: Residential Lighting, Commercial Lighting, Automotive Lighting, Decorative Lighting Material: Copper, PVC, Silicone, Polycarbonate |
| Companies Covered | Prysmian Group, Corning Incorporated, Nexans, Sumitomo Electric, LS Cable & System, Furukawa Electric, Signify Holding, Acuity Brands, ams-OSRAM AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Cable Market Shifts & Advancements
Control-embedded cable architectures are displacing discrete wiring topologies as building automation systems consolidate around unified IP-based management platforms.
Self-diagnostic cable assemblies with integrated temperature and current sensors are automating fault detection in large-scale commercial installations. Facility operators in US Class A office buildings are specifying these systems for predictive maintenance contracts. The technology is automating service dispatch decisions and compressing warranty claim resolution cycles.
REACH substance restrictions are tightening permissible thresholds for phthalate plasticizers in PVC compounds across European public space installations. Cable manufacturers serving German and French municipal clients are accelerating migration to bio-based plasticizer formulations. The regulation is reshaping compound supplier relationships and qualifying new raw material sources.
Direct procurement from cable fabricators is displacing traditional electrical distributor channels among large lighting OEMs with consolidated supplier programs. Tier-one fixture manufacturers in China and Italy are establishing annual volume agreements that bypass regional stocking distributors. The shift is most visible in high-volume architectural linear lighting programs where specification consistency outweighs local inventory convenience.
LED Cable Market Segmentation
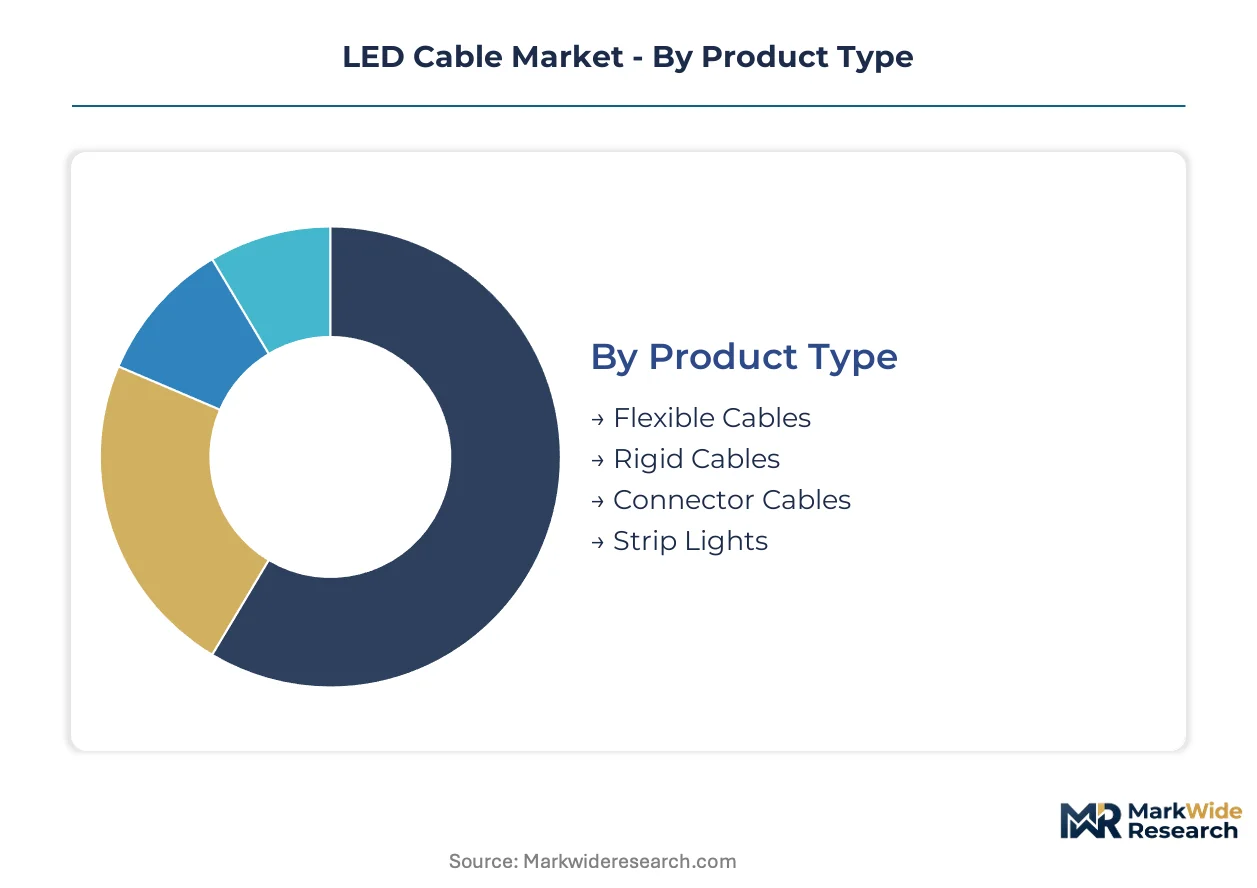
LED cable purchasing decisions diverge sharply across installation environments, with commercial contractors prioritizing protocol compatibility while residential buyers emphasize bending radius and ease of termination. Material specifications and control integration capabilities create tiered price bands that reshape supplier selection criteria.
Product Type:
Installation mechanics and spatial constraints separate buyers into distinct procurement behaviors.
- Flexible Cables:Multi-strand copper conductors with silicone or PVC jacketing rated for tight bending radii below 50mm. Architectural cove lighting in German commercial real estate and under-cabinet residential installations in US kitchen renovations drive consistent specification. REACH-compliant halogen-free formulations command premium positioning in EU public tenders.
- Connector Cables:Pre-terminated assemblies with standardized plug configurations for rapid field installation. LED fixture OEMs in Guangdong province source these for export-bound luminaire programs where labor cost minimization outweighs raw cable economics. Modular architectures reduce on-site termination errors and accelerate project commissioning timelines.
- Rigid Cables:Solid-core conductors with thicker wall insulation for fixed conduit runs where flexing never occurs.
- Strip Lights:Self-adhesive PCB-mounted LED arrays with integrated conductors for linear accent applications.
Flexible cables lead volumes today; connector cables are gaining share fastest.
Technology:
Control sophistication determines margin tiers, with basic illumination competing against networked systems.
- Smart Control:Multi-conductor assemblies embedding DALI-2 signal pairs alongside power conductors for unified building management integration. US Class A office developers specify these for predictive maintenance contracts tied to sensor-embedded cable diagnostics. FCC emissions compliance testing extends product launch cycles but locks in multi-year specification relationships.
- RGB:Four-conductor configurations delivering independent red, green, blue channels plus common return for dynamic color mixing. Hospitality venues in Dubai and entertainment districts in Seoul deploy these for brand-aligned ambient programming. Controller interoperability with wireless protocols remains a procurement friction point.
- Tunable White:Dual-channel CCT-adjustable systems for circadian lighting in healthcare and workplace wellness applications.
- Linear:Single-color fixed-output systems for basic functional illumination with minimal control overhead.
Linear systems anchor baseline volumes; smart control configurations show the steepest expansion trajectory.
Application:
End-use durability requirements and regulatory exposure create distinct material specification patterns.
- Commercial Lighting:Large-footprint installations demanding extended cable runs with voltage drop mitigation. German municipal infrastructure tenders mandate LSZH sheathing for public space compliance. Facility managers prioritize single-source procurement packages integrating power delivery with DALI-2 and wireless protocols.
- Automotive Lighting:Vibration-resistant conductor assemblies with high-temperature silicone jacketing rated above 125°C. Tier-one suppliers in Japan and South Korea specify thin-gauge flexible conductors for precision electronics integration. Thermal cycling resistance dominates qualification protocols.
- Residential Lighting:Cost-optimized PVC-jacketed products for consumer-grade fixture attachment.
- Decorative Lighting:Aesthetic-focused assemblies where color consistency and concealment drive selection.
Commercial applications dominate revenue concentration; automotive lighting is climbing the fastest.
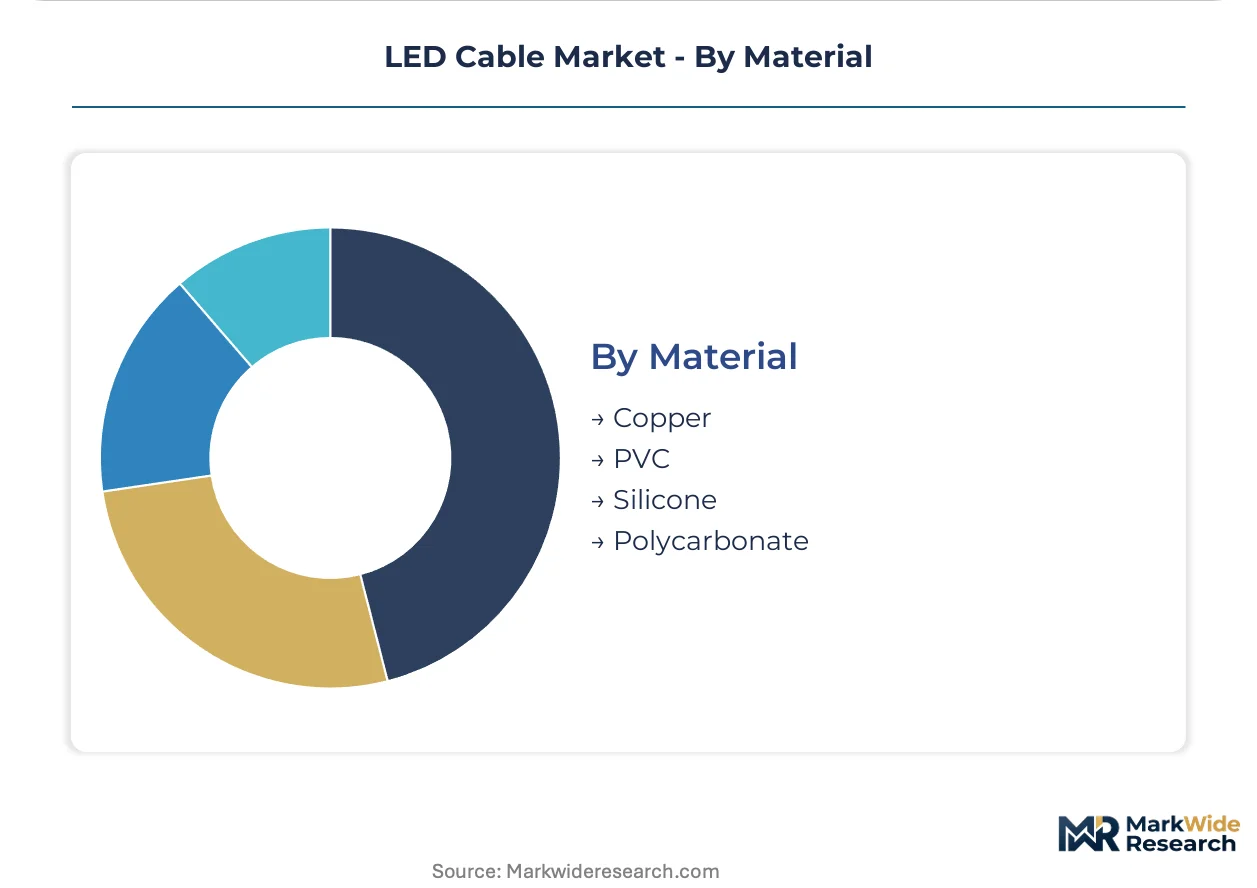
Material:
Performance thresholds and regulatory compliance reshape compound selection across geographies.
- Copper:Oxygen-free high-conductivity alloys for minimized resistive losses across extended LED runs. Asian metallurgical producers are rebalancing capacity toward illumination-grade specifications as fixture OEMs consolidate supplier bases. LME price volatility above 8,000 USD per metric ton compresses fabricator margins.
- Silicone:High-temperature elastomer jacketing for industrial and automotive thermal extremes. Medical-grade silicone diversion during health emergencies constrains availability for LED applications, forcing qualification of alternative high-temperature compounds.
- PVC:Cost-optimized standard jacketing facing REACH phthalate plasticizer restrictions in European public installations.
- Polycarbonate:Rigid connector housings and mechanical protection components.
Copper conductors anchor all volume tiers; silicone formulations are expanding most quickly in premium thermal applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as cable fabricators migrate capacity toward jurisdictions with streamlined compliance pathways and concentrated downstream demand. Cost-of-compliance gaps between REACH-governed Europe and MIIT-certified China are accelerating specialization by geography.
China
Domestic LED fixture OEMs in Guangdong and Jiangsu provinces consume the majority of regional cable output through captive supply arrangements. MIIT certification requirements shape export-ready product specifications for manufacturers serving overseas markets. The Pearl River Delta cluster anchors flexible cable extrusion capacity serving both local installation and global luminaire export programs.
Germany
Commercial real estate developers specify LSZH sheathing as baseline for public infrastructure tenders under REACH and RoHS mandates. ECHA substance restrictions are tightening permissible thresholds for phthalate plasticizers in PVC compounds. The Ruhr industrial corridor hosts compound formulation R&D facilities developing bio-based plasticizer alternatives for municipal clients.
United States
Class A office building developers specify smart control cable assemblies for predictive maintenance contracts tied to sensor-embedded diagnostics. FCC electromagnetic emissions standards govern signal-integrated cable assemblies in commercial installations. The Southeast manufacturing belt is attracting cable extrusion investments serving utility-scale lighting infrastructure partnerships.
Japan
Precision electronics manufacturers specify thin-gauge flexible conductors for automotive and industrial LED integration. METI efficiency standards drive conductor alloy specialization toward illumination-grade oxygen-free copper. The Kansai region hosts metallurgical producers rebalancing capacity toward thermal-cycling-resistant jacketing formulations.
India
Bureau of Indian Standards certification alignment with IEC 60502 creates entry pathways for halogen-free cable suppliers in municipal lighting retrofits. Smart city infrastructure programs are expanding specification opportunities for multi-conductor assemblies with integrated control pathways. Maharashtra and Gujarat industrial corridors are emerging as fabrication hubs serving domestic fixture OEMs.
LED Cable Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart control integration and halogen-free compound specialization. The vendor base stratifies across three tiers: integrated cable-luminaire conglomerates, standalone conductor specialists, and regional extrusion houses serving captive demand. Archetypes include European heritage brands leveraging certification credibility, Asian scale players optimizing unit economics, and niche specialists in high-temperature silicone formulations. Competitive moves center on backward integration into copper alloy production and strategic partnerships with lighting OEMs for co-development of protocol-embedded assemblies.
Among European heritage conglomerates, Prysmian Group and Nexans exemplify the certification-driven archetype, anchoring high-reliability commercial installation specifications through REACH-aligned compound portfolios. Sumitomo Electric occupies a position within the precision-specialist tier, representing Japanese metallurgical expertise in thin-gauge flexible conductors. These three fabricators illustrate the geographic segmentation of competitive advantage: European incumbents leverage regulatory compliance credibility, while Asian specialists optimize conductor geometries for thermal and spatial constraints.
| Leading Market Players |
|---|
| Prysmian Group |
| Corning Incorporated |
| Nexans |
| Sumitomo Electric |
| LS Cable & System |
| Furukawa Electric |
| Signify Holding |
| Acuity Brands |
| ams-OSRAM AG |
| Others |
Supply & Pricing Matrix
Control-embedded cable architectures are compressing procurement tiers as building automation systems consolidate around unified IP-based management platforms. This technology shift simultaneously raises compound R&D costs for multi-conductor assemblies and concentrates volume purchasing power among tier-one fixture OEMs.
Pricing Analysis
Distributor margin compression runs through the channel as direct procurement from cable fabricators displaces traditional electrical distributor networks among large lighting OEMs. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale. Cost compression in standard-grade PVC-jacketed products is intensifying because of LME copper volatility above 8,000 USD per metric ton. Residential contractors exhibit the highest price sensitivity, while Class A office developers prioritize predictive maintenance bundling over unit economics.
Supply Chain Analysis
Copper conductor supply rests on Asian metallurgical producers in China, Japan, and South Korea that are rebalancing capacity toward illumination-grade oxygen-free alloys. Silicone jacketing compounds and halogen-free LSZH formulations constitute critical input dependencies alongside copper cathode. Single-source vulnerability concentrates in East China's flexible cable extrusion cluster, where port congestion and regional power rationing threaten delivery continuity. Distribution runs through annual volume agreements that bypass regional stocking distributors for high-volume architectural linear programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LED cable market functions as a stable compounder anchored by irreversible building electrification mandates and smart infrastructure retrofit cycles across commercial real estate.
For Market Incumbents: Hedge copper price exposure through long-term offtake agreements with Guangdong and Jiangsu metallurgical suppliers. Accelerate backward integration into compound formulation R&D to defend margin position against REACH phthalate restrictions. Prioritize certification investment at FCC-accredited laboratories to compress DALI-2 protocol approval timelines. For New Entrants and Emerging Players: The price-point gap between REACH-compliant LSZH premium assemblies and standard PVC-jacketed economy products creates entry space for mid-tier halogen-free specialists. Target India's municipal lighting retrofit programs where BIS certification alignment with IEC 60502 lowers regulatory barriers. Pursue co-development partnerships with tier-two fixture OEMs in Maharashtra and Gujarat industrial corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional extrusion houses serving captive domestic demand with undifferentiated product portfolios. Five-to-ten-year viability favors compound specialists with verified bio-based plasticizer pipelines and regional manufacturing footprints under EU Green Deal procurement scoring. Watch copper LME futures direction and REACH substance threshold announcements as inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Alloy Production | Captive supply of illumination-grade oxygen-free copper mitigates LME volatility exposure for Guangdong fabricators. |
| Halogen-Free Compound R&D Partnership | Bio-based plasticizer development with Ruhr corridor chemical conglomerates secures REACH-compliant municipal tender eligibility. |
| DALI-2 Protocol Certification Investment | FCC-accredited laboratory relationships compress four-to-six month interoperability testing bottlenecks for US commercial specifications. |
| Direct-to-OEM Volume Agreements | Annual contracts with Guangdong and Jiangsu fixture manufacturers displace distributor margins and lock specification consistency. |
| India Smart City Infrastructure Entry | BIS certification alignment with IEC 60502 opens municipal lighting retrofit procurement in Maharashtra and Gujarat corridors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged cable fabricator procurement directors, LED fixture OEM supply chain managers, commercial real estate facility operators, compound formulation R&D leads, and MIIT certification consultants. Secondary validation drew from customs trade databases, ECHA substance restriction filings, FCC equipment authorization records, and SEC 10-K disclosures from listed cable producers. Bottom-up volume triangulation against top-down spending estimates anchored market sizing.
Historical reference periods established baseline growth trajectories across product type, technology tier, application environment, and material composition dimensions. Modeled projections incorporated copper price elasticity coefficients, REACH compliance cost pass-through rates, and smart control adoption curves across the analysis window. CAGRs derived from segmented growth rate reconciliation against aggregate market expansion. Forecast inputs included MIIT certification timeline data and German municipal tender specification trends.
Caveats apply where copper futures volatility, REACH substance threshold revisions, or DALI-2 protocol standardization delays could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cables
Mexico Wires and Cables Market
Cables
Anti-Static Space Wires Market
Cables
Low-Temperature Cable Market
Cables
Coaxial Cable Market
Cables
Medium Voltage Cables Accessories Market
Cables
Multicore Cables Market
Cables
EV Charging Cable and Connector Durability and Safety Test Equipment Market
Cables
Cable Clamp Market
Cables
Usb Data Cable Market
Cables
Fiber Optic Cable Accessories Market
Cables
Copper Cabling Systems Market
Cables
Europe Cable Management Market
Cables
Submarine Communication Cables Market
Cables
US Medium Voltage Cable Accessories Market
Cables
Global Ethernet Cable Market
Cables
Submarine Cable System Market