
 External Wall Insulation Board Market | 2026-2036
External Wall Insulation Board Market Size, Share, and Industry Trends Forecast 2026-2036
External Wall Insulation Board Market Insights
The capital-intensity divergence between integrated mineral wool producers and specialist foam board fabricators is redrawing competitive boundaries in external wall insulation. Saint-Gobain leverages captive glass-melting capacity and vertical raw material control to sustain margin stability across European retrofit cycles. Kingspan competes through polyurethane core innovation and prefabricated panel system integration, while Rockwool anchors its position with non-combustible stone wool formulations that dominate high-rise fire-safety specifications.
External wall insulation board comprises rigid or semi-rigid panels engineered from synthetic foams, mineral fibers, or composite laminates, typically achieving thermal conductivities between 0.022 and 0.040 W/mK depending on core chemistry. These boards reduce heat transfer through building envelopes when mechanically fixed or adhesively bonded to masonry or framed substrates, enabling compliance with progressively stringent energy codes. Mineral wool commands the largest installed base among material types due to fire resistance and acoustic damping properties, though polyisocyanurate and polyurethane segments are expanding fastest in commercial facade retrofit where space constraints demand thinner insulating layers. Wet rendered installation dominates residential applications across Northern Europe, while mechanical fixing systems lead in commercial complexes requiring rainscreen ventilation cavities.
The EU Green Deal and Energy Performance of Buildings Directive mandate near-zero energy standards for new construction and deep renovation benchmarks across member states, with ECHA REACH compliance governing flame retardant chemistries in foam cores. National regulators including BSI in the United Kingdom and DIBt in Germany enforce reaction-to-fire classification thresholds that directly determine product eligibility for publicly funded retrofit programs. Stakeholders must monitor evolving carbon border adjustment mechanisms and embodied carbon disclosure rules that will increasingly differentiate suppliers based on lifecycle data transparency rather than thermal performance alone.
Market Dynamics
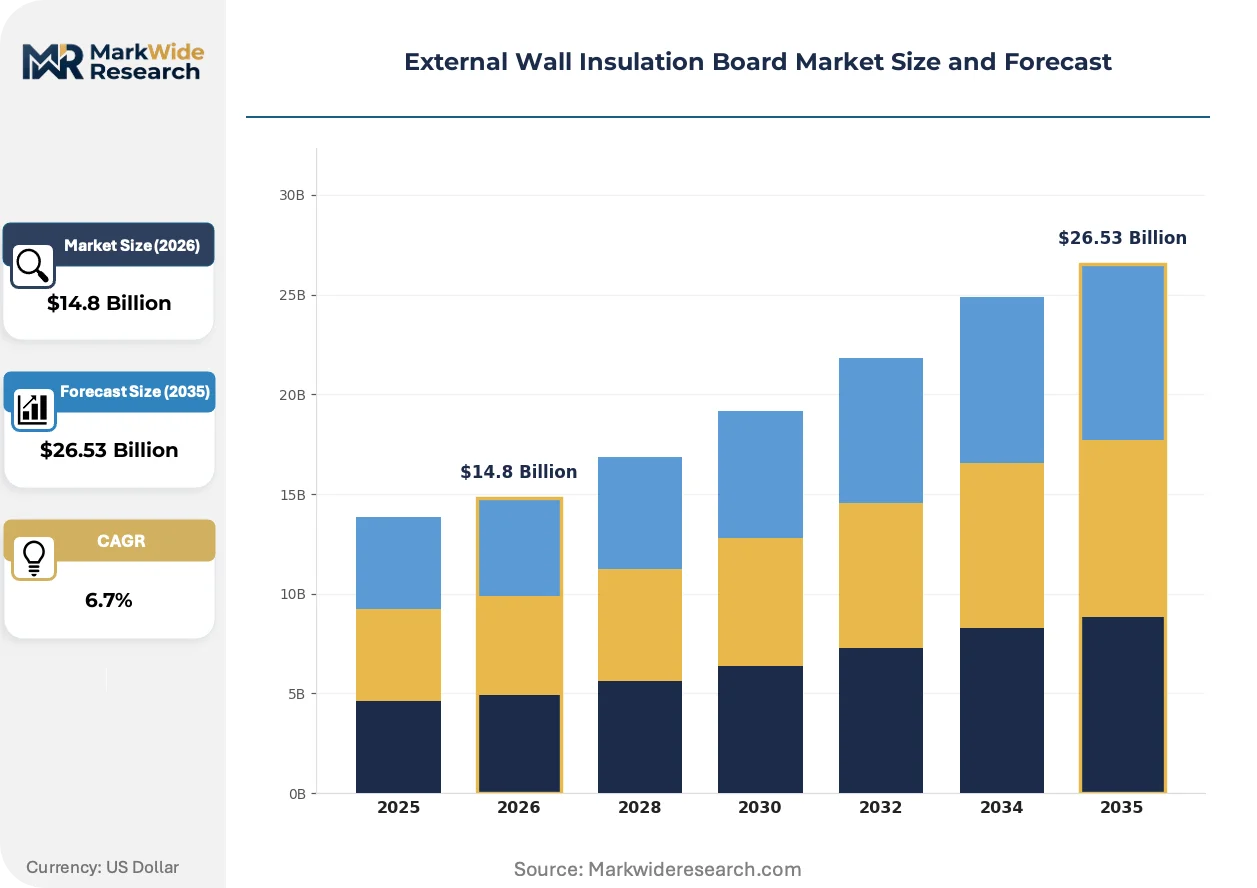
Deep renovation mandates under the EU Green Deal are compressing specification cycles for external wall insulation boards, forcing manufacturers to recertify products against tightening U-value and fire-safety thresholds within shorter windows than historical retrofit programs allowed.
Growth Catalysts
- EU Green Deal renovation wave:Member states must double renovation rates by 2030, channeling public funding toward mineral wool and expanded polystyrene systems in residential retrofits across Germany, France, and Poland.
- Stone wool fire-safety premium:Non-combustible A1-classified boards capture high-rise specifications where national regulators enforce stricter reaction-to-fire standards than mid-rise construction.
- Polyurethane core chemistry:Thinner insulating layers achieve equivalent thermal performance in commercial facade retrofits where floor-area ratios limit envelope thickness.
Market Restraints
- Bitumen and resin input volatility:Mineral wool production depends on petroleum-derived binders and phenolic resins whose price swings compress margin predictability for non-integrated fabricators.
- Carbon border adjustment exposure:Imported foam boards face escalating embodied carbon scrutiny under EU CBAM phase-in, disadvantaging suppliers without verified lifecycle data.
- Mechanical fixing labor scarcity:Rainscreen installation requires certified facade technicians in short supply across Northern European construction markets.
Strategic Opportunities
- Prefabricated panel integration:Factory-assembled facade systems combining insulation, weatherproofing, and cladding reduce on-site labor and accelerate project timelines for commercial developers.
- United Kingdom PAS 2035 compliance:Retrofit coordinator certification requirements create specification pull for whole-building envelope solutions rather than isolated insulation upgrades.
- Recycled glass feedstock:Captive cullet processing from construction waste streams lowers Scope 3 emissions and differentiates mineral wool in public procurement scoring.
Industry Challenges
- CE marking transition complexity:Construction Products Regulation revision demands renewed technical documentation and notified body engagement, stretching smaller fabricators' compliance resources.
- Installer certification bottlenecks:Wet-rendered system application requires trained applicator networks that expand slower than specification growth in France and Poland.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | External Wall Insulation Board Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.53 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polyurethane, Phenolic Foam, Expanded Polystyrene, Mineral Wool, Polyisocyanurate Installation Type: Wet Rendered, Dry Lining, Cladding Panel, Mechanical Fixing End Use Industry: Residential Buildings, Commercial Complexes, Institutional Establishments, Hospitality Venues Board Thickness: 20 mm, 30 mm, 50 mm, 100 mm, 150 mm |
| Companies Covered | Saint-Gobain, Kingspan, Rockwool, BASF, Knauf Insulation, Owens Corning, Johns Manville, Paroc, Dow Building Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
External Wall Insulation Board Market Trends and Innovations
Product chemistry and installation methodology are converging to address the tension between thermal performance targets and embodied carbon accountability, with manufacturers racing to decouple insulation value from petrochemical dependence.
Vacuum insulation panels are miniaturizing envelope thickness requirements for heritage building retrofits where planning restrictions prohibit external protrusion. Conservation architects in Belgium and the Netherlands specify these silica-cored systems for listed facades. The technology is miniaturizing the trade-off between thermal efficiency and architectural preservation that previously favored internal insulation with its condensation risks.
ECHA REACH restrictions on halogenated flame retardants in polystyrene foams are forcing reformulation toward phosphorus-based chemistries or graphite-enhanced grades. German DIBt certification timelines have lengthened as laboratories validate alternative fire-performance pathways. High-rise residential developers in Hamburg and Munich now prioritize mineral wool pending foam board re-approval, redirecting specification flows toward stone wool suppliers with existing A1 classifications.
Public housing authorities are consolidating procurement into multi-year framework agreements with lifecycle carbon clauses. French OPH social landlords and English housing associations now require Environmental Product Declarations for insulation boards, with embodied carbon thresholds written into tender specifications. This behavioral shift favors vertically integrated mineral wool producers with verified supply chain data over foam board importers lacking granular lifecycle transparency.
External Wall Insulation Board Market Segmentation
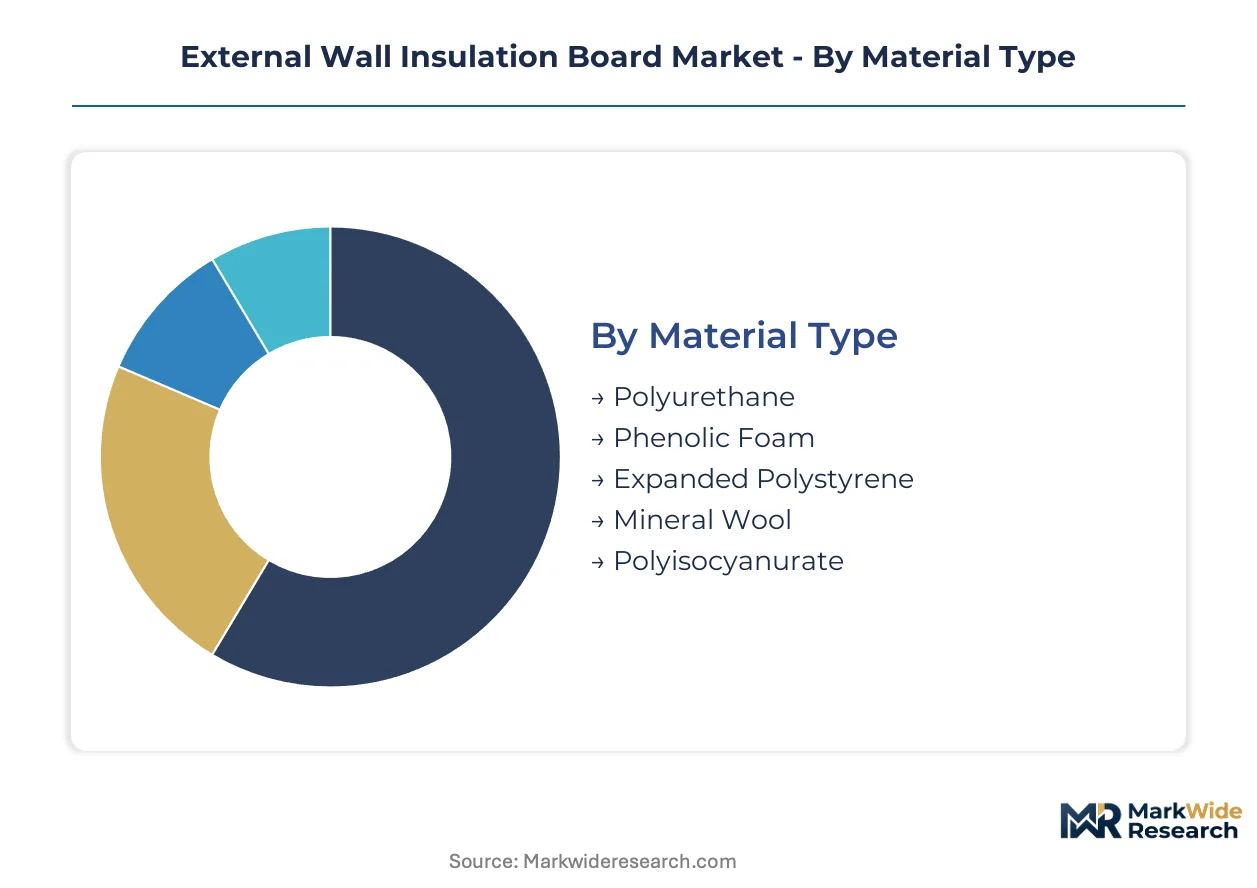
External wall insulation board specification hinges on fire-safety classification, thermal conductivity targets, and installation methodology constraints that vary sharply across building typologies and regulatory jurisdictions. Segmentation reveals where mineral wool's non-combustible advantage clashes with polyurethane's space-efficiency gains, and which thickness thresholds trigger cost-performance trade-offs in deep renovation programs.
Material Type:
Substitution pressure intensifies where ECHA REACH flame-retardant restrictions and national fire codes disqualify incumbent foam chemistries, forcing rapid recertification or material switching.
- Mineral Wool:Stone wool and glass wool boards achieve A1 non-combustible classification under EN 13501-1, dominating high-rise residential specifications in Germany and France where DIBt and national regulators enforce stricter reaction-to-fire standards. German housing associations specify mineral wool for publicly funded retrofits pending foam board re-approval timelines.
- Polyurethane:Closed-cell rigid foam boards deliver thermal conductivities near 0.022 W/mK, enabling thinner envelope assemblies where floor-area ratios constrain external protrusion in commercial facade retrofits across Belgium and the Netherlands. ECHA restrictions on halogenated flame retardants are forcing phosphorus-based reformulation and extended DIBt certification cycles.
- Polyisocyanurate:Thermoset foam core with facer laminates targets commercial rainscreen applications requiring dimensional stability across temperature cycling.
- Expanded Polystyrene:Graphite-enhanced grades compete on cost in residential wet-rendered systems where fire-safety exemptions apply to buildings below specified height thresholds.
- Phenolic Foam:Low-smoke emission characteristics serve transportation-adjacent buildings and tunnels with stringent toxicity requirements under national construction codes.
Mineral wool retains volume leadership across European retrofit programs; polyurethane holds the steepest expansion curve in commercial facade applications where space constraints dominate specification.
Installation Type:
Cost tier differentiation separates labor-intensive traditional methods from capital-intensive prefabricated systems that compress project timelines for commercial developers.
- Wet Rendered:Adhesive bonding with polymer-modified base coat and decorative finish dominates residential retrofits across Northern Europe, particularly in Germany and Poland where established applicator networks support mass-scale public housing programs. Installer certification bottlenecks constrain expansion speed relative to specification growth in France.
- Mechanical Fixing:Stainless steel anchors and rail systems create ventilated rainscreen cavities required for commercial complexes, demanding certified facade technicians in short supply across UK and Scandinavian construction markets.
- Dry Lining:Insulated plasterboard laminates suit internal wall applications where external envelope modification is prohibited by planning restrictions on listed buildings.
- Cladding Panel:Factory-assembled composite systems integrate insulation, weatherproofing, and architectural finish, reducing on-site labor for commercial developers targeting PAS 2035 compliance in UK retrofit coordinator frameworks.
Wet rendered systems command the largest installed base in residential renovation waves; cladding panels are climbing the fastest as prefabrication reduces labor dependency.
End Use Industry:
Volume concentration tracks national renovation program funding flows, with public procurement scoring favoring suppliers with verified lifecycle carbon data.
- Residential Buildings:Deep renovation mandates under EU Green Deal channel subsidies toward mineral wool and expanded polystyrene systems in Germany, France, and Poland, with French OPH social landlords requiring Environmental Product Declarations and embodied carbon thresholds in tender specifications.
- Commercial Complexes:Floor-area ratio constraints and accelerated project timelines drive specification toward polyurethane thin-profile boards and prefabricated panel systems in Belgian and Dutch urban cores.
- Institutional Establishments:Schools and healthcare facilities prioritize A1 fire classification and acoustic damping properties, anchoring mineral wool specification.
- Hospitality Venues:Heritage building constraints in conservation areas of Belgium and the Netherlands drive vacuum insulation panel adoption where external protrusion is prohibited.
Residential buildings retain volume leadership through national renovation wave funding; commercial complexes are gaining share fastest where space constraints and timeline pressure converge.
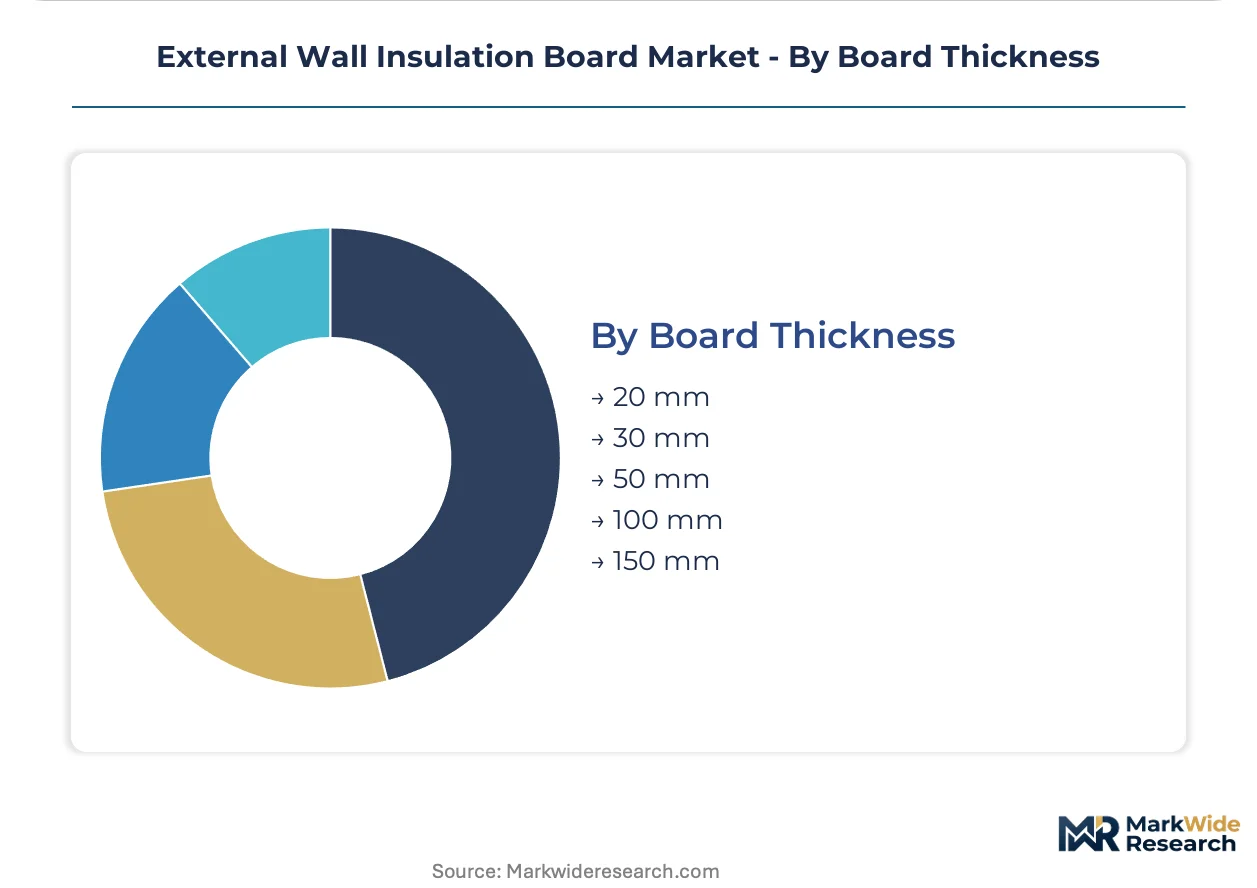
Board Thickness:
Thickness selection crystallizes the trade-off between thermal performance targets and embodied carbon accountability, with regulatory U-value compression pushing specifications toward higher thickness tiers.
- 100 mm:Standard specification for residential deep renovation achieving compliance with tightening Energy Performance of Buildings Directive U-value benchmarks across German and Polish retrofit programs.
- 150 mm:Premium tier for near-zero energy building standards in new construction and aggressive retrofit targets, facing embodied carbon scrutiny under emerging lifecycle disclosure rules.
- 50 mm:Limited to internal insulation applications or heritage buildings where external modification is restricted.
- 30 mm:Vacuum insulation panel territory for space-constrained commercial retrofits in Belgian and Dutch conservation zones.
- 20 mm:Niche applications in window reveal detailing and thermal bridge mitigation.
100 mm boards retain volume leadership in standard residential retrofit; 150 mm specifications are expanding most quickly as near-zero energy standards tighten across member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Poland and Romania demonstrate acute price sensitivity amid subsidy-dependent retrofit programs, while Dutch and Belgian commercial developers prioritize thin-profile performance over unit cost in dense urban cores.
Germany
German housing associations drive mineral wool volumes through KfW-funded deep renovation programs targeting 55 kWh/m²a consumption thresholds. DIBt certification delays for reformulated foam boards redirect public procurement toward stone wool suppliers with existing A1 classifications. The Rhine-Ruhr metropolitan corridor concentrates installer networks for wet-rendered systems.
France
French OPH social landlords consolidate multi-year framework agreements requiring Environmental Product Declarations with embodied carbon scoring. ANAH renovation subsidies channel specification toward whole-building envelope solutions rather than isolated insulation upgrades. The Paris metropolitan area generates concentrated demand for heritage-compatible vacuum insulation panels.
United Kingdom
UK housing associations mandate PAS 2035 retrofit coordinator certification, creating specification pull for integrated facade systems over component-level insulation. BSI reaction-to-fire classifications determine product eligibility for publicly funded programs. Greater Manchester and West Midlands clusters face certified facade technician shortages for rainscreen installations.
Poland
Polish residential retrofit programs prioritize expanded polystyrene cost efficiency in mass-scale public housing renovations. National Energy and Climate Plan subsidies compress specification cycles toward rapid compliance solutions. Warsaw and Kraków metropolitan areas concentrate wet-rendered applicator networks expanding slower than program scale.
Netherlands
Dutch commercial developers specify polyurethane thin-profile boards where floor-area ratios prohibit external envelope protrusion in Amsterdam and Rotterdam urban cores. Conservation area planning restrictions accelerate vacuum insulation panel adoption for listed facade retrofits. National carbon disclosure requirements favor suppliers with verified lifecycle data transparency.
External Wall Insulation Board Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive raw material control separating margin-stable incumbents from input-price-exposed fabricators. The upper tier commands specification through fire-safety certification depth and vertical integration into glass melting or resin chemistry. Mid-scale specialists compete on installation system integration and regional applicator network density. Capacity expansion and prefabricated panel system development represent the dominant competitive moves.
Among European-integrated material producers, Saint-Gobain, Rockwool, and Kingspan occupy distinct archetype positions. Saint-Gobain exemplifies the captive-supply model with in-house glass-melting infrastructure. Rockwool anchors the non-combustible specialization vector through stone wool chemistry. Kingspan represents the system-integration approach combining core innovation with prefabricated facade assembly. These three illustrate how thermal performance competition has bifurcated between raw-material control and installation-methodology integration.
| Leading Market Players |
|---|
| Saint-Gobain |
| Kingspan |
| Rockwool |
| BASF |
| Knauf Insulation |
| Owens Corning |
| Johns Manville |
| Paroc |
| Dow Building Solutions |
| Others |
Pricing and Supply Chain Analysis
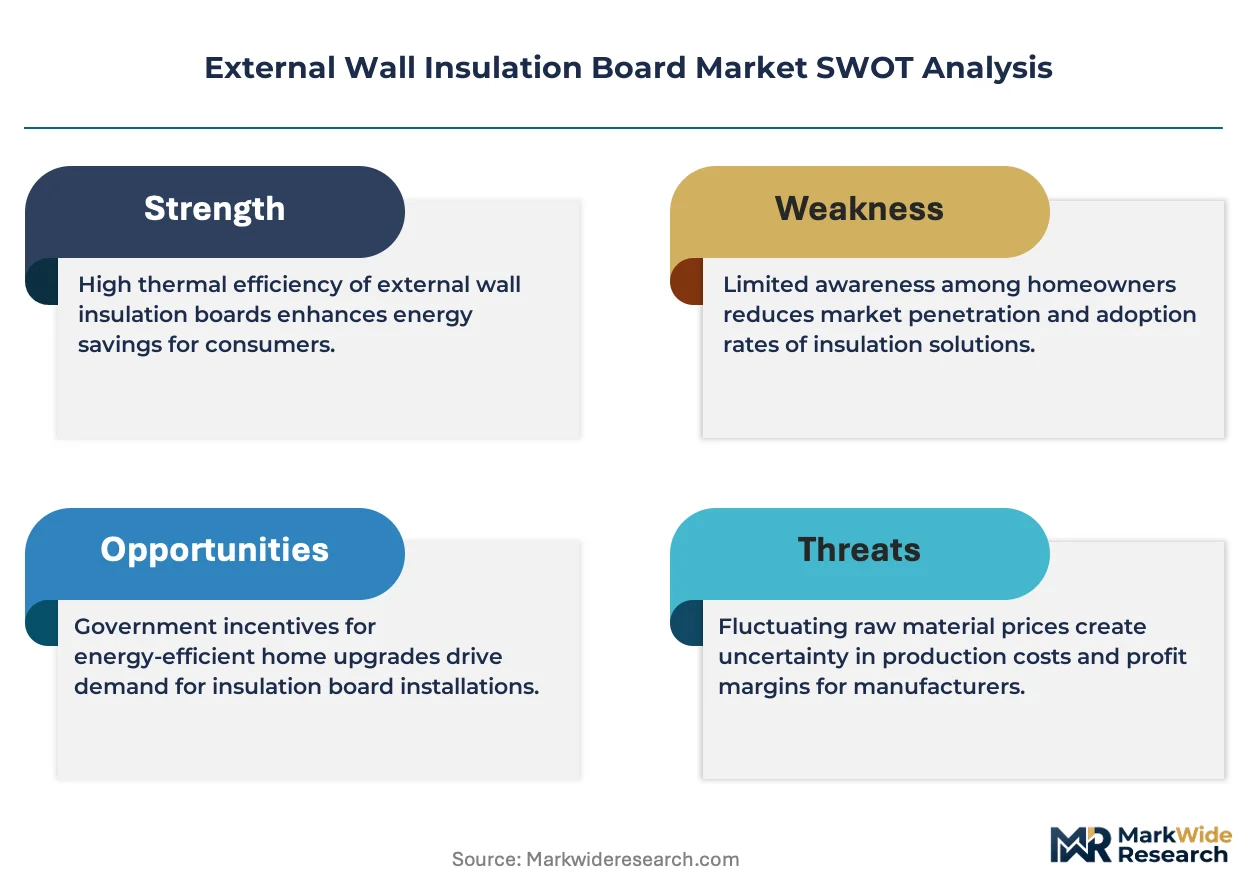
Captive glass-melting capacity at integrated mineral wool producers anchors cost floors that non-integrated foam board fabricators cannot match, concentrating pricing power among vertically controlled suppliers serving German and French public housing retrofits. Scale economies in binder chemistry and cullet processing translate directly into bid competitiveness for EU Green Deal-funded programs, where lifecycle carbon scoring increasingly separates winners from price-takers.
Pricing Analysis
After-sales service revenue from certified installer networks and extended warranty programs drives lifetime value for wet-rendered system suppliers. Three-tier pricing structure across premium, standard, and economy levels separates A1-classified stone wool from graphite-enhanced polystyrene and unmodified foam grades. Price differentiation rests on fire-safety certification depth and DIBt approval status. Cost compression in mid-tier expanded polystyrene is intensifying because Polish and Romanian housing authorities prioritize rapid compliance over performance premiums. Polish public procurement shows acute price sensitivity; Dutch commercial developers exhibit lowest sensitivity where floor-area ratios constrain envelope thickness.
Supply Chain Analysis
Just-in-time binder delivery from petrochemical suppliers dominates mineral wool production, though strategic stockpiling of recycled glass cullet is expanding among producers with captive construction waste processing. Manufacturing concentrates in Germany, France, and Poland, with Belgium and the Netherlands serving as distribution hubs for thin-profile polyurethane imports. Raw material dependencies include phenolic resins, bitumen binders, and flame-retardant chemistries governed by ECHA REACH restrictions. Single-source vulnerability in halogenated flame-retardant supply chains is forcing reformulation toward phosphorus-based alternatives. Distribution runs through certified applicator networks for wet-rendered systems and facade technician pools for mechanical fixing installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated French OPH social landlords and English housing associations, whose multi-year framework agreements with embodied carbon clauses are squeezing smaller fabricators lacking verified lifecycle data.
For Market Incumbents: Consolidate backward integration into recycled glass feedstock and captive resin chemistry to defend margin stability against petroleum-derived input volatility. Deepen certification investment for DIBt and BSI reaction-to-fire re-approval timelines ahead of foam board competitors. Prioritize prefabricated panel system development to capture PAS 2035 retrofit coordinator specification pull in the United Kingdom. For New Entrants and Emerging Players: Anchor in vacuum insulation panel heritage retrofit applications where Belgian and Dutch conservation restrictions prohibit external protrusion and incumbent mineral wool suppliers lack miniaturized product portfolios. Target Polish expanded polystyrene residential retrofits where rapid program scale has outpaced certified applicator network expansion. Pursue go-to-market partnerships with wet-rendered system distributors seeking alternative fire-safe chemistries pending ECHA REACH compliance. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated facade system providers with captive installer certification programs and multi-year public housing maintenance contracts. Long-term viability across the analysis window favors vertically controlled mineral wool producers with verified Scope 3 emissions data over foam board importers exposed to EU carbon border adjustment phase-in. Target acquisition archetypes include regional wet-rendered system specialists with dense applicator networks in France and Poland. The signal to watch is DIBt certification timeline compression for reformulated polyurethane boards, which would redirect specification flows and revalue incumbent mineral wool positions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Glass Feedstock | Lowers Scope 3 emissions and improves scoring in French OPH tender evaluations with embodied carbon clauses. |
| Prefabricated Panel System Development | Reduces on-site labor dependency and accelerates project timelines for UK PAS 2035 retrofit coordinator frameworks. |
| DIBt Certification Investment for Reformulated Chemistries | Secures product eligibility for German publicly funded retrofits pending foam board re-approval timelines. |
| Certified Installer Network Expansion | Addresses labor scarcity bottlenecks constraining wet-rendered system growth in France and Poland. |
| Environmental Product Declaration Investment | Meets mandatory disclosure requirements for English housing association and French social landlord procurement. |
Research Methodology
Cross-validation between primary interviews with installation system distributors, facade contractor operations managers, and public housing procurement officers anchors the qualitative findings against secondary validation from EU Green Deal policy documentation, ECHA REACH regulatory filings, and national energy agency retrofit program disclosures. Bottom-up demand modeling from construction permit data and top-down macroeconomic triangulation ensure segmentation coherence across material type, installation methodology, and end-use industry dimensions.
Sensitivity analysis across the projection horizon tests forecast robustness against renovation rate acceleration scenarios and carbon border adjustment phase-in timing. Segmentation dimensions modeled include fire-safety classification tier, thermal conductivity target, board thickness specification, and national regulatory framework cluster. CAGRs derive from regression analysis against historical retrofit program deployment rates and projected Energy Performance of Buildings Directive compliance deadlines. Industry-specific forecast inputs include KfW subsidy allocation trajectories and ANAH renovation wave funding commitments.
Decision-makers should treat outputs as directional under assumptions of continued EU Green Deal funding continuity and stable ECHA REACH regulatory timelines; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding installer certification network expansion speed and DIBt laboratory validation capacity. Revision becomes warranted when halogenated flame-retardant restriction implementation crosses enforcement thresholds or when carbon border adjustment mechanism coverage expands to embodied construction materials.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Concrete Protective Liners Market
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
Artificial Wood Beams Market