
 Building Automation and Control System Market | 2026-2036
Building Automation and Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Building Automation and Control System Market Analysis
Healthcare facility modernization is repositioning procurement priorities toward infection-control-grade air handling and real-time environmental monitoring. Johnson Controls International plc leverages its vertical integration across chillers, controls, and software to capture hospital retrofit contracts. Siemens AG sustains engineering intensity through its Desigo platform architecture. Honeywell International Inc. anchors North American presence via deep channel relationships with mechanical contractors.
Building automation and control systems comprise networked sensors, actuators, controllers, and software platforms that regulate HVAC, lighting, security, and energy consumption across built environments. BACnet protocol stacks enable interoperability across multi-vendor device ecosystems, while edge computing nodes process occupancy and thermal load data within milliseconds to optimize setpoints. HVAC Control commands the largest installed base and replacement revenue pool, though Energy Management solutions are expanding fastest as utility rate structures penalize peak demand. Cloud-Based Solutions are displacing on-premise deployments in mid-market commercial buildings where IT staffing constraints limit local server maintenance.
The EU Green Deal and F-Gas Regulation are mandating refrigerant phase-downs and building performance certificates that force automation upgrades. The EPA's ENERGY STAR program and ASHRAE Standard 90.1 establish minimum efficiency thresholds that filter non-compliant control vendors from federal and utility-rebate-funded projects. Stakeholders must monitor convergence between cybersecurity frameworks and operational technology networks as building systems integrate with enterprise IT infrastructure.
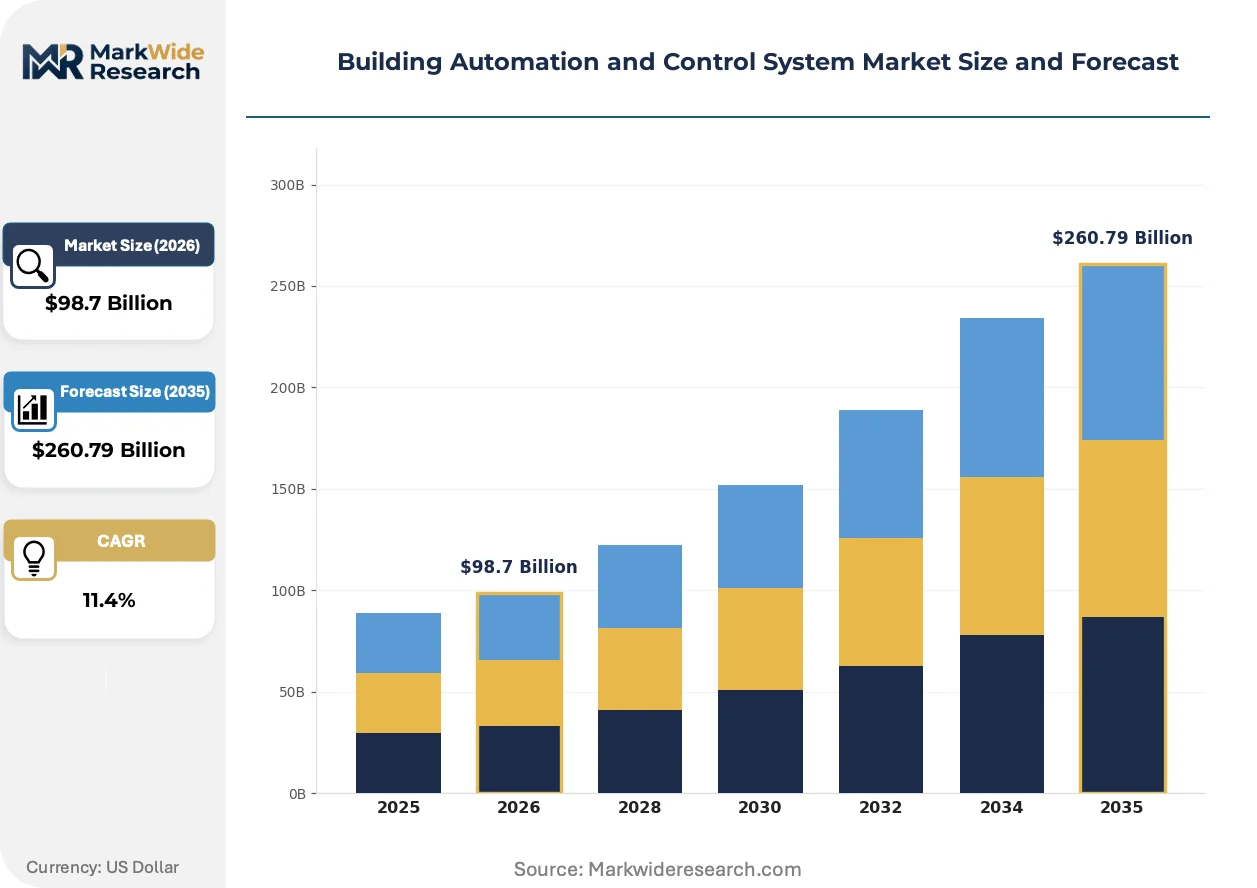
Market Dynamics
Retrofit cycles in aging commercial buildings are converging with refrigerant phase-down mandates under the EU F-Gas Regulation, forcing simultaneous HVAC replacement and control system upgrades that compress procurement timelines and expand contract values.
Growth Catalysts
- EU Green Deal building performance certificates:Mandatory energy disclosure requirements in Germany, France, and the Netherlands are accelerating automation retrofits in Class B and C office stock.
- Healthcare infection-control standards:Post-pandemic hospital construction specifications now require real-time air quality monitoring and pressure differential control, expanding addressable market for environmental sensors.
- Edge computing latency requirements:Sub-100-millisecond response times for occupancy-based setpoint adjustment are pulling compute resources from cloud to on-premise controllers.
Market Restraints
- Semiconductor supply concentration:Taiwan and South Korea dominate microcontroller and power electronics fabrication, exposing control hardware vendors to geographic disruption risk.
- Cybersecurity compliance fragmentation:Divergent national standards for operational technology network security create certification overhead for multi-country deployments.
- Copper and rare earth price volatility:Permanent magnet motors and wiring harnesses face input cost pressure that squeezes hardware margins.
Strategic Opportunities
- India smart city infrastructure:Municipal building energy management tenders under the country's national urban mission create concentrated demand for integrated control platforms.
- Data center liquid cooling integration:Convergence of building automation with IT infrastructure management systems opens cross-selling pathways for thermal optimization software.
- Utility demand response incentives:FERC Order 2222 and state-level virtual power plant programs in the United States monetize automated load flexibility.
Industry Challenges
- BACnet/IT network segmentation expertise:Scarce talent capable of configuring secure protocol gateways between operational technology and enterprise systems extends commissioning timelines.
- ASHRAE 90.1 certification documentation:Compliance verification for federal and utility rebate eligibility requires specialized energy modeling and submission workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building Automation and Control System Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $260.79 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HVAC Control, Lighting Control, Security Control, Energy Management Technology: BACnet, LonWorks, Modbus, KNX End User: Commercial Buildings, Residential Buildings, Industrial Facilities, Educational Institutions Solution: Monitoring Systems, Integration Services, Cloud-Based Solutions, On-Premise Solutions |
| Companies Covered | Johnson Controls International plc, Emerson Electric Co., Siemens AG, Carrier Global Corporation, Delta Electronics, Inc., Schneider Electric SE, ABB Ltd, Rockwell Automation, Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building Automation and Control System Market Emerging Trajectories
Digital twin technology is compressing commissioning cycles and enabling predictive maintenance contracts that shift vendor revenue from equipment sales to recurring software fees.
Machine learning inference at the controller level is automating fault detection and diagnostic sequences that previously required manual engineering review. Large commercial real estate operators in the United States are deploying these capabilities across multi-building portfolios to reduce technician dispatch frequency. The shift is compressing service contract margins for traditional mechanical contractors while expanding addressable market for analytics software vendors.
The EU F-Gas Regulation's refrigerant phase-down schedule is mandating heat pump retrofits that require compatible control system replacements. Building owners in Germany and France face simultaneous HVAC and automation procurement decisions that favor integrated platform vendors over component specialists. The regulatory pressure is consolidating specification authority around mechanical contractors with turnkey service capabilities.
Facility managers are consolidating vendor relationships around single-platform contracts that bundle hardware, software, and maintenance under unified service level agreements. The purchasing pattern displaces point-solution procurement through independent controls distributors in the mid-market commercial segment. This concentration is most visible in United States suburban office and retail properties where capital constraints limit in-house engineering staff.
Building Automation and Control System Market Segmentation
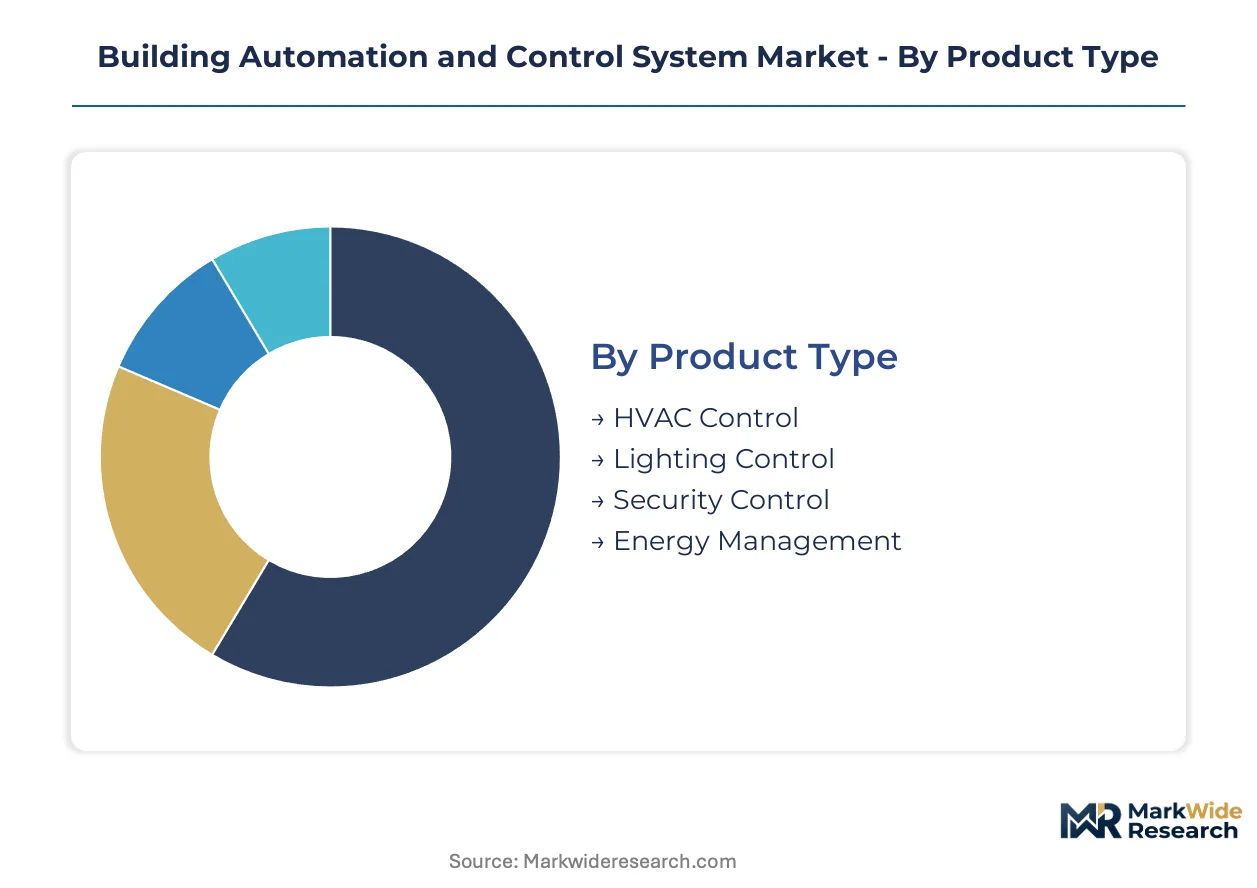
Building automation and control systems fragment across integration depths that determine procurement complexity and vendor selection criteria. Standalone point solutions serve budget-constrained retrofits while embedded platform architectures dominate new construction specifications requiring unified service level agreements.
Product Type:
Integration depth varies sharply: HVAC and lighting controls embed directly into mechanical infrastructure, while security and energy management layers operate as overlay systems requiring protocol gateways.
- HVAC Control:Chiller sequencing, variable air volume modulation, and refrigerant monitoring functions anchor the largest installed base. Demand concentrates in German hospital retrofits where F-Gas Regulation mandates simultaneous equipment and control replacement cycles.
- Lighting Control:Daylight harvesting algorithms and occupancy-based dimming circuits reduce electrical loads in United States commercial office portfolios. Building owners in California and New York prioritize these systems for utility rebate eligibility under state energy efficiency programs.
- Security Control:Access credentialing and video analytics platforms.
- Energy Management:Sub-metering aggregation and demand response automation.
HVAC Control leads volumes today; Energy Management is gaining share fastest.
Technology:
Protocol selection dictates interoperability scope and vendor lock-in risk across multi-generation building portfolios.
- BACnet:ASHRAE-standardized object models enable multi-vendor device discovery across HVAC, lighting, and fire safety networks. Specification authority in United States federal buildings and military installations mandates BACnet compliance for procurement eligibility.
- KNX:Twisted-pair and powerline carrier configurations dominate European residential and light commercial installations. German integrators specify KNX for multi-family housing developments requiring centralized visualization of heating and shutter control.
- LonWorks:Neuron chip-based networking for legacy industrial and transportation infrastructure.
- Modbus:Serial and TCP/IP variants serving cost-sensitive industrial retrofit applications.
BACnet commands the largest specification footprint; KNX is expanding most quickly in residential adjacencies.
End User:
Building typology determines sensor density, response latency requirements, and cybersecurity posture.
- Commercial Buildings:Class A office towers and retail complexes deploy integrated platforms unifying HVAC, lighting, and access control under single-pane management. Operators in United States suburban office markets consolidate vendor relationships to reduce commissioning overhead.
- Industrial Facilities:Manufacturing plants and warehouses require ruggedized controllers tolerating temperature extremes and electromagnetic interference. Food processing installations in France specify stainless steel enclosures and washdown-rated sensors for regulatory compliance.
- Residential Buildings:Multi-family and single-family smart home deployments.
- Educational Institutions:K-12 and university campuses with deferred maintenance backlogs.
Commercial Buildings anchor current procurement volumes; Industrial Facilities show the steepest expansion trajectory.
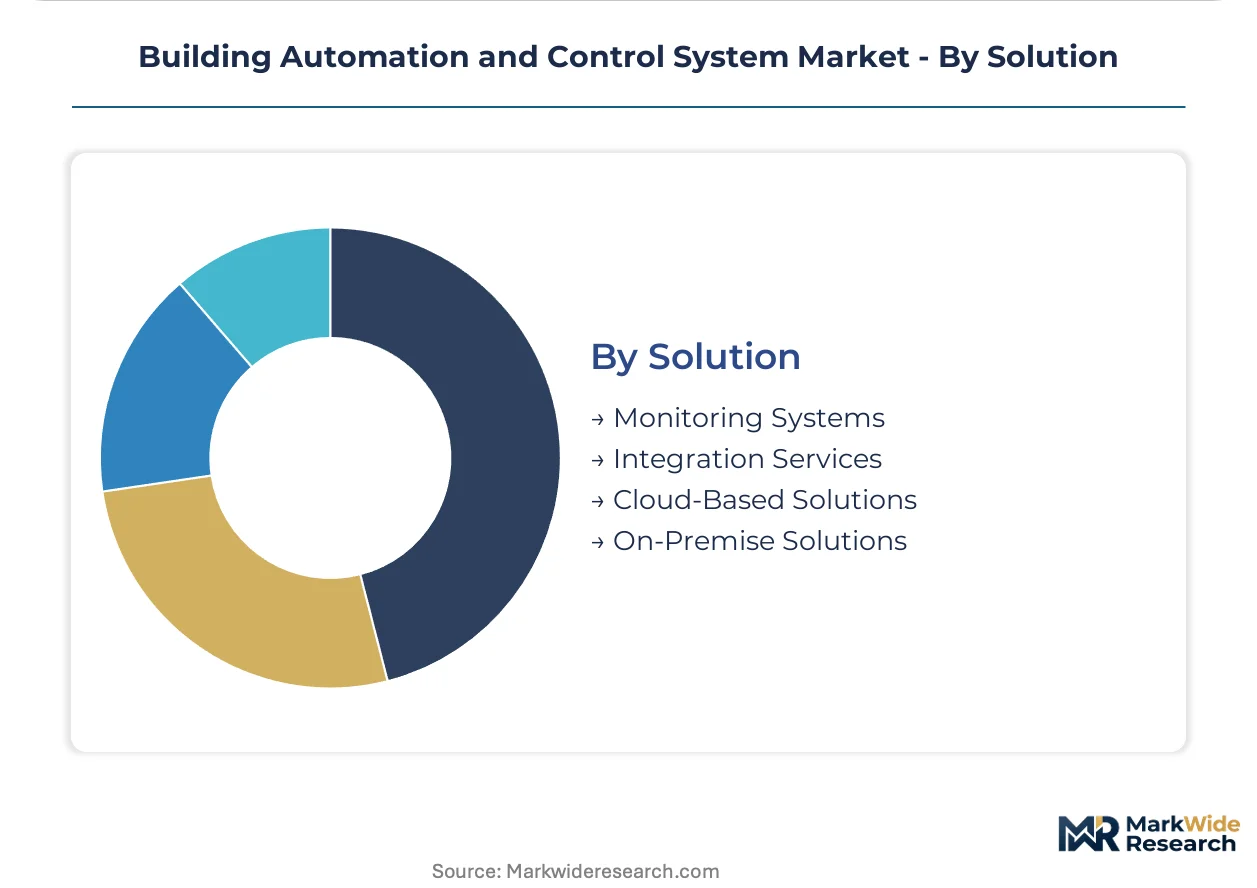
Solution:
Deployment architecture determines capital intensity, recurring revenue potential, and IT staffing requirements.
- Cloud-Based Solutions:Browser-accessible dashboards and API integrations enable remote portfolio management without on-premise server maintenance. Mid-market United States property managers adopt these platforms to overcome constrained engineering headcount.
- Integration Services:Protocol gateway configuration and legacy system migration projects. System integrators in China bundle these services with hardware procurement for municipal smart building tenders under national urban development initiatives.
- Monitoring Systems:Sensor networks and alarm aggregation platforms.
- On-Premise Solutions:Local server installations for latency-sensitive or air-gapped environments.
Integration Services dominate contract values today; Cloud-Based Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage around refrigerant phase-down timelines and energy disclosure mandates is redirecting procurement investment toward jurisdictions with the most stringent enforcement mechanisms. Manufacturers and system integrators are establishing regional engineering centers to capture retrofit contracts tied to compliance deadlines.
United States
FERC Order 2222 and state-level virtual power plant programs are monetizing automated load flexibility for commercial building operators. The EPA's ENERGY STAR program and ASHRAE Standard 90.1 establish minimum efficiency thresholds that filter non-compliant control vendors from federal and utility-rebate-funded projects. Building owners in California and New York prioritize lighting control systems for utility rebate eligibility under state energy efficiency programs.
Germany
The EU F-Gas Regulation's refrigerant phase-down schedule is mandating heat pump retrofits that require compatible control system replacements. Building performance certificates under the EU Green Deal are accelerating automation retrofits in Class B and C office stock. Hospital operators in Berlin and Munich face simultaneous HVAC and automation procurement decisions that favor integrated platform vendors.
China
Municipal building energy management tenders under the national smart city urban mission create concentrated demand for integrated control platforms. The country's dual carbon goals tighten energy efficiency mandates for new construction and major retrofits. System integrators in Shanghai and Beijing bundle protocol gateway configuration services with hardware procurement for municipal smart building tenders.
India
The national urban mission is generating municipal building energy management tenders that concentrate demand for integrated control platforms. Central Electricity Authority regulations are tightening commercial building energy consumption standards. Smart city infrastructure projects in Mumbai and Delhi-NCR are deploying networked sensor and actuator systems for HVAC and lighting optimization.
France
EU Green Deal building performance certificates mandate energy disclosure requirements that accelerate automation retrofits. The F-Gas Regulation forces simultaneous HVAC replacement and control system upgrades in aging commercial buildings. Food processing installations in Lyon specify stainless steel enclosures and washdown-rated sensors for regulatory compliance.
Building Automation and Control System Market Vendor Landscape
Platform consolidation dominates the current landscape as vendors bundle hardware, software, and maintenance under unified service level agreements. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with captive HVAC equipment production, pure-play controls specialists with deep protocol expertise, and IT infrastructure vendors extending into operational technology networks. M&A activity and vertical integration into chiller and sensor manufacturing represent the dominant competitive moves.
Within the diversified industrial tier, Johnson Controls International plc, Siemens AG, and Honeywell International Inc. exemplify platform-scale positioning. These entities leverage engineering intensity across mechanical equipment and software layers to capture turnkey retrofit contracts. Their geographic footprints span multiple regulatory jurisdictions, enabling standardized product architectures with localized compliance certification.
| Leading Market Players |
|---|
| Johnson Controls International plc |
| Emerson Electric Co. |
| Siemens AG |
| Carrier Global Corporation |
| Delta Electronics, Inc. |
| Schneider Electric SE |
| ABB Ltd |
| Rockwell Automation, Inc. |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up controls distributors in the United States Midwest and German family-owned sensor manufacturers both extract pricing power through captive relationships with mechanical contractors, compressing margin transparency for end users while insulating integrated platform vendors from commodity input volatility.
Pricing Analysis
Distributor margin layers in the mid-market commercial segment typically capture 15-25 points before mechanical contractor markups, though direct-to-OEM procurement by hospital systems and data center operators compresses this stack. Pricing stratifies across premium BACnet-certified controllers, standard KNX-compatible devices, and economy-tier Modbus retrofit kits differentiated by warranty length and cloud connectivity bundling. Cost compression in the economy tier is intensifying because Taiwanese microcontroller supply constraints force hardware vendors to absorb input volatility or sacrifice volume. Healthcare facility buyers exhibit the lowest price sensitivity given infection-control compliance mandates, while suburban office property managers prioritize capital expenditure minimization over lifecycle operating cost.
Supply Chain Analysis
Certification gating through BACnet Testing Laboratories and UL 916 energy management equipment listings restricts qualified supplier pools to vendors with sustained engineering investment in protocol compliance documentation. Hardware fabrication concentrates in China for cost-optimized controllers, Germany for precision actuators and sensors, and Taiwan for edge-computing microcontrollers and power electronics. Copper windings for motor drives, rare earth elements for permanent magnet actuators, and silicon carbide substrates for power conversion modules constitute critical input dependencies. Single-source vulnerability around TSMC-fabricated Neuron chips for LonWorks legacy networks exposes long-tail maintenance contracts to geographic disruption risk. Distribution runs through authorized systems integrators in Europe and North America, direct municipal procurement channels in China and India, and electrical wholesale distributors in fragmented Middle Eastern and Southeast Asian markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
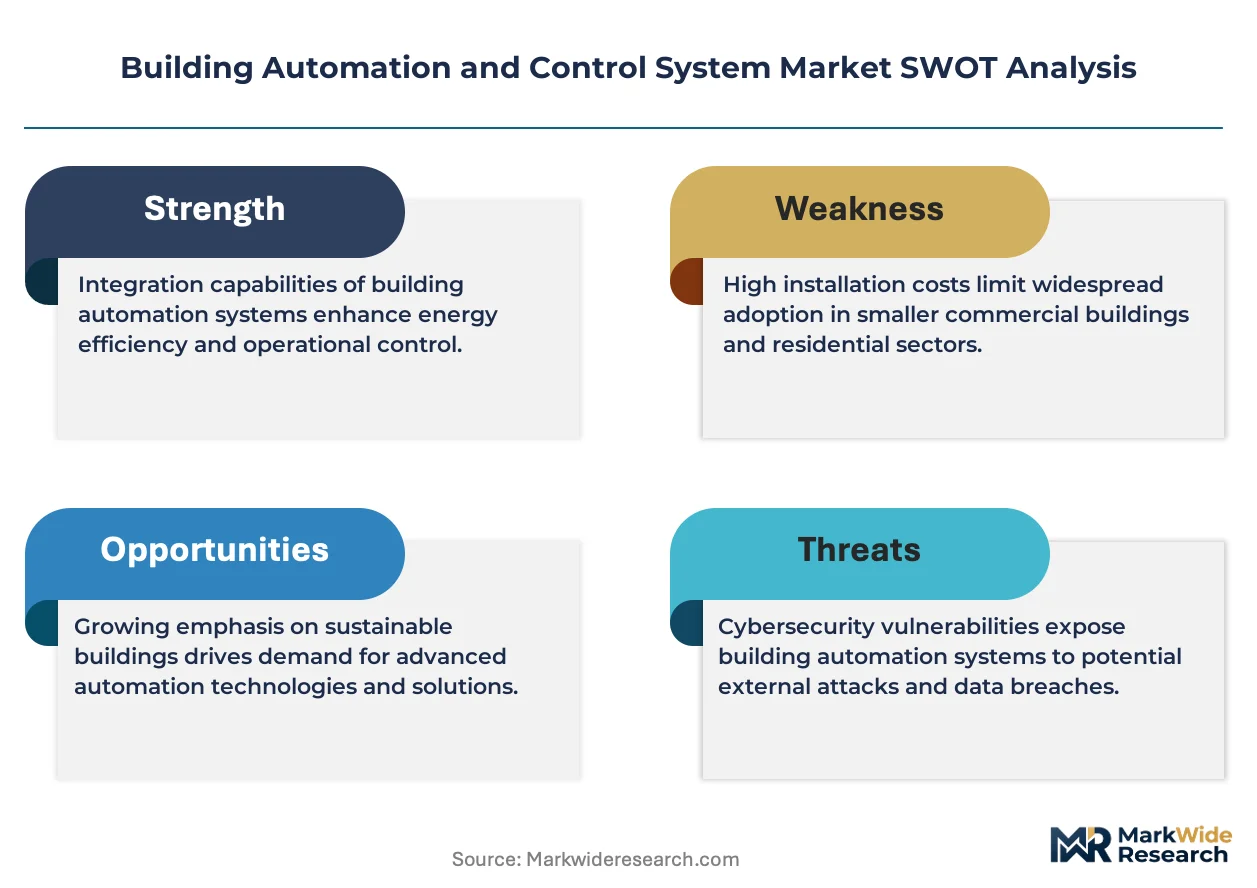
Margin expansion in building automation hinges on software recurring revenue displacing hardware transactional sales, with cloud-based energy management platforms capturing annual contract value multiples of traditional equipment procurement.
For Market Incumbents: Extend platform consolidation momentum by bundling HVAC equipment, controls hardware, and predictive maintenance software under unified service level agreements that lock out component specialists. Defend against pure-play analytics vendors by deepening backward integration into sensor manufacturing and edge-computing hardware. Prioritize certification investment in EU cybersecurity frameworks for operational technology networks ahead of enforcement deadlines. For New Entrants and Emerging Players: Enter via white-space opportunities in India municipal smart city tenders and United States data center liquid cooling integration projects where incumbent platform coverage remains thin. Target mid-market commercial building operators in secondary United States metropolitan areas with cloud-native deployment models that eliminate on-premise server maintenance burdens. Pursue channel partnerships with electrical contractors rather than mechanical specialists to bypass established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among regional systems integrators with BACnet protocol expertise and municipal procurement relationships in Germany, France, and China. Long-term viability favors acquisition targets with recurring software revenue above 40 percent of total contract value and demonstrated cross-selling capability from controls into adjacent energy management or security applications. Monitor FERC Order 2222 implementation velocity and state-level virtual power plant program enrollment as demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies HVAC, lighting, and security under single-pane management, displacing point-solution procurement. |
| Backward Integration into Sensor Manufacturing | Captures margin pool from semiconductor supply concentration and accelerates product development cycles. |
| Cloud-Native Deployment Launch | Targets mid-market buyers with constrained IT staffing through browser-accessible dashboards. |
| Strategic Partnership with Mechanical Contractors | Secures specification authority in EU F-Gas-mandated retrofit cycles and hospital modernization projects. |
| Certification Investment in Cybersecurity Frameworks | Enables procurement eligibility in United States federal buildings and EU critical infrastructure mandates. |
Methodological Framework
Bottom-up building typology modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with controls engineering directors, mechanical contractor procurement leads, facility management executives at commercial real estate investment trusts, and municipal smart city program officers were validated against secondary sources including ASHRAE Standard 90.1 compliance documentation, EPA ENERGY STAR certification databases, EU F-Gas Regulation implementation reports, and SEC filings from publicly traded building automation vendors. Triangulation between installation volume estimates and equipment revenue disclosures isolates pricing and margin structure assumptions.
Input-output matrices map HVAC control, lighting control, security control, and energy management demand against BACnet, KNX, LonWorks, and Modbus protocol supply across commercial, industrial, residential, and educational end-use categories. CAGRs derive from regression analysis of historical retrofit cycle timing, regulatory compliance deadline clustering, and utility incentive program budget trajectories. Forecast inputs incorporate edge-computing latency requirements for occupancy-based setpoint adjustment, refrigerant phase-down schedules under the EU F-Gas Regulation, and semiconductor foundry capacity allocation patterns across the projection horizon.
Inputs from ASHRAE technical committees and EU regulatory consultation documents were available through the study window; gaps in real-time municipal tender award data from India and China introduce uncertainty bands around geographic demand allocation. Forecasts reflect documented assumptions regarding compliance enforcement intensity and technology substitution elasticities. A model refresh is warranted upon material change in FERC Order 2222 implementation velocity or Taiwan semiconductor export restriction scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Automation Systems
Commercial Building Automation Systems Market
Building Automation Systems
China Revolving Doors Market
Building Automation Systems
Smart Window Film Market
Building Automation Systems
Tunnel Automation Market
Building Automation Systems
Building Analytics Market
Building Automation Systems
Automated Infrastructure Management (AIM) Solutions Market
Building Automation Systems
US Commercial Building Automation Market
Building Automation Systems
Building Information Management System Market
Building Automation Systems
Global Platform Screen Doors for Subway Lines Market
Building Automation Systems
Europe Building Automation Systems Market
Building Automation Systems
Building Automation System Market
Building Automation Systems
Global HVAC Controls Market
Building Automation Systems
Elevator Modernization Market
Building Automation Systems
Computer-Aided Facility Management (CAFM) Market
Building Automation Systems
Building-To-Grid Technology Market
Building Automation Systems
Global Door Closers Market