
 Roof Cladding Market | 2026-2036
Roof Cladding Market Size, Share, and Industry Trends Forecast 2026-2036
Roof Cladding Market Analysis
Modular panel-and-insulation bundling is restructuring buyer choice across commercial and industrial procurement channels. Kingspan Group leverages its integrated insulated panel architecture to dominate specification-driven projects in cold-storage and logistics facilities. Atas International, Inc. competes through specialized standing-seam metal systems engineered for high-wind zones. Firestone Building Products anchors its position via membrane-to-cladding crossover solutions that bridge traditional roofing and advanced envelope performance.
Roof cladding encompasses the weatherproof outer layer installed over roof structures, typically fabricated from metal alloys, mineral composites, or bituminous materials with specified fire-resistance ratings and thermal conductivity coefficients below 0.25 W/m·K, functioning primarily to prevent moisture ingress while managing building energy loads. Metal panels currently occupy the largest installed base across industrial applications, while membrane systems represent the fastest-growing installation method as single-ply TPO and PVC technologies displace built-up roofing in commercial re-roofing cycles. Agricultural applications remain the most price-sensitive segment, with asphalt shingles retaining volume leadership in residential retrofits despite metal's inroads in new construction.
EMA's Construction Products Regulation and the EU Green Deal's embodied carbon thresholds are tightening compliance burdens for imported mineral wool and steel substrates across European markets. REACH chemical restrictions on certain flame retardants are simultaneously forcing reformulation of coating systems used in metal cladding finishes. OSHA fall-protection mandates during installation influence contractor preference for lighter panel systems that reduce rooftop exposure time. Stakeholders must monitor how evolving lifecycle assessment requirements alter material substitution patterns between metal, asphalt, and emerging bio-based alternatives.
Market Dynamics
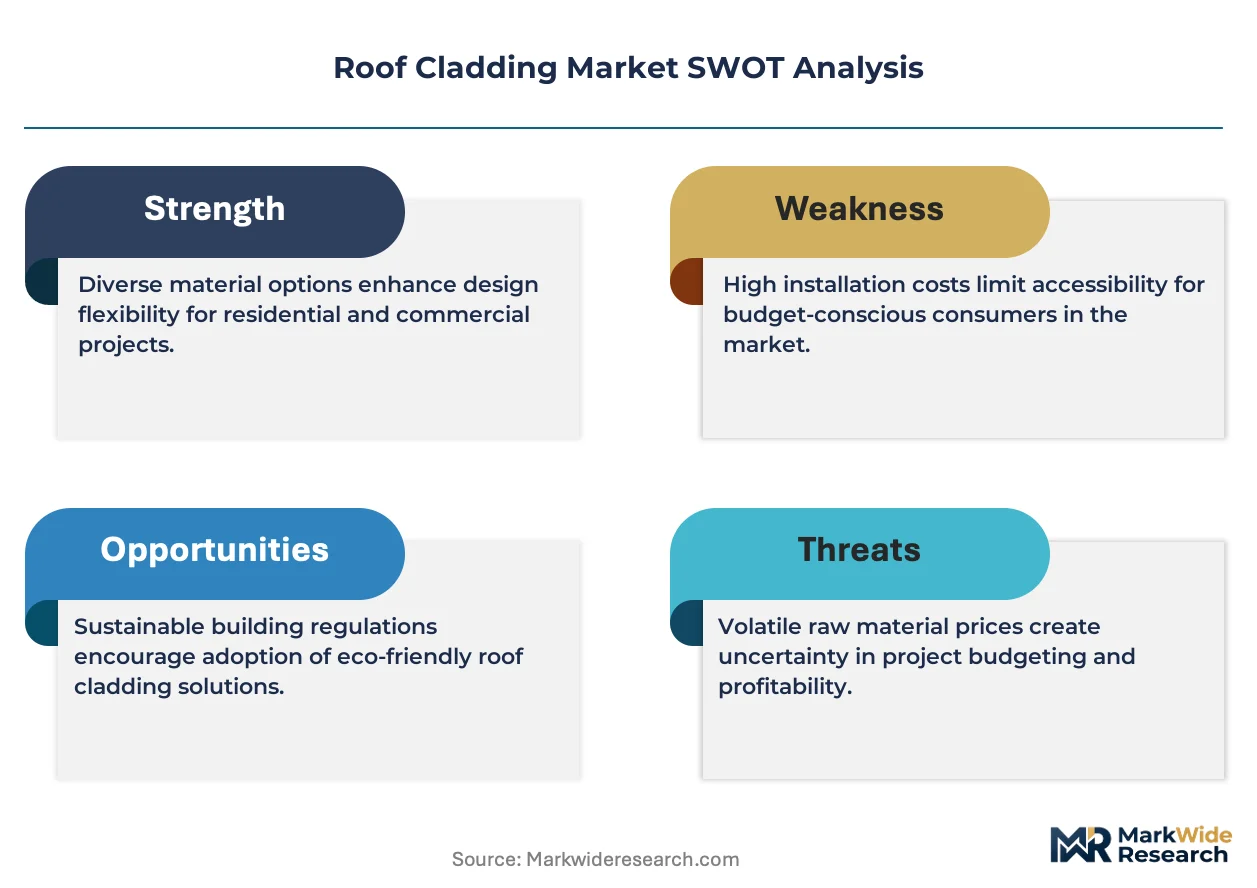
Insulated metal panel systems are compressing traditional multi-layer roof assembly timelines as cold-storage and logistics developers prioritize speed-to-occupancy over material cost minimization.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Germany's industrial corridor is retrofitting warehouse stock with high-performance envelope systems to meet compliance deadlines. Specifiers now prioritize thermal conductivity ratings below 0.25 W/m·K.
- Cold-chain logistics expansion:Food and pharmaceutical distribution networks require continuous insulation integrity. Insulated metal panels deliver monolithic thermal breaks that membrane systems cannot replicate.
- Single-ply TPO membrane technology:Commercial re-roofing cycles are accelerating as heat-welded seams replace adhesive-dependent built-up roofing. Installation labor hours compress by roughly half.
Market Restraints
- Steel substrate price volatility:Galvanized coil costs fluctuate with scrap metal and energy input markets. Panel fabricators face margin compression when hedging strategies fail.
- REACH chemical restrictions:ECHA's flame-retardant reformulation mandates force coating system redesigns. Qualification timelines extend 18-24 months for revised finishes.
- Asphalt shingle substitution threat:Residential retrofits retain price-sensitive demand for mineral-surfaced fiberglass products. Metal's first-cost premium blocks volume penetration.
Strategic Opportunities
- OSHA fall-protection compliance:Lighter panel systems reduce rooftop exposure hours. Contractors gain bid competitiveness through reduced insurance and labor burden.
- Agricultural building envelope modernization:Dairy and controlled-environment agriculture facilities require condensation control. Insulated panels penetrate this historically price-driven segment.
- Bio-based insulation core development:Hemp and mycelium composites align with lifecycle assessment requirements. Early adopters secure specification preference in public procurement.
Industry Challenges
- Installation technician certification gaps:Standing-seam metal systems require specialized seaming equipment operation. Training pipelines lag demand in high-growth construction markets.
- Legacy membrane-to-panel interface complexity:Hybrid retrofit projects demand flashing details that neither trade fully understands. Warranty disputes proliferate at system boundaries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roof Cladding Market |
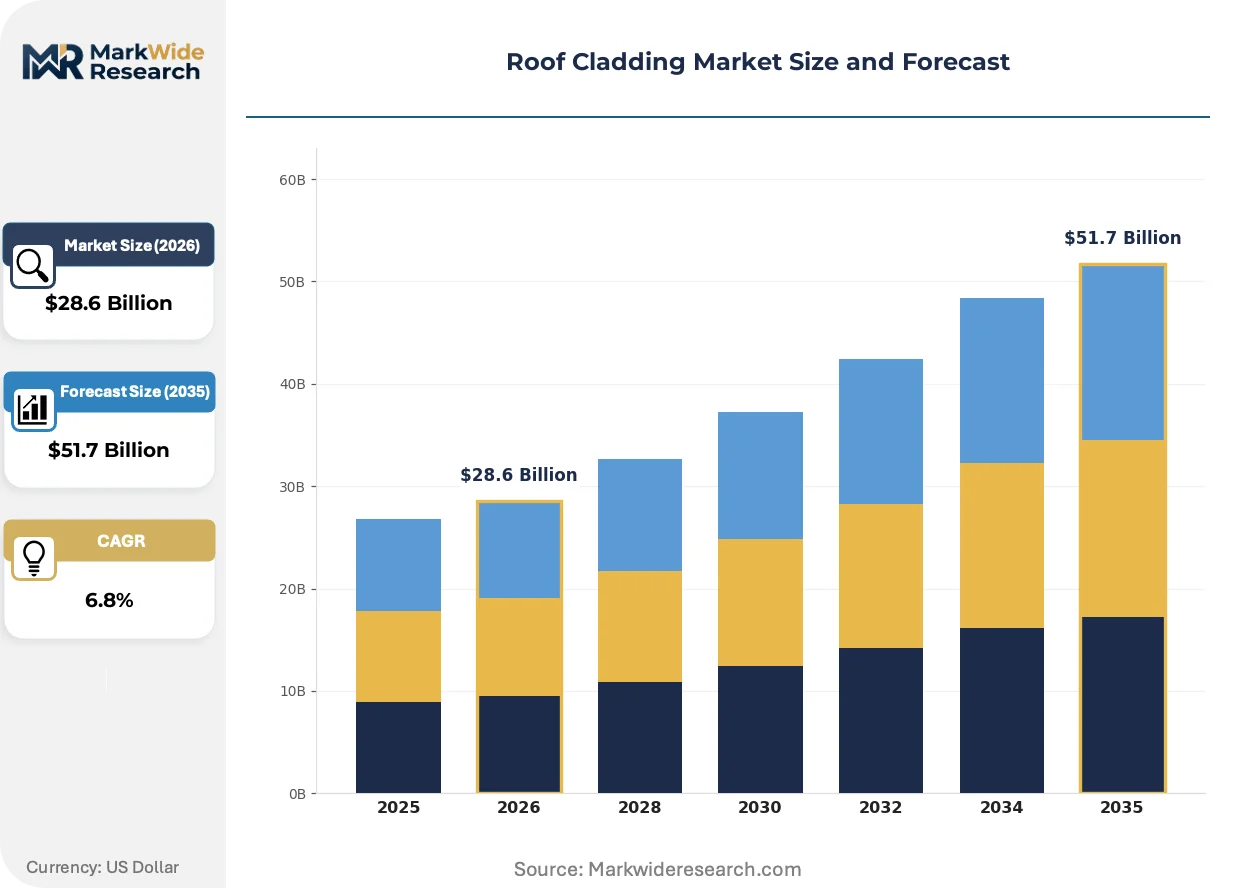
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Metal, Asphalt, Wood, Slate Application: Residential, Commercial, Industrial, Agricultural Installation Method: Roofing Shingles, Panels, Tiles, Membrane Design Style: Contemporary, Traditional, Rustic, Minimalist |
| Companies Covered | Kingspan Group, Atas International, Inc., Cembrit Holdings A/S, Decra Roofing Systems Inc., Everest Industries Limited, Firestone Building Products, Westlake Corporation, Sika AG, Shildan Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roof Cladding Market Emerging Trajectories
Material convergence and regulatory tightening are compressing traditional product category boundaries. Specification decisions now hinge on lifecycle performance data rather than first-cost metrics.
Prefinished metal coil systems with integrated PVDF coatings are unifying weathering protection and aesthetic longevity in a single substrate. Cold-storage developers specify these for 30-year color retention without field painting. The technology is unifying what were historically separate roofing and facade specification channels.
REACH chemical restrictions on halogenated flame retardants are forcing coating reformulations across European supply chains. Manufacturers must qualify alternative intumescent systems without performance degradation. Mineral wool-cored panels face the tightest compliance timelines as ECHA reviews expand.
Design-build procurement is consolidating specification authority with envelope contractors. Traditional architect-led roofing selection is fragmenting as turnkey installers guarantee system performance. This pattern concentrates most visibly in Germany's logistics corridor, where speed-to-market overrides conventional bid processes.
Roof Cladding Market Segmentation
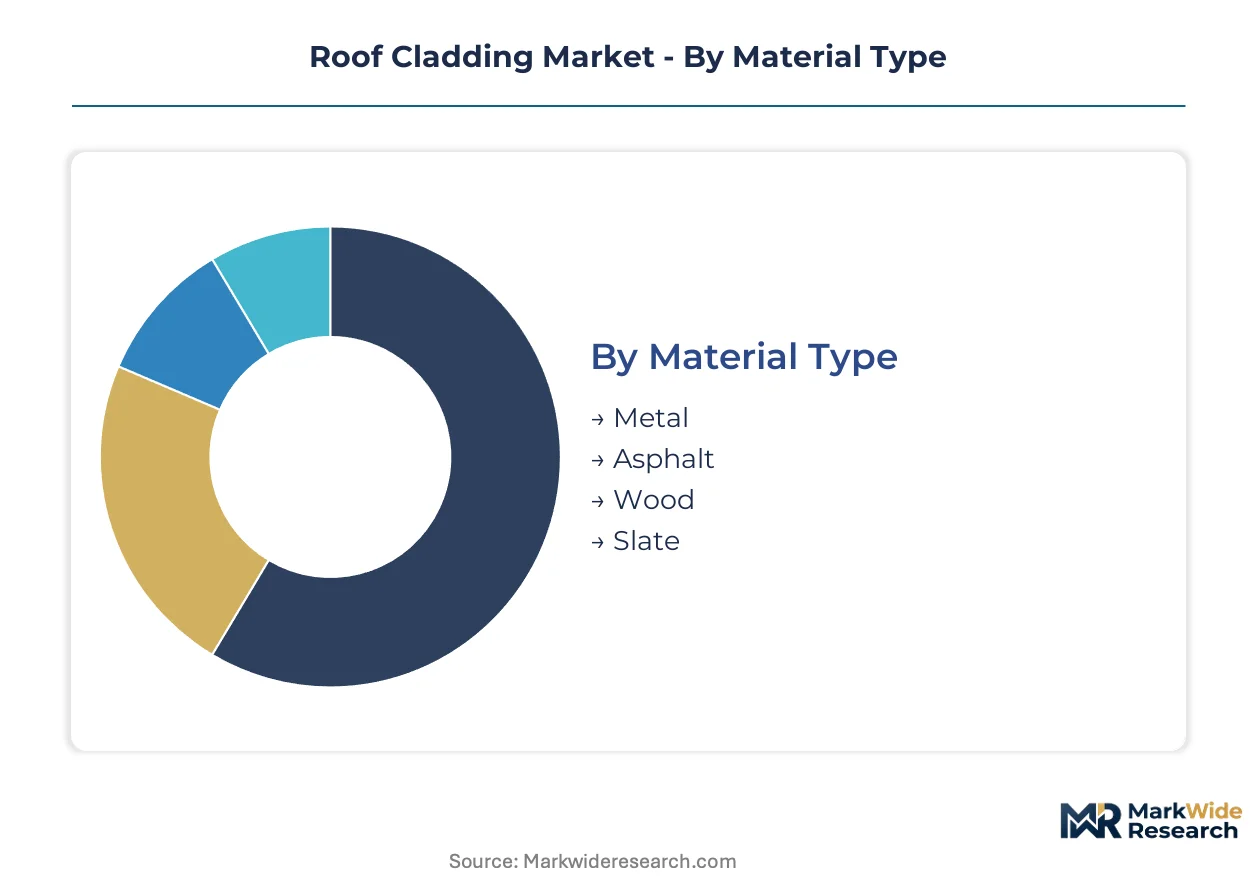
Roof cladding procurement splits sharply between specification-driven commercial projects and price-sensitive residential retrofits. Material selection varies dramatically across climate zones, fire-code jurisdictions, and energy-efficiency mandates. Understanding these segment boundaries reveals where margin compression concentrates versus where premium pricing holds.
Material Type:
Volume leadership sits with commodity substrates, while thermal performance specifications drive premium tier selection.
- Metal:Galvanized steel and aluminum alloys dominate industrial envelopes with thermal conductivity coefficients below 0.25 W/m·K. Cold-storage developers in Germany's logistics corridor specify standing-seam profiles for monolithic weathering integrity. REACH chemical restrictions on coating systems are forcing reformulation of PVDF finishes across EU supply chains.
- Asphalt:Mineral-surfaced fiberglass shingles retain residential retrofit volume leadership despite metal's inroads. First-cost sensitivity in agricultural buildings blocks specification upgrade. EPDM-modified bitumen variants penetrate commercial re-roofing where membrane conversion is incomplete.
- Wood:Cedar shakes and shingles serve heritage restoration and high-end residential aesthetics. Moisture vulnerability limits commercial application.
- Slate:Natural stone delivers century-scale durability for institutional and prestige residential projects. Weight constraints restrict retrofit use.
Mature deployment sits with Asphalt. Newer deployment is concentrated in Metal.
Application:
End-use differentiation separates speed-to-occupancy imperatives from lifecycle cost optimization.
- Commercial:Office and retail envelopes prioritize speed of installation through single-ply TPO membrane systems. Heat-welded seam technology compresses labor hours by roughly half versus built-up roofing. Design-build procurement concentrates specification authority with turnkey envelope contractors.
- Industrial:Warehouse and manufacturing facilities specify insulated metal panels for continuous thermal breaks. EU Green Deal embodied carbon thresholds are accelerating high-performance retrofits across Germany's industrial corridor. OSHA fall-protection mandates favor lighter panel systems that reduce rooftop exposure time.
- Residential:New construction shows metal penetration, but retrofits retain asphalt dominance due to first-cost barriers. Fire-resistance ratings increasingly influence suburban specification in wildland-urban interface zones.
- Agricultural:Dairy and controlled-environment agriculture facilities require condensation control that insulated panels now address. This historically price-driven segment is opening to premium envelope solutions.
Volume concentration remains in Residential. Steepest expansion trajectory is occurring in Industrial.
Installation Method:
Assembly complexity separates contractor-specialized systems from generalist-installable products.
- Panels:Insulated metal systems compress multi-layer roof assembly timelines through factory-integrated insulation and weathering layers. Cold-chain logistics developers prioritize speed-to-occupancy over material cost minimization. Standing-seam profiles require specialized seaming equipment that creates technician certification bottlenecks.
- Membrane:Single-ply TPO and PVC technologies are displacing built-up roofing in commercial re-roofing cycles. Heat-welded installation delivers seam integrity without adhesive dependency. The technology is gaining share fastest among methods targeting 20-year service life guarantees.
- Roofing Shingles:Asphalt and composite shingles remain the default for residential pitched roofs. Installation labor is widely available, compressing contractor mobilization timelines.
- Tiles:Clay and concrete profiles serve Mediterranean and Spanish Colonial architectural programs. Weight and structural loading requirements limit retrofit applicability.
Established contractor networks support Roofing Shingles. Technical specialization is concentrating in Panels.
Design Style:
Aesthetic specification authority varies between architect-led selection and developer-driven standardization.
- Contemporary:Flat and low-slope profiles with hidden-fastener metal systems dominate logistics and data center envelopes. PVDF-coated coil delivers 30-year color retention without field painting. The style is unifying historically separate roofing and facade specification channels.
- Traditional:Gabled forms with visible-fastener metal or asphalt shingles persist in residential and institutional markets. Heritage compliance mandates in European jurisdictions preserve specification volume.
- Rustic:Weathered metal finishes and wood shakes serve rural residential and agritourism aesthetics. Regional material availability shapes procurement geography.
- Minimalist:Monolithic membrane and standing-seam profiles eliminate visual articulation for industrial and commercial clients. Lifecycle assessment alignment is strengthening specification preference in public procurement.
Specification stability characterizes Traditional. Design innovation is clustering in Contemporary.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Zollverein industrial heritage zone and adjacent logistics corridors concentrate European demand for high-performance envelope retrofits. Special economic zones in the UAE and Saudi Arabia accelerate specification of lightweight panel systems for rapid warehouse deployment. China's Yangtze River Delta special economic zones drive prefabricated construction adoption.
Germany
Energy-efficient warehouse retrofits dominate procurement across the Ruhr industrial corridor. EU Green Deal embodied carbon thresholds force thermal conductivity specifications below 0.25 W/m·K. The Leipzig-Halle logistics cluster accelerates insulated metal panel adoption for cold-chain facilities.
United States
OSHA fall-protection mandates reshape contractor preference toward lighter panel systems. The Inflation Reduction Act's energy efficiency tax credits accelerate commercial re-roofing cycles. Dallas-Fort Worth's logistics boom concentrates specification authority with design-build envelope contractors.
China
Dual carbon goals and GB standards for building energy efficiency tighten envelope performance requirements. Prefabricated construction mandates in tier-one cities compress traditional multi-layer assembly timelines. The Yangtze River Delta manufacturing belt drives standardized panel system volume.
United Arab Emirates
Expo City Dubai and adjacent logistics free zones prioritize speed-to-occupancy over material cost minimization. Dubai Municipality's green building regulations align specification with lifecycle assessment criteria. Jebel Ali's industrial corridor concentrates turnkey envelope procurement for warehousing.
India
PLI scheme incentives for cold-chain infrastructure expand insulated panel demand. Bureau of Indian Standards fire-resistance ratings increasingly influence commercial specification. Gujarat's Sanand industrial belt anchors automotive and logistics facility construction.
Roof Cladding Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material and installation method boundaries. The market structure tilts toward specification-driven consolidation in commercial and industrial channels, while residential retrofits retain fragmented distribution. Three archetypes dominate: integrated insulation-panel fabricators, specialized metal system engineers, and membrane-to-cladding crossover providers. Competitive moves concentrate on backward integration into coating and core material supply, plus geographic expansion through regional fabrication licensing.
Among Ireland-based building envelope specialists, Kingspan Group exemplifies integrated insulated panel architecture. Atas International, Inc. and Firestone Building Products occupy distinct positioning vectors within metal system engineering and membrane crossover solutions respectively. These three anchors represent the archetype spectrum from factory-integrated thermal breaks to traditional roofing membrane extensions.
| Leading Market Players |
|---|
| Kingspan Group |
| Atas International, Inc. |
| Cembrit Holdings A/S |
| Decra Roofing Systems Inc. |
| Everest Industries Limited |
| Firestone Building Products |
| Westlake Corporation |
| Sika AG |
| Shildan Group |
| Others |
Supply Flow & Price Mechanics
Galvanized steel coil costs transmit directly from scrap metal and energy input markets through to panel fabricator margins, with volatility compressing profitability across standard-grade insulated metal systems while premium thermal-performance tiers retain pricing power through specification lock-in.
Pricing Analysis
Cost compression in standard-grade metal panels intensifies as galvanized substrate volatility erodes hedging effectiveness, forcing fabricators toward project-based contract structures that transfer risk downstream. Three-tier pricing structure across premium, standard, and economy levels separates specification-driven commercial projects from price-sensitive agricultural retrofits. REACH-driven coating reformulation extends qualification timelines, concentrating margin pressure on smaller European suppliers lacking R&D scale. Residential asphalt shingle buyers exhibit highest price sensitivity, while cold-chain logistics developers accept first-cost premiums for thermal-performance guarantees.
Supply Chain Analysis
Seaming equipment technician shortages in Germany's Ruhr corridor and Dallas-Fort Worth logistics cluster constrain standing-seam panel output, compressing delivery timelines for specification-driven projects. Manufacturing concentrates in China, Germany, and the United States, with prefabricated construction mandates in Chinese tier-one cities driving standardized panel volume. Raw material dependencies center on galvanized steel coil, mineral wool insulation cores, and PVDF resin systems. Single-source vulnerability in specialized seaming equipment creates qualification bottlenecks for new market entrants. Distribution runs through design-build envelope contractors in commercial channels and fragmented roofing distributors in residential retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roof cladding market consolidation accelerates as EU Green Deal embodied carbon thresholds force smaller fabricators into compliance-driven margin compression that rewards integrated players with captive coating and core supply.
For Market Incumbents: Anchor specification authority through backward integration into PVDF coating formulation and mineral wool core production, insulating margin position from REACH-driven reformulation cycles. Prioritize certification investment for standing-seam seaming equipment operation to capture technician-scarcity premiums in Germany's logistics corridor. Defend against membrane-to-panel crossover threats by guaranteeing system-performance warranties that hybrid competitors cannot match. For New Entrants and Emerging Players: Controlled-environment agriculture facilities represent the most penetrable buyer archetype as condensation-control requirements displace historical price sensitivity with performance-driven procurement. Target dairy operations in Gujarat's Sanand belt and controlled-environment horticulture in China's Yangtze Delta with lightweight panel systems that reduce structural loading costs. Pursue regional fabrication licensing to bypass capital-intensive coil coating infrastructure. For Investors and Strategic Acquirers: ECHA's expansion of flame-retardant reviews beyond halogenated systems is the leading indicator that mineral wool-cored panel specialists face accelerated compliance timelines that will separate viable acquisition targets from stranded assets. Five-to-ten-year viability hinges on lifecycle assessment alignment with EU Green Deal thresholds. Target mid-cap fabricators with existing bio-based insulation core partnerships. Monitor Dubai Municipality green building regulation tightening as signal for Gulf Cooperation Council specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Supply | Captive PVDF formulation insulates margins from REACH-driven reformulation cycles and eighteen-month qualification delays. |
| Seaming Equipment Certification Programs | Technician pipeline investment secures bid competitiveness in OSHA-mandated fall-protection environments. |
| Bio-Based Insulation Core Development | Hemp and mycelium composite qualification aligns with EU Green Deal lifecycle assessment requirements for public procurement. |
| Regional Fabrication Licensing | Asset-light expansion into India's PLI-subsidized cold-chain corridor bypasses capital-intensive coil coating infrastructure. |
| Design-Build Partnership Structuring | Turnkey performance guarantees consolidate specification authority with envelope contractors in Germany's logistics belt. |
Methodological Framework
Document review covered SEC 10-K filings of listed building envelope specialists, ECHA regulatory submission databases, and EU Green Deal implementation guidance documents, complemented by interviews with plant managers at insulated panel fabrication facilities, procurement leads at cold-chain logistics developers, and technical directors at coating formulation suppliers. Secondary validation drew from customs trade data for galvanized steel coil movements, OSHA enforcement records for fall-protection compliance patterns, and building permit databases for warehouse construction activity. Bottom-up project pipeline analysis triangulated against top-down material flow estimates.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between material type, installation method complexity, and application-specific thermal performance requirements. The analytical framework incorporated energy-efficiency retrofit cycle timing, embodied carbon threshold compliance deadlines, and cold-chain infrastructure investment patterns as industry-specific demand drivers. CAGRs derived from regression-weighted historical growth rates adjusted for regulatory inflection points and technology substitution elasticities.
Revisions become necessary when ECHA expands flame-retardant review scope beyond current halogenated restrictions, when steel substrate volatility exceeds modeled hedging effectiveness bands, or when OSHA mandates additional fall-protection equipment requirements that alter panel weight specifications. Material deviation in named triggers warrants pause and re-evaluation of volume and margin assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Railing Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
India Ceramic Tiles Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
United Kingdom Timber Cladding Market