
 Global Raised Access Floor Systems Market | 2026-2036
Global Raised Access Floor Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Raised Access Floor Systems Market Outlook
Heavy-duty load-rated specifications is reorganizing procurement priorities across commercial infrastructure. MERO-TSK International GmbH & Co. KG leverages its German engineering heritage to dominate precision-manufactured steel panel systems. Kingspan Group plc anchors its position through integrated insulated panel technology and broad European distribution. Tate Access Floors Inc. specializes in cable management-optimized designs for North American data center operators.
Raised access floor systems consist of modular elevated panels supported on adjustable pedestals, typically fabricated from steel with galvanized or epoxy-coated finishes and designed to provide a service plenum for power, data, and HVAC distribution. The primary purpose is to create flexible, reconfigurable floor cavities that accommodate infrastructure changes without structural modification. Steel panels lead product type demand due to cost-efficiency and load-bearing performance, while aluminum segments command premium positioning where weight reduction and corrosion resistance matter. Data center applications generate the fastest-growing demand pool as hyperscale operators prioritize cooling efficiency and cable density management.
CE marking under the EU Construction Products Regulation governs structural performance and fire reaction classifications for European installations, while OSHA guidelines in the United States establish load safety and workplace access standards. China's GB standards and NMPA-equivalent building material certifications shape product compliance for Asian supply chains. Stakeholders must monitor evolving fire safety codes and embodied carbon reporting requirements as these frameworks increasingly influence specification decisions and supplier qualification.
Market Dynamics
Hyperscale data center construction is compressing specification cycles and forcing panel manufacturers to certify products against simultaneous thermal, seismic, and cable-density loads that exceed legacy design envelopes.
Growth Catalysts
- EU Green Deal embodied carbon mandates:Building codes across Germany, France, and the Netherlands now require Environmental Product Declarations for structural steel, pulling recycled-content panels into specification pipelines.
- AI training cluster power densities:Rack loads exceeding 50kW in Virginia, Singapore, and Ireland facilities demand perforated steel panels with directional airflow engineering.
- Edge computing facility rollouts:Distributed node construction in secondary US metros and Chinese provincial cities is expanding addressable floor area beyond core hyperscale hubs.
Market Restraints
- Galvanized steel coil price volatility:Raw material input swings of 20-40% within single quarters compress fabricator margins and destabilize project bidding.
- Chinese pedestal component concentration:Die-cast aluminum base assemblies rely on Zhejiang and Guangdong supply bases, exposing procurement to single-region logistics disruptions.
- Raised floor displacement by overhead busway systems:Power distribution innovations in Nordic and North American facilities reduce plenum dependency for electrical infrastructure.
Strategic Opportunities
- India data center buildouts:Mumbai, Chennai, and Hyderabad hyperscale projects remain undersupplied by certified local panel fabricators, creating first-mover qualification windows.
- Modular containment integration:Cold aisle containment vendors are specifying factory-integrated floor-to-ceiling systems that lock in raised floor suppliers as sole-source partners.
- US Inflation Reduction Act clean energy incentives:Data center operators qualifying for tax credits are prioritizing LEED and BREEAM certifications that reward embodied carbon reduction in structural materials.
Industry Challenges
- Seismic certification bottlenecks:ICC-ES AC156 testing queue delays in California and Japan are extending project timelines by 8-14 weeks for facilities in fault zones.
- Fire reaction classification harmonization:Divergent EN 13501-1, ASTM E84, and GB 8624 testing protocols force manufacturers to maintain parallel certification inventories for multi-continent operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Raised Access Floor Systems Market |
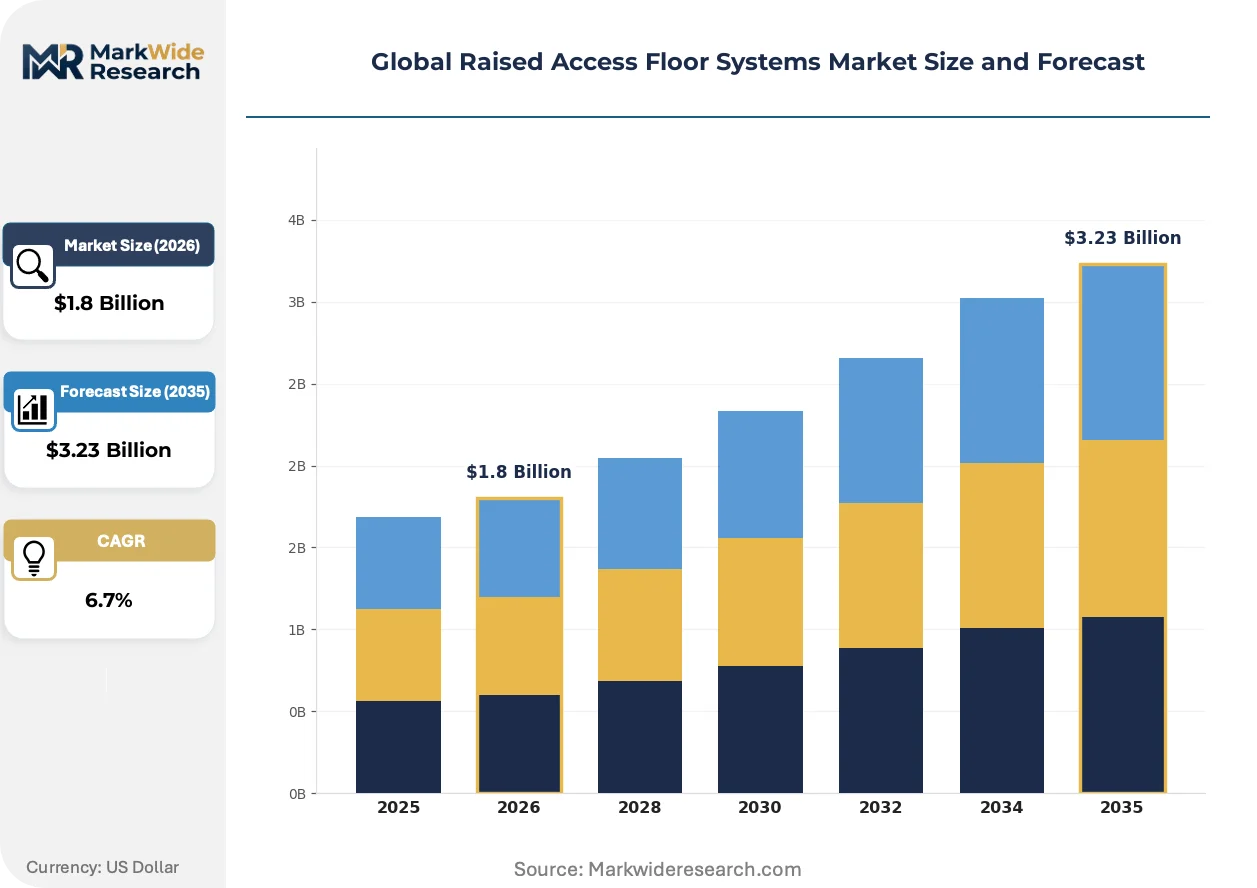
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Aluminum, Wood, Concrete Application: Data Centers, Commercial Offices, Educational Institutions, Healthcare Facilities Installation Type: New Construction, Renovation, Upgrades, Modular Load Capacity: Light Duty, Medium Duty, Heavy Duty, Super Heavy Duty |
| Companies Covered | MERO-TSK International GmbH & Co. KG, ASP Access Floors Pty Ltd, Tate Access Floors Inc., Unitile Group of Companies, Jansen AG, Kingspan Group plc, Polygroup, Changzhou Huatong Floor Machine Co. Ltd., Lindner Group KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Raised Access Floor Systems Market Strategic Shifts
Specification engineering is pivoting from static load-bearing metrics to dynamic thermal-fluid performance, forcing panel designers to optimize simultaneously for structural integrity and precision airflow management.
Perforated steel panel technology with variable open-area ratios is fragmenting the traditional solid-panel market as hyperscale operators demand tunable cooling performance. Google, Microsoft, and Amazon Web Services procurement teams now require computational fluid dynamics validation for floor layouts exceeding 10,000 square meters. This capability threshold is compressing the qualified supplier base to fabricators with in-house thermal modeling resources.
China's GB 51245 fire safety standard for data center facilities is tightening smoke density and toxicity requirements for raised access floor assemblies. Domestic manufacturers in Jiangsu and Shandong provinces are reformulating epoxy coatings to meet Class A2-s1,d0 equivalent performance. Export-oriented fabricators face parallel compliance burdens as European operators with Chinese construction partners demand dual-certified product lines.
Lifecycle service contracting is displacing transactional panel procurement among co-location and enterprise data center operators. Equinix, Digital Realty, and NTT facilities managers are unbundling installation, seismic recertification, and panel replacement into multi-year service agreements. This model concentrates purchasing authority with national facility management teams rather than regional construction contractors, most visibly across the United States and United Kingdom markets.
Global Raised Access Floor Systems Market Segmentation
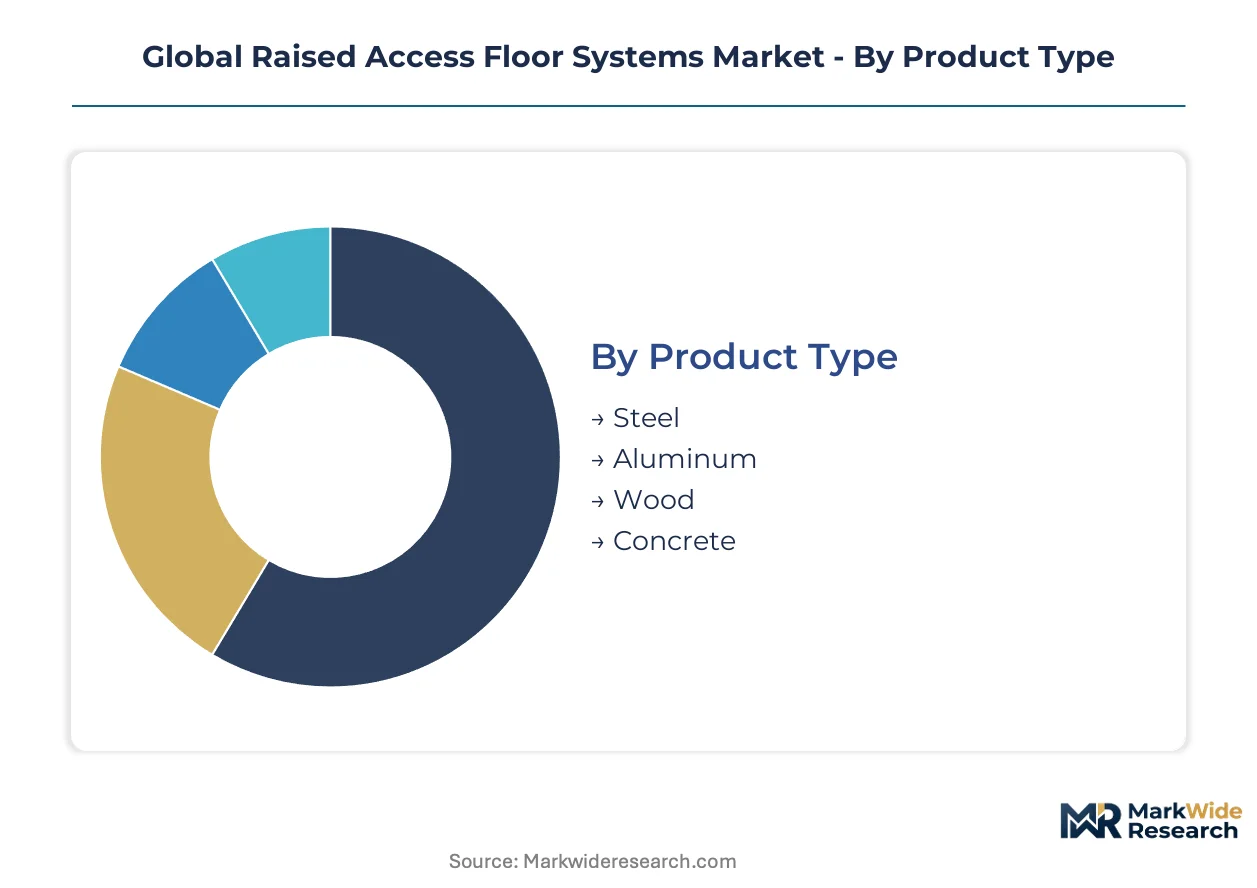
Raised access floor procurement diverges sharply across end-use requirements, with data center operators prioritizing thermal-fluid performance while commercial developers optimize for cost per square meter. Specification engineers must reconcile these competing demands against divergent regulatory compliance burdens across steel grades, fire reaction classifications, and seismic certification protocols.
Product Type:
CE marking under the EU Construction Products Regulation and China's GB standards enforce divergent material purity thresholds that reshape supplier qualification pathways for steel and aluminum compositions.
- Steel:Galvanized or epoxy-coated steel panels deliver cost-efficient load-bearing performance for standard commercial and data center deployments. Demand concentrates in hyperscale facilities across Virginia, Singapore, and Ireland where rack loads exceed 50kW and perforated configurations with directional airflow engineering dominate procurement specifications.
- Aluminum:Die-cast and extruded aluminum systems reduce structural weight by 40-60% versus steel equivalents while delivering superior corrosion resistance for coastal or high-humidity installations. Premium positioning in Nordic data centers and Japanese seismic zones reflects ICC-ES AC156 certification requirements and embodied carbon reporting mandates under the EU Green Deal.
- Wood:Engineered wood core panels serve heritage building renovations and acoustic-sensitive environments where fire reaction classifications permit organic substrates.
- Concrete:Precast concrete panels anchor super heavy-duty specifications for industrial manufacturing floors and military command facilities requiring blast resistance.
Established volume favors steel; emerging adoption favors aluminum.
Application:
End-use concentration determines margin structure, with data center operators accepting 15-25% premiums for thermal-validated designs while commercial office procurement compresses supplier margins through standardized specifications.
- Data Centers:Hyperscale operators in Germany, China, and the United States now require computational fluid dynamics validation for floor layouts exceeding 10,000 square meters. Google, Microsoft, and Amazon Web Services procurement teams specify perforated steel panels with tunable open-area ratios that optimize cooling efficiency against cable density management.
- Commercial Offices:Flexible workspace configurations in London, Frankfurt, and New York drive demand for reconfigurable pedestal systems supporting frequent infrastructure changes without structural modification.
- Educational Institutions:Campus IT modernization across US state university systems and Chinese provincial technical colleges generates steady replacement demand for legacy floor systems.
- Healthcare Facilities:Infection control protocols and medical equipment load requirements in German Krankenhaus and US hospital construction specify sealed-panel designs with enhanced cleanability.
Data centers command the steepest expansion trajectory; commercial offices anchor baseline revenue stability.
Installation Type:
Project delivery models are displacing transactional procurement, with national facility management teams at Equinix and Digital Realty unbundling installation, seismic recertification, and panel replacement into multi-year service agreements.
- New Construction:Greenfield hyperscale projects in Mumbai, Chennai, and Hyderabad integrate raised floor specifications during structural design phases, enabling optimized plenum depth and cable routing.
- Renovation:Legacy commercial building retrofits in Paris, Milan, and Chicago face asbestos abatement and structural load verification challenges that extend project timelines.
- Upgrades:Data center operators in Northern Virginia and Dublin replace solid panels with perforated configurations to accommodate AI training cluster power densities.
- Modular:Factory-integrated floor-to-ceiling containment systems lock in raised floor suppliers as sole-source partners for edge computing rollouts in secondary US metros.
New construction captures the largest absolute spend; modular formats gain share fastest among distributed facility deployments.
Load Capacity:
Specification engineering has pivoted from static load-bearing metrics to dynamic performance validation, with seismic and thermal loads now tested simultaneously against legacy design envelopes.
- Light Duty:Office environments and retail spaces with pedestrian traffic and minimal equipment loads specify 1,000-1,500 pound concentrated load ratings.
- Medium Duty:General data center applications with standard rack configurations and moderate cable density dominate volume production.
- Heavy Duty:Hyperscale facilities with dense server deployments and rolling equipment traffic require 2,500-4,000 pound ratings with enhanced pedestal anchoring.
- Super Heavy Duty:Military, broadcast, and industrial manufacturing applications in Japan and California fault zones demand seismic-certified systems exceeding 5,000 pound concentrated loads with ICC-ES AC156 validation.
Medium duty specifications anchor current production volumes; super heavy duty certifications command the widest supplier margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances tilt toward steel panel shipments from Chinese fabricators to Southeast Asian data center projects, while German and US manufacturers retain premium aluminum system exports to Nordic and Japanese seismic zones. Regional procurement patterns diverge sharply between embodied carbon compliance in Europe and raw cost optimization in emerging markets.
United States
Hyperscale construction in Northern Virginia and Dallas-Fort Worth drives perforated steel panel procurement for 50kW-plus rack densities. OSHA workplace access standards govern pedestal anchoring and load safety certification. Phoenix and Atlanta secondary markets absorb modular containment-integrated floor systems for edge computing deployments.
Germany
Frankfurt Rhine-Main data center clusters demand aluminum systems with EU Green Deal Environmental Product Declarations for recycled content. CE marking under the EU Construction Products Regulation enforces structural performance and fire reaction classifications. Bavarian engineering fabricators supply precision-manufactured steel panels to domestic hyperscale operators and export markets.
China
Jiangsu and Shandong province manufacturers reformulate epoxy coatings to meet GB 51245 fire safety standards for smoke density and toxicity. GB standards and NMPA-equivalent building material certifications shape compliance for domestic and export supply chains. Beijing-Tianjin-Hebei and Yangtze River Delta data center construction concentrates demand for locally fabricated steel and aluminum panels.
India
Mumbai, Chennai, and Hyderabad hyperscale projects face undersupply from certified local panel fabricators, creating qualification windows for first-mover entrants. The country's national building code and state-level construction regulations govern structural material specifications. Maharashtra and Telangana state data center policies accelerate floor system procurement timelines for cloud operator facilities.
Japan
Tokyo and Osaka seismic zones require ICC-ES AC156 certified systems exceeding 5,000 pound concentrated loads with enhanced pedestal anchoring. METI industrial standards and JIS certification protocols enforce performance validation for fault-zone installations. Chubu region manufacturing facilities supply heavy-duty specifications to domestic data center operators and export to Taiwan and South Korea.
Global Raised Access Floor Systems Market Competitive Environment
Listed leaders compete with private specialists across capital access and engineering agility dimensions. The vendor base stratifies into three tiers: scale-driven European conglomerates with integrated insulated panel technology, mid-cap German engineering specialists with precision manufacturing heritage, and regional Asian fabricators competing on galvanized steel cost structures. Dominant competitive moves include M&A consolidation of containment system vendors and capacity expansion into underserved Indian and Southeast Asian markets.
Within the premium engineering tier, MERO-TSK International GmbH & Co. KG and Kingspan Group plc exemplify divergent strategic positions—German GmbH-structured precision manufacturing against Irish plc-integrated building envelope systems. Tate Access Floors Inc. occupies a position as a North American Inc.-structured specialist in cable management-optimized designs. These three anchors represent the geographic and structural archetypes shaping procurement authority: European engineering heritage, integrated building technology platforms, and regional application specialization.
| Leading Market Players |
|---|
| MERO-TSK International GmbH & Co. KG |
| ASP Access Floors Pty Ltd |
| Tate Access Floors Inc. |
| Unitile Group of Companies |
| Jansen AG |
| Kingspan Group plc |
| Polygroup |
| Changzhou Huatong Floor Machine Co. Ltd. |
| Lindner Group KG |
| Others |
Value Chain & Pricing Dynamics
Perforated steel panel substitution for legacy solid-panel designs is redrawing procurement geography toward Jiangsu and Shandong fabricators while compressing price premiums for thermal-validated configurations. This input shift simultaneously concentrates supply in Chinese coastal provinces and erodes margin buffers for European manufacturers lacking in-house airflow engineering capabilities.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on seismic certification grade and computational fluid dynamics validation, with ICC-ES AC156-certified systems commanding substantial premiums over unrated alternatives. Cost compression in standard-grade steel panels is intensifying because galvanized coil input volatility feeds directly through fabrication contracts. Hyperscale data center operators exhibit lowest price sensitivity, while commercial office developers in secondary US metros drive aggressive procurement negotiation.
Supply Chain Analysis
China, Germany, and the United States anchor global panel fabrication, with Zhejiang and Guangdong provinces supplying die-cast aluminum pedestal assemblies. Raw material dependencies rest on galvanized steel coil from integrated mills, epoxy resin systems for coating formulations, and precision-machined pedestal hardware. Single-region concentration in Chinese base component manufacturing exposes procurement to logistics disruptions from port congestion or regulatory export controls. Distribution runs through national facility management teams at Equinix and Digital Realty rather than regional construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face a substitution defense against overhead busway power distribution systems that eliminate plenum dependency in Nordic and North American facilities. This electrical infrastructure innovation threatens to displace raised floor specifications in greenfield hyperscale projects where cable density requirements are moderate.
For Market Incumbents: Shield installed base relationships through backward integration into containment system manufacturing, locking in sole-source partnerships with cold aisle vendors. Accelerate seismic certification investment to clear ICC-ES AC156 testing queues ahead of California and Japan fault-zone construction cycles. Prioritize lifecycle service contracting to displace transactional procurement and concentrate purchasing authority with national facility management teams.
For New Entrants and Emerging Players: Anchor in Mumbai, Chennai, and Hyderabad hyperscale corridors where certified local fabricators remain undersupplied against accelerating data center construction timelines. Target modular containment-integrated floor specifications for edge computing rollouts in secondary US metros, leveraging factory pre-integration as qualification shortcut. Pursue direct engagement with Maharashtra and Telangana state data center agencies to secure fast-track certification pathways.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-cap engineering specialists with precision manufacturing heritage and established EU Green Deal Environmental Product Declaration portfolios. Long-term viability hinges on embodied carbon reporting capabilities becoming mandatory specification filters across European hyperscale procurement. Monitor GB 51245 fire safety standard harmonization progress as inflection indicator for Chinese export-oriented fabricators facing dual-certification cost burdens.
| Strategic Initiative | Industry Significance |
|---|---|
| Seismic Certification Investment | ICC-ES AC156 validation clears 8-14 week testing bottlenecks for California and Japan fault-zone projects. |
| Backward Integration into Containment | In-house production of floor-to-ceiling systems locks in sole-source partnerships with hyperscale operators. |
| EPD Portfolio Expansion | EU Green Deal recycled-content documentation qualifies panels for Frankfurt and Amsterdam hyperscale specifications. |
| India Manufacturing Qualification | Mumbai and Hyderabad facility certification captures first-mover advantage in undersupplied hyperscale corridor. |
| Lifecycle Service Contracting | Multi-year installation and recertification agreements displace transactional procurement with Equinix and Digital Realty. |
Study Parameters
The analysis maps steel panel, aluminum system, and modular containment sub-sectors, each validated through data center facility managers, construction procurement leads, and seismic engineering consultants. Primary fieldwork with OEM procurement teams at hyperscale operators combined with secondary validation against SEC capex disclosures, EU Construction Products Regulation filings, and Chinese GB standard certification databases. Bottom-up project pipeline tracking and top-down construction spend analysis triangulate volume estimates across the analysis window.
Consistency checks against hyperscaler facility announcement timelines and regional building permit databases validated projection outputs. Segmentation modeling spans material composition, load capacity tier, installation type, and application end-use throughout the forecast period. CAGRs derive from fitted growth curves against historical construction completion data and announced pipeline capacity. AI training cluster power density trajectories and embodied carbon reporting mandate adoption curves serve as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained hyperscale construction commitment and stable galvanized steel input pricing; material deviation in either assumption would warrant model refresh. Specific risks include accelerated overhead busway substitution, Chinese export control escalation on die-cast aluminum components, or seismic code harmonization delays. Recalibration cycles align with material shifts in EU Green Deal implementation timelines and hyperscaler regional expansion announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Europe Construction Chemicals Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Cleanroom Flooring Market
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Mexico Oriented Strand Board Market
Building & Construction Materials
Steel Wire Rope Products Market