
 North America Prefab Wood Building Market | 2026-2036
North America Prefab Wood Building Market Size, Share, and Industry Trends Forecast 2026-2036
North America Prefab Wood Building Market Analytics
Cross-laminated timber is shifting cost structures away from steel and concrete in mid-rise construction across North America. Clayton Homes leverages its manufacturing scale to dominate single-family modular production in the southeastern United States. Skyline Champion Corporation anchors its position through vertical control over distribution channels and retail parks. RedBuilt, LLC specializes in engineered wood components for commercial and institutional applications, differentiating on structural performance specifications.
Prefab wood buildings are factory-manufactured structures using engineered wood products, dimensional lumber, and mass timber assemblies fabricated under controlled conditions with moisture content typically held below nineteen percent, then transported to sites for erection. These systems serve residential, commercial, and institutional clients seeking compressed construction schedules and reduced on-site labor exposure. Modular homes command the largest share of product type revenue, while structural insulated panels represent the fastest-growing segment driven by stringent energy code compliance requirements across Canadian provinces and US states. Panelized homes occupy a mature position with established supply chains, though margin pools are migrating toward turnkey installation contracts that bundle design, fabrication, and assembly.
The International Code Council's mass timber provisions, Canada's National Building Code wood-frame height revisions, and US state-level carbon accounting rules for public procurement collectively shape product standards and market access across the region. British Columbia's building code amendments and California's CALGreen standards are tightening embodied carbon thresholds, steering public and private buyers toward certified prefab wood systems. Stakeholders must monitor pending ANSI/APA standards for cross-laminated timber performance grading and assess how evolving height allowances alter competitive positioning against concrete and steel in the multi-family and institutional segments.
Market Dynamics
The International Building Code's mass timber height allowances are compressing project timelines for multi-family developers across the Pacific Northwest. This regulatory shift is redrawing competitive boundaries between engineered wood systems and conventional steel-concrete construction in mid-rise segments.
Growth Catalysts
- CALGreen embodied carbon thresholds:California's building standards are mandating lower-carbon materials in public procurement, steering institutional buyers toward certified cross-laminated timber systems.
- Cross-laminated timber modules:Factory-fabricated mass timber panels are cutting on-site labor exposure and weather delays for multi-family residential projects.
- British Columbia forestry-manufacturing clusters:Integrated softwood supply chains from coastal forests to prefabrication plants are compressing raw material transport costs.
Market Restraints
- Lumber price volatility:Structural softwood input costs fluctuate with North American housing starts and trade policy, squeezing margin predictability for panelized home producers.
- Adhesive supply concentration:Engineered wood production depends on polyurethane and phenolic resin supply chains concentrated in Gulf Coast petrochemical corridors.
- Seismic code limitations:High seismic zones in California and British Columbia restrict mass timber height allowances below those permitted under the International Building Code.
Strategic Opportunities
- US Mountain West multi-family:Colorado and Utah municipalities are adopting progressive mass timber codes faster than national timelines, opening underpenetrated geographies.
- Turnkey installation contracts:Bundling design, fabrication, and site assembly is capturing margin pools migrating away from component-only sales.
- Canada's National Building Code wood-frame height revisions:Federal code harmonization is creating regulatory tailwinds for six-storey prefab wood construction in Ontario and Quebec.
Industry Challenges
- Mass timber erection crews:Shortages of certified installers for cross-laminated timber and glued-laminated beam assembly are extending project mobilization timelines.
- APA/ANSI certification timelines:Performance grading standards for cross-laminated timber remain in draft, delaying product qualification for speculative developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Prefab Wood Building Market |
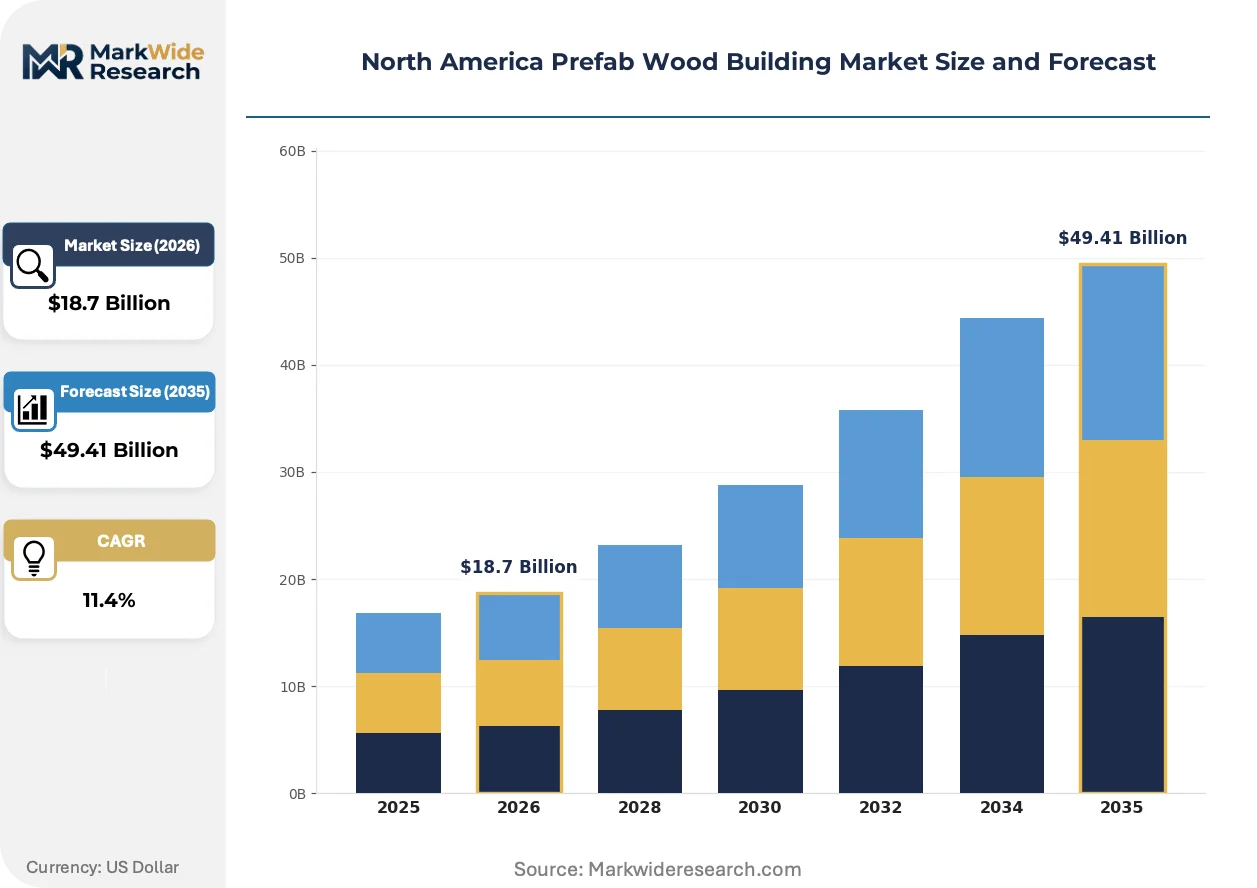
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Panelized Homes, Structural Insulated Panels, Prefabricated Beams End User: Residential, Commercial, Industrial, Government Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors Installation Type: On-site, Off-site, Hybrid, Turnkey |
| Companies Covered | Heinrich Brothers, Inc., Clayton Homes, Speed Space, Appalachian Log Structures, Inc., Alta-Fab Structures, R.P. Crawford Co., Inc., RedBuilt, LLC, Foxworth-Galbraith Lumber Company, Skyline Champion Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Prefab Wood Building Market Evolving Landscape
Factory automation and digital fabrication are converging to reshape how engineered wood products move from design to site assembly. These shifts are compressing traditional construction schedules and altering where value accumulates across the supply chain.
Robotic milling and CNC cutting of mass timber components is electrifying precision in factory environments. Multi-family developers in Seattle and Vancouver are specifying digitally fabricated cross-laminated timber panels for mid-rise projects. This precision is eliminating field-fit waste and enabling just-in-time delivery models that compress carrying costs.
The International Code Council's mass timber provisions are triggering code adoption cascades across US states. California and Oregon have enacted height allowances ahead of federal minimums, forcing concrete and steel incumbents to defend mid-rise positions. The multi-family residential segment is responding by embedding mass timber expertise into development teams earlier in project cycles.
Institutional buyers are unbundling design from fabrication and erection, selecting separate contractors for each phase. University housing authorities and municipal developers across the Pacific Northwest are driving this disintermediation, replacing single-source general contractors with direct procurement of prefab wood modules. British Columbia's public infrastructure pipeline exhibits this pattern most visibly, with school districts and health authorities issuing discrete RFPs for engineered wood supply.
North America Prefab Wood Building Market Segmentation
Prefab wood building manufacturers configure production lines around specific product architectures, with each segment demanding distinct capital equipment, moisture control protocols, and logistics footprints. Understanding where margin pools concentrate across these dimensions determines capital allocation and partnership strategies.
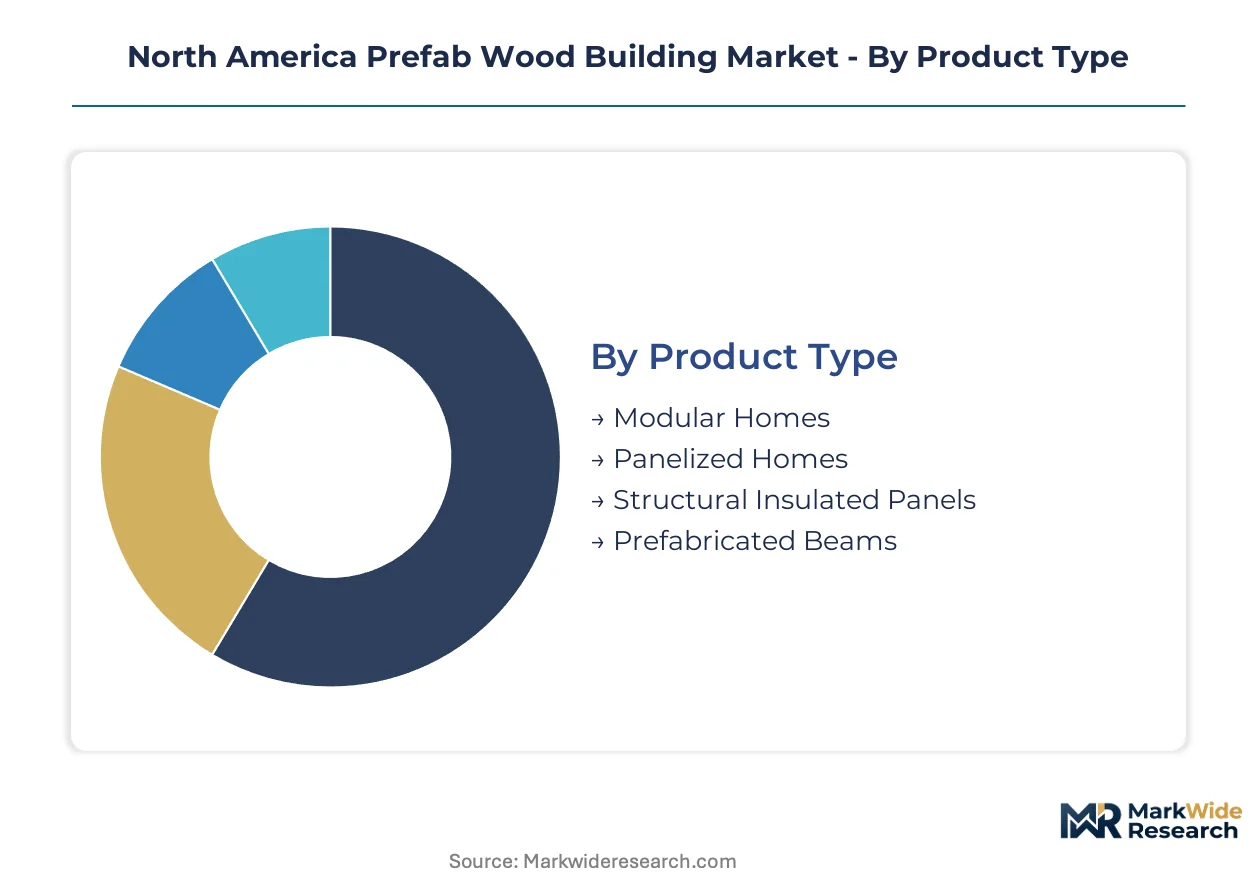
Product Type:
Supply concentration in British Columbia and the US Pacific Coast favors mass timber producers with captive softwood access, while southeastern manufacturing clusters compete on volume throughput of standardized modules.
- Modular Homes:Factory-built volumetric units with complete interior finishes, electrical, and plumbing pre-installed. Demand clusters in single-family and low-rise multi-family residential across the southeastern United States where Clayton Homes and Skyline Champion Corporation operate high-throughput facilities.
- Structural Insulated Panels:Rigid foam cores laminated between oriented strand board facings, delivering thermal performance exceeding conventional framing. British Columbia and California builders specify these for energy code compliance in net-zero residential and small commercial projects, with procurement accelerating fastest where CALGreen standards apply.
- Panelized Homes:Wall, floor, and roof components fabricated to precise dimensions for field assembly. Established supply chains serve mature markets with thin margins, though turnkey installation bundling is capturing value migration.
- Prefabricated Beams:Engineered wood I-joists, laminated veneer lumber, and glued-laminated timber members produced for commercial and institutional structural systems. RedBuilt and similar specialists differentiate on load-span specifications for mid-rise construction.
Today's leader: Modular Homes. Tomorrow's challenger: Structural Insulated Panels.
End User:
Application-driven procurement patterns separate residential volume buyers from institutional clients with extended qualification timelines and performance-based specifications.
- Residential:Single-family and multi-family developers seeking compressed construction schedules and reduced on-site labor exposure. Pacific Northwest multi-family projects increasingly specify cross-laminated timber modules under revised International Building Code height allowances.
- Commercial:Office, retail, and hospitality developers evaluating mass timber for embodied carbon reduction and biophilic design appeal. California's public procurement carbon accounting rules steer institutional buyers toward certified wood systems.
- Government:Federal, state, and municipal agencies with sustainability mandates and progressive building standards. British Columbia school districts and health authorities issue discrete RFPs for engineered wood supply, unbundling design from fabrication.
- Industrial:Warehouse, distribution, and light manufacturing facilities requiring rapid enclosure. Less penetrated segment with price-sensitive procurement favoring conventional steel in most geographies.
Residential commands current volume. Government procurement is climbing the fastest as carbon accounting tightens.
Distribution Channel:
Customer type and project scale dictate channel selection, with direct relationships dominating large developments and intermediaries serving fragmented residential demand.
- Direct Sales:Manufacturer-to-developer relationships for multi-unit residential and institutional projects. Skyline Champion Corporation leverages vertical control over retail parks and direct contractor networks.
- Wholesalers:Regional building material distributors stocking panelized components for custom home builders. Established presence in mature markets with thin differentiation.
- Distributors:Specialized engineered wood distributors with technical sales support for commercial and institutional specification. Concentrated in Pacific Northwest and southeastern manufacturing corridors.
- Online Retail:Emerging channel for standardized accessory dwelling units and small residential modules. Limited current penetration due to transportation logistics complexity and site-specific engineering requirements.
Direct Sales anchors premium project flow. Distributors are gaining share fastest as commercial specification deepens.
Installation Type:
Margin migration toward site-integrated services is reshaping competitive boundaries between component manufacturers and full-service providers.
- Turnkey:Bundled design, fabrication, transportation, and erection contracts capturing expanded margin pools. University housing authorities and municipal developers across the Pacific Northwest drive this disintermediation.
- Hybrid:Split responsibility models with factory fabrication and separate site assembly contractors. Common in mid-rise multi-family where certified mass timber erection crews remain scarce.
- On-site:Traditional construction with prefabricated components delivered for builder assembly. Mature approach with commoditized pricing.
- Off-site:Complete volumetric construction with minimal site work. Constrained by transportation dimensions and crane capacity for multi-story applications.
Turnkey commands expanding margin share. Hybrid models are expanding most quickly as capability constraints persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
British Columbia's forestry-manufacturing corridor anchors prefab wood production across North America. Cross-laminated timber fabrication clusters in Vancouver and the Fraser Valley compress supply chains from coastal forests to modular plants. The region's dominance stems from integrated softwood access and progressive building codes.
United States
California's CALGreen embodied carbon thresholds mandate lower-carbon materials in public procurement, steering institutional buyers toward certified mass timber systems. The International Building Code's height allowances for mass timber construction have accelerated adoption in mid-rise multi-family projects. Seattle and Portland developers specify cross-laminated timber modules for compressed construction schedules.
Canada
Ontario and Quebec benefit from federal National Building Code wood-frame height revisions enabling six-storey prefab construction. British Columbia's building code amendments tighten embodied carbon thresholds faster than national timelines. Toronto's multi-family developers increasingly procure factory-fabricated wall and floor assemblies from Quebec manufacturing clusters.
Mexico
Northern border states near US lumber supply chains see emerging panelized home production for export markets. Mexico's federal housing agency INFONAVIT has piloted prefabricated wood systems in affordable housing programs. Monterrey manufacturers serve Texas and southwestern US markets through streamlined cross-border logistics.
North America Prefab Wood Building Market Competitive Landscape
Global majors compete with regional champions across manufacturing scale and distribution reach. The vendor base stratifies between high-volume modular producers and specialized engineered wood component fabricators. Three archetypes dominate: vertically integrated housing manufacturers controlling retail channels, mass timber specialists serving commercial specification markets, and regional panelized home builders competing on turnkey installation bundling. Capacity expansion and strategic partnerships represent the primary competitive vectors as firms position for turnkey contract capture.
Among US-based manufacturers, Clayton Homes exemplifies scale-driven vertical integration through captive retail networks, while Skyline Champion Corporation anchors its position through distribution channel control. RedBuilt, LLC occupies the engineered wood specialist tier, differentiating on structural performance specifications for commercial and institutional applications. These three represent distinct strategic postures: volume throughput, channel dominance, and technical specification leadership.
| Leading Market Players |
|---|
| Heinrich Brothers, Inc. |
| Clayton Homes |
| Speed Space |
| Appalachian Log Structures, Inc. |
| Alta-Fab Structures |
| R.P. Crawford Co., Inc. |
| RedBuilt, LLC |
| Foxworth-Galbraith Lumber Company |
| Skyline Champion Corporation |
| Others |
Value Network & Pricing Analysis
CALGreen embodied carbon thresholds gate qualified supply and premium-tier pricing access for prefab wood building manufacturers serving California's institutional procurement pipeline. British Columbia's parallel carbon accounting rules create a dual-mandate environment where certified cross-laminated timber commands price premiums while uncertified producers face margin compression.
Pricing Analysis
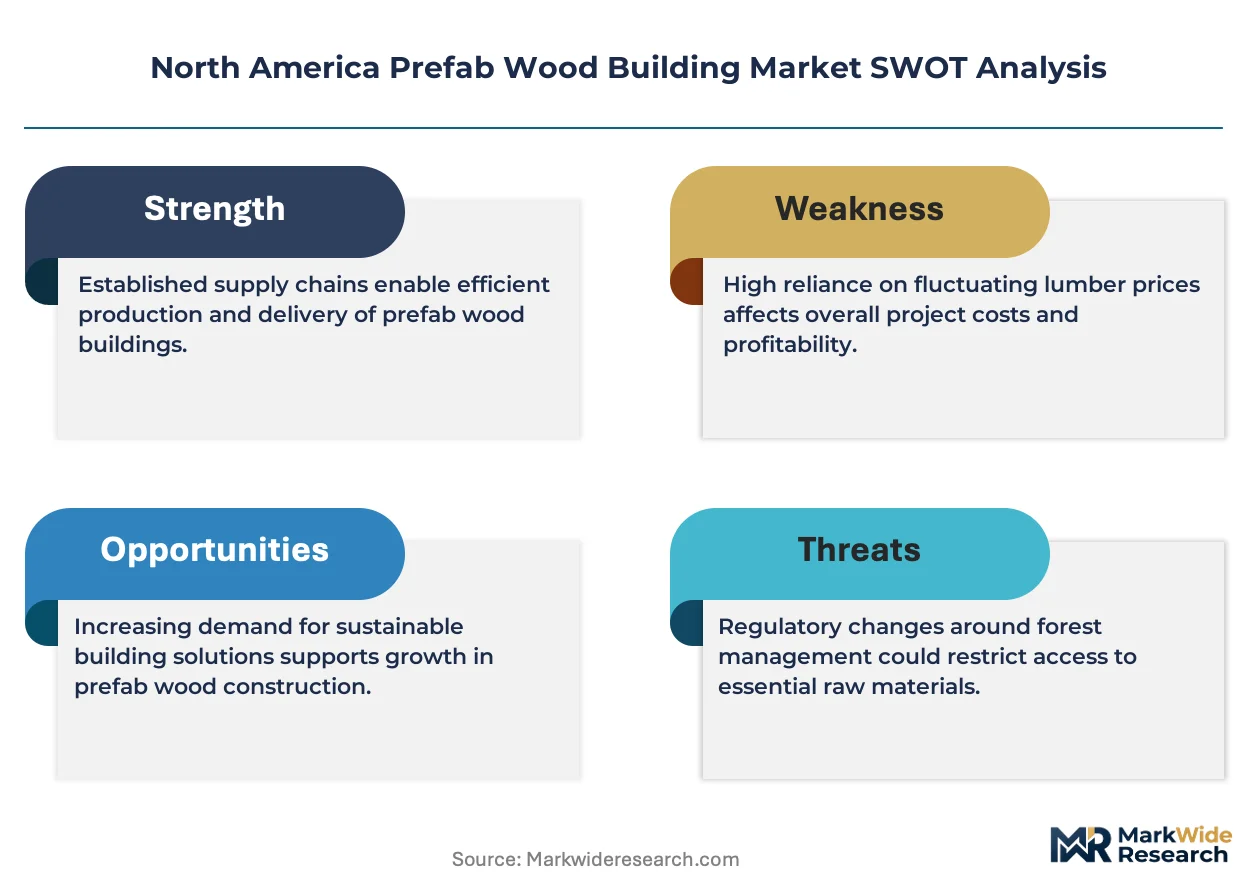
Input-cost pass-through from structural softwood and adhesive resin fluctuations shapes margin predictability across product tiers. Pricing stratifies across certified mass timber, standard engineered wood, and economy panelized systems based on certification grade and volume scale. Cost compression in economy panelized homes is intensifying because lumber price volatility squeezes producers without captive forestry access. Residential developers exhibit highest price sensitivity, while government procurement with sustainability mandates shows lowest sensitivity.
Supply Chain Analysis
Freight cost differentials favor manufacturing co-location with coastal softwood forests in British Columbia, Washington, and Oregon. Production draws from Douglas fir and spruce-pine-fir feedstocks, polyurethane resins, and steel connection hardware. Single-source vulnerability concentrates in Gulf Coast petrochemical corridors for adhesive supply. Distribution runs through manufacturer-direct channels for large projects and regional distributors for fragmented residential demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America prefab wood building market functions as a stable compounder anchored by regulatory ratcheting on embodied carbon in public procurement. Code harmonization across Canadian provinces and US states sustains demand visibility without cyclical volatility.
For Market Incumbents: Deploy turnkey installation bundling to capture margin migration from component-only sales. Clayton Homes and Skyline Champion Corporation should deepen captive retail channel control against emerging direct-to-developer competitors. Mass timber specialists must accelerate APA/ANSI certification investment before standards finalize to lock in specification advantages.
For New Entrants and Emerging Players: Digital fabrication capabilities offer entry into precision-engineered cross-laminated timber segments where incumbent automation lags. The US Mountain West presents most penetrable geography as Colorado and Utah municipalities adopt progressive mass timber codes ahead of national timelines. A design-fabricate-erect unbundling strategy targeting university housing authorities bypasses entrenched general contractor relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional panelized home builders lacking turnkey capabilities but holding established contractor relationships. Long-term viability centers on regulatory persistence in carbon-accounting procurement rules. The signal to watch is ANSI/APA standard finalization timing, which will trigger qualification cascades and consolidation among uncertified producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Turnkey Installation Bundling | Captures margin pools migrating from component sales as Pacific Northwest developers disintermediate general contractors. |
| Mass Timber Certification Investment | Secures specification access under CALGreen and British Columbia carbon accounting before ANSI/APA standards finalize. |
| Mountain West Geographic Expansion | Positions capacity in Colorado and Utah ahead of code adoption curves that outpace federal timelines. |
| Digital Fabrication Capability Buildout | Enables just-in-time delivery models that compress carrying costs for Seattle and Vancouver multi-family developers. |
| Forestry-Manufacturing Integration | Reduces raw material transport costs through co-location with coastal Douglas fir supply in British Columbia and Washington. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build segment-level demand models. Primary fieldwork engaged prefab wood manufacturing executives, multi-family development project managers, municipal procurement officers, and mass timber erection contractors. Secondary validation drew from International Code Council amendments, CALGreen standard filings, British Columbia building code bulletins, and US Census construction spending data. Bottom-up project pipeline analysis triangulated against top-down regional construction forecast frameworks.
Segment-weighting approaches distributed value across modular homes, structural insulated panels, panelized homes, and prefabricated beams by end-use intensity. The analytical framework modeled residential, commercial, government, and industrial demand patterns across the projection horizon. CAGRs derived from fitted growth curves applied to disclosed manufacturing capacity and announced facility expansions. Forecast inputs incorporated lumber futures price trajectories and code adoption timelines by state and province.
The model holds under sustained regulatory ratcheting on embodied carbon; deviation in lumber trade policy or adhesive supply disruption would shift volume and value trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gypsum and Drywall Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Global Wall Putty Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Welded Wire Mesh Market