
 India Luxury Vinyl Tile (LVT) Market | 2026-2036
India Luxury Vinyl Tile (LVT) Market Size, Share, and Industry Trends Forecast 2026-2036
India Luxury Vinyl Tile (LVT) Market Foresight
Gujarat's petrochemical corridor is tilting toward PVC resin capacity additions that feed domestic LVT substrate production. Responsive Industries leverages backward integration into PVC compounding to control raw material costs across its flooring division. Inovar Floor anchors its position through specialized distribution networks targeting tier-two city contractors. Polyflor India Pvt Ltd differentiates via hospitality-focused design collections that compete with imported European alternatives.
Luxury Vinyl Tile comprises multi-layer synthetic flooring products built around a PVC core with a printed design layer and wear-resistant transparent top coating, typically manufactured through calendering or extrusion processes that yield dimensional stability under thermal cycling. The material serves commercial and residential environments requiring water resistance, acoustic dampening, and aesthetic replication of natural surfaces. Click-lock rigid core formats are capturing margin pools as installers favor floating-floor systems that reduce subfloor preparation costs. Glue-down products still dominate healthcare end-use specifications where seamless welded installations meet hygiene protocols. Wood-look design styles sustain volume leadership though stone-look variants are gaining traction in premium hospitality fit-outs across South Indian metros.
BIS flooring standards and the CEA's building energy codes are shaping product specifications by mandating thickness tolerances and surface emission thresholds that favor established domestic manufacturers. State-level RERA compliance requirements in Maharashtra and Telangana are accelerating specification-grade material adoption in verified real estate projects. Stakeholders must monitor evolving green building certification benchmarks from IGBC and GRIHA that increasingly credit low-VOC flooring selections in commercial developments.
Market Dynamics
Domestic PVC resin capacity expansion across Gujarat's petrochemical corridor is compressing substrate costs and tilting procurement toward locally manufactured rigid-core formats, fundamentally restructuring supplier economics for flooring manufacturers serving Maharashtra and Karnataka construction pipelines.
Growth Catalysts
- BIS flooring standards tightening:Certification mandates for thickness tolerances and surface emission thresholds are filtering out substandard imports and consolidating specification-grade demand around domestic producers with testing infrastructure.
- Organized retail construction:Mall and hypermarket developers in Mumbai and Bangalore are specifying LVT for high-traffic zones, creating recurring specification demand from anchor tenants and franchise operators.
- Click-lock rigid core technology:Floating-floor installation systems are reducing subfloor preparation costs by 30-40% for commercial fit-outs, accelerating contractor adoption in tier-two city projects.
Market Restraints
- Phthalate plasticizer cost volatility:Input prices for PVC flexibility modifiers fluctuate with crude oil derivatives, squeezing margin predictability for calendering-based manufacturers without backward integration.
- Import dependency for decorative films:High-fidelity wood-grain and stone-look print layers rely on Korean and European suppliers, exposing domestic assemblers to currency risk and extended lead times.
- Welded seam installation skill scarcity:Healthcare specifications requiring seamless glue-down applications face contractor bottlenecks, limiting penetration in hospital operating theaters and pharmaceutical cleanrooms.
Strategic Opportunities
- Telangana RERA compliance acceleration:State-level project verification mandates are elevating material traceability requirements, favoring domestic LVT suppliers with documented BIS certification chains.
- IGBC Green Building certification credits:Low-VOC flooring selections are gaining weighted scoring in commercial developments, opening specification pathways for emissions-tested rigid-core products.
- Tier-two city contractor networks:Distribution partnerships with regional flooring distributors in Pune, Hyderabad, and Chennai are capturing specification influence before projects reach Mumbai procurement desks.
Industry Challenges
- Wear-layer calibration technician shortage:Transparent top-coat thickness consistency requires specialized quality control personnel that domestic manufacturers struggle to retain against polymer industry competitors.
- Multi-format inventory complexity:Simultaneous production of glue-down, click-lock, and loose-lay variants strains working capital and forecasting accuracy for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Luxury Vinyl Tile (LVT) Market |
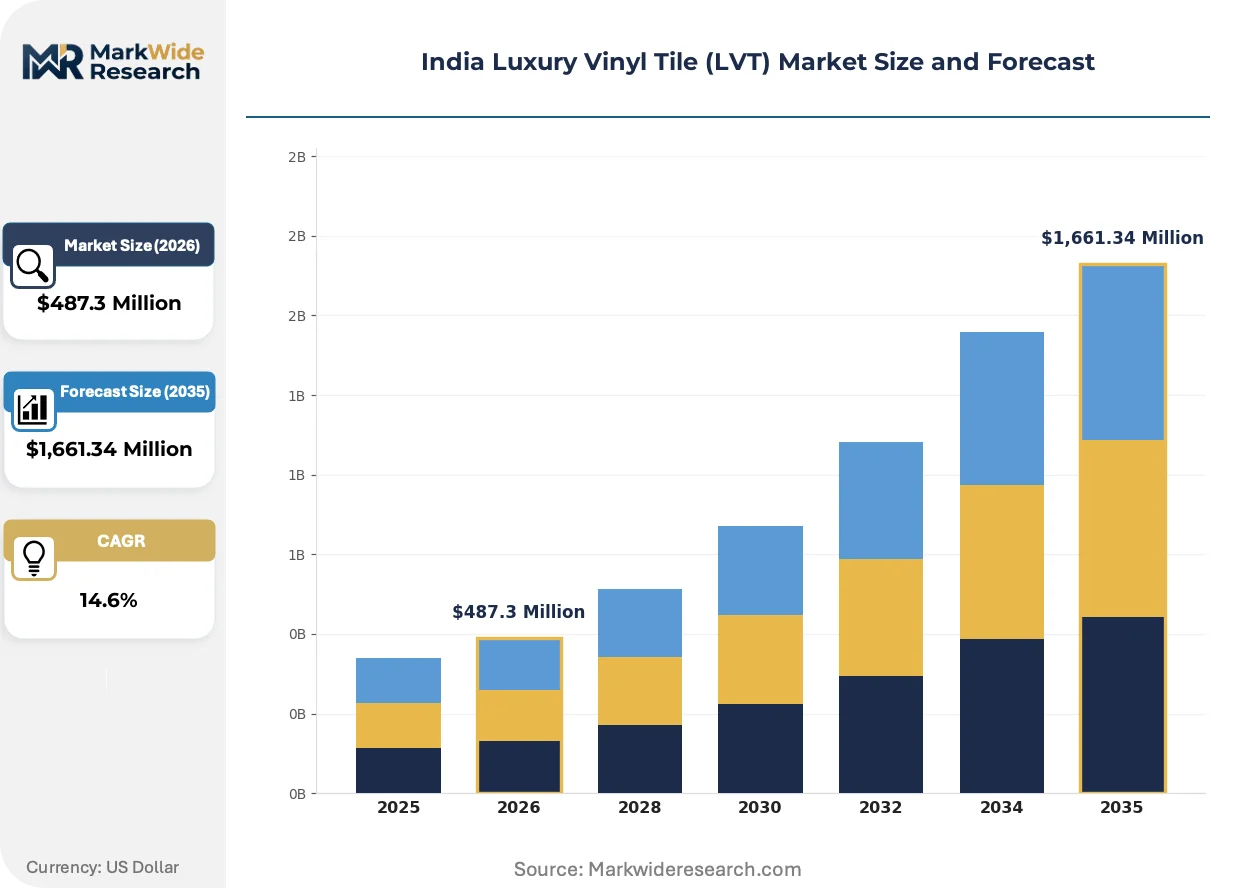
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glue-down, Click-lock, Loose lay, Rigid core End User: Residential, Commercial, Hospitality, Healthcare Thickness: 3mm, 4mm, 5mm, 8mm Design Style: Wood look, Stone look, Abstract, Custom |
| Companies Covered | Responsive Industries, Inovar Floor, Polyflor India Pvt Ltd, Forbo Flooring India Private Limited, Puneet India, Premier Polyfilm Ltd, Gold Leaf International, M/S Weldone Interior Homez Pvt. Ltd., Universal Floorings, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Luxury Vinyl Tile (LVT) Market Shifts & Advancements
Product architecture and installation economics are converging around rigid-core formats that reduce skilled labor dependency, while regulatory pressure on emissions and energy performance is elevating certified domestic supply.
Stone-plastic composite (SPC) core technology is hybridizing traditional vinyl flooring with mineral-filled polymer matrices that deliver dimensional stability under thermal cycling. Hospital facility managers in Bangalore are specifying SPC-backed LVT for diagnostic imaging suites where subfloor moisture resistance is non-negotiable. This material convergence is compressing demand for traditional flexible vinyl sheet goods in premium commercial segments.
CEA building energy codes are mandating surface emission thresholds and thermal performance benchmarks for flooring materials in commercial developments above 20,000 square feet. Developers in Maharashtra are pre-qualifying LVT suppliers based on documented compliance with BIS 15622 thickness tolerances and low-VOC certification. Specifiers are responding by consolidating procurement around domestic manufacturers with in-house testing laboratories.
Project owners are compressing installation timelines by demanding pre-finished flooring systems that eliminate on-site sanding and sealing. General contractors in South Indian metros are substituting traditional tile and hardwood specifications with click-lock LVT that enables parallel trade sequencing. This behavioral shift is most visible in hospitality fit-outs across Chennai and Hyderabad where accelerated opening schedules override material tradition preferences.
India Luxury Vinyl Tile (LVT) Market Segmentation
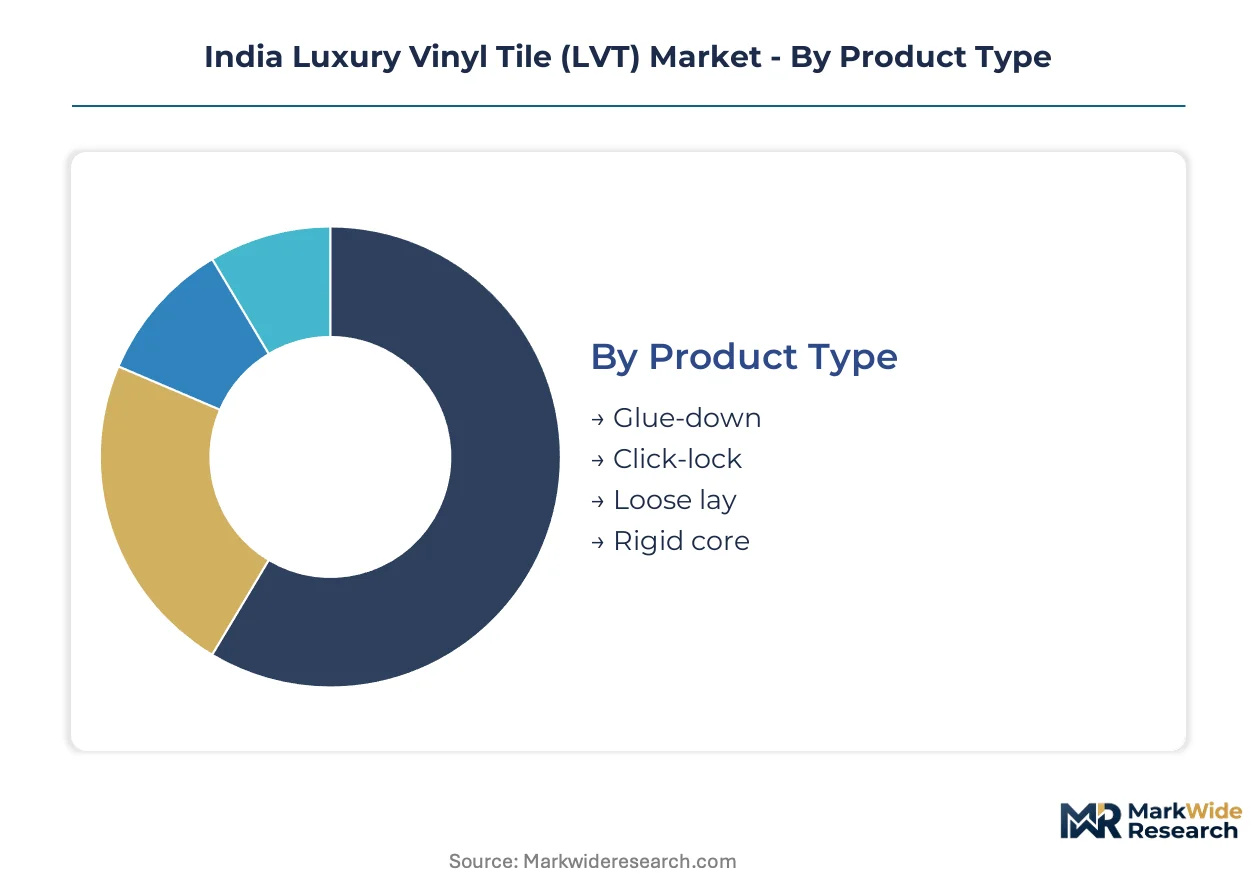
Installer service requirements and subfloor preparation intensity vary dramatically across LVT formats, creating distinct margin profiles and distribution channel economics for each segment. Specification-grade projects in Maharashtra and Karnataka demand differentiated support infrastructure that reshapes competitive positioning by product category.
Product Type:
After-sales service intensity separates winners from commodity suppliers, with installation complexity dictating contractor loyalty and repeat specification rates.
- Glue-down:Permanent adhesive bonding to prepared subfloors delivers superior dimensional stability for heavy rolling loads. Hospital administrators in Bangalore specify welded seam installations for operating theaters where hygiene protocols override speed considerations.
- Click-lock:Interlocking tongue-and-groove edges enable floating-floor installation without adhesives, cutting skilled labor hours by half. Commercial fit-out contractors across Mumbai favor this format for accelerated project timelines in retail and office environments.
- Loose lay:Friction-backed panels rely on perimeter anchoring and dimensional mass for stability, suited for temporary installations and rental property turnovers.
- Rigid core:Mineral-composite substrates provide the highest resistance to subfloor moisture and thermal cycling. SPC-backed variants are displacing flexible vinyl in premium South Indian hospitality developments.
By volume, click-lock leads. By growth pace, rigid core is climbing the fastest.
End User:
Application-specific performance requirements create divergent procurement behaviors, with institutional buyers prioritizing certification documentation over unit economics.
- Residential:Homeowners in tier-two cities prioritize aesthetic replication of hardwood at lower installed cost, driving demand for thinner click-lock formats through regional distributor networks.
- Commercial:Office developers across Hyderabad specify LVT for high-traffic lobbies and elevator banks, with BIS certification mandatory for RERA-compliant projects.
- Hospitality:Hotel operators in Chennai and Pune demand stone-look rigid core for luxury guest rooms where moisture resistance and acoustic performance justify premium positioning.
- Healthcare:Seamless welded installations in diagnostic imaging suites and pharmaceutical cleanrooms require specialized contractor certification that limits supplier options.
Commercial applications dominate current volume. Healthcare represents the steepest expansion trajectory as hospital construction accelerates.
Thickness:
Material cost tiers align with installation durability requirements, with thicker formats commanding specification in premium segments despite higher per-square-meter pricing.
- 3mm:Entry-level flexible vinyl suited for residential bedrooms and light commercial use with minimal traffic loads.
- 4mm:Mid-range specification balancing cost and performance for standard office fit-outs across Maharashtra.
- 5mm:Rigid-core standard for hospitality and retail environments requiring enhanced acoustic dampening and subfloor forgiveness.
- 8mm:Premium mineral-composite construction specified for healthcare and heavy commercial installations where dimensional stability under thermal cycling is critical.
Five-millimeter formats anchor current procurement volume. Eight-millimeter products are gaining share fastest in certified green building projects.
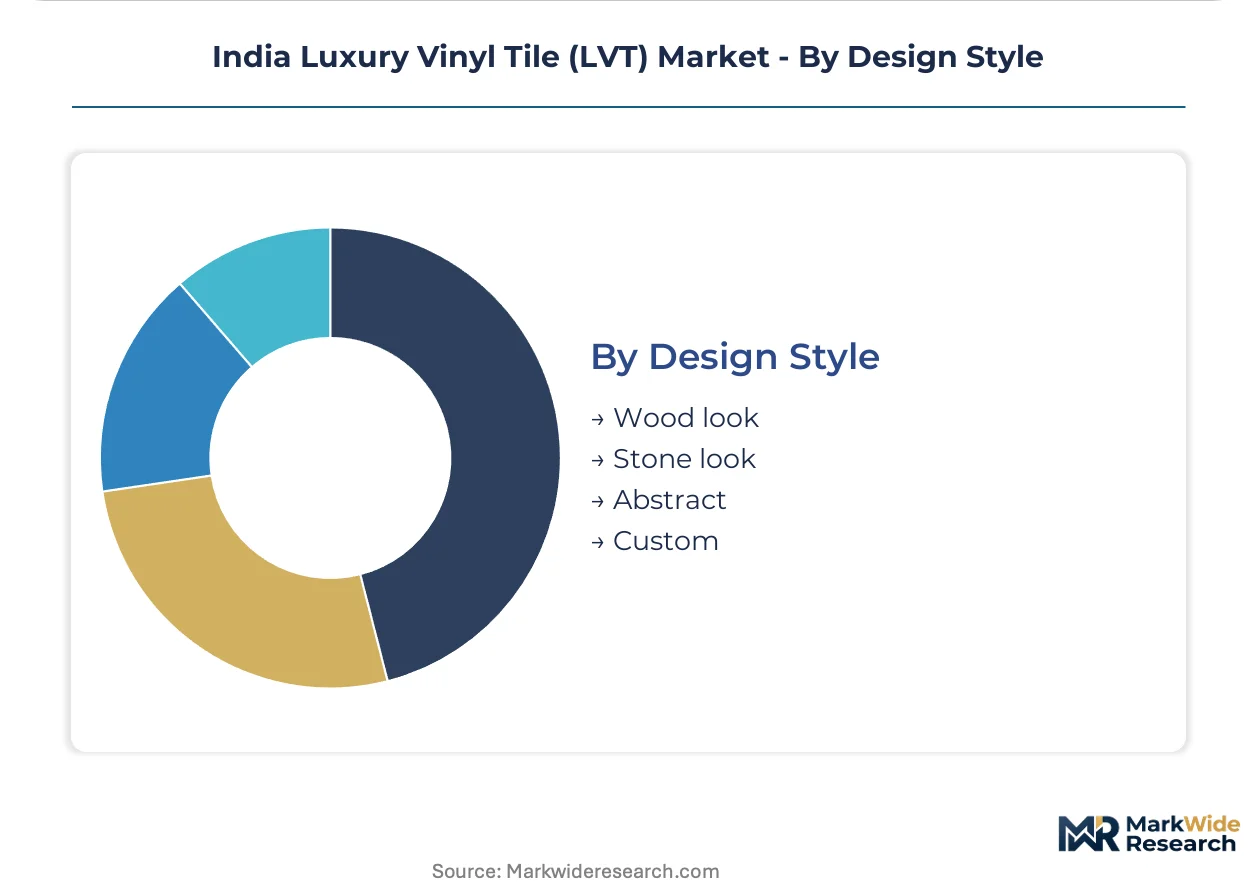
Design Style:
Print layer fidelity and embossing technology differentiation determine specification success, with domestic assemblers competing against Korean and European decorative film imports.
- Wood look:Oak and walnut grain patterns sustain volume leadership across residential and commercial segments. High-fidelity embossing that replicates hand-scraped texture commands specification premiums in Mumbai luxury developments.
- Stone look:Marble and slate replication gains traction in premium hospitality fit-outs across South Indian metros where cool-toned aesthetics align with regional design preferences.
- Abstract:Geometric and terrazzo-inspired patterns target contemporary commercial interiors seeking differentiated visual identity.
- Custom:Digital print-on-demand capabilities serve boutique hotel operators and corporate branding requirements with project-specific color matching.
Wood look maintains volume dominance. Stone look is expanding most quickly as hospitality developers in Bangalore and Chennai specify cooler aesthetic palettes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic PVC resin capacity additions across Gujarat's petrochemical corridor are compressing substrate costs and restructuring procurement economics for flooring manufacturers serving western and southern construction pipelines.
Maharashtra
Mumbai's commercial real estate developers specify rigid-core LVT for high-traffic office lobbies and retail environments, with BIS certification mandatory under state-level RERA compliance requirements. The CEA's building energy codes mandate surface emission thresholds for commercial developments exceeding 20,000 square feet. Organized retail construction in Mumbai and Pune generates recurring specification demand from anchor tenants and franchise operators.
Gujarat
Petrochemical corridor expansions feed domestic LVT substrate production through backward-integrated PVC compounding operations. BIS flooring standards tightening thickness tolerances favor established manufacturers with in-house testing infrastructure. The Vadodara-Surat industrial belt concentrates calendering and extrusion capacity serving national distribution networks.
Karnataka
Bangalore's hospital construction pipeline drives specification-grade demand for seamless welded installations in diagnostic imaging suites and pharmaceutical cleanrooms. State-level project verification mandates elevate material traceability requirements. Healthcare facility managers specify SPC-backed LVT for moisture-critical environments.
Telangana
Hyderabad's accelerating RERA compliance creates specification pathways for domestic suppliers with documented certification chains. Commercial office developers specify click-lock formats for accelerated fit-out timelines. Regional distributor partnerships in Hyderabad capture specification influence before projects reach Mumbai procurement desks.
Tamil Nadu
Chennai's hospitality fit-outs drive stone-look rigid-core demand where accelerated opening schedules override traditional material preferences. Low-VOC flooring selections gain weighted scoring in IGBC Green Building certification credits. Hotel operators specify premium mineral-composite construction for luxury guest room applications.
India Luxury Vinyl Tile (LVT) Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream controlling raw material conversion economics. The vendor base organizes around three tiers: petrochemical-backed producers with captive resin supply, specialized flooring assemblers with distribution network scale, and regional fabricators serving contractor-direct procurement. Consolidation pressures favor players with backward integration into PVC compounding and in-house decorative film sourcing capabilities. Capacity expansion and certification infrastructure investment represent the dominant competitive moves as BIS standards filter substandard imports.
Among domestic petrochemical-integrated producers, Responsive Industries anchors the upstream tier through captive PVC compounding operations. Inovar Floor occupies a position within specialized distribution networks targeting tier-two city contractors. Polyflor India Pvt Ltd exemplifies the design-differentiated archetype competing with imported European alternatives in hospitality-focused segments. These three represent distinct strategic postures: raw material control, channel depth, and aesthetic specialization.
| Leading Market Players |
|---|
| Responsive Industries |
| Inovar Floor |
| Polyflor India Pvt Ltd |
| Forbo Flooring India Private Limited |
| Puneet India |
| Premier Polyfilm Ltd |
| Gold Leaf International |
| M/S Weldone Interior Homez Pvt. Ltd. |
| Universal Floorings |
| Others |
Supply & Pricing Matrix
Gujarat's petrochemical corridor concentrates domestic PVC resin production, compressing substrate costs and anchoring margin pools with manufacturers possessing backward integration into PVC compounding. This upstream concentration enables domestic producers to undercut import-dependent assemblers while BIS certification requirements create pricing premiums for specification-grade products.
Pricing Analysis
BIS flooring standards dictate the pricing tier structure across the India LVT market by mandating thickness tolerances and surface emission thresholds that filter substandard imports. Three-tier pricing stratifies across premium rigid-core SPC formats, mid-range click-lock systems, and economy glue-down sheets. Price differentiation rests on certification grade and wear-layer thickness consistency. Cost compression in entry-level flexible vinyl intensifies as Gujarat resin capacity expands. Residential buyers in tier-two cities exhibit highest price sensitivity, while healthcare procurement committees prioritize certified supply chains over unit economics.
Supply Chain Analysis
Import dependency for decorative print films between South Korea and domestic assemblers dominates supply chain risk exposure for high-fidelity wood-grain and stone-look layers. Raw material sourcing draws from Gujarat for PVC resin, South Korea for decorative films, and domestic compounding operations for mineral fillers. Single-source vulnerability concentrates in Korean print layer suppliers, exposing assemblers to currency fluctuation and extended lead times. Distribution runs through specialized flooring distributors in Mumbai and Bangalore before reaching tier-two city contractor networks in Pune, Hyderabad, and Chennai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India LVT market rewards players controlling scarce technical capabilities—wear-layer calibration expertise and seamless welded installation certification—that limit competitive replication and sustain pricing power in specification-grade segments.
For Market Incumbents: Build captive resin supply moats through backward integration into Gujarat PVC compounding operations. Incumbents should expand in-house decorative film sourcing capabilities to reduce Korean import dependency, while investing BIS certification infrastructure to filter substandard competitors from RERA-compliant project pipelines. For New Entrants and Emerging Players: Mid-market commercial buildings in Telangana and Tamil Nadu represent the most penetrable entry point given accelerating RERA compliance and specification-grade material traceability requirements. New entrants should target regional distributor partnerships in Hyderabad and Chennai to capture specification influence before projects reach Mumbai procurement desks, leveraging click-lock rigid core formats that reduce contractor skill barriers. For Investors and Strategic Acquirers: Capital is best deployed toward domestic manufacturers with documented BIS certification chains and in-house testing laboratories positioned for healthcare and green building specification growth. Long-term viability hinges on consolidation around players controlling both substrate production and distribution network scale. The signal to monitor is IGBC Green Building certification credit expansion for low-VOC flooring selections in commercial developments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Compounding | Gujarat resin capacity anchors cost control for domestic manufacturers against import-dependent competitors. |
| BIS Certification Infrastructure Investment | In-house testing laboratories filter substandard imports from Maharashtra and Karnataka project pipelines. |
| Regional Distribution Partnership Expansion | Tier-two city networks in Pune and Hyderabad capture specification influence before Mumbai procurement consolidation. |
| Healthcare Installation Certification Programs | Welded seam contractor training opens penetration in Bangalore hospital operating theaters and pharmaceutical cleanrooms. |
| Low-VOC Product Portfolio Development | Emissions-tested rigid core formats gain weighted scoring in IGBC Green Building certification credits. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with flooring division heads, commercial real estate developers, hospital facility managers, and regional distributor principals; and secondary validation through BIS certification records, CEA building energy code filings, state-level RERA project databases, and customs trade data for PVC resin and decorative film imports. Bottom-up volume estimates from product format and end-use segmentation were triangulated against top-down construction pipeline values across Maharashtra, Karnataka, Telangana, and Tamil Nadu.
Forecast inputs incorporated product type evolution, thickness format migration, and design style preferences across the projection horizon. Segmentation dimensions modeled include installation system, end-use application, material thickness tier, and aesthetic category. CAGRs were derived from elasticity-adjusted demand projections tied to commercial real estate completions and hospital construction permits. Industry-specific inputs encompassed BIS standard implementation timelines and IGBC Green Building certification adoption curves.
Stress conditions across resin price volatility, import tariff fluctuations, and contractor skill scarcity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and specification-grade procurement behavior. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Steel Sections Market
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
GCC Exterior Sheathing Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Door Canopy Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Europe Geogrids Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
Fire Rated Glass Market