
 Softwood Lumber Market | 2026-2036
Softwood Lumber Market Size, Share, and Industry Trends Forecast 2026-2036
Softwood Lumber Market Analysis
Subscription-based forest management and yield-optimization software is realigning how timber rights and harvest schedules get bundled into long-term supply contracts. Weyerhaeuser Company leverages its vast Pacific Northwest timberland base to sustain vertically integrated production from seedling to mill. West Fraser Timber Co. Ltd. anchors Canadian supply through large-scale interior British Columbia sawmilling complexes that dominate North American SPF distribution.
Softwood lumber consists of processed timber from gymnosperm tree species, typically kiln-dried to moisture content below nineteen percent and graded by visual or machine stress rating for load-bearing performance. Its primary commercial purpose centers on structural framing, sheathing, and engineered wood products for buildings and infrastructure. Pine and spruce categories lead volume throughput across North American and Nordic markets, while cedar commands premium positioning in exterior applications and decorative grades where natural decay resistance justifies higher price realization. Structural grades capture the deepest margin pools as building code compliance and engineering certification requirements tighten specification tolerances.
The USDA Forest Service and Lacey Act enforcement in the United States, combined with EU Timber Regulation due diligence obligations and Canadian Standards Association sustainable forest management criteria, collectively shape chain-of-custody documentation requirements and market access conditions for imported and domestic material alike. These frameworks elevate compliance costs for uncertified producers while rewarding holders of FSC or PEFC chain-of-custody credentials with preferred supplier status. Stakeholders must monitor evolving mass timber building code adoptions and biogenic carbon accounting methodologies to anticipate which grade and species combinations will capture tomorrow's structural specification premiums.
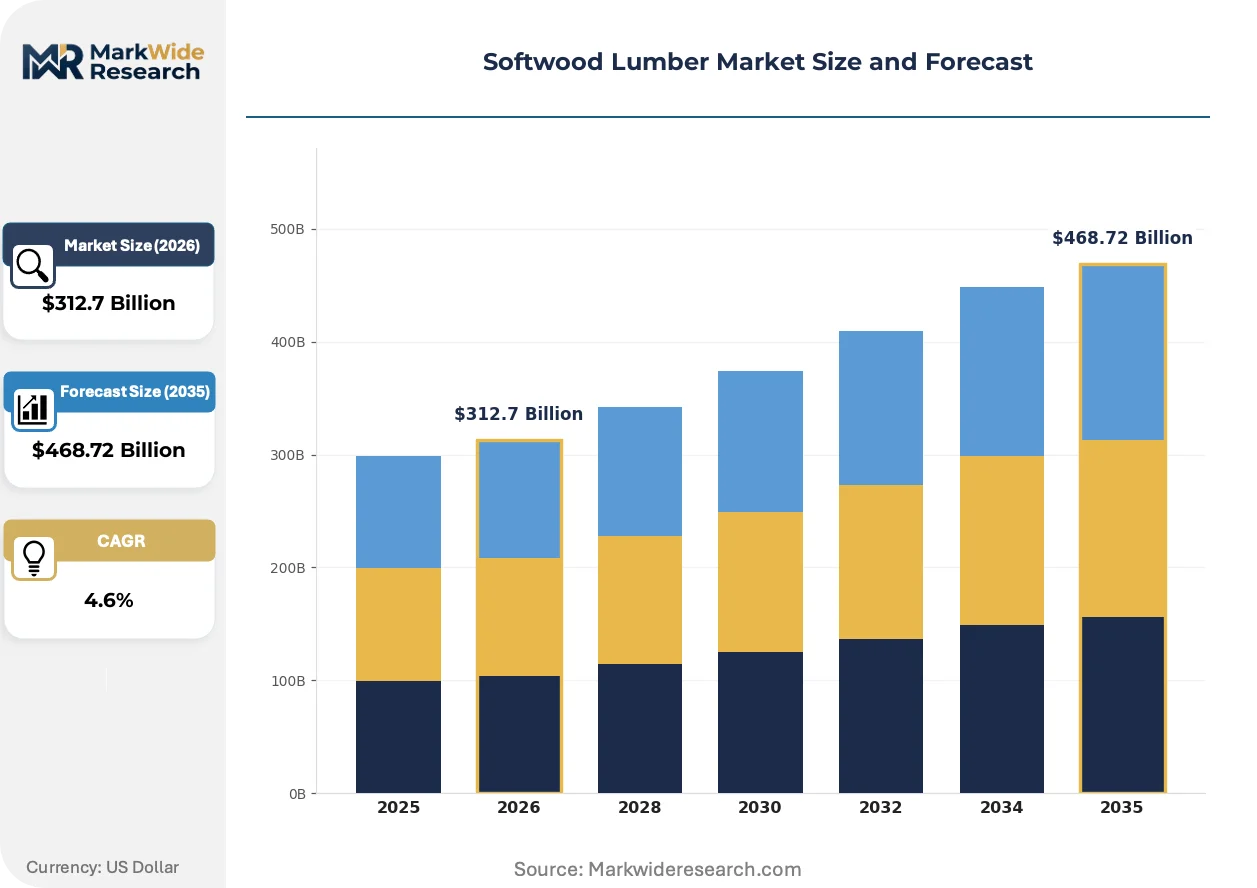
Market Dynamics
Mass timber building codes and biogenic carbon accounting methodologies are compressing specification cycles for structural grades while redirecting procurement toward certified supply chains with full chain-of-custody documentation.
Growth Catalysts
- EU Timber Regulation due diligence:Mandatory chain-of-custody verification for European Union imports is elevating demand for FSC and PEFC certified material, locking out uncertified suppliers.
- Mass timber construction:Cross-laminated timber and glulam adoption in mid-rise commercial and institutional buildings is expanding addressable volume for high-grade Douglas fir and spruce-pine-fir structural products.
- Coastal British Columbia fiber access:Proximity to Pacific Rim export markets and deepwater port infrastructure concentrates premium hemlock and Douglas fir supply for Japanese and Chinese specification markets.
Market Restraints
- Diesel and ocean freight volatility:Harvest equipment fuel costs and trans-Pacific container rates inject margin instability into delivered lumber pricing, particularly for British Columbia export-dependent producers.
- Interior British Columbia sawmilling concentration:SPF dimension lumber output clusters in a narrow geographic band vulnerable to wildfire, beetle infestation, and rail corridor disruption.
- Steel and concrete substitution in seismic zones:Building code exceptions and engineering familiarity with conventional materials limit mass timber penetration in high-severity earthquake regions of California and Japan.
Strategic Opportunities
- German and Austrian tall-wood codes:Regulatory mandates permitting 8-12 story timber structures create specification pull for North American coastal species with proven glulam performance data.
- Subscription yield-optimization software:Forest management platforms bundling harvest scheduling with long-term supply contracts enable mill-direct relationships bypassing traditional broker channels.
- Carbon-negative building procurement:Biogenic carbon accounting in LEED v4.1 and similar frameworks positions certified softwood as a compliance material for corporate net-zero construction commitments.
Industry Challenges
- Certified grader workforce scarcity:Visual and machine stress rating certification programs face enrollment gaps, creating inspection bottlenecks at high-throughput British Columbia and Pacific Northwest facilities.
- Kiln drying energy intensity:Natural gas and electricity costs for moisture reduction to sub-19 percent targets strain margin structures, particularly for lower-grade commodity production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Softwood Lumber Market |
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $468.72 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pine, Spruce, Fir, Cedar End Use: Construction, Furniture, Packaging, Flooring Grade: Common Grades, Select Grades, Structural Grades, Premium Grades Distribution Channel: Retail, Wholesale, Online, Direct Sales |
| Companies Covered | Canfor Corporation, Georgia-Pacific LLC, Weyerhaeuser Company, Hampton Affiliates, Tolko Industries Ltd., West Fraser Timber Co. Ltd., Interfor Corporation, Resolute Forest Products Inc., Sierra Pacific Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Softwood Lumber Market Emerging Trajectories
Digitalization of forest inventory and automated sawline optimization are compressing grade recovery variance while machine learning applications in defect detection reshape quality control protocols across primary processing.
Machine stress-rated lumber is overtaking visual grading for structural specification in multi-family residential and light commercial construction. Engineered wood product manufacturers and prefabricated wall panel fabricators specify MSR material for predictable load-bearing performance. This standardization is compressing grade arbitrage opportunities and consolidating procurement around certified mechanical rating systems.
EU Green Deal carbon border adjustment mechanisms and the CSRD corporate sustainability reporting directive are tightening documentation requirements for imported construction materials. European Union member states now require embodied carbon declarations for public procurement above threshold contract values. Nordic and German mass timber developers are responding by sourcing exclusively from PEFC or FSC chain-of-custody certified North American suppliers with third-party verified carbon inventories.
Buyers in multi-family residential development and institutional construction are consolidating vendor relationships around vertically integrated suppliers with captive timberland and in-house grading certification. Long-term offtake agreements with fixed-price escalators are displacing spot market purchasing for project pipelines exceeding 24 months duration. This concentration is most visible in United States Pacific Coast markets where developer-scale mass timber projects require grade consistency across multi-year build schedules.
Softwood Lumber Market Segmentation
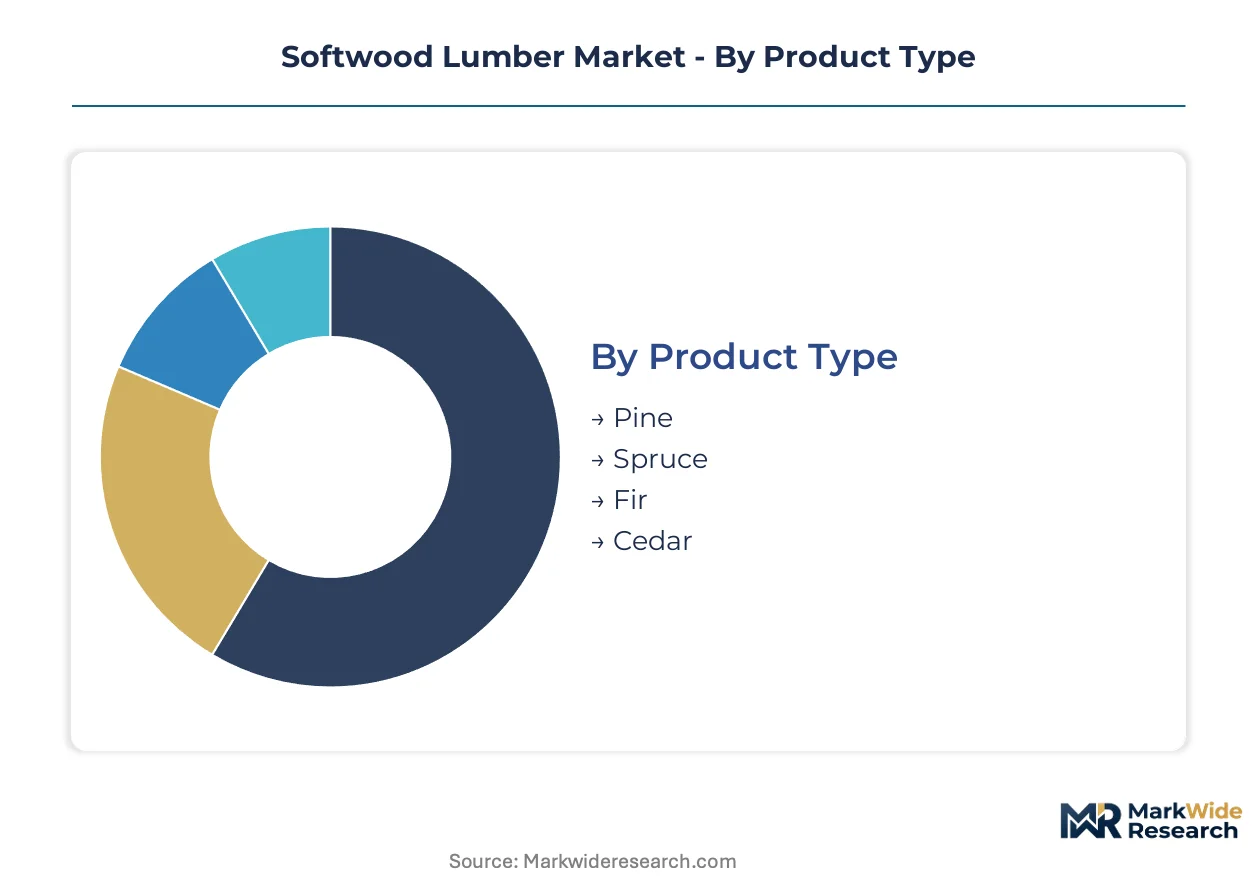
Softwood lumber procurement splits along structural performance requirements, moisture specifications, and certification tiers that determine building code compliance. Buyers prioritize grade consistency and chain-of-custody documentation over commodity pricing in multi-year construction pipelines.
Product Type:
Species selection differentiates buyers by decay resistance needs, structural modulus, and regional availability constraints.
- Pine:Southern yellow pine and lodgepole pine dominate SPF dimension lumber production with high strength-to-weight ratios for platform framing. Demand concentrates in United States multi-family residential construction where machine stress-rated SPF studs satisfy engineered specifications.
- Spruce:White and Engelmann spruce grades serve cold-climate markets with superior dimensional stability during freeze-thaw cycles. Canadian interior British Columbia sawmills ship spruce-heavy SPF mixes to Midwestern United States markets for stick-frame housing.
- Fir:Douglas fir and balsam fir provide high specific gravity for glulam and cross-laminated timber feedstock.
- Cedar:Western red cedar commands exterior siding and decking premiums through natural extractive resistance.
Pine leads volumes today; cedar is gaining share fastest in high-performance exterior specifications.
End Use:
Application-driven procurement separates commodity volume buyers from specification-sensitive project developers.
- Construction:Structural framing absorbs kiln-dried studs, joists, and engineered wood product feedstock across single-family, multi-family, and mass timber commercial segments. United States Pacific Northwest and British Columbia coastal mills supply Douglas fir glulam laminations for German and Austrian tall-wood building codes.
- Furniture:Clear grades and appearance specifications drive kiln-dried pine and alder demand for case goods and upholstered frame manufacturing.
- Packaging:Lower-grade SPF and hemlock serve pallet, crate, and dunnage applications with minimal drying requirements.
- Flooring:Vertical grain and select appearance grades of Douglas fir and yellow pine target restoration and premium residential installations.
Construction leads volumes today; mass timber commercial applications are climbing the fastest.
Grade:
Margin capture separates visual-graded commodity producers from machine-rated certified suppliers.
- Structural Grades:Machine stress-rated and visually graded lumber for load-bearing walls, floors, and roofs carries engineering certification requirements. United States building code adoption of MSR material in prescriptive tables is compressing visual grade arbitrage in multi-family construction.
- Select Grades:Clear appearance specifications with minimal knot content serve millwork, furniture, and premium interior applications.
- Common Grades:Standard and utility grades with relaxed knot and wane tolerances fill sheathing, blocking, and temporary construction demand.
- Premium Grades:Appearance-grade clear and vertical grain material commands specification premiums in historic restoration and architect-driven commercial interiors.
Structural grades lead volumes today; premium grades are expanding most quickly in carbon-negative building procurement.
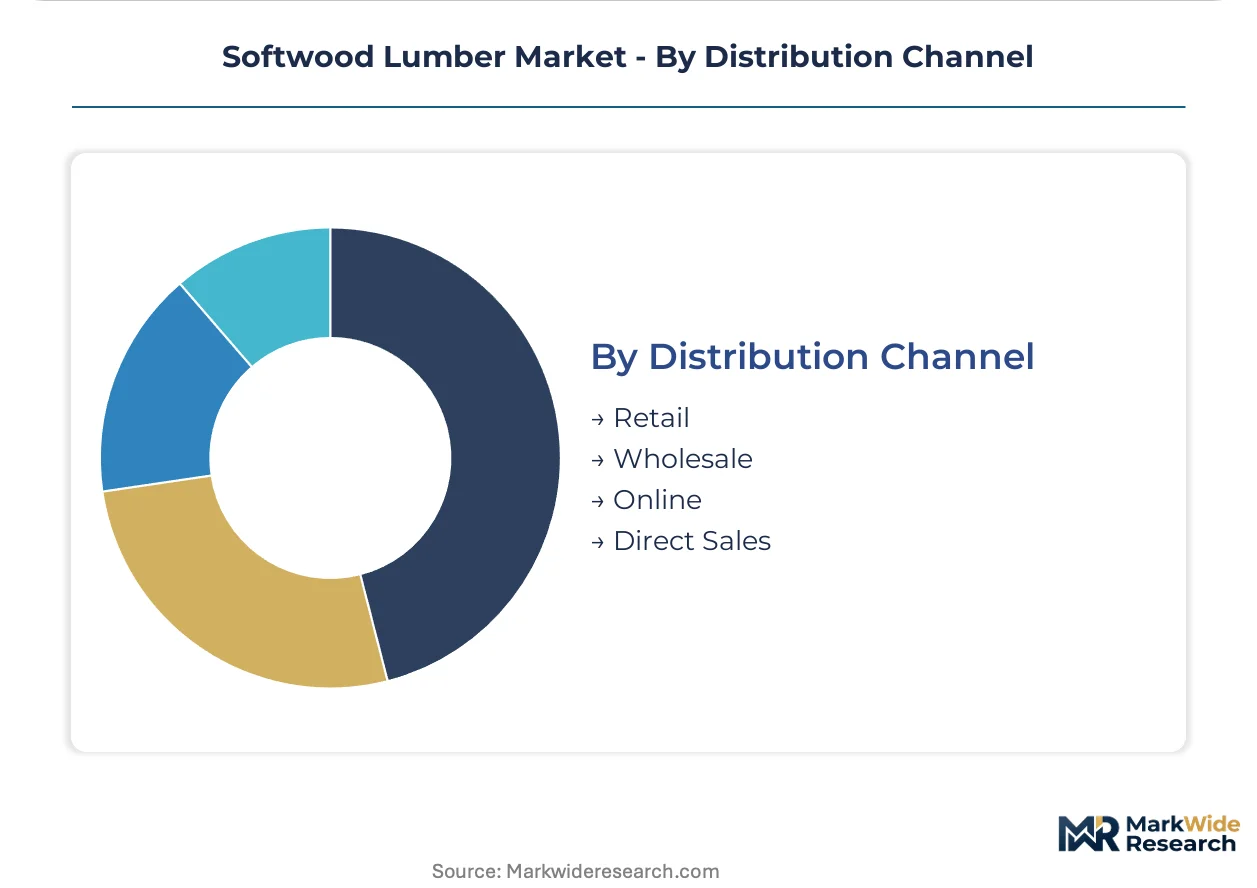
Distribution Channel:
Channel selection reflects project scale, certification documentation needs, and inventory carrying capacity.
- Wholesale:Distributor and pro-dealer yards aggregate mixed truckload and railcar volumes for regional contractor and retail lumberyard supply. British Columbia interior sawmills route SPF dimension lumber through Calgary and Minneapolis distribution centers to capture Midwestern United States housing starts.
- Direct Sales:Mill-direct procurement with fixed-price escalators locks grade consistency for developer-scale mass timber projects exceeding 24-month build schedules.
- Retail:Big-box and independent lumberyards serve repair-and-remodel demand with pre-cut dimensional stock and project packs.
- Online:Digital platforms aggregate certified specialty grades and appearance products for specification buyers requiring chain-of-custody documentation.
Wholesale leads volumes today; direct sales are gaining share fastest in multi-year mass timber offtake agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada commands larger export volumes than the United States, yet American domestic consumption absorbs more absolute board feet annually. This divergence shapes procurement patterns across both nations. Germany and Austria now import North American coastal species for tall-wood construction mandates.
United States
Multi-family residential construction in Texas and Florida drives SPF stud consumption through machine stress-rated specifications. The USDA Forest Service enforces Lacey Act chain-of-custody documentation for imported material. Pacific Northwest mills in Oregon and Washington supply Douglas fir glulam laminations to German mass timber developers seeking proven seismic performance data.
Canada
Interior British Columbia sawmills ship dimension lumber to Midwestern United States markets via Calgary distribution nodes. Canadian Standards Association sustainable forest management criteria elevate compliance costs for uncertified producers. Coastal British Columbia fiber access concentrates premium hemlock and Douglas fir supply for Japanese specification markets through Vancouver port infrastructure.
Germany
Tall-wood building codes mandating 8-12 story timber structures create specification pull for North American coastal species. EU Green Deal carbon border adjustment mechanisms tighten documentation requirements for imported construction materials. Bavarian and Baden-Württemberg mass timber developers source exclusively from PEFC or FSC chain-of-custody certified suppliers with third-party verified carbon inventories.
Japan
Post-and-beam traditional construction maintains steady demand for high-grade Douglas fir and hemlock from British Columbia. METI building code exceptions for seismic zones limit mass timber penetration in high-severity earthquake regions. Tokyo and Osaka metropolitan area developers specify coastal British Columbia species for commercial interiors requiring chain-of-custody certification.
Sweden
Mass timber building code adoptions in Stockholm and Gothenburg expand addressable volume for spruce-pine-fir structural products. EU Timber Regulation due diligence obligations lock out uncertified suppliers from public procurement above threshold contract values. Nordic glulam manufacturers import North American Douglas fir to supplement domestic spruce feedstock for engineered wood product lines.
Softwood Lumber Market Vendor Landscape
Top-tier vendors anchor integrated timberland-to-mill operations, while mid-scale sawmillers compete on grade recovery and regional logistics efficiency. The vendor base clusters around three strategic archetypes: timberland-owning integrated producers, independent sawmillers with broker-dependent distribution, and subscription-software-enabled yield optimizers. Competitive moves concentrate on long-term offtake agreements with fixed-price escalators and backward integration into captive timberland bases.
Among North American integrated producers, Weyerhaeuser Company and West Fraser Timber Co. Ltd. exemplify timberland-heavy structures with in-house grading certification. Canfor Corporation occupies a position within the Canadian interior sawmilling tier. These entities represent the consolidation trajectory as developer-scale mass timber projects demand grade consistency across multi-year build schedules and procurement shifts toward mill-direct relationships.
| Leading Market Players |
|---|
| Canfor Corporation |
| Georgia-Pacific LLC |
| Weyerhaeuser Company |
| Hampton Affiliates |
| Tolko Industries Ltd. |
| West Fraser Timber Co. Ltd. |
| Interfor Corporation |
| Resolute Forest Products Inc. |
| Sierra Pacific Industries |
| Others |
Supply Flow & Price Mechanics
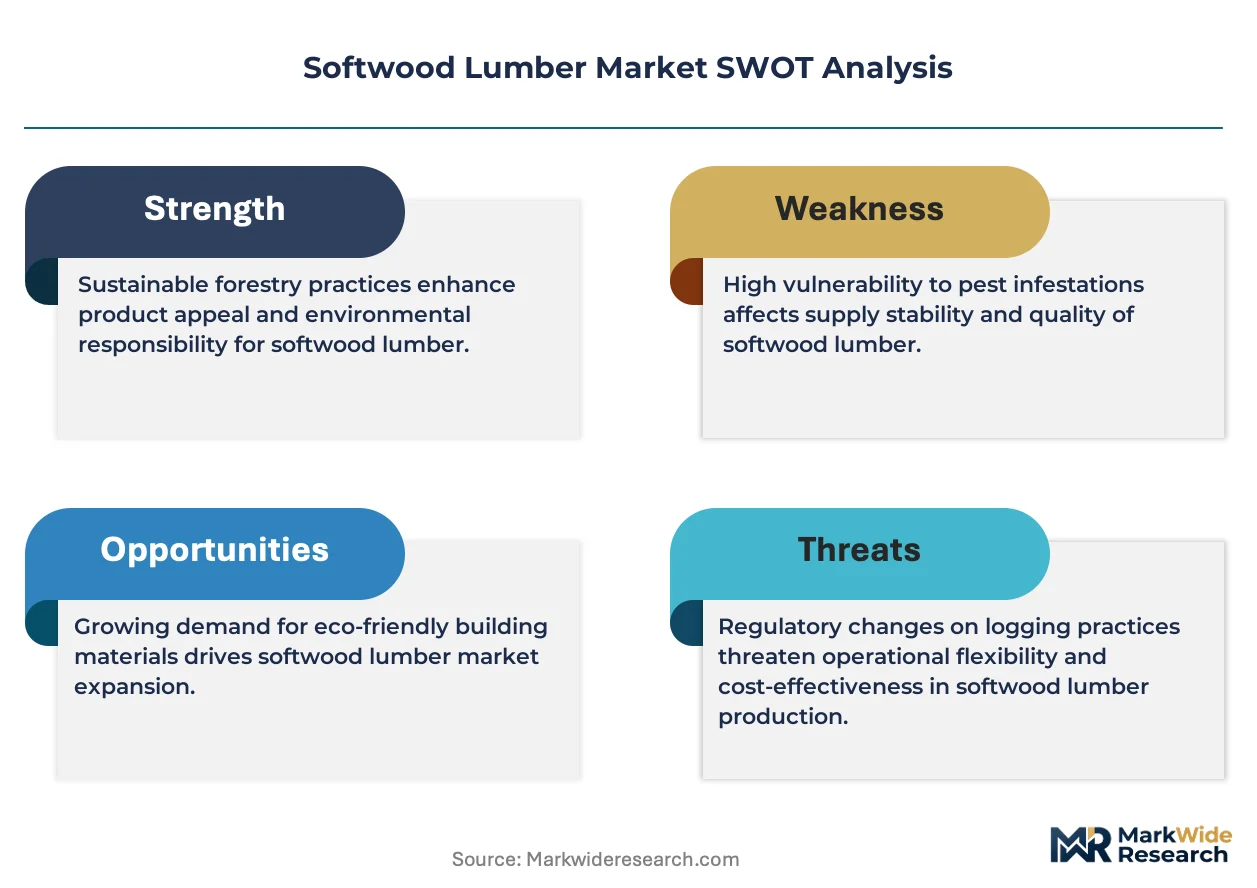
Certification-grade bifurcation between FSC/PEFC chain-of-custody material and uncertified commodity supply concentrates pricing power among integrated Pacific Northwest producers while forcing spot-market buyers into volatile procurement cycles. This divergence manifests in contract structures: long-term offtake agreements with fixed-price escalators anchor premium-tier transactions, while interior British Columbia SPF flows through broker-dependent wholesale channels exposed to diesel and ocean freight volatility.
Pricing Analysis
Capacity additions in Nordic glulam manufacturing are reshaping price floors for high-grade Douglas fir laminations, compressing arbitrage windows for North American coastal mills. Three-tier pricing structure across certified structural, standard kiln-dried, and green rough-sawn economy levels differentiates buyers by specification tolerance and documentation burden. Cost compression in lower-grade SPF dimension lumber is intensifying because interior British Columbia sawmilling concentration amplifies rail and wildfire disruption risk. Multi-family residential developers show highest price sensitivity, while German tall-wood project sponsors absorb premiums for verified carbon inventories and seismic performance data.
Supply Chain Analysis
Ocean freight rate volatility and trans-Pacific container availability inject margin instability into British Columbia export-dependent producers serving Japanese post-and-beam and Chinese industrial markets. Geographic supply concentration centers on Canada, the United States, and Sweden, with coastal British Columbia fiber access and Pacific Northwest timberland bases anchoring premium hemlock and Douglas fir output. Raw material dependencies rest on seedling nursery capacity, diesel-dependent harvesting equipment, and natural gas for kiln-drying energy intensity. Single-source vulnerability runs through concentrated interior British Columbia SPF sawmilling corridors vulnerable to beetle infestation and rail corridor disruption. Distribution runs through Calgary and Minneapolis distribution nodes for Midwestern United States housing starts, with mill-direct procurement gaining share in developer-scale mass timber pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement consolidation around certified structural grades rewards integrated timberland owners. Mass timber building code adoptions in Germany and Austria pull specification demand toward coastal species with proven glulam performance data.
For Market Incumbents: Acquire certified grader workforce capacity and machine stress-rating infrastructure to capture inspection bottleneck premiums at high-throughput British Columbia and Pacific Northwest facilities. Defensive consolidation moves should center on backward integration into captive seedling-to-mill timberland bases and long-term offtake agreements with fixed-price escalators that lock out spot-market competitors. Steel and concrete substitution threats in California and Japanese seismic zones demand R&D investment in hybrid structural systems that preserve timber specification share. For New Entrants and Emerging Players: Subscription-software forest management platforms offer channel partner entry points that bypass traditional broker networks by bundling harvest scheduling with mill-direct supply contracts. White-space targets include carbon-negative building procurement mandates under LEED v4.1 and corporate net-zero construction commitments, where third-party verified carbon inventories command specification premiums. The most penetrable segment sits in online digital platforms aggregating certified specialty grades for specification buyers requiring chain-of-custody documentation. For Investors and Strategic Acquirers: Consolidation pressure builds where certified grader workforce scarcity and kiln-drying energy intensity strain margin structures for independent sawmillers without timberland integration. Long-term viability across the projection horizon favors vertically integrated producers with in-house grading certification and Pacific Northwest or coastal British Columbia fiber access. Acquisition target archetypes include mid-scale interior British Columbia sawmillers with broker-dependent distribution vulnerable to rail disruption and wildfire risk. The signal to watch is mass timber building code adoption velocity in German and Austrian jurisdictions, which determines addressable volume expansion for North American coastal species.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timberland Bases | Captive fiber supply secures grade consistency for multi-year mass timber offtake agreements with German developers. |
| Machine Stress-Rating Certification Investment | MSR infrastructure captures specification premiums as United States building codes compress visual grade arbitrage opportunities. |
| Long-term Supply Agreement with Fixed-Price Escalators | Contract structures displace spot-market purchasing for developer-scale projects exceeding 24-month build schedules. |
| Subscription Yield-Optimization Platform Launch | Forest management software bundles harvest scheduling with mill-direct relationships that bypass traditional broker channels. |
| PEFC/FSC Chain-of-Custody Certification Program | EU Timber Regulation due diligence obligations lock out uncertified suppliers from European public procurement thresholds. |
Methodological Framework
Direct dialogue with sawmill operations managers, timberland asset directors, mass timber project developers, and procurement officers at multi-family residential developers grounded qualitative findings in operational reality. Secondary validation drew from USDA Forest Service timber output data, Canadian Standards Association sustainable forest management filings, EU Timber Regulation enforcement disclosures, and British Columbia coastal export statistics. Bottom-up and top-down triangulation reconciled facility-level production capacity with national housing start projections and mass timber building code adoption timelines.
Bottom-up modeling aggregated individual sawmill throughput by species and grade tier, while top-down analysis calibrated against regional construction spending and engineered wood product consumption patterns across the analysis window. Segmentation dimensions included species category, structural grade certification level, end-use application, and distribution channel archetype. CAGRs derived from regression analysis of historical price realization and volume shipment data, with forecast inputs incorporating diesel and ocean freight futures, wildfire risk-adjusted fiber availability, and mass timber code adoption velocity in German and Austrian jurisdictions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biogenic carbon accounting methodology shifts, seismic code exceptions in high-risk zones, and trans-Pacific trade policy volatility. Forecasts reflect assumptions about sustained residential construction activity and continued regulatory preference for certified supply chains. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Aluminum Curtain Wall Market
Building & Construction Materials
Skirting Board Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Sheet Metal Market
Building & Construction Materials
Modular Commercial Building System Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market
Building & Construction Materials
East Africa Gypsum Plaster Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
PVC Window Market