
 Egypt Prefab Wood Buildings Market | 2026-2036
Egypt Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Prefab Wood Buildings Market Analysis
Grade-A engineered wood certification is collapsing the price gap between conventional concrete and prefab timber in Egypt's premium construction segment. Stora Enso leverages its Nordic supply chain to dominate cross-laminated timber imports into Alexandria Port. Karmod Prefabricated Technologies anchors turnkey resort contracts across the Red Sea coast. ICON Egypt differentiates through lightweight frame systems designed for seismic zones in Greater Cairo.
Prefab wood buildings are factory-manufactured structures using standardized timber components, engineered wood products, or structural insulated panels assembled offsite and transported for installation, typically achieving 30-50% faster construction cycles than cast-in-place methods. Egypt's hospitality sector drives demand for modular cabins and portable structures in coastal tourism zones, where speed-to-occupancy commands premium returns. Residential end users gravitate toward timber frame and SIPs technologies as mortgage lenders gradually accept prefab collateral in gated communities outside Cairo. Engineered wood competes aggressively with lightweight frame systems in commercial educational facilities, where fire-rated specifications and acoustic performance determine specification outcomes.
Egypt's Housing and Building National Research Center sets material standards for prefab structural systems, while the New Urban Communities Authority governs land-use compliance in satellite cities. BIS-aligned import protocols for engineered wood products shape supplier access and customs clearance timelines. Stakeholders must monitor how Egypt's central bank construction financing rules evolve for factory-built housing, as mortgage liquidity will determine whether prefab timber escapes niche resort and luxury residential positioning.
Market Dynamics
Egypt's prefab wood buildings sector pivots on the New Urban Communities Authority's recognition of engineered wood for mid-rise construction, which compresses compliance timelines and redirects capital flows from concrete-dominated supply chains into timber frame systems.
Growth Catalysts
- Regulatory Recognition:The New Urban Communities Authority building codes now permit engineered wood in mid-rise structures, eliminating previous height restrictions that confined timber to single-story applications.
- Tourism Corridor Demand:Red Sea hospitality developers specify modular timber cabins to accelerate speed-to-occupancy and capture premium seasonal returns before concrete alternatives complete.
- Cross-Laminated Timber:Grade-A certification protocols from the Housing and Building National Research Center collapse performance uncertainty, enabling mortgage lenders to accept prefab collateral in gated communities.
Market Restraints
- Import Concentration Risk:Engineered wood supply concentrates at Alexandria Port through Nordic shipping lanes, exposing developers to customs clearance volatility and currency fluctuation.
- Concrete Substitution Threat:Local cement producers maintain cost advantages in mass housing segments through subsidized energy inputs and established distribution networks.
- Fire-Rating Friction:The Housing and Building National Research Center mandates additional intumescent coating layers for educational facilities, extending specification timelines against competing steel frame systems.
Strategic Opportunities
- Seismic Zone Applications:Greater Cairo's earthquake-prone districts present untapped demand for lightweight frame systems that reduce foundation loads and structural mass.
- New Administrative Capital:Government-mandated sustainability targets in this satellite city create procurement preferences for timber structures with verified carbon footprints.
- Digital Fabrication Convergence:CNC machining integration with BIM workflows enables mass-customized panel production, compressing design-to-installation cycles for boutique hospitality projects.
Industry Challenges
- Skilled Assembly Shortage:Egypt's construction workforce lacks certified installers for structural insulated panel connections, forcing manufacturers to deploy foreign supervision teams.
- Financing Documentation Gaps:Central bank construction lending rules lack standardized collateral valuation methods for factory-built housing, constraining mortgage liquidity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Prefab Wood Buildings Market |
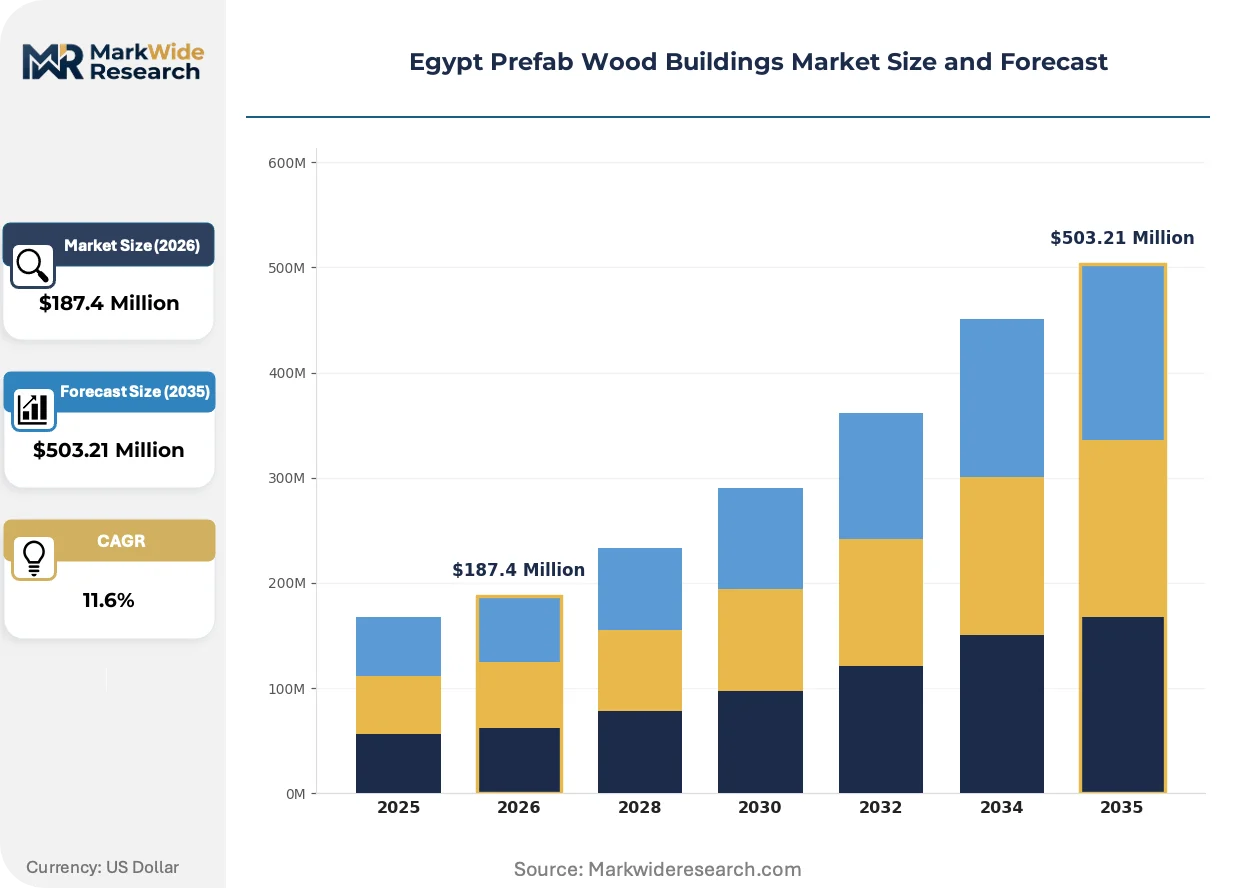
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Cabins, Prefabricated Panels, Portable Structures End User: Residential, Commercial, Hospitality, Educational Technology: Lightweight Frame, Engineered Wood, SIPs, Timber Frame Installation: Onsite Assembly, Offsite Prefabrication, Turnkey Solutions, DIY Kits |
| Companies Covered | Stora Enso, DTH Prefabricated Buildings, Karmod Prefabricated Technologies, Lida Group, ICON Egypt, Ideal EV Prefabrik Evim, SIKA Group, Arabian Construction House, Derix, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Prefab Wood Buildings Market Emerging Trajectories
Digital fabrication and regulatory recalibration are compressing traditional construction timelines while rerouting procurement authority from general contractors toward specialized timber system integrators.
Cross-laminated timber is decomposing the conventional design-bid-build sequence by enabling architects to specify structural performance rather than dimensional lumber grades. Red Sea resort developers now procure entire wall assemblies from Nordic suppliers, collapsing on-site labor requirements. This decomposition shifts margin capture from local contractors toward import distributors with certification authority.
The New Urban Communities Authority's mid-rise wood allowance represents the most significant regulatory recalibration since the authority's formation. Industrial consequence includes mandatory third-party inspection protocols that extend project timelines but reduce liability exposure. Educational facilities in satellite cities face the steepest compliance curve, with fire-rated acoustic assemblies now requiring dual certification from the Housing and Building National Research Center.
Buyer concentration among hospitality developers is compressing supplier negotiation cycles and unbundling after-sales service from initial procurement contracts. Red Sea resort operators now contract maintenance separately through facility management firms, forcing timber system providers to price installation-only. This pattern concentrates in coastal tourism corridors where seasonal occupancy demands dictate rapid defect resolution.
Egypt Prefab Wood Buildings Market Segmentation
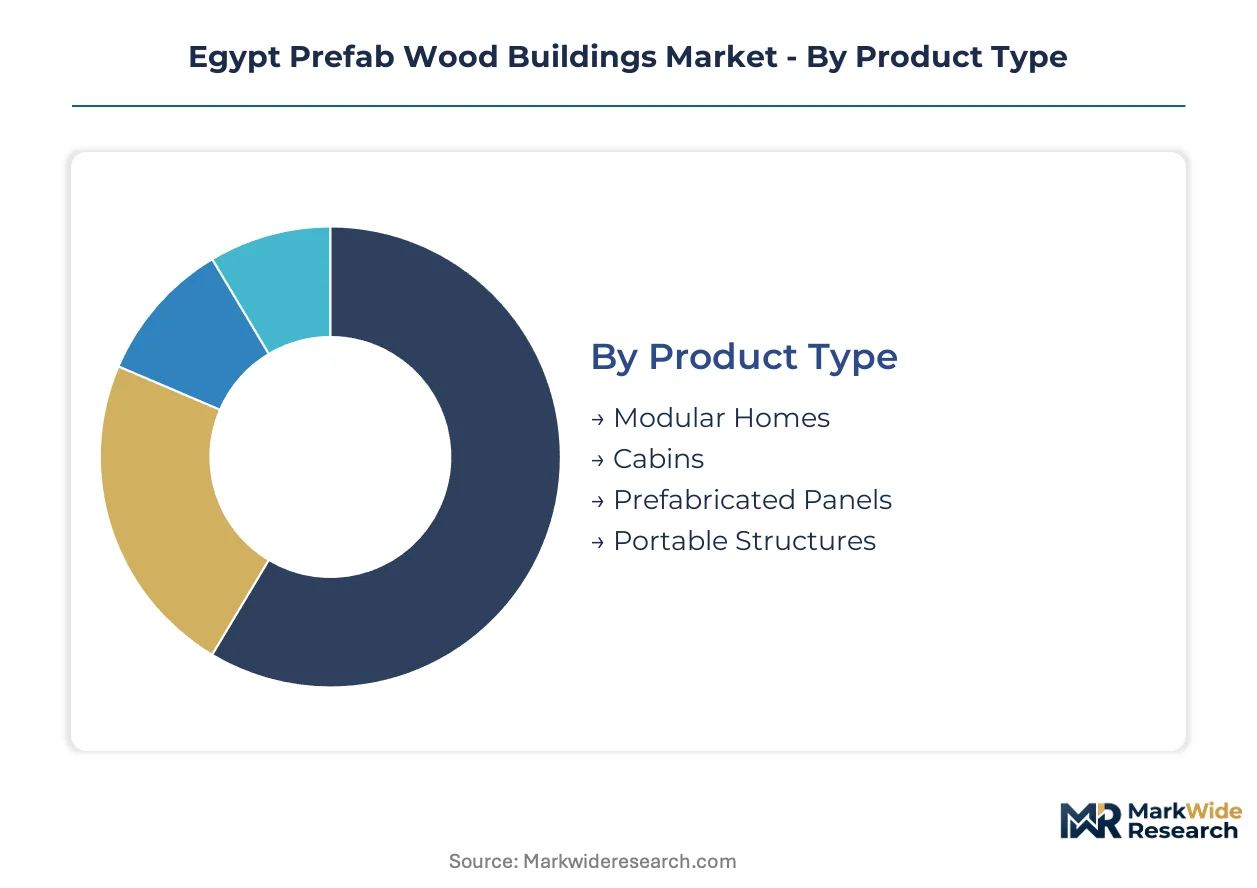
Egypt's prefab wood buildings market fragments across four structural dimensions that determine procurement patterns and margin capture. Product type and technology choices concentrate in Alexandria Port import corridors, while end-user demand splits between domestic hospitality developers and residential buyers in satellite cities.
Product Type:
Domestic manufacturing anchors portable structures and basic cabins, while modular homes and engineered panels flow through Nordic import channels into Red Sea tourism zones.
- Modular Homes:Factory-built volumetric units with integrated MEP systems arrive as complete living spaces requiring only foundation connections. New Administrative Capital gated communities absorb these units as mortgage lenders gradually accept prefab collateral, though customs clearance at Alexandria Port extends lead times.
- Cabins:Compact single-room structures dominate Red Sea coastal resorts where speed-to-occupancy commands premium seasonal returns. Marsa Alam and Hurghada developers specify these for staff housing and guest accommodation, compressing construction cycles against concrete alternatives.
- Prefabricated Panels:Wall and roof assemblies fabricated in Cairo industrial zones serve Greater Cairo educational facilities requiring rapid classroom expansion.
- Portable Structures:Relocatable units with minimal foundation requirements address temporary site offices and emergency housing needs in Sinai development corridors.
Modular homes hold the largest share; momentum sits with cabins as Red Sea tourism investment accelerates.
End User:
Cost tier stratification separates premium hospitality specifications from mass residential applications, with educational facilities occupying a compliance-intensive middle band.
- Hospitality:Red Sea resort developers specify Grade-A engineered wood for luxury eco-lodges and boutique properties, absorbing 30-50% faster construction cycles to capture peak season occupancy. Stakeholders prioritize carbon footprint verification for European tourist market positioning.
- Residential:Gated community buyers in 6th of October City and Sheikh Zayed gravitate toward timber frame systems as the Housing and Building National Research Center certification enables mortgage collateralization. Foundation cost savings in seismic zones drive specification in Greater Cairo.
- Commercial:Retail and office applications concentrate in New Administrative Capital government-mandated green building zones.
- Educational:Satellite city schools face fire-rating friction from additional intumescent coating requirements that extend specification timelines against steel alternatives.
Hospitality commands premium pricing tiers; residential applications are expanding most quickly as financing documentation gaps narrow.
Technology:
Supply concentration in Alexandria Port favors import-dependent engineered wood and cross-laminated timber, while domestic fabrication sustains lightweight frame alternatives.
- Engineered Wood:Cross-laminated and glue-laminated products from Nordic suppliers dominate mid-rise applications permitted under New Urban Communities Authority codes. Alexandria Port concentration exposes developers to currency fluctuation and customs volatility.
- Lightweight Frame:Steel-reinforced timber systems designed for seismic zones reduce foundation loads in Greater Cairo earthquake-prone districts. ICON Egypt anchors this segment through specialized structural engineering.
- SIPs:Structural insulated panels face skilled assembly shortages that force manufacturers to deploy foreign supervision teams for connection certification.
- Timber Frame:Traditional post-and-beam methods persist in luxury residential applications where aesthetic exposure drives specification.
Engineered wood dominates import volume; lightweight frame systems are gaining share fastest in seismic zone applications.
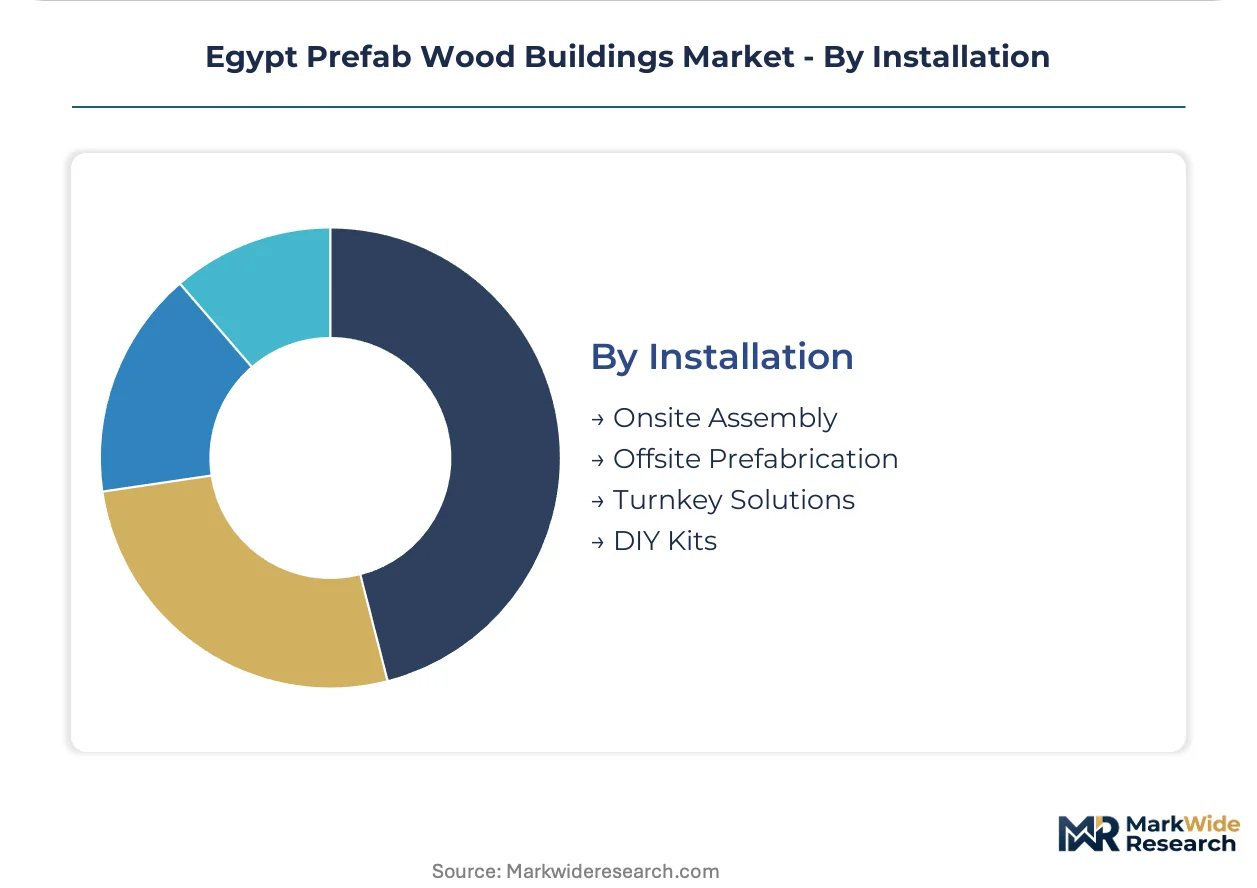
Installation:
Customer type determines service bundling, with hospitality developers unbundling maintenance contracts and residential buyers demanding integrated financing.
- Turnkey Solutions:End-to-end delivery including foundation, assembly, and MEP integration captures Red Sea resort contracts where single-point accountability reduces project risk. Karmod Prefabricated Technologies anchors this segment across coastal tourism corridors.
- Offsite Prefabrication:Factory production of wall and floor assemblies shipped for rapid onsite erection serves educational facilities with compressed summer construction windows.
- Onsite Assembly:Component-based installation requires certified crews that remain scarce in Egyptian construction labor markets.
- DIY Kits:Self-assembly packages target remote agricultural and Sinai development zones with limited contractor access.
Turnkey solutions capture the largest contract value; offsite prefabrication is climbing the fastest as digital fabrication converges with BIM workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's prefab wood buildings sector operates as a net importer of engineered timber products, with Nordic supply chains dominating Alexandria Port throughput while domestic fabrication clusters emerge around Cairo and Red Sea logistics corridors.
Greater Cairo
Seismic zone construction drives lightweight frame system demand across earthquake-prone districts in Giza and Cairo Governorates. The Housing and Building National Research Center certifies timber structural systems for residential collateralization, enabling mortgage acceptance in 6th of October City and Sheikh Zayed gated communities. Foundation cost savings anchor specification decisions in New Cairo satellite developments.
New Administrative Capital
Government-mandated sustainability procurement preferences redirect capital toward timber structures with verified carbon footprints in this purpose-built administrative zone. The New Urban Communities Authority building codes permit engineered wood in mid-rise government and commercial facilities, compressing compliance timelines against concrete alternatives. Digital fabrication integration with BIM workflows accelerates panel production for boutique hospitality and office projects.
Red Sea Coast
Marsa Alam and Hurghada resort developers specify modular timber cabins to capture premium seasonal occupancy returns before concrete construction completes. Speed-to-occupancy commands pricing power in Hurghada's tourism corridor, where European market positioning requires carbon footprint verification. Karmod Prefabricated Technologies anchors turnkey contracts across coastal zones with integrated MEP delivery.
Alexandria Port Corridor
Cross-laminated timber and glue-laminated products concentrate through Nordic shipping lanes into Egypt's primary maritime entry point. Stora Enso leverages established Baltic-Black Sea logistics to dominate engineered wood import volumes. Customs clearance volatility and currency fluctuation expose developers to procurement risk in this single-point supply concentration.
Sinai Development Zones
Portable structures address temporary site offices and emergency housing needs in limited-access development corridors. DIY kit formats target remote agricultural and infrastructure projects where certified contractor availability remains scarce. Minimal foundation requirements suit the region's challenging terrain and logistics constraints.
Egypt Prefab Wood Buildings Market Vendor Landscape
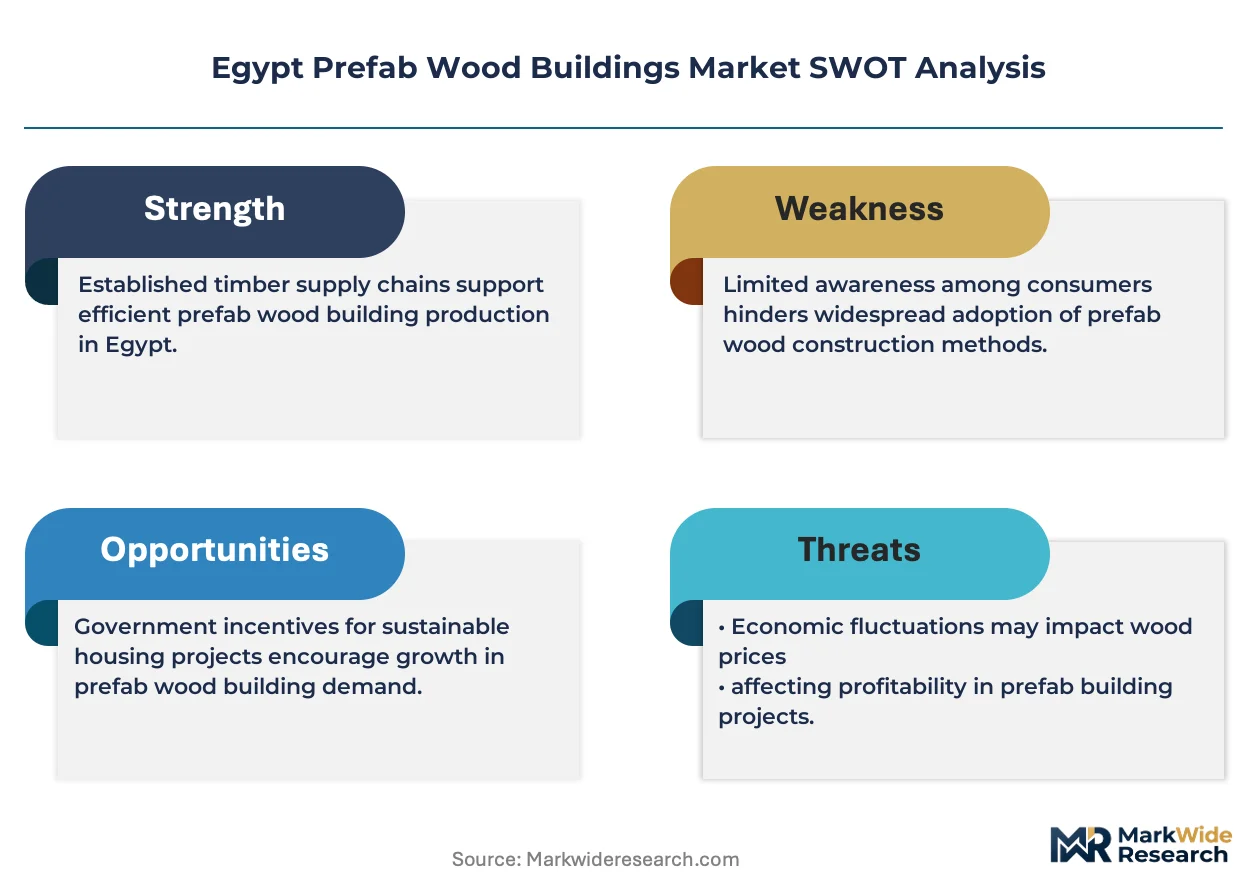
Concentration sits with import-dependent engineered wood distributors and domestic turnkey integrators competing across distinct value chain positions. Nordic suppliers control cross-laminated timber flows through Alexandria Port, while Egyptian fabricators capture installation and MEP integration margins. Three archetypes dominate: international material suppliers with certification authority, regional turnkey contractors with coastal resort relationships, and lightweight frame specialists targeting seismic applications. Capacity expansion through CNC machining integration and strategic partnerships with hospitality developers constitute the primary competitive vectors.
Among Nordic-based material suppliers, Stora Enso represents the import-dominant archetype controlling engineered wood certification pathways. Karmod Prefabricated Technologies and ICON Egypt exemplify contrasting domestic strategies: the former anchors turnkey resort contracts across Red Sea corridors, while the latter occupies a position in lightweight frame systems designed for Greater Cairo seismic zones. These three players illustrate the market's structural division between upstream material control and downstream integration capabilities.
| Leading Market Players |
|---|
| Stora Enso |
| DTH Prefabricated Buildings |
| Karmod Prefabricated Technologies |
| Lida Group |
| ICON Egypt |
| Ideal EV Prefabrik Evim |
| SIKA Group |
| Arabian Construction House |
| Derix |
| Others |
Supply Flow & Price Mechanics
Housing and Building National Research Center Grade-A certification gates both supply qualification and price differentiation in Egypt's prefab wood buildings sector, compressing the premium gap between Nordic-engineered timber and domestic lightweight frame systems while segmenting procurement authority across Alexandria Port import corridors and Cairo fabrication zones.
Pricing Analysis
Hospitality developers anchor project-based pricing structures across Red Sea resort contracts, with Grade-A certification and turnkey MEP integration driving premium-mid-economy pricing differentiation. Cost compression in standard-grade cabin segments is intensifying because domestic portable structure manufacturers compete on volume scale against Nordic import distributors. Residential buyers in gated communities exhibit highest price sensitivity due to mortgage collateralization friction, while Red Sea resort operators absorb premium tiers for speed-to-occupancy advantages.
Supply Chain Analysis
Strategic stockpile preferences dominate among hospitality developers facing seasonal construction windows, while just-in-time panel delivery serves educational facilities with compressed summer installation periods. Cross-laminated timber supply concentrates in Finland, Sweden, and Austria, with raw material dependencies on Nordic spruce feedstock, Baltic birch adhesives, and Alexandria Port handling capacity. Single-source vulnerability at the port exposes developers to customs clearance volatility. Distribution runs through import distributors with certification authority toward turnkey integrators capturing installation margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's prefab wood buildings sector presents a service-attach opportunity as facility management contracts for seasonal resort maintenance expand faster than hardware procurement, unbundling after-sales service from initial timber system sales and redirecting recurring revenue toward specialized operators.
For Market Incumbents: Shield installed base relationships in Red Sea tourism corridors by embedding proprietary BIM-to-fabrication workflows that increase switching costs for hospitality developers. Anchor certification investment at Housing and Building National Research Center to preempt competitor qualification pathways. Counter concrete substitution threats in mass housing through foundation cost savings documentation in Greater Cairo seismic zones.
For New Entrants and Emerging Players: Anchor in lightweight frame system deployment across earthquake-prone Giza districts where structural mass reduction commands specification premiums. Target educational facilities in New Administrative Capital satellite cities facing fire-rating compliance friction against steel alternatives. Pursue CNC machining partnerships with Cairo industrial zone fabricators to compress design-to-installation cycles for boutique hospitality projects.
For Investors and Strategic Acquirers: New Urban Communities Authority mid-rise wood allowance reshapes the acquisition landscape toward engineered wood distributors with Alexandria Port throughput relationships and certification authority. Long-term viability across the projection horizon favors turnkey integrators with hospitality resort maintenance contract backlogs. Monitor central bank construction financing rule evolution as the inflection signal determining whether prefab timber escapes niche positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | Housing and Building National Research Center Grade-A qualification unlocks mortgage collateralization pathways for residential segments. |
| Backward Integration | CNC machining capacity in Cairo industrial zones captures panel fabrication margins from Nordic import distributors. |
| Turnkey Service Expansion | Integrated MEP and maintenance contracts concentrate recurring revenue from Red Sea hospitality developers. |
| Seismic Zone Specialization | Lightweight frame engineering for Greater Cairo earthquake districts differentiates against concrete and steel alternatives. |
| Digital Fabrication Convergence | BIM-to-panel workflows compress design-to-installation cycles for boutique New Administrative Capital projects. |
Methodological Framework
Operator-level perspectives from resort development executives, timber system procurement managers, Housing and Building National Research Center certification officers, and Alexandria Port logistics coordinators anchored the qualitative base. Secondary validation drew from New Urban Communities Authority building code publications, Egyptian customs import records, Nordic timber trade association data, and hospitality sector construction permits. Bottom-up project pipeline analysis triangulated with top-down sector expenditure estimates across the forecast period.
Sensitivity analysis tested volume and value outputs against regulatory adoption timelines, currency fluctuation scenarios, and mortgage liquidity assumptions. Segmentation dimensions modeled include structural technology type, end-user vertical, installation service bundling, and regional construction corridor. CAGRs were derived from fitted growth curves applied to verified project announcements and import volume trajectories. Cross-laminated timber penetration rates and lightweight frame seismic code adoption served as industry-specific forecast inputs.
Material uncertainties — central bank construction financing rule revisions, Alexandria Port customs clearance disruptions, and cement producer pricing responses — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and Nordic supply chain continuity. Revision becomes warranted when mortgage collateralization acceptance for prefab timber crosses threshold penetration in gated community segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Suspended Ceiling Systems Market
Building & Construction Materials
Pocket Door Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Asia-Pacific Particle Board Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Sink Float Tank Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Waterproofing Solution Market
Building & Construction Materials
Philippines Building System Components Market
Building & Construction Materials
Cladding Systems Market