
 Fiberglass Light Poles Market | 2026-2036
Fiberglass Light Poles Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Light Poles Market Analysis
Direct-to-municipality procurement channels is reconfiguring how fiberglass light poles reach end users across North America and Europe. Valmont Industries leverages its vertically integrated manufacturing footprint to sustain cost advantages in utility-scale deployments. Shakespeare anchors its position through specialized marine-grade formulations that dominate coastal municipality contracts. Elsewedy Electric competes aggressively across Middle Eastern and African markets with region-tailored product lines.
Fiberglass light poles are fiber-reinforced polymer composite structures manufactured through pultrusion or filament winding processes, typically achieving strength-to-weight ratios exceeding conventional steel while eliminating conductive properties that create electrocution hazards. These poles serve primarily as structural supports for roadway, commercial, and recreational illumination systems where longevity and minimal maintenance offset higher initial material costs. Straight poles occupy the dominant volume position across highway and arterial road installations where standardized heights and load ratings streamline procurement. Solar poles represent the fastest-expanding product category as off-grid and renewable-integrated streetlighting programs gain traction among municipalities seeking energy independence. Above-ground installation types capture the largest margin pools due to reduced civil works and faster deployment timelines relative to in-ground alternatives.
ANSI C136 standards in the United States govern structural performance and dimensional requirements for roadway luminaire supports, while the EU Green Deal and associated national decarbonization frameworks in Germany and France are embedding lifecycle carbon assessments into public infrastructure procurement criteria. Health Canada's PMRA evaluates preservative alternatives for traditional wood poles, indirectly channeling specifications toward inert composite materials that eliminate chemical leaching concerns. Stakeholders must monitor evolving embodied-carbon accounting rules and corrosion-resistance certification thresholds as these criteria increasingly determine bid eligibility and contract awards.
Market Dynamics
Municipal infrastructure procurement is pivoting from traditional steel and wood toward corrosion-resistant composite formulations, driven by lifecycle cost accounting and coastal resilience mandates across North American and European highway authorities.
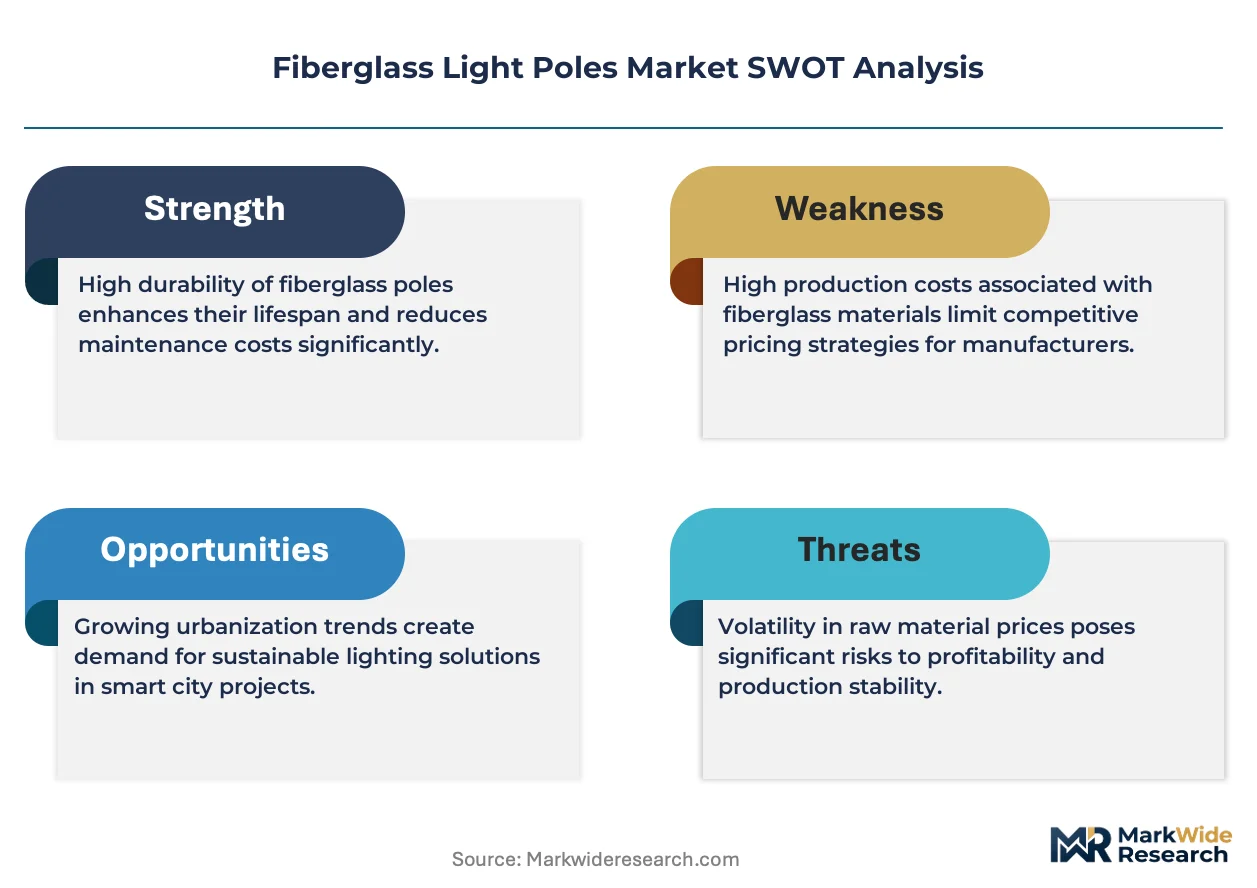
Growth Catalysts
- ANSI C136 Standards:Updated structural performance requirements for roadway luminaire supports are disqualifying conductive steel alternatives in United States federal highway contracts.
- EU Green Deal:Embodied-carbon assessment frameworks in Germany and France are embedding composite materials into public infrastructure procurement criteria.
- Coastal Humidity Exposure:De-icing salt degradation in United States Northeast corridor municipalities is accelerating specification shifts toward fiberglass formulations.
Market Restraints
- Resin Cost Volatility:Epoxy and polyester feedstock prices fluctuate with petrochemical supply chains, compressing manufacturer margins during crude oil spikes.
- Pultrusion Equipment Concentration:Specialized mandrel and die fabrication capabilities cluster in United States Midwest and German industrial regions, creating supply bottlenecks.
- Steel Price Arbitrage:Temporary dips in galvanized steel pricing resuscitate incumbent material specifications in budget-constrained municipal procurement cycles.
Strategic Opportunities
- Solar-Integrated Poles:Off-grid renewable streetlighting programs in Australian remote communities are opening demand for bifacial panel-ready composite structures.
- Direct Municipality Channels:Bypassing traditional electrical distributor networks through public tender platforms is capturing margin previously lost to intermediaries.
- Marine-Grade Formulations:Salt-spray certification requirements in United Arab Emirates coastal developments are creating premium product tier differentiation.
Industry Challenges
- Composite Design Certification:Structural engineers with fiber-reinforced polymer expertise remain scarce relative to steel and concrete specialists, extending project timelines.
- Legacy Anchor Compatibility:Retrofitting existing foundation bolts and base plates to accommodate composite pole diameters requires custom adapter fabrication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Light Poles Market |
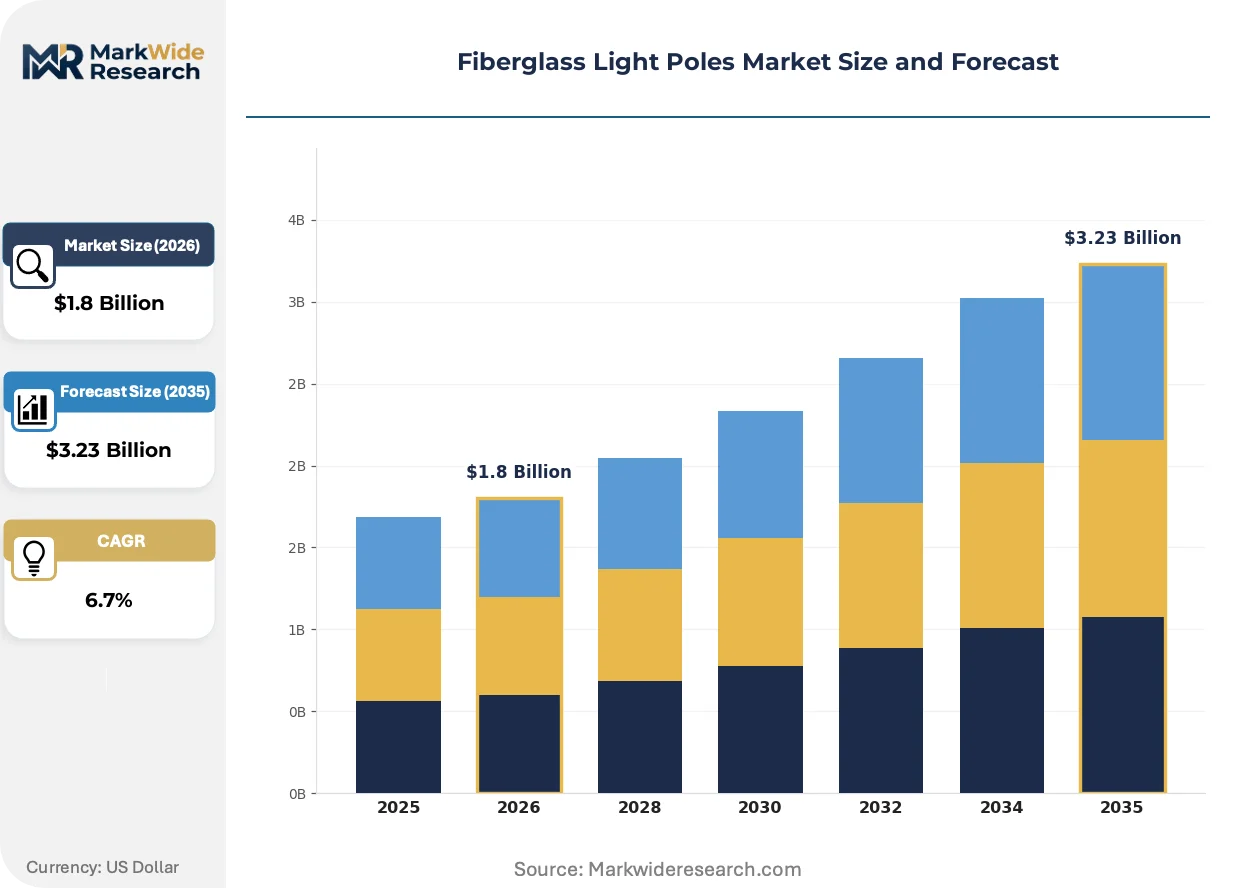
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Straight Poles, Decorative Poles, Wall-Mounted Poles, Solar Poles Application: Residential Areas, Commercial Spaces, Highways, Parks Installation Type: Above Ground, In-Ground, Modular, Recessed End User: Municipalities, Contractors, Utility Companies, Retailers |
| Companies Covered | PLP Composite Technologies, Aeron Composite Pvt. Ltd., Valmont Industries, Elsewedy Electric, Creative Composite, NAFCO International, Wood Preservers, Shakespeare, Alliance Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Light Poles Market Emerging Trajectories
Embedded sensor integration and predictive maintenance capabilities are transforming passive structural components into data-generating infrastructure assets, altering how municipalities evaluate total cost of ownership.
Pultrusion manufacturing is digitizing quality control through real-time die temperature monitoring and automated fiber placement feedback systems. United States Department of Transportation contractors are specifying these traceable production methods for critical highway installations. The technology is digitizing supply chain transparency by linking batch records directly to asset management databases.
EU Green Deal lifecycle carbon accounting rules are mandating environmental product declarations for all public infrastructure materials above specified contract thresholds. Composite pole manufacturers in France and Germany are responding with third-party verified embodied-carbon certifications. German federal highway procurement offices are now weighting these declarations at fifteen percent of technical bid scores.
Aggregated municipal purchasing cooperatives are consolidating demand across multiple city jurisdictions to negotiate volume-based pricing and standardized specifications. Electrical distributors in United States Sun Belt states are losing share to these buyer consortiums. Florida and Texas county-level purchasing alliances represent the most advanced examples of this procurement consolidation.
Fiberglass Light Poles Market Segmentation
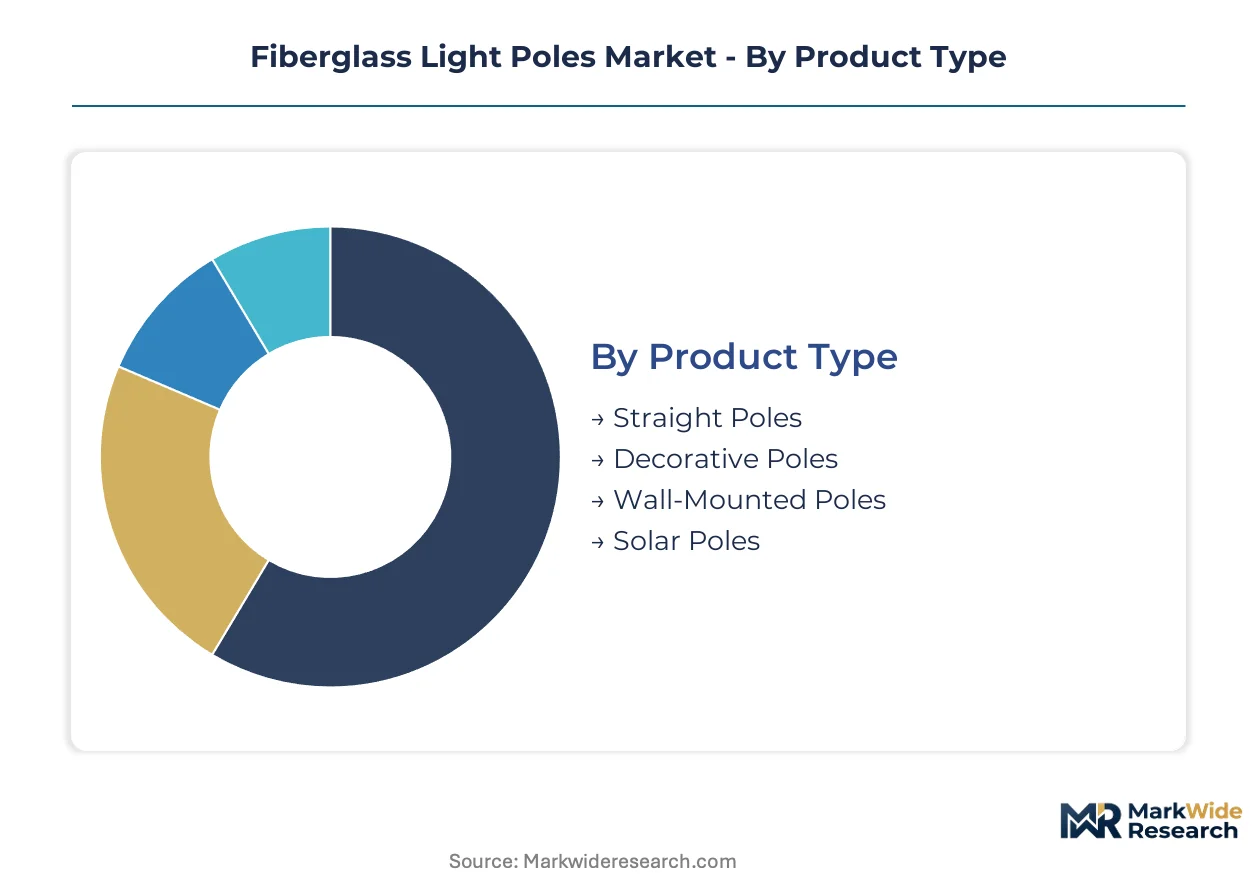
Fiberglass light pole procurement varies sharply across structural configurations, deployment contexts, and buyer authority levels. Specification engineers weight corrosion resistance, foundation compatibility, and lifecycle cost differently depending on whether the installation serves arterial highways, municipal parks, or commercial parking structures.
Product Type:
Structural geometry determines load-bearing capacity, aesthetic integration, and renewable energy accommodation across the use-case spectrum.
- Straight Poles:Pultruded cylindrical profiles with uniform cross-sections deliver standardized strength-to-weight ratios for high-volume highway and roadway deployments. United States state DOT contracts favor these configurations for interchange lighting where wind load ratings and luminaire mounting heights follow predictable patterns.
- Solar Poles:Integrated composite structures incorporate mounting hardware for photovoltaic panels and battery enclosures, enabling off-grid operation in remote Australian communities and rural United States counties where grid extension proves uneconomical.
- Decorative Poles:Ornamental fluting, tapered profiles, and color-matched gel coats serve historic district revitalization and main street commercial corridors.
- Wall-Mounted Poles:Cantilevered bracket systems extend illumination from building facades, eliminating foundation requirements in dense urban cores.
Established volume favors straight poles; emerging adoption favors solar poles.
Application:
Environmental exposure severity and maintenance access constraints reshape material specifications across deployment environments.
- Highways:High-speed corridors demand crash-tested breakaway bases and stringent deflection standards under ANSI C136 protocols. German autobahn authorities specify these for median lighting where vehicle impact recovery dominates procurement criteria.
- Parks:Pedestrian-scale installations prioritize aesthetic cohesion with landscape architecture and reduced foundation footprints in sensitive ecological zones. Coastal municipalities in Florida specify marine-grade formulations for boardwalk illumination.
- Residential Areas:Subdivision developers balance upfront cost against homeowner association maintenance budgets.
- Commercial Spaces:Retail parking lots and logistics facilities emphasize rapid installation and minimal service disruption.
Revenue concentration sits with highway deployments; steepest expansion trajectory appears in park and recreational infrastructure.
Installation Type:
Foundation methodology directly determines project timeline, labor skill requirements, and adaptability to substrate conditions.
- Above Ground:Surface-mounted base plates anchor to existing concrete pads or engineered piers, eliminating excavation and curing delays. This configuration captures premium margins in United States urban retrofit projects where lane closures carry penalty costs.
- In-Ground:Direct burial with concrete backfill delivers maximum overturning resistance for high-wind corridors and heavy luminaire loads.
- Modular:Segmented pole assemblies enable field height adjustment and simplified transport to remote sites.
- Recessed:Flush-mounted systems integrate lighting into architectural surfaces and pedestrian plazas.
Margin pools concentrate in above-ground systems; technical innovation clusters around modular configurations.
End User:
Procurement authority and technical specification control vary dramatically across buyer categories.
- Municipalities:Public works departments wield direct contracting authority for streetlighting capital programs, increasingly bypassing electrical distributors through aggregated purchasing cooperatives. Texas county-level alliances exemplify this consolidation trend.
- Utility Companies:Investor-owned and municipal electric utilities maintain standardized material specifications across multi-state service territories, creating volume concentration for qualified suppliers.
- Contractors:General and electrical contractors respond to specification-driven bidding environments with limited material substitution flexibility.
- Retailers:Big-box and commercial property developers prioritize speed-to-occupancy over lifecycle optimization.
Contracting leverage is concentrating among municipalities; specification influence remains strongest with utility companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANSI C136 standards in the United States anchor procurement specifications for roadway luminaire supports, while EU Green Deal lifecycle carbon accounting in Germany and France redirects infrastructure budgets toward composite materials. Municipal procurement across coastal and high-humidity jurisdictions is accelerating material substitution away from traditional steel and wood alternatives.
United States
Federal highway contracts under updated ANSI C136 protocols disqualify conductive steel poles in median and interchange lighting. State DOTs in the Northeast corridor specify corrosion-resistant formulations where de-icing salt exposure degrades conventional alternatives. The Texas county-level purchasing alliance consolidates demand across multiple jurisdictions to negotiate standardized fiberglass pole specifications.
Germany
Autobahn authorities mandate crash-tested breakaway bases and stringent deflection standards for high-speed corridor illumination. Federal highway procurement offices weight environmental product declarations at fifteen percent of technical bid scores under EU Green Deal implementation. Industrial clusters in North Rhine-Westphalia host pultrusion equipment fabricators serving cross-border infrastructure projects.
Australia
Remote communities in Queensland and Western Australia drive demand for solar-integrated composite poles where grid extension proves uneconomical. TGA-equivalent infrastructure standards evaluate preservative alternatives for traditional wood poles, channeling specifications toward inert composite materials. Coastal municipalities specify marine-grade formulations for boardwalk and recreational illumination exposed to salt-spray conditions.
United Arab Emirates
Coastal developments in Dubai and Abu Dhabi require salt-spray certification for structural supports in marine environments. MOHAP-adjacent infrastructure frameworks evaluate material longevity in extreme humidity conditions. Fabrication capabilities in the Jebel Ali industrial zone supply premium-tier composite poles for premium real estate and hospitality projects.
Canada
Health Canada's PMRA evaluates chemical preservative alternatives for traditional wood poles, indirectly favoring inert composite materials that eliminate leaching concerns. Provincial highway authorities in Ontario and British Columbia specify corrosion-resistant alternatives for bridge and coastal roadway installations. Municipal procurement in the Atlantic provinces accelerates substitution where freeze-thaw cycles degrade conventional alternatives.
Fiberglass Light Poles Market Vendor Landscape
Vertically integrated conglomerates and specialized composite fabricators split the market into distinct capability tiers. Consolidation concentrates around manufacturers with captive pultrusion capacity and certified structural engineering resources. Three archetypes dominate: utility-scale infrastructure suppliers, marine-grade formulation specialists, and regional procurement consolidators. Competitive positioning hinges on backward integration into resin compounding and geographic expansion through public tender platforms.
Within the utility-scale tier, Valmont Industries exemplifies the vertically integrated archetype with manufacturing footprints spanning multiple continents. Elsewedy Electric anchors the regional procurement consolidator position across Middle Eastern and African markets. Shakespeare occupies the marine-grade specialization vector with coastal municipality contracts. These three represent distinct strategic postures rather than interchangeable competitors.
| Leading Market Players |
|---|
| PLP Composite Technologies |
| Aeron Composite Pvt. Ltd. |
| Valmont Industries |
| Elsewedy Electric |
| Creative Composite |
| NAFCO International |
| Wood Preservers |
| Shakespeare |
| Alliance Composites |
| Others |
Supply Flow & Price Mechanics
Undercapacity in United States Midwest pultrusion equipment fabrication is driving extended lead times and selective supplier prioritization toward high-volume municipal contracts. This utilization squeeze simultaneously compresses margin pools for mid-tier fabricators while amplifying pricing power among vertically integrated manufacturers with captive mandrel production.
Pricing Analysis
Geographic price spreads between German autobahn-grade certified poles and standard United States highway configurations reflect embedded carbon accounting premiums and salt-spray certification tiers. The dominant pricing structure stratifies across premium marine-grade, standard highway-grade, and economy residential-tier levels, with differentiation driven by ANSI C136 compliance depth and resin formulation quality. Cost compression in the economy tier is intensifying as Chinese epoxy imports displace domestic feedstock sourcing. Municipal procurement cooperatives exhibit the lowest price sensitivity due to lifecycle cost accounting mandates, while residential subdivision developers remain highly sensitive to upfront capital outlays.
Supply Chain Analysis
Tariff exposure between United States and Chinese epoxy resin suppliers dominates supply chain risk planning for composite pole fabricators. Manufacturing capacity concentrates in the United States Midwest, Germany's North Rhine-Westphalia industrial cluster, and China's Jiangsu province. Raw material dependencies rest on fiberglass roving from Owens Corning's domestic facilities, epoxy formulations from Huntsman and Hexion, and polyester gel coats from Ashland. Single-source vulnerability in specialized pultrusion die fabrication creates bottlenecks during demand surges. Distribution runs through direct municipal tender platforms, bypassing traditional electrical distributor networks in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fiberglass light pole penetration remains below saturation thresholds across coastal municipality infrastructure replacement cycles, with ANSI C136 standard updates creating forced replacement tailwinds that extend the early-cycle expansion phase.
For Market Incumbents: Harden defensive positions through backward integration into resin compounding and captive pultrusion die fabrication to neutralize equipment bottlenecks. Secure exclusive supply agreements with Owens Corning and Huntsman to lock in fiberglass roving and epoxy formulation access against emerging entrant bidding. Invest in marine-grade salt-spray certification infrastructure to capture premium-tier differentiation as UAE and Australian coastal specifications tighten. For New Entrants and Emerging Players: Build out modular solar-integrated pole capabilities targeting Queensland remote communities and rural Texas counties where grid extension economics favor off-grid deployment. The most penetrable white space sits in Australian solar pole applications and United States aggregated municipal purchasing cooperatives seeking second-source suppliers. Pursue direct tender platform registration in Florida and Texas county alliances to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated manufacturers with multi-year municipal maintenance contracts and certified structural engineering resources. Long-term viability over the next decade hinges on EU Green Deal carbon accounting compliance and ANSI C136 certification depth rather than pure manufacturing scale. Target acquisition archetypes include marine-grade formulation specialists with UAE salt-spray credentials and regional procurement consolidators with established Middle Eastern tender platform access. The signal to watch is municipal cooperative purchasing alliance formation velocity in United States Sun Belt states.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive epoxy formulation control neutralizes petrochemical price volatility and secures margin pools. |
| Marine-Grade Salt-Spray Certification Investment | UAE MOHAP-adjacent requirements and Australian coastal specifications create premium tier access. |
| Direct Municipal Tender Platform Registration | Texas and Florida county alliances are consolidating demand away from electrical distributors. |
| Solar-Integrated Pole Product Line Expansion | Queensland remote communities and rural United States counties drive off-grid renewable demand. |
| Pultrusion Equipment Capacity Addition | Midwest mandrel fabrication undercapacity creates bottlenecks for qualified suppliers. |
Methodological Framework
Operator-level perspectives from municipal public works directors, state DOT specification engineers, pultrusion plant managers, and electrical distributor category managers anchored the qualitative base. Primary interviews with these stakeholders combined with secondary validation against ANSI C136 technical standards, EU Green Deal procurement guidelines, EPA environmental product declaration databases, and United States Census Bureau municipal expenditure surveys. Bottom-up volume estimates from individual manufacturer capacity disclosures triangulated with top-down infrastructure budget allocations from federal highway administration sources.
Scenario-bracketing around resin cost volatility trajectories and municipal procurement cycle timing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include structural geometry, installation methodology, end-user procurement authority, and geographic regulatory cluster. CAGRs derived from weighted average of historical replacement rates and projected infrastructure budget growth, with specific inputs from de-icing salt exposure severity indices and solar streetlighting program adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese composite fabricators or disruptive moves by steel industry lobbyists to delay ANSI C136 enforcement would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Concrete Form Oil Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Acoustic Panel Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
Global Metal-Faced Insulated Panels Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market