
 Acoustical Ceiling Market | 2026-2036
Acoustical Ceiling Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustical Ceiling Market Intelligence
The availability of certified installers for complex suspended and floating ceiling systems is reorganizing project timelines and contractor selection. Armstrong World Industries leverages its extensive distribution network and brand recognition to secure large commercial projects. Saint-Gobain Ecophon specializes in high-performance solutions for acoustically sensitive environments like hospitals, while USG Corporation competes through its integrated wall-to-ceiling system offerings.
Acoustical ceilings are specialized building components designed to absorb sound and control reverberation within an enclosed space. Their performance is quantified by metrics like the Noise Reduction Coefficient (NRC), which indicates the proportion of sound absorbed. Mineral fiber tiles continue to dominate the product landscape due to their balance of cost and performance. However, premium applications in commercial buildings increasingly specify wood and metal systems, which are specified by architects for superior aesthetics and durability.
Performance and material safety are governed by a matrix of standards. ISO 354 provides a universal method for measuring sound absorption, creating a common performance language. In the United States, EPA guidelines on indoor air quality impact material choices, while the EU's CE marking is mandatory for market access. Stakeholder decisions will increasingly center on balancing certified acoustic performance with the lifecycle environmental impact of specified materials.
Market Dynamics
The central structural force shaping the acoustical ceiling market is the convergence of sustainable building mandates and occupant well-being standards. Regulatory pressures, exemplified by the EU Green Deal, are pushing material specifications toward products with certified environmental and health performance, influencing design choices globally.
Growth Catalysts
- Healthcare Sector Expansion:New hospital and clinic construction in the United States and China requires high-performance ceilings with superior Noise Reduction Coefficient (NRC) ratings to create optimal healing environments and meet stringent acoustic regulations.
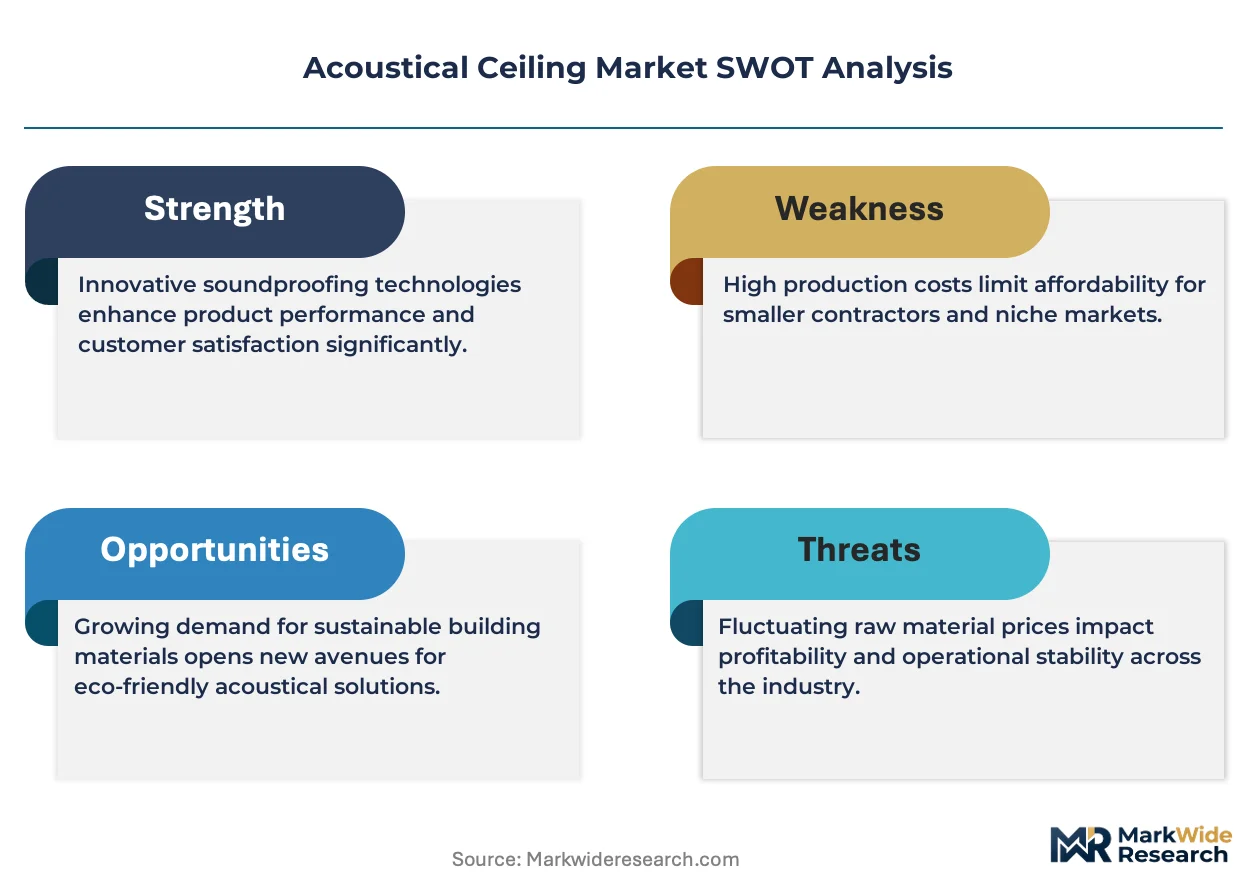
- Sustainable Building Codes:Green building initiatives, including LEED and BREEAM certification programs, create direct demand for ceiling products made from recycled materials and possessing low volatile organic compound (VOC) emissions.
- Open-Plan Office Design:The continued prevalence of open-plan corporate offices necessitates advanced acoustical solutions to mitigate noise, control reverberation, and improve employee concentration and productivity, sustaining demand for specialized ceiling systems.
Market Restraints
- Skilled Labor Shortages:A deficit of certified installers for complex and custom floating or suspended ceiling systems leads to project bottlenecks, increased labor costs, and extended construction timelines in developed markets.
- Raw Material Price Volatility:Fluctuations in the cost of key inputs such as mineral fiber, fiberglass, and aluminum create margin pressure for manufacturers and introduce pricing uncertainty into the project bidding process.
- Threat from Alternative Finishes:The architectural trend toward exposed structures and the use of integrated plasterboard systems that offer seamless finishes present a substitution risk, particularly in minimalist commercial and residential designs.
Strategic Opportunities
- Circular Economy Products:Developing ceiling tiles with high recycled content and clear end-of-life recycling or take-back programs can create a competitive advantage in markets prioritizing circular economy principles.
- Southeast Asian Construction Boom:Rapid commercial and institutional construction in emerging economies like Vietnam and Indonesia presents a significant opportunity for market entry and expansion with performance-tiered ceiling solutions.
- Integration with Smart Building Systems:Embedding technology such as LED lighting, air quality sensors, and speakers directly into modular ceiling panels opens new revenue streams and provides higher-value, integrated solutions to clients.
Industry Challenges
- Complex Regulatory Navigation:Manufacturers face the operational challenge of ensuring products comply with a diverse and evolving matrix of international and regional standards, including ISO 354 for acoustics, ASTM E84 for fire safety, and EPA guidelines for air quality.
- Installer Training and Certification:The industry confronts an ongoing need to develop and scale effective training programs to qualify a sufficient workforce capable of correctly installing increasingly sophisticated and customized ceiling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustical Ceiling Market |
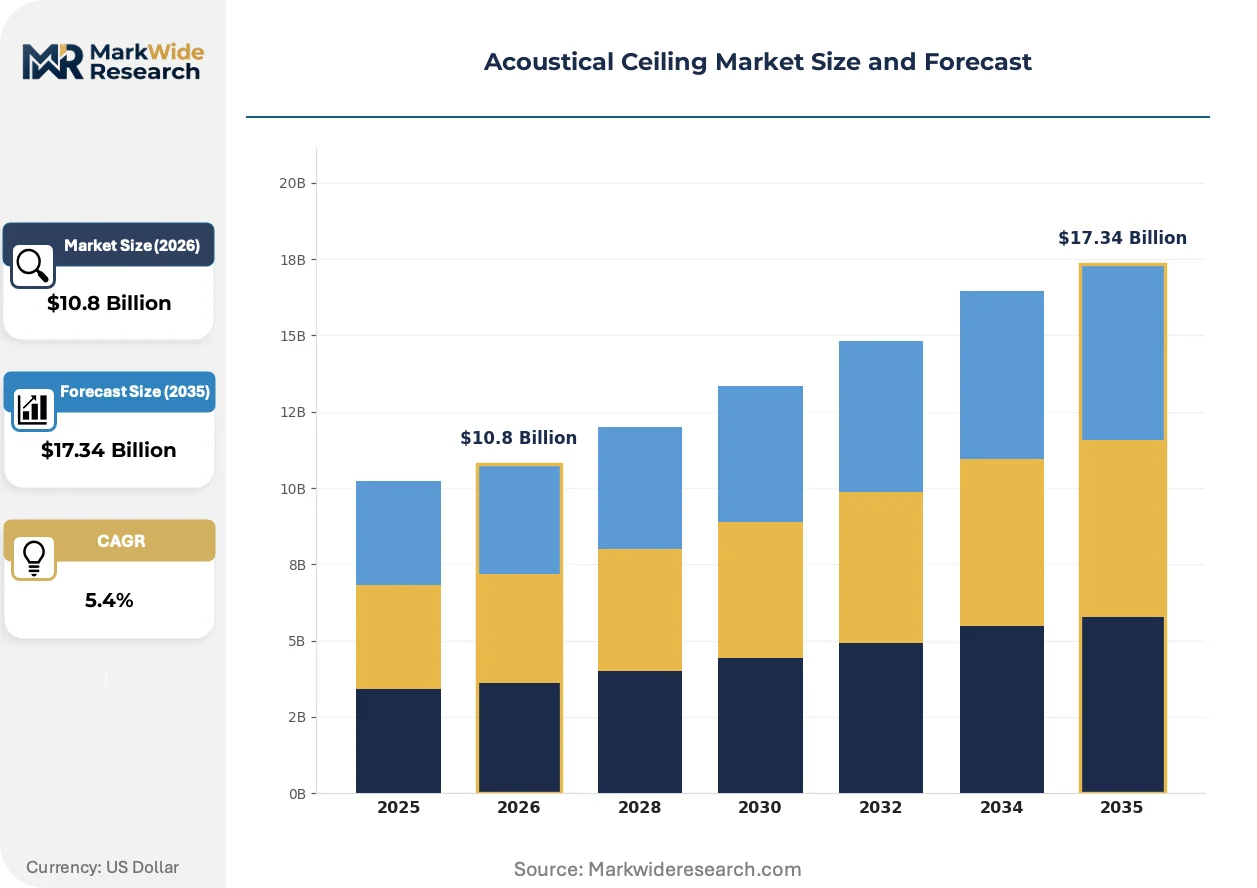
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.34 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Fiber, Metal, Wood, Gypsum, Plastic Installation: Suspended, Direct Attach, Stretch Ceiling, Floating Ceiling Application: Commercial Buildings, Institutional Facilities, Entertainment Venues, Transportation Terminals End User: Architects, Interior Designers, Construction Contractors, Facility Managers |
| Companies Covered | Rockfon, Hunter Douglas Architectural, Armstrong World Industries, Georgia-Pacific, Saint-Gobain Ecophon, USG Corporation, Knauf AMF, ROCKWOOL, CertainTeed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustical Ceiling Market Strategic Shifts & Innovations
Specification of acoustical ceilings is moving beyond simple sound absorption toward a holistic focus on indoor environmental quality. Material science advancements and digitalization are creating new performance benchmarks and aesthetic possibilities for architects and building owners, reshaping product development priorities across the industry.
Technology and Product Evolution
Bio-soluble mineral fiber formulations represent a key material evolution, offering improved fire resistance and superior indoor air quality compliance. Commercial and institutional specifiers are adopting these materials to meet stringent health and safety codes in schools and hospitals. This advanced material composition is supplanting traditional mineral wool in premium applications where occupant well-being is a primary design driver.
Regulatory and Policy Shifts
The EU's Corporate Sustainability Reporting Directive (CSRD) is compelling manufacturers to provide detailed lifecycle assessment data for building products. This regulation forces greater transparency in the supply chain, from raw material sourcing to end-of-life recyclability. The wood and metal ceiling segments are most affected, as they must now rigorously document material provenance and environmental impact to maintain market access in Europe.
Demand-Side and Behavioral Shifts
A notable shift in buying behavior is the prioritization of products with verified Environmental Product Declarations (EPDs). Architects and corporate clients increasingly use EPDs and other third-party certifications as a primary filter in the selection process, moving beyond just NRC ratings or cost. This trend, which elevates lifecycle environmental performance to a core purchasing criterion, is most visible in North American and European green building projects.
Acoustical Ceiling Market Segmentation
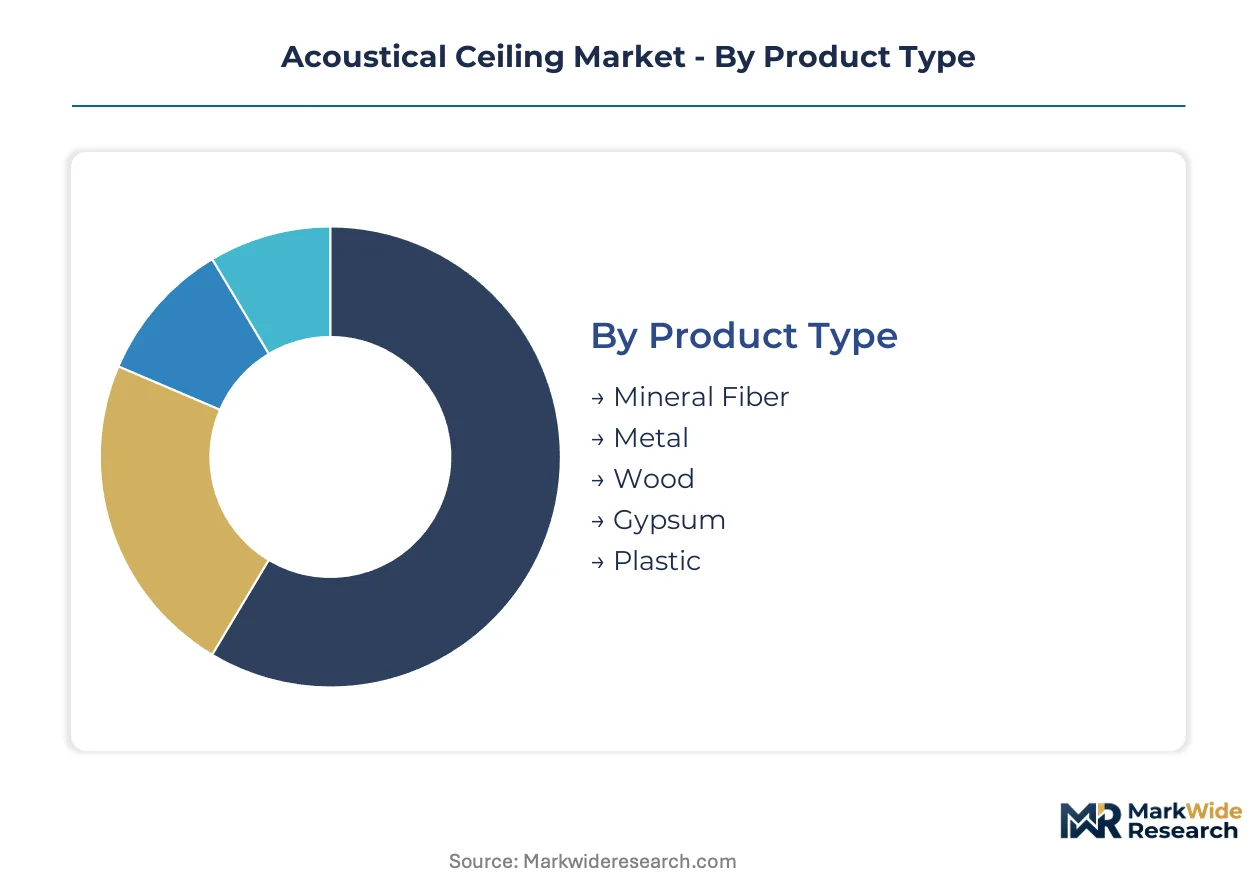
Understanding the acoustical ceiling market through segmentation provides critical insights into product performance, installation complexity, and end-user requirements. This detailed breakdown helps stakeholders identify specific demand drivers and competitive landscapes across various product types and applications. Market dynamics vary significantly across these distinct segments.
Product Type:
Margin pools for acoustical ceilings largely concentrate within premium material segments offering superior aesthetic and acoustic performance.
- Mineral Fiber:Mineral fiber tiles constitute a porous composition designed for broad sound absorption. Demand from commercial office renovations in China drives continued volume, balancing cost-effectiveness with functional acoustic control.
- Metal:Metal ceiling systems, often perforated aluminum or steel, offer high durability and modern aesthetics, suitable for humid or high-traffic areas. Architects specify metal systems for airports in the United States, valuing their longevity and design flexibility.
- Wood:Wood panels provide natural aesthetics and good acoustic properties, favored in high-end hospitality and corporate spaces.
- Gypsum:Gypsum-based acoustical panels integrate sound absorption with fire resistance, common in institutional facilities.
- Plastic:Plastic or PVC acoustical panels offer moisture resistance and cleanability, utilized in food processing and healthcare cleanrooms.
The dominant share belongs to Mineral Fiber, while Metal is closing the gap fastest.
Installation:
The cost tier for acoustical ceiling installations varies significantly based on system complexity and labor intensity.
- Suspended:Suspended ceiling systems involve a grid framework hung from the structural slab, supporting lay-in or tegular panels. Open-plan office designs in Europe frequently utilize suspended systems to integrate lighting and HVAC while providing acoustic comfort.
- Floating Ceiling:Floating ceiling systems are custom-engineered panels or baffles suspended independently, creating a distinct visual and acoustic feature. High-performance concert halls and auditoriums globally specify floating ceilings for precise sound diffusion and absorption.
- Direct Attach:Direct attach panels adhere directly to the substrate, suitable for smaller rooms or where minimal plenum space is available.
- Stretch Ceiling:Stretch ceilings consist of a fabric or PVC membrane stretched over a perimeter track, offering seamless aesthetics and integrated lighting options.
Installation complexity influences project timelines, with Floating Ceiling systems requiring specialized expertise, while Suspended installations remain the most common.
Application:
Volume drivers for acoustical ceiling applications are heavily concentrated in sectors undergoing significant new construction and renovation.
- Commercial Buildings:Commercial buildings encompass offices, retail spaces, and convention centers, prioritizing both aesthetic appeal and speech intelligibility. New office developments in the United States drive demand for systems that enhance employee well-being and productivity.
- Institutional Facilities:Institutional facilities include hospitals, schools, and government buildings, requiring stringent acoustic performance for patient privacy and learning environments. Healthcare expansion in China necessitates high-NRC ceilings for optimal healing spaces.
- Entertainment Venues:Entertainment venues like theaters and studios demand precise acoustic control to optimize sound quality for performances and recordings.
- Transportation Terminals:Transportation terminals, such as airports and train stations, utilize durable acoustical ceilings to manage noise from large crowds and public address systems.
Commercial Buildings consistently generate the largest demand, with Institutional Facilities showing the steepest expansion trajectory due to regulatory requirements.
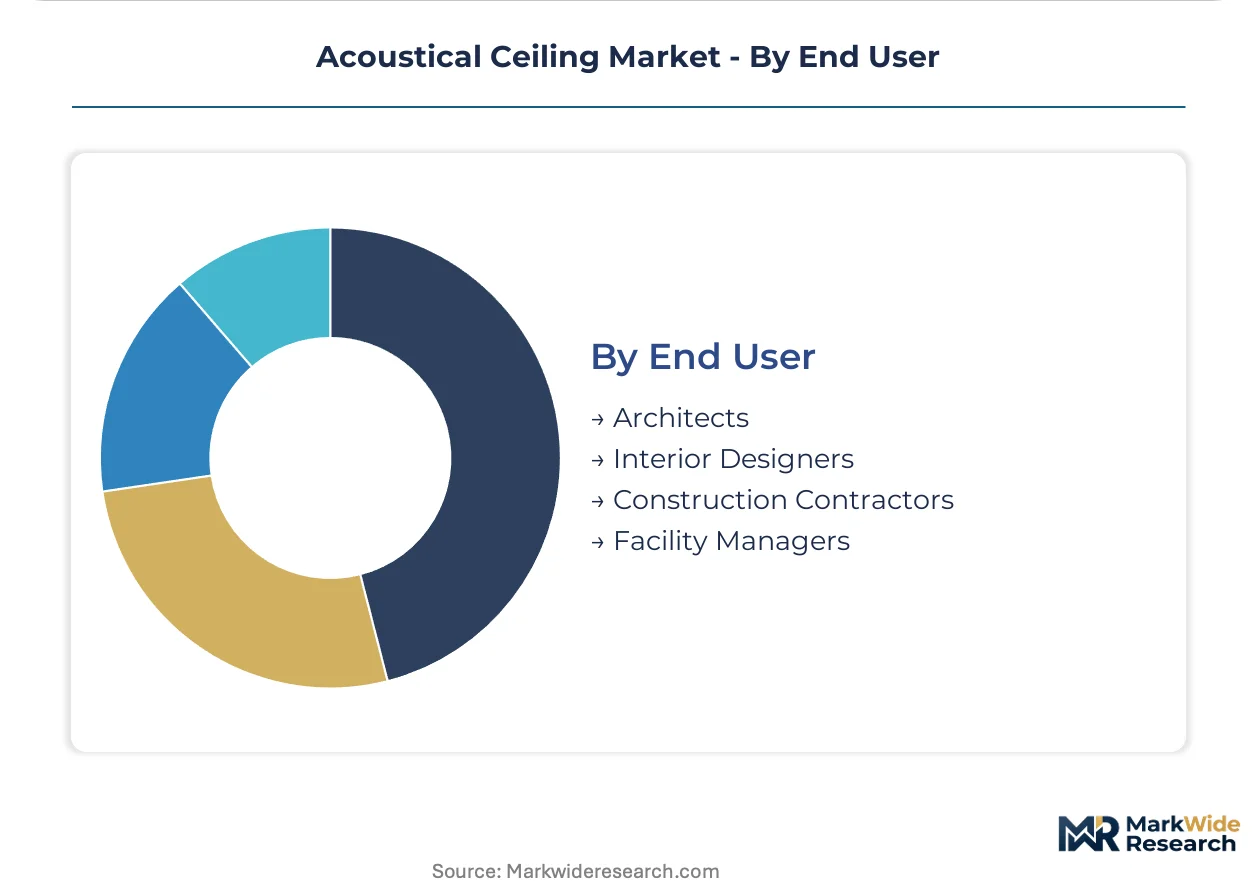
End User:
Decision-making influence in acoustical ceiling specification is distributed across various professional roles, each prioritizing different product attributes.
- Architects:Architects lead the initial design phase, specifying aesthetic, performance, and sustainability criteria for ceiling systems. They often choose premium wood or metal systems for their design flexibility and certified environmental performance in European projects.
- Interior Designers:Interior designers focus on visual integration and occupant comfort, selecting ceiling finishes that complement overall space aesthetics.
- Construction Contractors:Construction contractors manage procurement, installation logistics, and budget adherence for ceiling projects. They prioritize ease of installation and material availability, especially for large-scale commercial developments in North America.
- Facility Managers:Facility managers oversee long-term maintenance and operational costs, favoring durable and easily cleanable ceiling solutions for commercial properties.
Construction Contractors drive significant purchasing volume, while Architects increasingly shape material specifications through early design decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards for building materials influence acoustical ceiling specifications across Asia-Pacific. These regulations emphasize performance and safety in new commercial and institutional projects. The global market shows diverse regional growth patterns.
China
Demand for acoustical ceilings in China stems from extensive commercial construction and healthcare facility expansion. The country's dual carbon goals promote sustainable building materials in large-scale projects. Major urban centers like Shanghai and Beijing are seeing significant adoption in new office towers and hospitals.
United States
New hospital and office construction in the United States drives significant demand for high-NRC acoustical ceilings. EPA guidelines on indoor air quality directly influence material choices for these building projects. Construction activity in metropolitan areas such as New York and Los Angeles prioritizes advanced sound control solutions.
Germany
Open-plan office designs and the EU Green Deal drive demand for performance-tiered acoustical solutions in Germany. CE marking is mandatory for market access, ensuring product compliance with European health and safety standards. Frankfurt's financial district and Berlin's tech hubs integrate sophisticated suspended ceiling systems.
India
Rapid commercial and institutional construction across India presents substantial opportunities for acoustical ceiling market expansion. BIS standards for building materials increasingly incorporate acoustic performance criteria for public spaces. Tier-1 cities like Mumbai and Bengaluru are experiencing a surge in demand for modern office and healthcare fit-outs.
Acoustical Ceiling Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the acoustical ceiling market. This tiered structure reflects the diverse product offerings and installation complexities across various applications. Archetypes include global material conglomerates leveraging extensive distribution, specialized acoustic solution providers targeting niche environments, and regional manufacturers focusing on cost-effective, high-volume segments. Companies pursue product innovation, particularly in sustainable materials and smart building integration, alongside strategic partnerships to expand their market reach and installation capabilities.
Among the established players, Armstrong World Industries exemplifies a global leader leveraging extensive distribution networks and strong brand recognition to secure large commercial projects. Saint-Gobain Ecophon represents a specialist in high-performance solutions, particularly tailored for acoustically sensitive environments such as hospitals and concert halls. USG Corporation sits within the integrated system providers, offering comprehensive wall-to-ceiling solutions that streamline construction processes. These companies collectively anchor different segments of the market, from broad commercial applications to highly specialized acoustic requirements in institutional settings.
| Leading Market Players |
|---|
| Rockfon |
| Hunter Douglas Architectural |
| Armstrong World Industries |
| Georgia-Pacific |
| Saint-Gobain Ecophon |
| USG Corporation |
| Knauf AMF |
| ROCKWOOL |
| CertainTeed Corporation |
| Others |
Cost & Logistics Intelligence
Bio-soluble mineral fiber formulations replacing traditional mineral wool simultaneously reshapes material sourcing geographies and pricing economics for premium applications. This substitution dynamic influences manufacturing investments and procurement strategies across the acoustical ceiling market.
Pricing Analysis
Geographic price-spread observations indicate higher average unit costs for specialized systems in Europe compared to volume segments in China. Project-based pricing dominates the market, reflecting customization and installation complexity. Price differentiation stems from certified acoustic performance levels and the aesthetic appeal of premium materials like wood and metal. Cost compression in mineral fiber tiles intensifies due to high-volume demand from commercial office renovations in China. Construction contractors exhibit significant price sensitivity, while architects prioritize value-based pricing for long-term durability and design flexibility.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized components, are influenced by global shipping lanes and regional manufacturing hubs. The supply chain for acoustical ceilings draws from concentrated production in China for mineral fiber, the United States for advanced fiberglass, and Germany for specialized metal systems. Key raw material dependencies include mineral fiber, fiberglass, aluminum, and wood. Raw material price volatility represents a significant structural risk, impacting manufacturer margins and project bidding. Downstream distribution runs through extensive networks managed by large players like Armstrong World Industries, complemented by specialized channels for high-performance solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acoustical ceiling market navigates a platform-economics inflection, driven by the integration of modular ceiling panels with smart building systems. This interoperability shift creates new value propositions for end-users.
For Market Incumbents: Compound investment in bio-soluble mineral fiber formulations to meet stringent indoor air quality standards. Acquire specialized installation firms to mitigate skilled labor shortages and control project timelines. Focus R&D on integrated smart ceiling solutions, embedding sensors and lighting into modular panels. This strategy defends against substitution from exposed structural designs and new entrants offering integrated solutions.
For New Entrants and Emerging Players: Certification fast-track programs, particularly for Environmental Product Declarations (EPDs), offer a distinct market entry advantage. Target the rapidly expanding institutional facilities segment in Southeast Asia, focusing on performance-tiered solutions. Offer comprehensive lifecycle assessment data to architects and corporate clients as a primary go-to-market angle. This approach leverages demand for sustainable building materials and underpenetrated emerging markets.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional manufacturers specializing in cost-effective mineral fiber solutions, offering consolidation opportunities. Long-term viability rests on sustained construction activity and evolving green building mandates. Target specialized acoustic solution providers with strong R&D in sustainable materials or advanced installation capabilities. The signal to watch is the increasing adoption rate of circular economy products and integrated smart ceiling systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Bio-Soluble Mineral Fiber R&D | Enhances compliance with health and safety codes, particularly in schools and hospitals. |
| Acquire Specialized Installation Firms | Addresses skilled labor shortages and streamlines complex project execution for custom systems. |
| Expand into Southeast Asian Construction | Captures significant demand from rapid commercial and institutional development in emerging economies. |
| Develop Integrated Smart Ceiling Solutions | Unlocks new revenue streams by combining acoustics with technology like sensors and lighting. |
| Secure EPD and Green Building Certifications | Meets architect and corporate client demand for verified environmental performance and market access. |
Research Approach
Cross-validation between primary interviews with industry stakeholders and extensive secondary research anchors the qualitative findings of this study. This approach combines insights from architects, construction contractors, facility managers, and material scientists with data from ISO standards, EPA guidelines, EU Green Deal documents, and LEED/BREEAM reports. Bottom-up market sizing and top-down validation ensure robust data integrity.
Sensitivity analysis framing guides the forecast framework across the analysis window, modeling various market scenarios. Segmentation dimensions, including product type (mineral fiber, metal, wood), installation method (suspended, floating), application (commercial, institutional), and regional demand, were meticulously projected. Compound Annual Growth Rates (CAGRs) derive from historical growth patterns and future construction pipeline analysis, with new construction starts and green building certification rates serving as key inputs.
Underlying assumptions cover stable economic growth and consistent regulatory enforcement, with deviation risk concentrated in unforeseen raw material price volatility or significant shifts in global trade policies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gypsum Board Market
Building & Construction Materials
Barn Door Hardware Market
Building & Construction Materials
Cement Grinding Aids Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Turkey Ceramic Tiles Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Building Modules Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
PVC Window Market