
 Chain Link Fencing Market | 2026-2036
Chain Link Fencing Market Size, Share, and Industry Trends Forecast 2026-2036
Chain Link Fencing Market Outlook
Residential homeowner demand is collapsing as commercial and municipal contractor procurement dominates new order flows. Betafert dominates North American distribution through its Master Halco subsidiary, leveraging vertical integration from steel wire rod to finished fence systems. Bekaert competes on specialty alloy formulations for corrosion-resistant coastal installations. Jerith Manufacturing Company anchors the decorative architectural segment with aluminum chain link alternatives for institutional clients.
Chain link fencing consists of woven steel wire mesh formed into a diamond pattern and attached to steel posts, typically manufactured from galvanized steel wire with zinc coatings ranging from 1.0 to 2.5 oz per square foot for corrosion protection. The product serves primarily as a cost-effective perimeter barrier for security, boundary demarcation, and access control across commercial, industrial, and institutional properties. Galvanized steel product type sustains the largest volume share due to its balance of durability and installed cost, while vinyl coated alternatives capture margin pools in aesthetic-sensitive applications such as residential communities and recreational facilities. Professional installation channels lead value capture as commercial and municipal buyers prioritize warranty-backed workmanship over DIY approaches.
ASTM International governs wire coating weights and mesh dimensional tolerances, while OSHA standards influence worker safety protocols during installation. The EPA regulates zinc runoff from galvanized products in environmentally sensitive watersheds, pushing manufacturers toward thicker polymer coatings or alternative substrate materials. Stakeholders must monitor evolving municipal procurement specifications that increasingly require Buy America compliance for federally funded infrastructure projects.
Market Dynamics
Municipal procurement concentration is restructuring the Chain Link Fencing Market as school districts and transportation authorities consolidate purchases through cooperative purchasing agreements, squeezing regional distributors and privileging national-scale manufacturers with certified installation networks.
Growth Catalysts
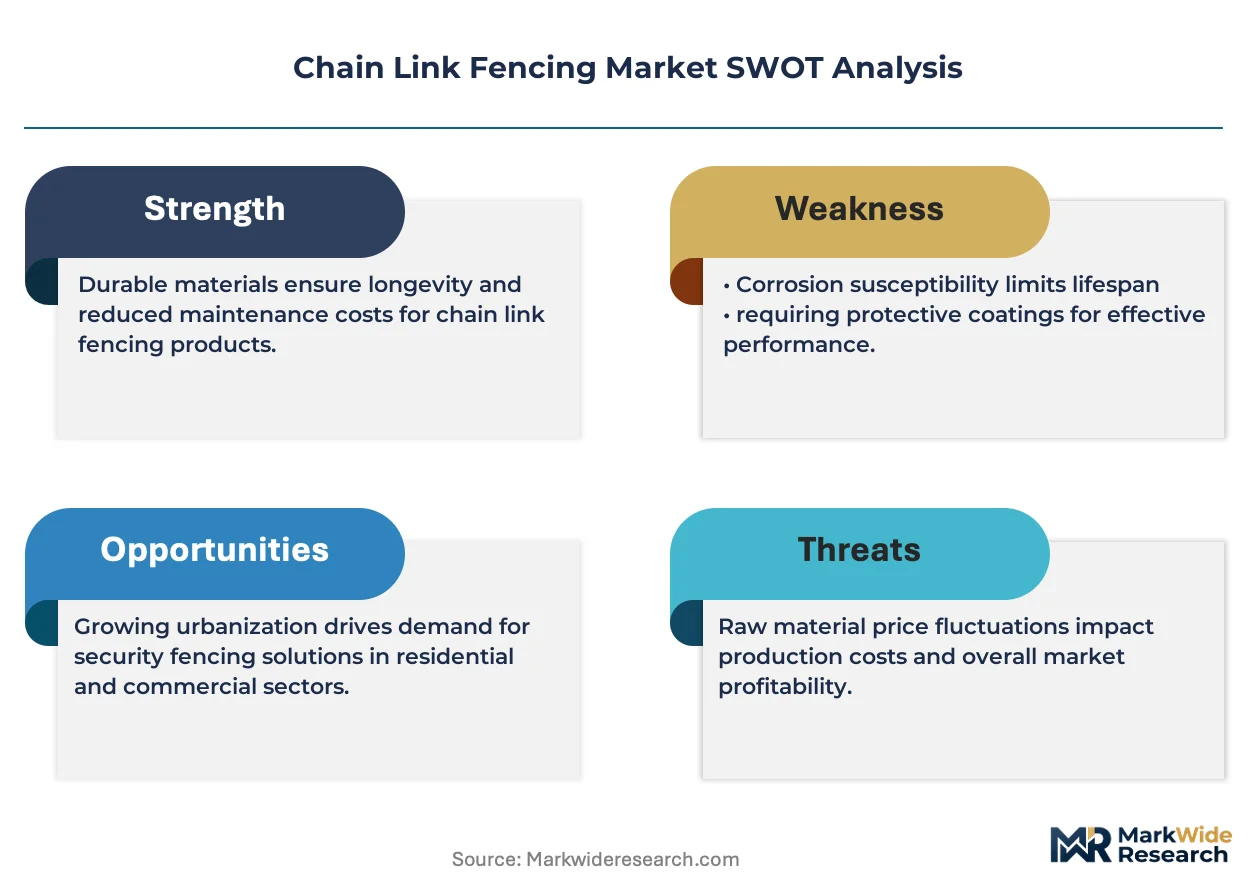
- Federal infrastructure spending:The Infrastructure Investment and Jobs Act channels funds toward perimeter security at ports, bridges, and transit facilities across Texas, Florida, and California. State transportation departments are bundling fencing with broader civil works contracts.
- ASTM A392 specification tightening:Heavier zinc coating mandates for galvanized wire extend product lifespans in corrosive environments. Coastal municipalities now specify 2.5 oz per square foot minimums for salt-air exposure.
- Security integration:Sensor-embedded mesh systems combining physical barriers with intrusion detection are displacing passive installations at data centers and utility substations.
Market Restraints
- Zinc price volatility:Galvanized wire coating costs fluctuate with London Metal Exchange zinc futures, compressing margins for coating-dependent product lines when raw material spikes exceed contract escalation clauses.
- Polymer substitution:Vinyl privacy fencing and composite alternatives capture residential perimeter applications where aesthetic requirements outweigh chain link's cost advantage.
- Buy America compliance:Federally funded projects require domestic steel sourcing, limiting contractor flexibility when domestic wire rod capacity tightens during infrastructure booms.
Strategic Opportunities
- Smart fencing convergence:Mesh-integrated fiber optic sensing and video analytics create premium product tiers for critical infrastructure operators seeking unified perimeter intelligence.
- Recreational facility modernization:Parks departments in Sun Belt states are replacing aging backstops and outfield fencing with powder-coated systems that reduce maintenance cycles.
- EPA watershed runoff rules:Stricter zinc discharge limits in Chesapeake Bay and Pacific Northwest watersheds favor polymer-coated or aluminum substrate alternatives with lower environmental liability.
Industry Challenges
- Welder certification bottlenecks:AWS D1.1 structural welding qualifications for fence post installation lag demand spikes, delaying project mobilization during municipal procurement windows.
- Mesh-tensioning equipment scarcity:Automated stretcher-bar machinery for high-tensile installations requires capital outlays that smaller regional installers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chain Link Fencing Market |
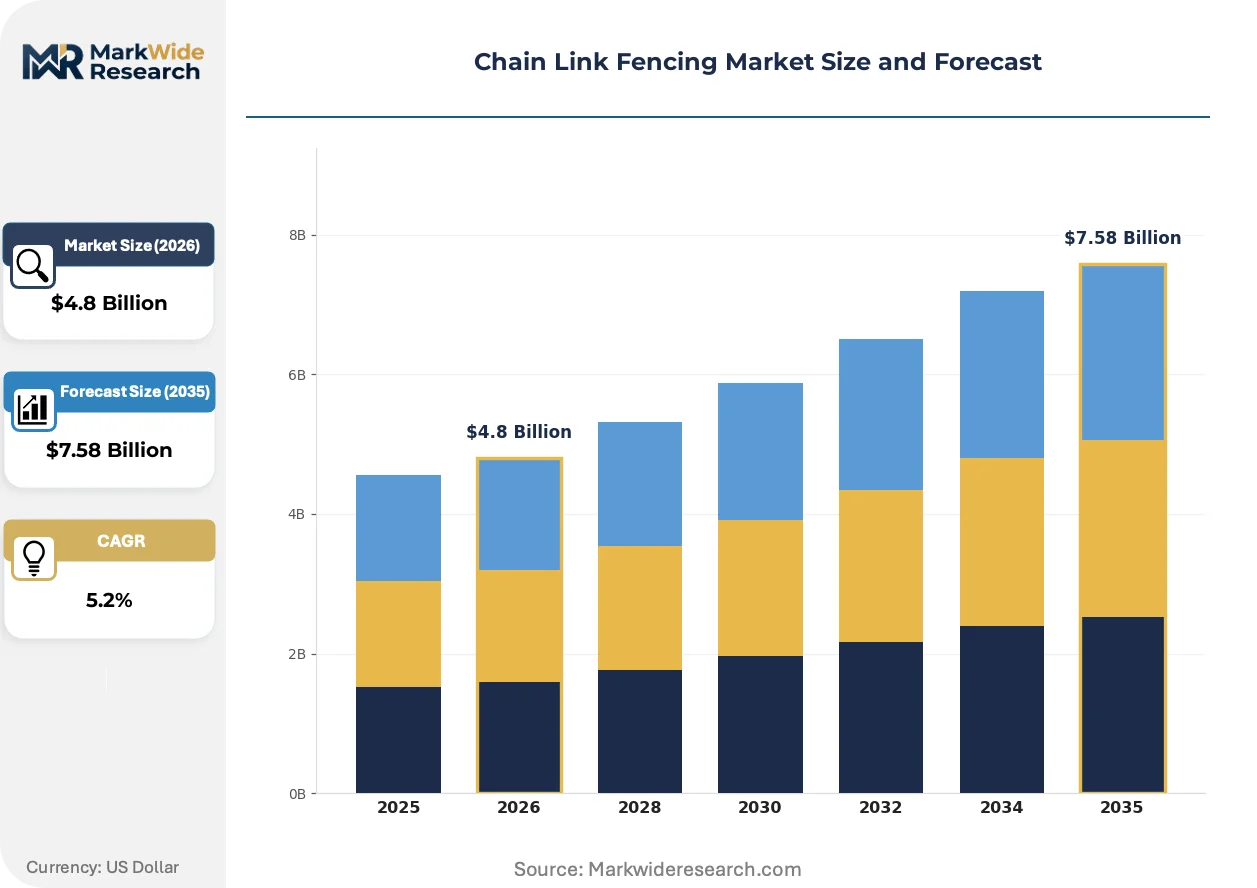
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Galvanized Steel, Vinyl Coated, Aluminum, Stainless Steel Application: Residential, Commercial, Industrial, Sports Facilities End User: Homeowners, Contractors, Municipalities, Businesses Installation Type: DIY, Professional, Prefabricated, Customized |
| Companies Covered | Master Halco, Betafence, Jerith Manufacturing Company, Ameristar Fence Products, Bekaert, Hoover Fence Co., Merchants Metals, Deacero, Allied Tube & Conduit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chain Link Fencing Market Strategic Shifts
Product differentiation is migrating from substrate metallurgy to integrated system intelligence, with manufacturers competing on installation speed, warranty terms, and compatibility with third-party security platforms rather than wire gauge alone.
Polymer coating formulations are fragmenting the traditional galvanized-dominant product architecture. Fluoropolymer and polyester powder coatings now exceed 3-mil thicknesses for coastal institutional applications, extending service intervals beyond fifteen years. Florida school districts and California water treatment facilities specify these systems despite forty percent installed cost premiums.
OSHA silica exposure rules for abrasive blasting operations are reshaping surface preparation protocols. Manufacturers are shifting to mechanical descaling and pre-galvanized wire feedstock to eliminate respirable crystalline silica risks. Texas-based fabricators have retooled coating lines to comply, passing compliance costs through municipal contract pricing.
Specification authority is concentrating among architectural-engineering firms managing design-build infrastructure contracts. These intermediaries now dictate mesh patterns, post schedules, and gate automation standards, compressing direct manufacturer influence over end-use product selection. California Department of Transportation projects exemplify this shift toward consolidated technical specification control.
Chain Link Fencing Market Segmentation
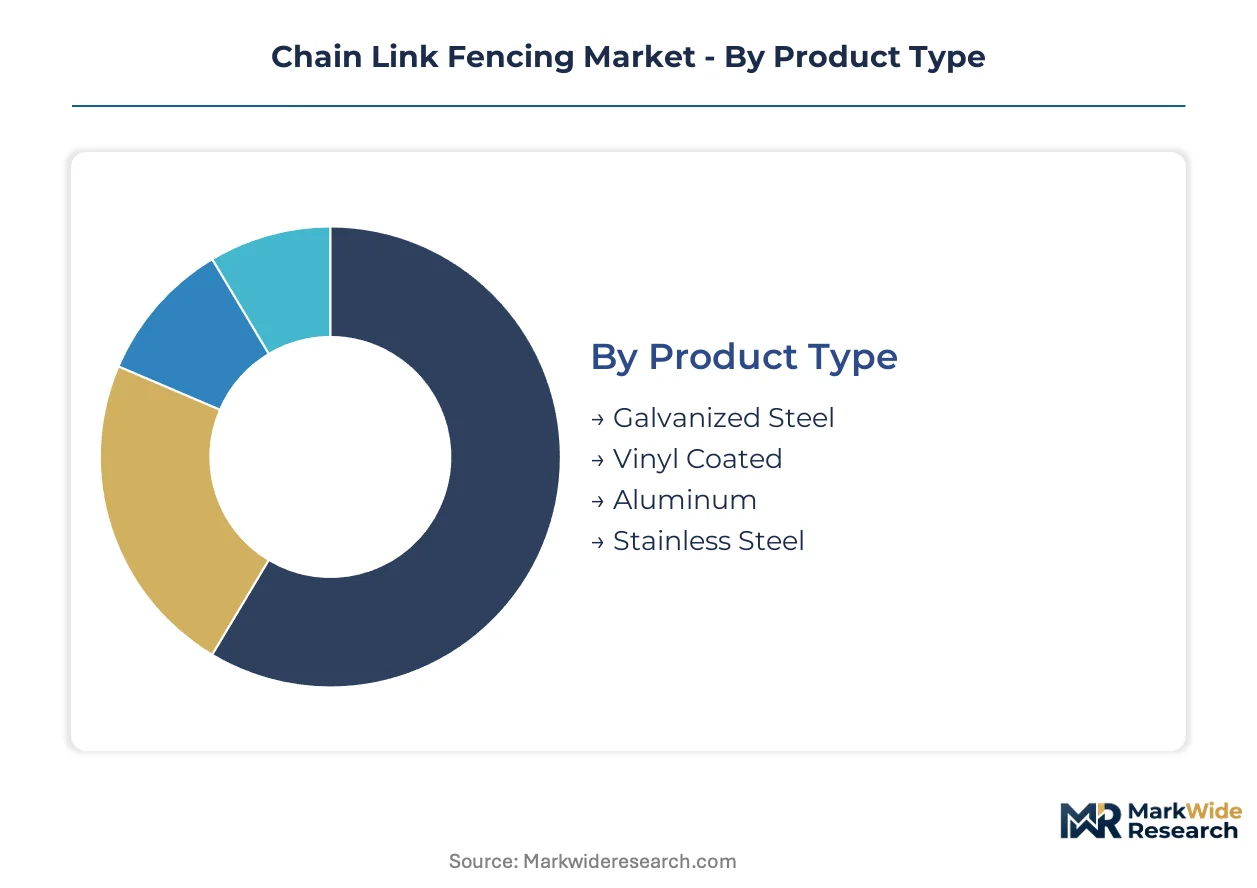
Chain link fencing procurement patterns diverge sharply across material specifications and buyer categories. Municipal infrastructure contracts favor standardized galvanized systems, while aesthetic-sensitive residential and recreational applications drive coating technology premiums.
Product Type:
Vinyl coated and aluminum alternatives exert mounting substitution pressure on traditional galvanized steel as coastal municipalities and recreational facilities prioritize corrosion resistance and visual integration.
- Galvanized Steel:Zinc-coated carbon steel wire with coating weights from 1.0 to 2.5 oz per square foot delivers baseline corrosion protection for cost-sensitive perimeter applications. Texas school districts and Florida transportation authorities specify this grade for standard security installations where budget constraints dominate material selection.
- Vinyl Coated:PVC or polyester polymer layers applied over galvanized cores extend service life and enable color matching with institutional branding. California water treatment facilities and Pacific Northwest parks departments specify these systems to satisfy EPA watershed runoff regulations while reducing maintenance cycles.
- Aluminum:Lightweight alloy substrates eliminate galvanic corrosion risks in salt-air environments. Coastal installations in Florida and California increasingly specify aluminum for boardwalk perimeters and marina security.
- Stainless Steel:Austenitic grades provide maximum corrosion resistance for chemical processing facilities and food-grade perimeters. Premium pricing limits deployment to critical infrastructure with extreme exposure conditions.
Galvanized steel retains volume leadership; vinyl coated holds the steepest expansion curve.
Application:
Commercial and industrial end-uses concentrate procurement volume through design-build contracts, while residential demand fragments across big-box retail and local installer channels.
- Residential:Single-family perimeter applications face intense competition from vinyl privacy fencing and composite alternatives. Homeowner procurement has shifted toward DIY installation of lower-specification systems as professional channels prioritize commercial contracts.
- Commercial:Retail, office, and warehouse properties specify mesh-integrated access control and automated gate systems. California commercial construction activity drives specification of powder-coated architectural grades for visible perimeters.
- Industrial:Manufacturing facilities and logistics yards demand high-tensile mesh with anti-climb specifications. Texas and Florida industrial development corridors sustain demand for rapid-installation systems with extended warranty terms.
- Sports Facilities:Backstops, outfield fencing, and court enclosures require specialized mesh tensioning and padding systems. Sun Belt states are modernizing recreational infrastructure with color-coated systems that reduce field maintenance.
Commercial applications dominate value capture; sports facilities are expanding most quickly.
End User:
Contractor and municipal procurement consolidation is marginalizing direct manufacturer relationships with smaller end users.
- Homeowners:Price-sensitive retail purchasers increasingly defer to big-box inventory of standard mesh gauges and post schedules. Volume share has contracted as professional channels capture commercial and institutional demand.
- Contractors:Design-build and civil works generalists bundle fencing with broader construction contracts. These intermediaries now dictate specification authority through consolidated procurement agreements.
- Municipalities:School districts and transportation authorities leverage cooperative purchasing to extract volume pricing. Federal infrastructure funding channels through state transportation departments in Texas, Florida, and California.
- Businesses:Corporate facility managers prioritize integrated security systems combining physical barriers with sensor networks. Data center and utility substation operators specify smart fencing convergence.
Municipalities anchor volume procurement; businesses command the highest specification tiers.
Installation Type:
Professional certification requirements and equipment capital intensity are stratifying the installer base.
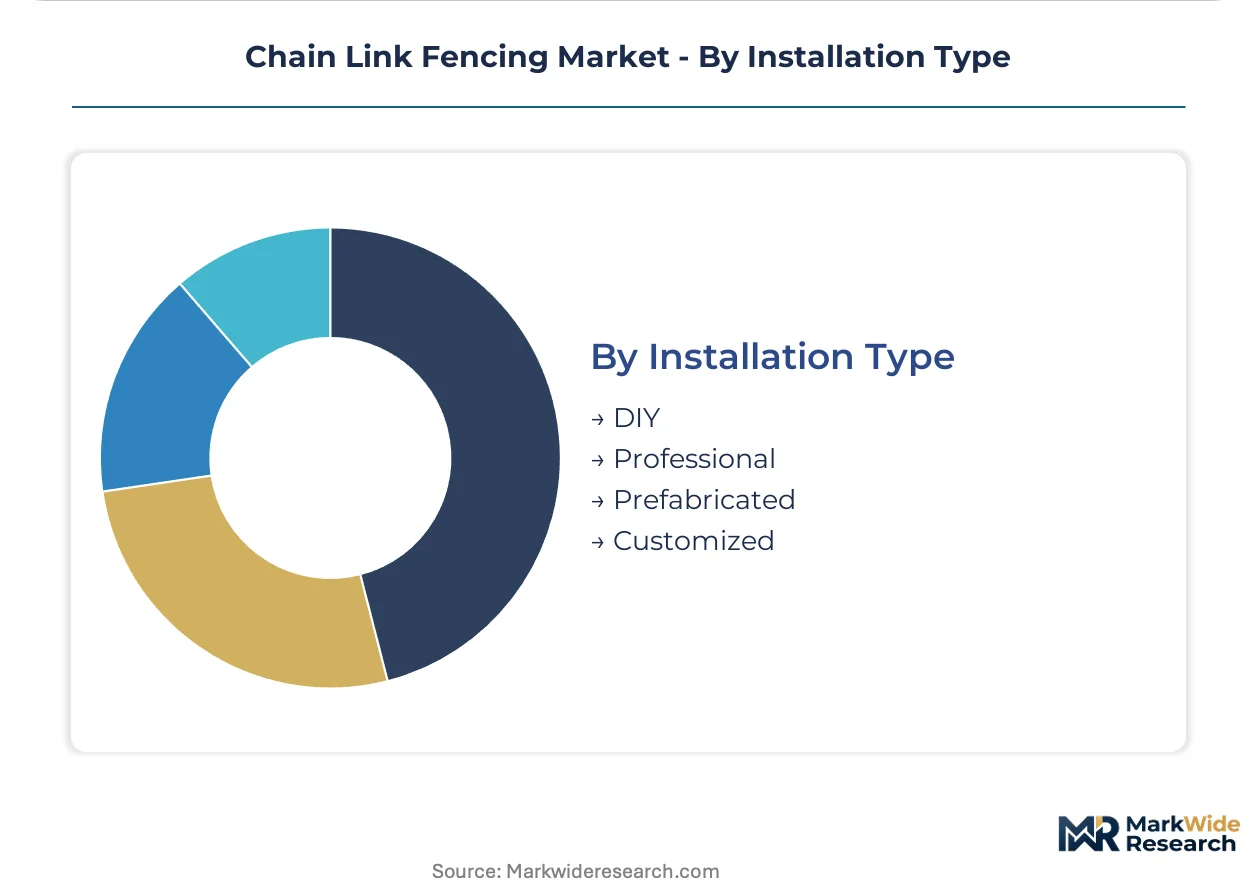
- DIY:Pre-packaged panel systems with simplified post-setting hardware target residential weekend installers. Volume has declined as commercial procurement concentrates in certified channels.
- Professional:AWS D1.1-qualified welding crews and automated stretcher-bar machinery deliver warranty-backed workmanship. Municipal contracts increasingly mandate certified installation networks.
- Prefabricated:Factory-assembled panel systems reduce field labor for rapid-deployment security perimeters. Transportation authorities specify these for emergency infrastructure protection.
- Customized:Site-specific engineering accommodates terrain variation, existing structure integration, and specialized security requirements. Architectural-engineering firms control specification for complex institutional projects.
Professional installation commands value leadership; prefabricated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach perimeter modernization anchors United States demand as federal infrastructure funding channels through California, Texas, and Florida transportation authorities. School district security upgrades and data center construction sustain procurement velocity across Sun Belt metropolitan corridors.
United States
California Department of Transportation bundles chain link fencing with bridge and transit facility contracts, specifying ASTM A392 heavy zinc coatings for coastal exposure. EPA watershed runoff rules in Chesapeake Bay and Pacific Northwest regions favor polymer-coated alternatives. Dallas-Fort Worth and Houston industrial development corridors drive specification of rapid-installation security systems for logistics yards.
Canada
Trans Mountain Pipeline expansion and port perimeter security projects concentrate demand in British Columbia and Alberta. Health Canada guidelines influence worker safety protocols for installation crews. Toronto and Vancouver metropolitan areas specify powder-coated architectural grades for visible institutional perimeters.
Mexico
Nearshoring manufacturing investment in Nuevo León and Baja California sustains industrial facility fencing demand. Federal highway and rail infrastructure programs channel procurement through state transportation departments. Monterrey and Tijuana industrial parks specify galvanized systems for cost-sensitive warehouse perimeters.
Germany
REACH regulations govern zinc coating formulations for galvanized wire products. Industrial automation facilities and logistics hubs in North Rhine-Westphalia and Bavaria specify mesh-integrated access control systems. Frankfurt and Stuttgart metropolitan construction activity drives specification of architectural-grade powder coatings.
China
GB standards for steel wire mesh products govern domestic manufacturing quality. Dual carbon goals accelerate specification of lower-emission coating processes in Yangtze River Delta manufacturing clusters. Shanghai and Shenzhen infrastructure investment sustains demand for high-tensile security perimeters at ports and utility facilities.
Chain Link Fencing Market Competitive Environment
Listed leaders compete with private specialists across certification and installation network dimensions. The vendor base stratifies into national-scale manufacturers with certified welding crews, regional fabricators serving municipal cooperative purchasing agreements, and specialty coating houses targeting coastal corrosion applications. Three archetypes dominate: vertically integrated steel-to-fence systems operators, alloy formulation specialists, and decorative architectural alternatives providers. Competitive moves concentrate on backward integration into wire rod supply and geographic expansion of installation certification networks.
Among North American fabricators, Master Halco exemplifies scale-driven distribution through captive supply chain control, while Bekaert occupies a position within specialty alloy formulation for salt-air environments. Jerith Manufacturing Company represents the decorative architectural tier with aluminum substrate alternatives. These three anchors illustrate how competitive positioning separates on coating technology, substrate metallurgy, and installation network density rather than wire gauge alone.
| Leading Market Players |
|---|
| Master Halco |
| Betafence |
| Jerith Manufacturing Company |
| Ameristar Fence Products |
| Bekaert |
| Hoover Fence Co. |
| Merchants Metals |
| Deacero |
| Allied Tube & Conduit |
| Others |
Value Chain & Pricing Dynamics
Long-term municipal offtake agreements lock in both galvanized wire rod supply access and price visibility for contractors serving Texas and California transportation authorities, insulating procurement from zinc futures volatility while committing buyers to ASTM A392 specification tiers.
Pricing Analysis
Volume-discount tiering structures separate municipal cooperative purchasing pools from fragmented residential retail. Municipal buyers extract pricing leverage through consolidated specification authority, while DIY channels face premium markups on pre-packaged panel systems. Cost compression in economy-grade galvanized mesh is intensifying because regional fabricators compete for federal infrastructure contract flow. School districts and transportation authorities exhibit lowest price sensitivity due to warranty-backed installation mandates, whereas residential homeowners defer purchases during zinc price spikes.
Supply Chain Analysis
Inventory lead times for high-tensile mesh-tensioning equipment stretch project mobilization windows, particularly when AWS D1.1-certified welding crews face certification bottlenecks. Raw material supply draws from United States, Mexico, and China wire rod production, with coating operations concentrated in Texas and Florida. Zinc price volatility on London Metal Exchange futures creates margin compression risk for coating-dependent product lines. Distribution runs through Master Halco's captive network for national-scale contracts, while regional fabricators serve cooperative purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Federal infrastructure spending through the Infrastructure Investment and Jobs Act positions chain link fencing in early-cycle expansion, with perimeter security mandates at ports and transit facilities accelerating specification velocity across Sun Belt states.
For Market Incumbents: Fortify installation certification networks against welder qualification bottlenecks that delay municipal contract mobilization. Pursue backward integration into wire rod supply to buffer zinc price volatility exposure. Master Halco's captive distribution model demonstrates how channel control insulates margin capture from regional fabricator competition. For New Entrants and Emerging Players: Smart fencing integration services represent an under-served layer where incumbents lack fiber optic sensing deployment expertise. Target data center and utility substation operators seeking unified perimeter intelligence platforms. Lead with sensor-embedded mesh pilot programs to bypass established coating technology barriers. For Investors and Strategic Acquirers: Capital is best deployed toward regional fabricators with certified welding crews and municipal cooperative purchasing relationships, positioned for federal infrastructure contract flow. Long-term viability hinges on EPA watershed compliance capabilities as zinc runoff rules tighten. Monitor ASTM specification tightening announcements as inflection indicators for coating technology upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Rod Supply | Captive zinc coating operations buffer London Metal Exchange futures volatility for municipal contractors. |
| Smart Fencing Convergence | Mesh-integrated fiber optic sensing creates premium tiers for critical infrastructure perimeter intelligence. |
| Cooperative Purchasing Network Expansion | Certified installation crews extract volume pricing leverage from consolidated school district procurement. |
| Polymer Coating Formulation Investment | Fluoropolymer systems exceed EPA watershed runoff limits in Chesapeake Bay and Pacific Northwest regions. |
| Prefabricated Panel System Scale-Up | Factory-assembled systems reduce field labor for transportation authority emergency infrastructure protection. |
Study Parameters
Operator-level perspectives from municipal procurement officers, AWS-certified welding contractors, coating line plant managers, and architectural-engineering specification writers anchored the qualitative base. Primary fieldwork combined with secondary validation against ASTM International standards documentation, EPA watershed discharge filings, and Infrastructure Investment and Jobs Act funding allocation records. Bottom-up project pipeline analysis triangulated against top-down steel wire rod consumption estimates.
Sensitivity analysis tested forecast outputs against zinc price volatility scenarios and municipal procurement timing variations across the projection horizon. Segmentation dimensions modeled include material substrate type, coating technology tier, installation channel, and end-use application intensity. CAGRs derived from installed base replacement cycles and federal infrastructure spending authorization trajectories. Forecast inputs incorporated wire rod capacity utilization rates and welder certification pipeline data.
Material uncertainties — zinc futures spikes exceeding contract escalation clauses, ASTM specification revision timing, and EPA watershed rule enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding infrastructure spending continuity and domestic steel sourcing capacity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Pre-Insulated Pipes Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Glazed Tiles Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Global Raised Access Floor Systems Market
Building & Construction Materials
Concrete Cooling Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market