
 HVAC Airflow and Blend Door Actuator Systems Market | 2026-2036
HVAC Airflow and Blend Door Actuator Systems Market Size, Share, and Industry Trends Forecast 2026-2036
HVAC Airflow and Blend Door Actuator Systems Market Insights
A capital-intensity divergence between high-volume motor manufacturers and precision sensor integrators is rotating competitive advantage toward players with captive electronics capabilities. DENSO Corporation leverages its semiconductor affiliate to control sensor-actuator integration costs. Valeo sustains European OEM relationships through dedicated climate-comfort R&D centers. BorgWarner competes by extending its powertrain electronics expertise into thermal management actuation.
HVAC airflow and blend door actuator systems are electromechanical devices that modulate air distribution and temperature mixing within vehicle climate control systems, typically operating through stepper or servo motors with positional feedback sensors to achieve duct airflow accuracy within degrees Celsius. These systems serve the primary industrial purpose of maintaining cabin thermal comfort while optimizing energy consumption from the vehicle's heating, ventilation, and air conditioning core. Brushless DC motor actuators now command premium positioning as electrified vehicles demand higher efficiency and reduced electromagnetic interference. Digital control architectures represent the fastest-expanding technology segment, displacing analog systems as OEMs mandate CAN bus integration and over-the-air diagnostic capability. Passenger vehicles anchor application volume, though commercial trucks present concentrated margin pools due to durability specifications and aftermarket replacement cycles.
The EPA enforces fuel economy standards that directly incentivize optimized HVAC energy draw, while the EU F-Gas Regulation phases down refrigerants with high global warming potential, forcing actuator redesigns for next-generation heat pump architectures. China's MIIT implements GB standards for new energy vehicle energy consumption that encompass thermal system efficiency, creating compliance-driven replacement demand. Stakeholders must monitor how refrigerant chemistry transitions and vehicle electrification timelines reshape actuator specification roadmaps across regulatory jurisdictions.
Market Dynamics
Vehicle electrification is compressing thermal management energy budgets, forcing actuator architectures toward brushless DC motors with integrated position sensing to meet precision requirements under strict power constraints.
Growth Catalysts
- EPA fuel economy standards:Stringent vehicle efficiency mandates in the United States incentivize OEMs to optimize HVAC energy draw, driving specification upgrades to precision actuation systems.
- China NEV energy consumption GB standards:MIIT-implemented regulations for new energy vehicle thermal efficiency create compliance-driven replacement cycles for legacy actuator designs.
- Heat pump architecture proliferation:Electrified vehicles require actuators capable of managing complex refrigerant flow paths across multiple thermal zones simultaneously.
Market Restraints
- Rare earth magnet cost volatility:Neodymium and dysprosium price swings embedded in brushless DC motor supply chains compress margin predictability for mid-tier suppliers.
- Semiconductor foundry concentration:Taiwan and South Korea manufacturing dominance for motor control ICs creates single-source vulnerability during capacity constraints.
- EU F-Gas refrigerant phase-down:Accelerated HFC reduction timelines force premature actuator redesigns before amortization of current-generation tooling investments.
Strategic Opportunities
- Commercial truck aftermarket:Heavy-duty vehicle durability specifications and compressed replacement cycles in North America offer concentrated margin pools for specialized actuator variants.
- India automotive manufacturing:Domestic OEM scaling of climate control module production under PLI scheme incentives creates localization opportunities for tier-one actuator suppliers.
- CAN bus diagnostic integration:Over-the-air update mandates from European OEMs enable software-defined actuator feature monetization through subscription calibration services.
Industry Challenges
- Embedded firmware talent scarcity:Shortage of engineers proficient in motor control algorithms and automotive functional safety standards delays product development timelines.
- ISO 26262 certification complexity:Functional safety documentation requirements for safety-critical cabin comfort systems extend validation cycles by 12-18 months.
- Legacy analog system integration:Hybrid vehicle platforms requiring backward compatibility with established HVAC control architectures constrain digital architecture migration speed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HVAC Airflow and Blend Door Actuator Systems Market |
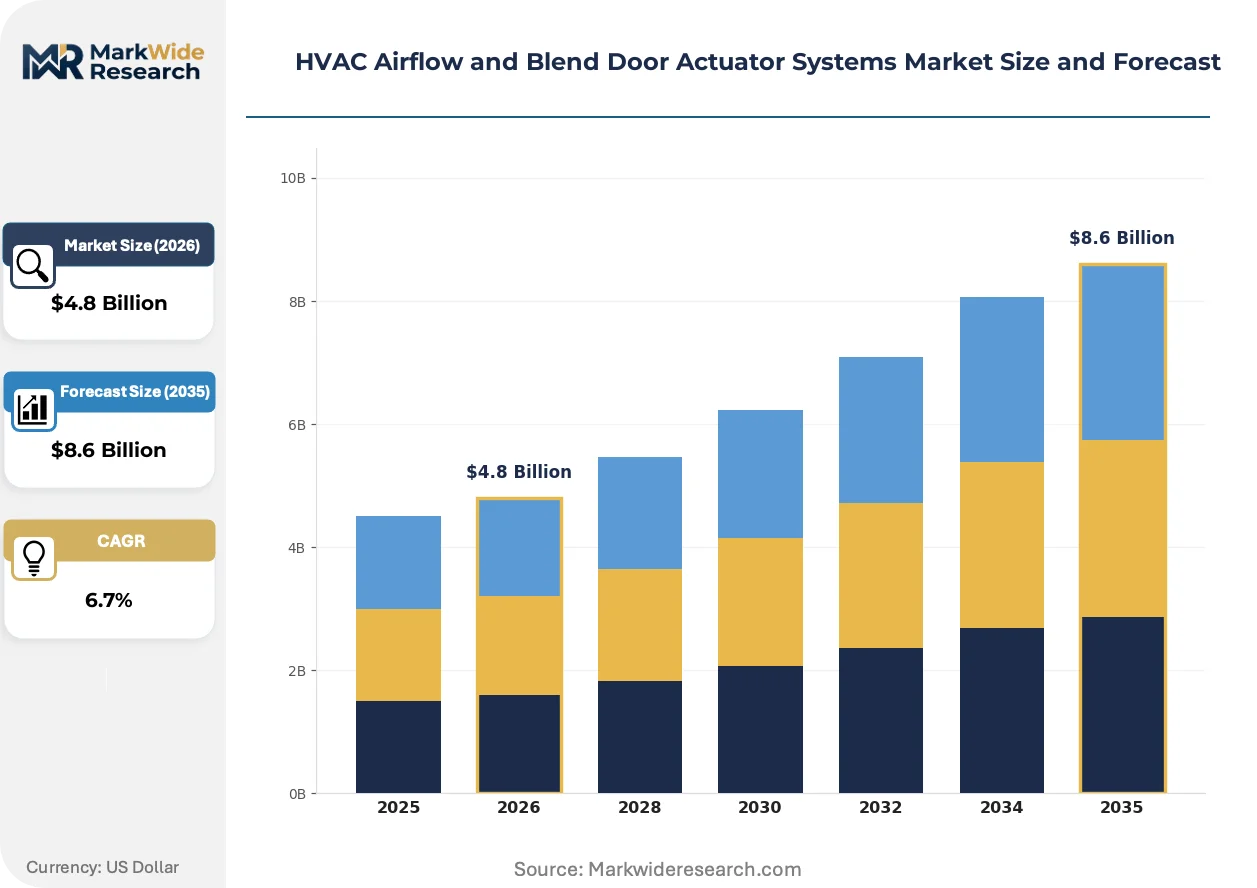
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stepper Motor Actuators, Servo Motor Actuators, Linear Actuators, Rotary Actuators, Brushless DC Motor Actuators Technology: Analog Control, Digital Control, PWM Control, Microcontroller-Based Control, Feedback Sensor Integration Application: Passenger Vehicles, Commercial Trucks, Agricultural Equipment, Construction Machinery, Heavy-Duty Vehicles End User Type: OEMs, Aftermarket Suppliers, Tier-1 Component Manufacturers, Refurbishment Services |
| Companies Covered | DENSO Corporation, Valeo, Hanon Systems, MAHLE, Brose Fahrzeugteile, Aisin Corporation, Nidec Corporation, Johnson Electric Holdings, BorgWarner, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HVAC Airflow and Blend Door Actuator Systems Market Trends and Innovations
Digital control architectures are overtaking established electromechanical paradigms, while regulatory chemistry transitions and buyer consolidation reshape specification roadmaps across passenger and commercial vehicle segments.
Brushless DC motor actuators with integrated Hall-effect position sensing are displacing brushed motor designs across premium and mass-market electric vehicle platforms. OEMs in Germany and South Korea now specify these variants as baseline for heat pump-equipped models. The shift is compressing supplier bases capable of delivering electromagnetic compatibility certification under 30 microvolts per meter.
The EU F-Gas Regulation's accelerated HFC phase-down is forcing actuator redesigns for CO2 and R-1234yf heat pump systems by 2027. European climate module suppliers must validate new sealing materials and expanded temperature operating ranges. Passenger vehicle OEMs with exposure to EU type-approval markets are pre-qualifying dual-refrigerant compatible actuators to hedge regulatory uncertainty.
Fleet operators and leasing companies now specify total cost-of-ownership clauses in climate system procurement contracts, displacing unit-price purchasing for commercial vehicle segments. Tier-one suppliers are responding with predictive maintenance telemetry bundled into actuator firmware. This behavioral shift is most visible in North American long-haul trucking, where downtime cost visibility has concentrated buyer power among top-20 fleet managers.
HVAC Airflow and Blend Door Actuator Systems Market Segmentation
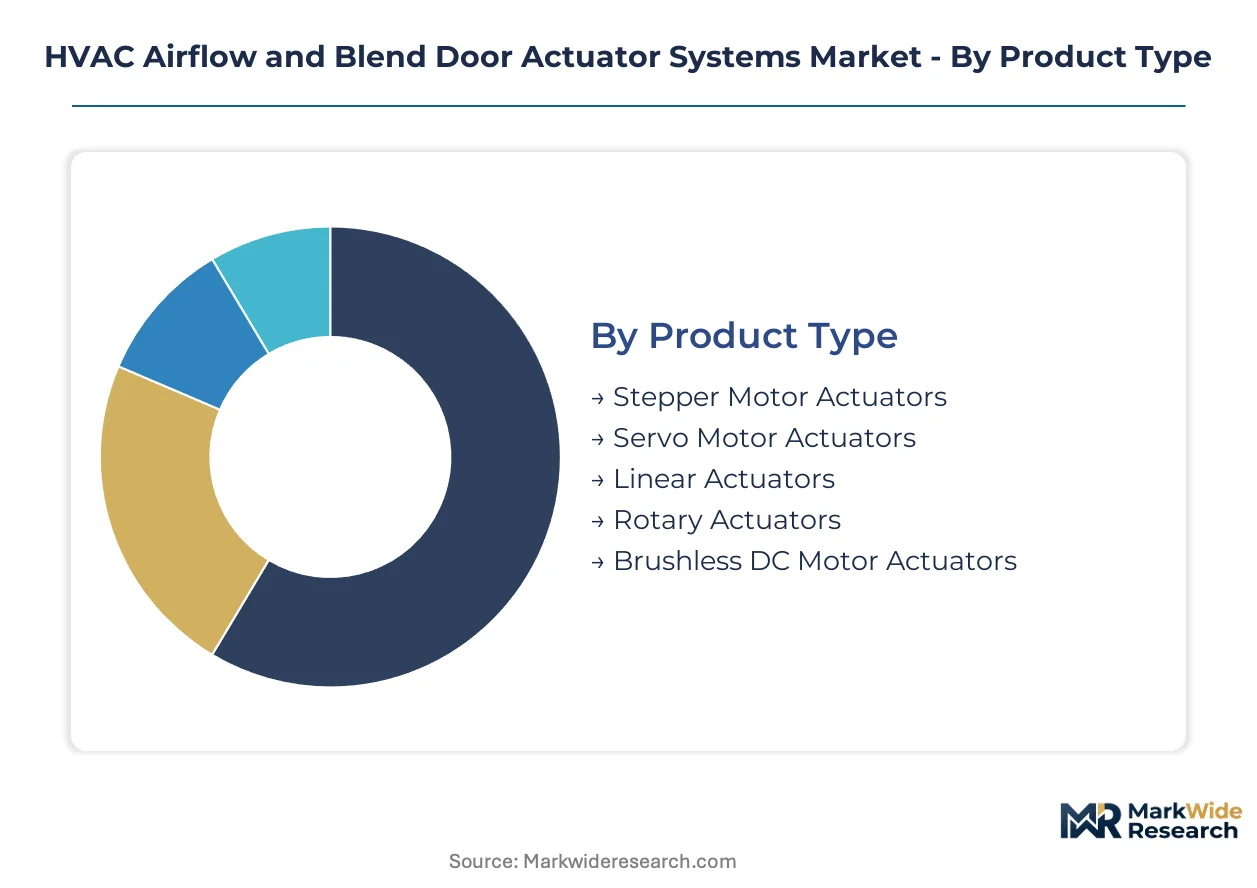
Actuator specification roadmaps diverge sharply across motor topologies and control architectures. Product type selection determines electromagnetic compatibility certification burden, while technology tier dictates firmware development amortization cycles. Application mix shapes durability testing protocols and aftermarket replacement revenue timing.
Product Type:
Brushless DC motor actuators exert substitution pressure on legacy brushed designs as electrified vehicle platforms mandate reduced electromagnetic interference and higher positional accuracy under strict thermal budgets.
- Brushless DC Motor Actuators:Permanent magnet synchronous motors with integrated Hall-effect position sensing deliver sub-degree duct airflow accuracy. Demand concentrates in Germany and South Korea where OEMs specify these as baseline for heat pump-equipped electric vehicle platforms. The EU F-Gas Regulation's refrigerant phase-down accelerates heat pump proliferation, amplifying specification pull for these variants.
- Stepper Motor Actuators:Electromechanical devices with discrete step positioning provide cost-optimized solutions for mass-market climate modules. China MIIT's GB standards for new energy vehicle energy consumption drive tier-one suppliers to upgrade stepper designs with finer resolution encoders to meet compliance thresholds without full brushless migration.
- Servo Motor Actuators:Closed-loop control systems with analog feedback dominate legacy vehicle platforms requiring backward compatibility. Agricultural equipment OEMs in the US Midwest specify these for field-proven reliability in dusty operating environments.
- Linear Actuators:Rack-and-pinion or screw-drive mechanisms convert rotational to translational motion for sliding blend door applications. Commercial truck HVAC modules in North America utilize these for high-torque air distribution requirements.
- Rotary Actuators:Compact angular motion devices serve flap-style blend door geometries in space-constrained dashboard architectures. Japanese passenger vehicle platforms favor these for packaging efficiency in right-hand-drive configurations.
Stepper motor actuators anchor the volume base while brushless DC motor actuators gain share at the steepest rate.
Technology:
Cost tier stratification separates legacy analog implementations from digital architectures requiring semiconductor foundry access and embedded firmware development capabilities.
- Digital Control:CAN bus-integrated architectures with over-the-air diagnostic capability displace analog systems across European OEM platforms. The EPA's fuel economy standards incentivize precision energy management algorithms that digital controllers enable. Firmware-defined feature monetization through subscription calibration services creates recurring revenue pools for tier-one suppliers.
- Feedback Sensor Integration:Positional sensing modules with redundant encoder channels support ISO 26262 functional safety certification for cabin comfort systems. German luxury OEMs mandate these for climate zones affecting driver alertness.
- PWM Control:Pulse-width modulation schemes offer intermediate cost positioning between analog and full digital architectures. Indian domestic automakers scaling climate module production under PLI scheme incentives specify these for localization cost targets.
- Microcontroller-Based Control:Dedicated motor control ICs with integrated gate drivers reduce external component count. Taiwan and South Korea foundry concentration creates supply vulnerability during capacity constraints.
- Analog Control:Discrete component implementations persist in commercial truck aftermarket where replacement cycle predictability outweighs feature advancement. Heavy-duty fleet operators in North America prioritize unit economics over diagnostic integration.
Analog control retains the installed base while digital control climbs the fastest as OEM over-the-air mandates harden.
Application:
Customer type fragmentation separates passenger vehicle volume procurement from commercial segment margin concentration through durability specification premiums and compressed replacement cycles.
- Passenger Vehicles:Multi-zone climate modules with eight or more actuators per vehicle generate the highest unit volumes. China's domestic automakers scaling electrified HVAC architectures concentrate demand growth for precision actuation systems compliant with MIIT energy consumption standards.
- Commercial Trucks:Severe-duty thermal cycling specifications and downtime cost visibility among top-20 North American fleet managers create concentrated margin pools. Predictive maintenance telemetry bundling into actuator firmware displaces unit-price purchasing in long-haul procurement contracts.
- Heavy-Duty Vehicles:Mining and logging equipment applications demand extended temperature operating ranges and sealed enclosures against particulate ingress. Australian and Canadian resource extraction operators specify these for remote service access constraints.
- Agricultural Equipment:Seasonal usage patterns with extended storage periods favor corrosion-resistant actuator variants. US Midwest OEMs prioritize field-proven designs over technology advancement.
- Construction Machinery:Vibration-hardened mounting configurations and rapid temperature swing tolerance characterize cabin HVAC requirements. European infrastructure investment cycles drive replacement demand for these specialized variants.
Passenger vehicles dominate unit volume while commercial trucks deliver the steepest margin expansion trajectory.
End User Type:
Supply concentration dynamics favor tier-one component manufacturers with captive electronics capabilities over pure-play actuator specialists facing semiconductor procurement constraints.
- OEMs:Vertical integration into climate module assembly by German and South Korean vehicle manufacturers constrains independent actuator supplier access. Direct specification authority enables feature bundling and software-defined calibration monetization.
- Tier-1 Component Manufacturers:Climate system specialists with semiconductor affiliate relationships control sensor-actuator integration costs. DENSO Corporation's captive electronics capabilities exemplify competitive positioning in this tier.
- Aftermarket Suppliers:Replacement cycle timing in North American commercial fleets creates revenue concentration for durability-validated actuator variants. Total cost-of-ownership procurement clauses favor suppliers with predictive maintenance telemetry integration.
- Refurbishment Services:Remanufacturing operations for legacy vehicle platforms extend actuator service life in price-sensitive segments. Agricultural and construction equipment operators in mature markets utilize these for extended asset utilization.
Tier-1 component manufacturers command specification influence while aftermarket suppliers capture replacement cycle timing advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany where precision certification commands 40-60% premiums over mass-market Chinese output, compressing margin pools for undifferentiated suppliers in cost-sensitive manufacturing clusters.
United States
EPA fuel economy standards and NHTSA safety mandates drive specification upgrades to brushless DC motor architectures with integrated position sensing. Long-haul fleet operators in the Midwest prioritize predictive maintenance telemetry to minimize downtime costs. Michigan and Ohio host climate module assembly operations serving Detroit-based OEM electrification programs.
Germany
EU F-Gas Regulation refrigerant phase-down forces actuator redesigns for CO2 heat pump systems by 2027. Stuttgart and Munich anchor premium climate-comfort R&D centers where OEMs mandate CAN bus integration and over-the-air diagnostic capability. Functional safety certification under ISO 26262 extends validation cycles for suppliers serving luxury vehicle platforms.
China
MIIT GB standards for new energy vehicle energy consumption create compliance-driven replacement demand for legacy actuator designs. Yangtze River Delta and Pearl River Delta clusters concentrate domestic automaker scaling of electrified HVAC architectures. Shanghai-based tier-one suppliers integrate captive semiconductor capabilities to control sensor-actuator integration costs.
South Korea
Heat pump-equipped electric vehicle platforms specify brushless DC motor actuators as baseline for electromagnetic compatibility certification under 30 microvolts per meter. Seoul Capital Area hosts dedicated climate module production serving Hyundai-Kia electrification roadmaps. Government battery-electric vehicle subsidies accelerate thermal management precision requirements.
India
PLI scheme incentives for automotive component manufacturing attract tier-one actuator suppliers establishing localized production. Tamil Nadu and Gujarat clusters scale climate control module assembly for domestic OEM export programs. BIS energy efficiency standards for passenger vehicles drive specification upgrades from analog to PWM control architectures.
HVAC Airflow and Blend Door Actuator Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where semiconductor-captive integrators command specification influence while pure-play motor specialists compete on unit economics. The vendor base separates into three strategic archetypes: diversified automotive electronics conglomerates with captive chip supply, climate-system specialists with OEM-embedded R&D relationships, and component-focused manufacturers serving aftermarket replacement cycles. Dominant competitive moves include backward integration into motor control IC sourcing and geographic expansion into India under PLI scheme incentives.
Among diversified automotive electronics conglomerates, DENSO Corporation occupies a position exemplifying semiconductor-captive competitive advantage through sensor-actuator integration cost control. Valeo and BorgWarner sit within the tier of powertrain-electronics extenders leveraging thermal management expertise into climate actuation. These three represent the archetype of technology-integrated suppliers capable of firmware-defined feature monetization through European OEM over-the-air mandate compliance.
| Leading Market Players |
|---|
| DENSO Corporation |
| Valeo |
| Hanon Systems |
| MAHLE |
| Brose Fahrzeugteile |
| Aisin Corporation |
| Nidec Corporation |
| Johnson Electric Holdings |
| BorgWarner |
| Others |
Pricing and Supply Chain Analysis
Brushless DC motor substitution for brushed designs is compressing supplier margins in China while elevating pricing power for semiconductor-captive integrators in Germany and South Korea. This motor topology shift simultaneously concentrates procurement authority among tier-one climate module manufacturers and fragments legacy actuator specialists dependent on commodity electronics sourcing.
Pricing Analysis
The customization-premium spread spans configured-to-order brushless DC actuators for heat pump architectures against standard stepper motor variants for mass-market climate modules. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 26262-functional-safety-validated designs commanding substantial premiums over analog control implementations. Pricing pressure stems from rare earth magnet cost volatility in neodymium-dependent brushless motor supply chains. Fleet operators in North American commercial trucking demonstrate lowest price sensitivity due to total cost-of-ownership procurement frameworks, while Indian domestic OEMs scaling under PLI scheme incentives exhibit highest sensitivity to unit economics.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan port corridors influence landed cost structures for motor control ICs and Hall-effect position sensors destined for climate module assembly. Taiwan, South Korea, and China concentrate semiconductor foundry capacity for automotive motor control ICs, while Germany and Japan anchor precision magnet and bearing component supply. The supply chain draws from rare earth processing concentrated in China and magnet fabrication distributed across Japan and Germany. Single-source vulnerability in Taiwan and South Korea foundry capacity creates structural risk during semiconductor allocation constraints. Distribution runs through tier-one climate system manufacturers with direct OEM platform engineering relationships, constraining independent actuator supplier channel access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The HVAC airflow and blend door actuator market is approaching a platform-economics inflection as CAN bus diagnostic integration and over-the-air calibration capability transform hardware margins into recurring software revenue streams.
For Market Incumbents: Secure captive semiconductor supply relationships to control sensor-actuator integration costs against emerging fabless competitors dependent on foundry allocation. Defend specification influence by accelerating ISO 26262 certification completion ahead of European OEM functional safety mandates. Capacity addition in Tamil Nadu and Gujarat clusters under India's PLI scheme incentives would anchor cost position against Chinese domestic supplier scaling. For New Entrants and Emerging Players: Anchor in the North American commercial truck aftermarket where predictive maintenance telemetry bundling displaces unit-price purchasing and concentrates buyer power among fleet managers seeking downtime reduction. Target white-space in agricultural equipment corrosion-resistant variants for US Midwest OEMs prioritizing field-proven reliability over technology advancement. A go-to-market angle emphasizing legacy analog system backward compatibility would bypass German and South Korean OEM digital architecture mandates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed automotive component specialists lacking semiconductor affiliate relationships and facing margin compression from brushless DC motor transition costs. Long-term viability in this market hinges on firmware-defined feature monetization capability through European OEM over-the-air mandate compliance. The acquisition target archetype encompasses tier-two actuator manufacturers with validated durability testing protocols but underdeveloped digital control architectures. The signal to watch is European OEM pre-qualification timing for dual-refrigerant compatible actuators hedging EU F-Gas regulatory uncertainty.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Affiliate Acquisition | Captive motor control IC sourcing secures supply allocation priority during Taiwan foundry constraints. |
| India PLI Scheme Manufacturing Expansion | Tamil Nadu and Gujarat localization captures domestic OEM climate module procurement under scheme incentives. |
| ISO 26262 Functional Safety Certification | Validation completion opens specification access for German luxury OEM climate zones affecting driver alertness. |
| Predictive Maintenance Telemetry Integration | Firmware bundling enables recurring revenue from North American fleet operator total cost-of-ownership contracts. |
| Dual-Refrigerant Actuator Pre-Qualification | CO2 and R-1234yf compatibility hedges EU F-Gas Regulation phase-down timeline uncertainty for European OEMs. |
Research Methodology
Desk research of automotive regulatory filings, vehicle production databases, and semiconductor trade data preceded structured interviews with OEM platform engineers, tier-one climate system procurement managers, aftermarket distributor operations heads, and motor control IC supplier technical leads. Primary fieldwork with actuator manufacturing specialists and thermal management R&D directors was validated against IHS Markit vehicle registration data, EPA fuel economy compliance records, and MIIT GB standard documentation. Bottom-up unit shipment estimates by vehicle platform were triangulated against top-down climate module production value analysis.
Variance decomposition across motor topology, control architecture, and application segments shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type differentiation between brushless DC and legacy motor designs, technology tier stratification from analog to digital control, vehicle class and propulsion architecture, and regional regulatory cluster alignment. CAGRs were derived from fitted growth curves calibrated to OEM electrification roadmaps and thermal management efficiency mandate implementation timelines. Heat pump architecture penetration rates and refrigerant chemistry transition schedules served as primary forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EPA fuel economy standard stringency and EU F-Gas Regulation phase-down adherence; material deviation would warrant model refresh. Forecasts reflect base-case assumptions regarding semiconductor foundry capacity normalization and rare earth magnet price stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Screw Compressor Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Swing Compressor Market
HVAC Equipment
India Residential Heat Pump Market
HVAC Equipment
North America, Europe, and Asia Pacific Air Compressor Market
HVAC Equipment
North America Bus HVAC Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Global Air Handling Units (AHU) Market
HVAC Equipment
Global Heat Exchangers Market
HVAC Equipment
Wall Fan Coil Market
HVAC Equipment
North America Air Conditioning Equipment Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
Global Split Systems Market
HVAC Equipment
South America Screw Compressor Market