
 China Elevator Ropes Market | 2026-2036
China Elevator Ropes Market Size, Share, and Industry Trends Forecast 2026-2036
China Elevator Ropes Market Outlook
A shift from single-source to multi-source procurement is repositioning supply relationships across the China elevator ropes sector. Jiangsu Safety Steel Wire Rope leverages its regional manufacturing base to capture recurring maintenance contracts. Guizhou Wire Rope Co., Ltd. anchors its position through deep specialization in high-strength steel formulations for heavy-load applications. Baosteel Group Corporation extends its influence through captive steel supply and backward integration into wire rod production.
China elevator ropes are high-tensile strength cables engineered from carbon steel wires with zinc or polymer coatings, typically rated for loads exceeding 1,000 kg and designed to withstand millions of bending cycles around sheave assemblies. Their primary purpose is to suspend and propel elevator cars within vertical transportation systems while maintaining dimensional stability under dynamic tension. Steel wire rope dominates installed base volumes across passenger elevator applications, while synthetic rope variants are gaining traction in modernization projects where reduced sheave wear and lower dead weight improve energy efficiency. Composite rope technology occupies a narrower but higher-margin niche in super-high-rise installations where payload optimization justifies premium pricing.
China's State Administration for Market Regulation enforces GB 8903 elevator rope standards that mandate minimum breaking strength and fatigue resistance benchmarks, while MIIT oversees industrial quality certification that shapes supplier qualification tiers for major property developers. The national dual carbon goals are pressuring building operators to prioritize rope technologies that reduce motor energy draw across the equipment lifecycle. Stakeholders must weigh material substitution timelines against the installed base's decades-long replacement cycles and evolving green building certification thresholds.
Market Dynamics
China's dual carbon goals are forcing building operators to reconsider rope lifecycle economics, compressing replacement cycles and elevating energy efficiency specifications in procurement decisions. MIIT certification tiers now filter supplier eligibility for major developments.
Growth Catalysts
- High-rise residential towers:Shanghai and Shenzhen developers are specifying premium-grade ropes for new construction, creating sustained demand for fatigue-resistant formulations.
- GB 8903 tightening:SAMR enforcement of elevated breaking strength benchmarks is disqualifying uncertified suppliers and consolidating procurement toward qualified manufacturers.
- Modernization cycles:Synthetic rope variants are penetrating retrofit projects in the Yangtze River Delta, where reduced sheave wear cuts maintenance costs.
Market Restraints
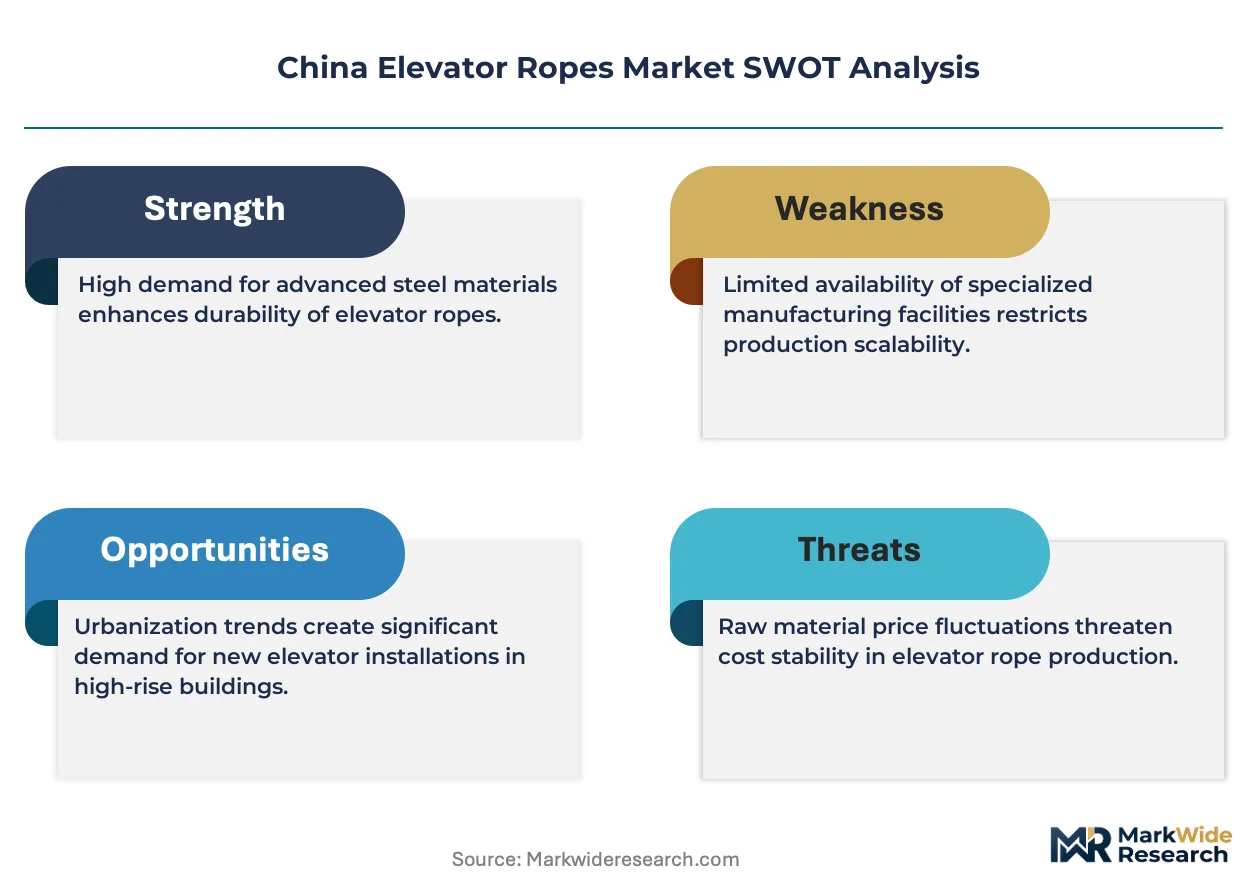
- Steel wire rod volatility:Carbon steel input costs fluctuate with Baosteel's captive pricing power, squeezing margin for non-integrated rope producers.
- Jiangsu manufacturing concentration:Over half of qualified capacity clusters in one province, exposing supply chains to regional logistics disruptions.
- Decades-long replacement cycles:The installed base's extended service life delays technology refresh rates and compresses near-term volume expansion.
Strategic Opportunities
- Super-high-rise niche:Composite rope technology commands premium positioning in structures exceeding 300 meters, where payload optimization justifies material substitution.
- Green building certification:MEE alignment with dual carbon targets creates procurement preference for low-friction rope systems that reduce motor energy draw.
- Multi-source contracting:Property developers are unbundling single-source agreements, opening secondary supplier qualification pathways for regional specialists.
Industry Challenges
- Fatigue testing capacity:SAMR's expanded certification requirements strain third-party laboratory throughput, extending product approval timelines.
- Legacy sheave compatibility:Synthetic rope adoption requires sheave groove redesigns that complicate retrofit engineering and raise installation costs.
- Skilled installation labor:Tensioning and termination protocols for high-strength formulations demand specialized technician training that outpaces workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Elevator Ropes Market |
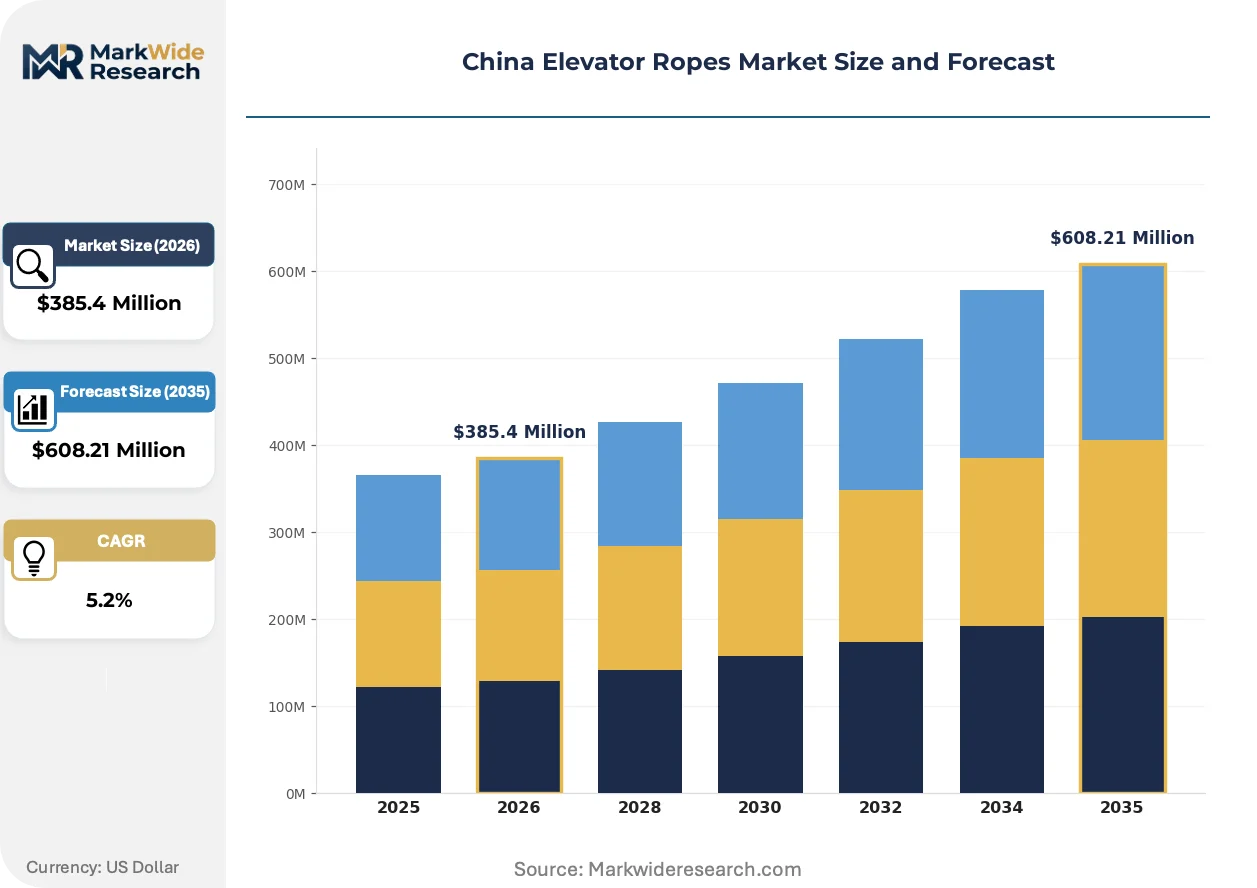
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Wire Rope, Synthetic Rope, Composite Rope, Fiberglass Rope Application: Passenger Elevators, Freight Elevators, Service Elevators, Dumbwaiters End User: Residential Buildings, Commercial Buildings, Industrial Facilities, Infrastructure Projects Installation Type: New Installations, Modernizations, Maintenance, Upgrades |
| Companies Covered | Jiangsu Safety Steel Wire Rope, Guizhou Wire Rope Co., Ltd., Baosteel Group Corporation, Jiangsu Fasten Elevator Rope & Sling Co., Ltd., Jiangsu Langshan Wire Rope Co., Ltd., Qingdao Amso International Co., Ltd., Tianjin Goldsun Wire Rope, Jiangsu Shenwang Group Wire Rope, Fasten Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Elevator Ropes Market Strategic Shifts
Material science advances and regulatory pressure are converging to redefine rope performance benchmarks and procurement criteria across China's vertical transportation sector.
Polymer-coated steel wire configurations are expanding into passenger elevator applications where corrosion resistance and reduced lubrication maintenance justify material cost premiums. Tier-one property developers in Guangzhou and Chengdu are piloting these formulations for mid-rise portfolios. The technology is expanding into segments previously reserved for bare steel wire, compressing the addressable market for conventional zinc-coated alternatives.
MIIT's industrial quality certification overhaul is mandating traceable wire rod sourcing and batch-level fatigue test documentation for supplier tier advancement. Manufacturers must now integrate metallurgical testing into production workflows to maintain eligibility for state-backed infrastructure bids. Heavy-load applications in commercial high-rises face the steepest compliance ramps, with several provincial developers already restricting procurement to tier-one certified suppliers.
After-sales service unbundling is separating rope supply from installation and maintenance contracts, enabling specialized contractors to compete for recurring revenue streams independently of original equipment manufacturers. This channel fragmentation is most pronounced in Shenzhen's competitive property management market, where facility operators negotiate direct maintenance agreements with Jiangsu-based rope specialists. The shift compresses OEM service margins while expanding addressable market access for component-focused suppliers.
China Elevator Ropes Market Segmentation
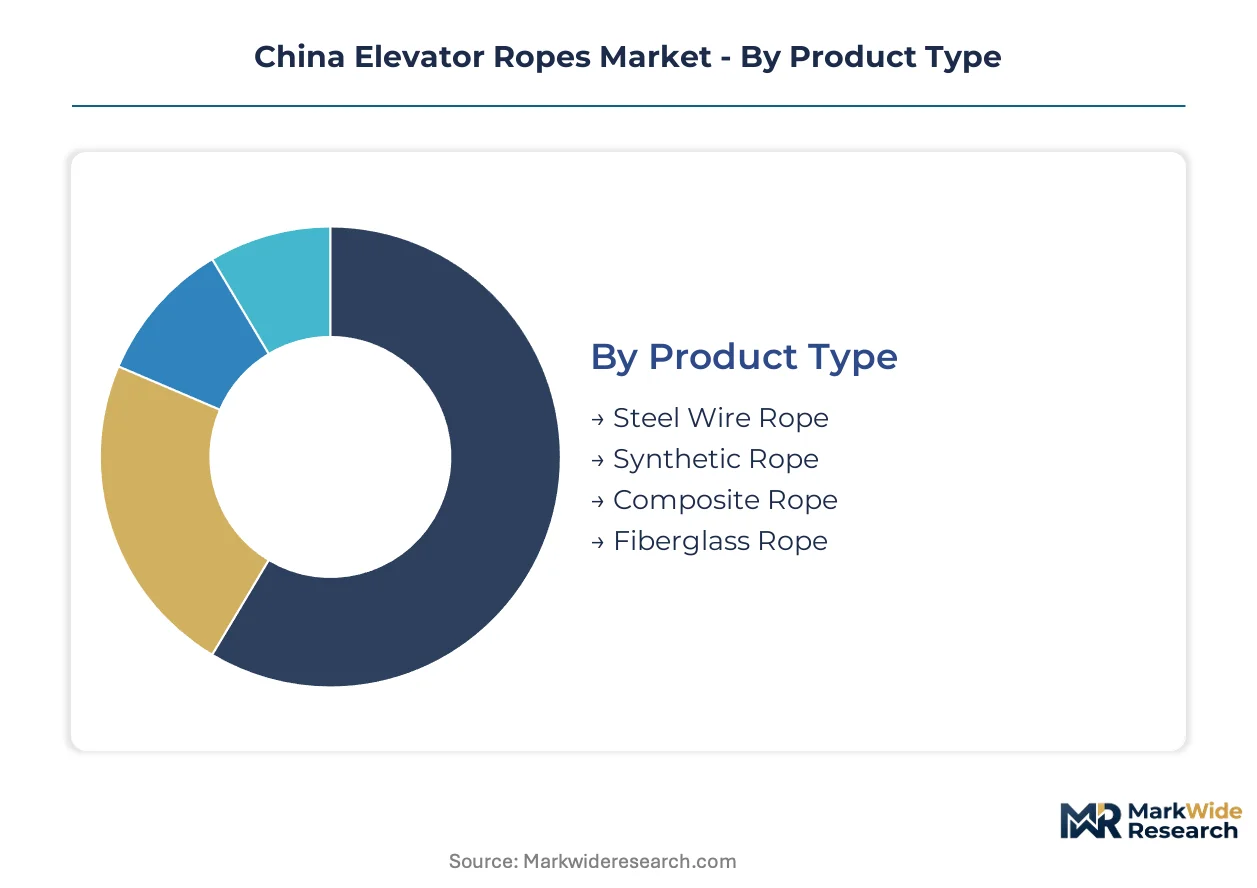
Product differentiation in China elevator ropes tracks closely to building height, load requirements, and energy efficiency mandates. Procurement patterns diverge sharply between new super-high-rise construction and the vast installed base requiring maintenance cycles. Understanding these segment boundaries clarifies where technology substitution pressures concentrate versus where legacy formulations retain lock-in.
Product Type:
The customization-to-standardization spectrum runs from application-engineered composite systems to commodity-grade steel wire configurations mass-produced for replacement markets.
- Steel Wire Rope:Carbon steel wires with zinc or polymer coatings rated for loads exceeding 1,000 kg and millions of bending cycles. Demand concentrates in Yangtze River Delta residential towers where GB 8903 compliance mandates proven fatigue resistance.
- Synthetic Rope:High-performance polymer fibers engineered for reduced dead weight and diminished sheave wear. Procurement is accelerating in Shenzhen and Guangzhou modernization projects where energy efficiency specifications tighten under dual carbon targets.
- Composite Rope:Hybrid constructions commanding premium positioning in structures exceeding 300 meters.
- Fiberglass Rope:Specialized electrical insulation applications in high-voltage elevator machine rooms.
Most installed capacity flows through Steel Wire Rope. Expansion is steepest in Synthetic Rope.
Application:
Volume concentration sits with high-frequency passenger transport, while margin differentiation emerges in specialized load-bearing configurations.
- Passenger Elevators:High-rise residential and commercial towers in Shanghai and Shenzhen drive procurement of fatigue-resistant formulations. GB standards enforcement is disqualifying uncertified suppliers from state-backed infrastructure bids.
- Freight Elevators:Heavy-load commercial and industrial applications require specialized high-strength steel formulations. Jiangsu manufacturing clusters dominate qualified capacity for these specifications.
- Service Elevators:Mid-rise commercial buildings with moderate duty cycles.
- Dumbwaiters:Small-format residential and hospitality installations with limited load requirements.
Passenger Elevators absorb the dominant share of qualified production. Freight Elevators generate the highest per-unit margins.
End User:
Customer sophistication varies from price-sensitive residential developers to infrastructure operators bound by certification tiers.
- Residential Buildings:High-rise towers in Shanghai and Shenzhen specify premium-grade ropes for new construction. Multi-source procurement is unbundling single-source agreements as property developers seek cost optimization.
- Commercial Buildings:Super-high-rise installations justify composite rope premiums where payload optimization delivers lifecycle savings. MEE alignment with dual carbon targets shapes procurement preferences.
- Industrial Facilities:Heavy-load applications with extended duty cycles.
- Infrastructure Projects:State-backed developments with mandatory tier-one supplier qualification.
Residential Buildings account for the largest addressable volume. Commercial Buildings are climbing the fastest as green certification thresholds tighten.
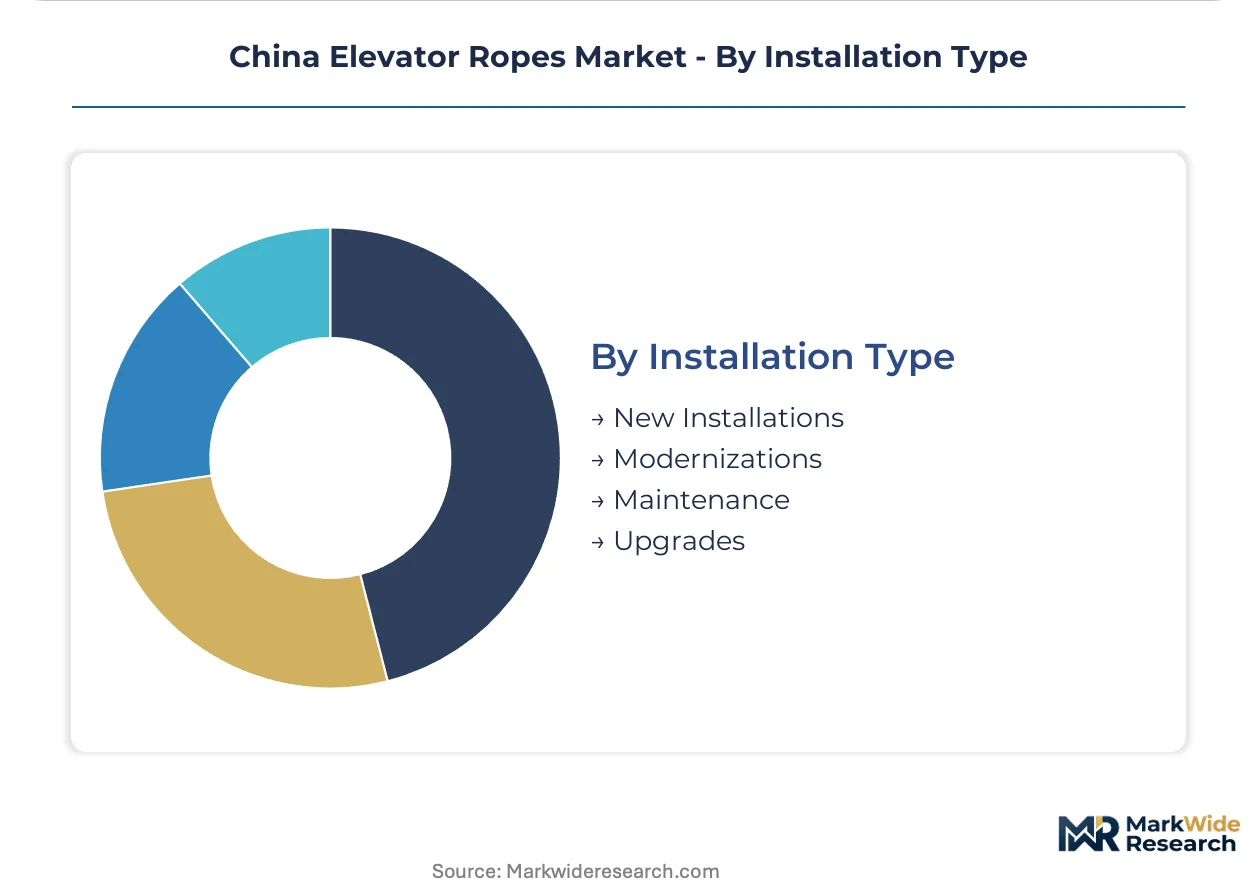
Installation Type:
Revenue stability concentrates in recurring maintenance streams, while technology substitution accelerates in modernization cycles.
- New Installations:Greenfield high-rise construction in Yangtze River Delta manufacturing corridor specifies certified formulations from qualified suppliers. SAMR enforcement of elevated breaking strength benchmarks is consolidating procurement.
- Modernizations:Synthetic rope variants penetrate retrofit projects where reduced sheave wear cuts maintenance costs. Legacy sheave compatibility challenges complicate engineering and raise installation expenses.
- Maintenance:After-sales service unbundling enables specialized contractors to compete for recurring revenue independently of OEMs.
- Upgrades:Technology refresh projects extending equipment lifecycle.
Maintenance commands the most predictable revenue streams. Modernizations are gaining share fastest as synthetic alternatives overcome retrofit engineering barriers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta manufacturing corridor concentrates qualified elevator rope capacity, with Shanghai and Jiangsu province anchoring procurement flows for high-rise residential towers. Provincial industrial policies and SAMR certification tiers reshape supplier eligibility across China's urban construction belts.
Yangtze River Delta
Shanghai and Suzhou developers specify premium-grade ropes for super-high-rise residential construction, driving fatigue-resistant formulation demand. SAMR enforces GB 8903 breaking strength benchmarks that disqualify uncertified manufacturers from state-backed bids. Jiangsu province clusters over half of national qualified capacity, with Wuxi and Nantong production bases serving maintenance contracts across the corridor.
Pearl River Delta
Shenzhen and Guangzhou modernization projects accelerate synthetic rope procurement where dual carbon targets elevate energy efficiency specifications. MEE alignment with national decarbonization goals shapes green building certification thresholds. Foshan and Dongguan facility operators negotiate direct maintenance agreements with Jiangsu-based specialists, fragmenting traditional OEM service channels.
Beijing-Tianjin-Hebei
State-backed infrastructure developments mandate tier-one MIIT certification for rope suppliers, filtering procurement toward qualified manufacturers. GB standards enforcement tightens material traceability requirements for heavy-load commercial applications. Tianjin port logistics and Baosteel's captive wire rod supply anchor backward-integrated production economics for regional distributors.
Sichuan-Chongqing
Western urban expansion generates replacement demand across mid-rise commercial portfolios with moderate duty cycles. Provincial developers prioritize cost optimization in multi-source contracting arrangements. Chengdu pilots polymer-coated configurations for corrosion resistance in high-humidity climate conditions, compressing addressable share for conventional zinc-coated alternatives.
Shandong Peninsula
Qingdao manufacturing bases serve export-oriented elevator OEMs with standardized steel wire configurations for international markets. Industrial quality certification overhauls mandate batch-level fatigue test documentation for supplier tier advancement. Jinan and Yantai clusters focus on commodity-grade replacement volumes rather than premium formulation development.
China Elevator Ropes Market Competitive Environment
Global majors compete with regional champions across certification tiers and procurement channels, producing a bifurcated structure where scale-driven steel conglomerates face specialized wire rope fabricators. The vendor base stratifies across three archetypes: backward-integrated steel producers with captive raw material supply, regional specialists with deep fatigue-testing capabilities, and synthetic material innovators targeting modernization niches. Capacity expansion and strategic partnerships dominate competitive moves as players secure SAMR qualification pathways.
Among Jiangsu-based fabricators, Jiangsu Safety Steel Wire Rope and Jiangsu Fasten Elevator Rope & Sling Co., Ltd. exemplify the regional specialist archetype, occupying positions anchored in manufacturing corridor proximity. Guizhou Wire Rope Co., Ltd. represents the high-strength formulation specialist tier, while Baosteel Group Corporation anchors the integrated steel producer segment with upstream control over wire rod supply.
| Leading Market Players |
|---|
| Jiangsu Safety Steel Wire Rope |
| Guizhou Wire Rope Co., Ltd. |
| Baosteel Group Corporation |
| Jiangsu Fasten Elevator Rope & Sling Co., Ltd. |
| Jiangsu Langshan Wire Rope Co., Ltd. |
| Qingdao Amso International Co., Ltd. |
| Tianjin Goldsun Wire Rope |
| Jiangsu Shenwang Group Wire Rope |
| Fasten Group |
| Others |
Value Chain & Pricing Dynamics
Family-owned Jiangsu fabricators anchor the mid-market tier through generational control of regional production assets, translating manufacturing corridor proximity into pricing discipline that resists margin erosion from integrated steel conglomerates. Their captive relationships with Yangtze River Delta property developers create contracting power that offsets Baosteel's captive wire rod pricing leverage.
Pricing Analysis
Carbon steel wire rod pass-through from Baosteel's captive supply governs baseline cost structures across non-integrated producers. Three-tier pricing structure across premium, standard, and economy levels separates MIIT tier-one certified formulations from commodity-grade replacement volumes. Pricing pressure stems from SAMR's expanded certification requirements extending product approval timelines and raising compliance overhead. Residential developers in Shenzhen exhibit highest price sensitivity, while super-high-rise commercial operators absorb premium composite rope margins.
Supply Chain Analysis
Refurbishment flows for legacy sheave assemblies create secondary material recovery channels that feed back into Jiangsu manufacturing clusters. Raw material sourcing draws from Baosteel's captive wire rod production, Guizhou high-strength steel formulations, and imported polymer fiber feedstocks for synthetic variants. Single-source vulnerability concentrates in Jiangsu province where over half of qualified capacity clusters within Wuxi and Nantong production bases. Distribution runs through direct procurement contracts with tier-one property developers and fragmented aftermarket service channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The China elevator ropes market reads as a late-cycle quality story where GB 8903 tightening and dual carbon mandates are compressing procurement toward certified premium formulations. Residential tower developers in Shanghai and Shenzhen are unbundling single-source agreements and elevating fatigue-resistance specifications.
For Market Incumbents: Anchor defensive positioning through MIIT tier-one certification investment and backward integration into wire rod supply. Synthetic rope substitution threatens steel wire volumes in modernization cycles; incumbents must secure captive polymer fiber sourcing or cede retrofit market share to specialized innovators. Channel control through direct maintenance contracting with facility operators preserves recurring revenue against OEM service margin compression. For New Entrants and Emerging Players: Composite rope technology for structures exceeding 300 meters offers the most penetrable white-space target, where payload optimization justifies premium positioning absent entrenched supplier relationships. Synthetic rope variants in Pearl River Delta modernization projects present secondary entry point through energy efficiency procurement preferences. Go-to-market execution should prioritize direct technical sales to facility operators unbundled from OEM maintenance agreements. For Investors and Strategic Acquirers: Valuations sit cheapest among Jiangsu-based regional specialists with deep fatigue-testing capabilities but limited brand recognition beyond manufacturing corridor proximity. Long-term viability hinges on certification tier advancement and synthetic material R&D investment rather than commodity-grade volume scale. Monitor SAMR enforcement intensity and tier-one supplier qualification velocity as inflection indicators for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| MIIT Tier-One Certification Investment | Unlocks state-backed infrastructure procurement and filters competitor eligibility. |
| Backward Integration into Wire Rod Supply | Mirrors Baosteel's captive production economics and insulates margin from steel volatility. |
| Synthetic Rope Manufacturing Scale-Up | Captures Pearl River Delta modernization demand under tightening dual carbon targets. |
| Direct Maintenance Contracting | Fragments traditional OEM service channels and secures recurring revenue streams. |
| Composite Rope R&D Partnership | Positions for super-high-rise niche premiums where payload optimization drives substitution. |
Study Parameters
Multiple input streams — technical director interviews at Jiangsu manufacturing clusters, procurement manager discussions with Shanghai property developers, and regulatory affairs dialogues with SAMR certification bodies — were reconciled against customs wire rod import records, MIIT industrial quality bulletins, and GB standards documentation. Secondary validation drew from elevator OEM technical specifications, provincial construction permit databases, and steel industry trade flow analysis. Bottom-up segment sizing and top-down macro constraint checks were triangulated to ensure coherence.
Historical shipment patterns from Jiangsu and Guizhou production bases were cross-referenced against panel input from facility operators across the analysis window. Segmentation modeling incorporated product type, application duty cycle, end-user sophistication tier, and installation type. CAGRs were derived from installed base replacement velocity, new high-rise construction permits, and technology substitution curves for synthetic and composite formulations. Energy efficiency mandate intensity and green building certification penetration served as scenario-weighting inputs.
The model holds under steady SAMR enforcement and dual carbon policy continuity; deviation in steel wire rod pricing volatility or synthetic fiber supply disruption would shift volume trajectories. Forecasts reflect assumptions about certification tier advancement rates and modernization cycle acceleration. Practitioners should monitor GB 8903 amendment timing and provincial developer procurement unbundling velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Utility Locator Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Excavator Augers Market
Construction Equipment
Global Cut and Bend Equipment Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
GCC Crane Market
Construction Equipment
Sawmill Machinery Market
Construction Equipment
Autonomous Construction Equipment Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market
Construction Equipment
North America Construction Equipment Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Roadheaders Market
Construction Equipment
Refurbished Construction Equipment Market