
 Customized Shopfitting Materials Market | 2026-2036
Customized Shopfitting Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Customized Shopfitting Materials Market Analysis
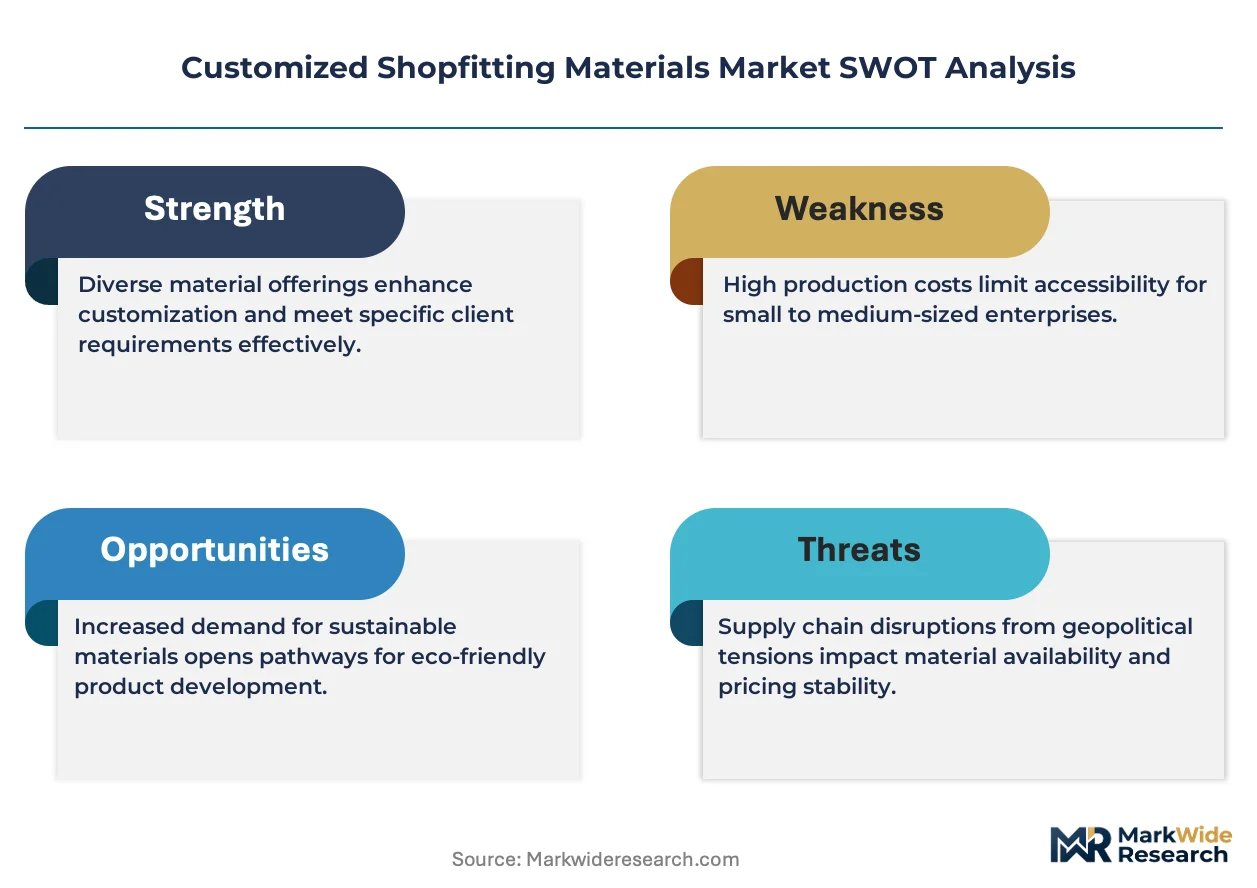
The gap between premium architectural-grade shopfitting and commodity fixture supply is broadening as luxury retailers specify bespoke metal-glass composites with millimeter tolerances while mass-market chains accept standard particleboard units. Leggett & Platt Incorporated leverages its North American manufacturing footprint to dominate coil-spring and display hardware categories. Madix Inc. sustains channel control through dedicated retail fixture distribution networks. REHAU AG + Co differentiates via polymer edgebanding and surface systems engineered for high-traffic commercial environments.
Customized shopfitting materials encompass engineered substrates, surface finishes, and structural hardware fabricated to precise dimensional and aesthetic specifications for commercial interior installations. Metal segments incorporating recycled aluminum and powder-coated steel command expanding specification sheets due to durability and circularity credentials. Wood remains the mature volume leader across mid-market retail applications, though glass and plastic composites represent the fastest-growing material category in flagship and exhibition contexts. Professional and modular installation types are capturing disproportionate margin pools as design firms and franchise operators prioritize speed-to-open and reconfigurable floor plans.
F-Gas Regulation and REACH compliance in Europe constrain adhesive and coating chemistries, redirecting procurement toward certified low-VOC suppliers. The EU AI Act introduces emerging requirements for smart fixture integrations with sensor-enabled inventory displays. India's BIS certification and PLI scheme for manufacturing are reshaping import substitution patterns for metal and polymer components. Stakeholders must monitor regulatory divergence between EU sustainability mandates and Gulf state speed-to-build priorities when allocating R&D and certification budgets.
Market Dynamics
Luxury retail expansion across Gulf Cooperation Council states is compressing project timelines to 90-day fit-out cycles, forcing material suppliers to pre-certify substrates and finishes before bid submission rather than after contract award.
Growth Catalysts
- Saudi giga-project retail corridors:NEOM and Red Sea Project developments specify bespoke metal-glass composites for flagship tenant spaces, creating dedicated specification pipelines for certified fabricators.
- F-Gas Regulation phase-down:European coating manufacturers reformulate solvent chemistries toward water-based and UV-cured systems, opening specification windows for compliant substrate suppliers.
- Modular installation protocols:Design-build firms in India adopt ISO-standardized reconfigurable fixture systems to accelerate speed-to-open for premium mall developments in Mumbai and Bangalore.
Market Restraints
- Recycled aluminum supply concentration:Secondary smelter capacity clusters in Germany and the UAE, exposing fabricators to regional energy price volatility and export quota fluctuations.
- REACH authorization timelines:ECHA's candidate list expansion for isocyanate-based adhesives extends product recertification cycles to 18-24 months, freezing specification updates.
- Particleboard substitution pressure:Mass-market retailers in Southeast Asia accept standardized MDF units at 40% lower installed cost, compressing margins for custom substrate producers.
Strategic Opportunities
- India PLI scheme localization:Metal and polymer component manufacturers establish captive extrusion and powder-coating capacity to displace Chinese imports under BIS certification requirements.
- Sensor-integrated smart fixtures:Convergence of RFID inventory tracking with glass display cases creates specification demand for embedded wiring channel substrates in EU luxury retail.
- Direct-to-contractor digital platforms:UAE-based fit-out specialists bypass traditional distributor networks through BIM-integrated material procurement portals, reducing lead times.
Industry Challenges
- Millimeter-tolerance fabrication skills:Shortage of CNC metalworkers capable of architectural-grade precision for bespoke brass and bronze fixtures limits Gulf project delivery capacity.
- Dual certification burden:Suppliers serving both EU and Saudi markets must maintain parallel REACH and SASO conformity assessment streams, doubling compliance overhead.
- Legacy ERP integration:Established fixture manufacturers face friction connecting modular configurator software to existing inventory management systems, delaying quote-to-cash cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Customized Shopfitting Materials Market |
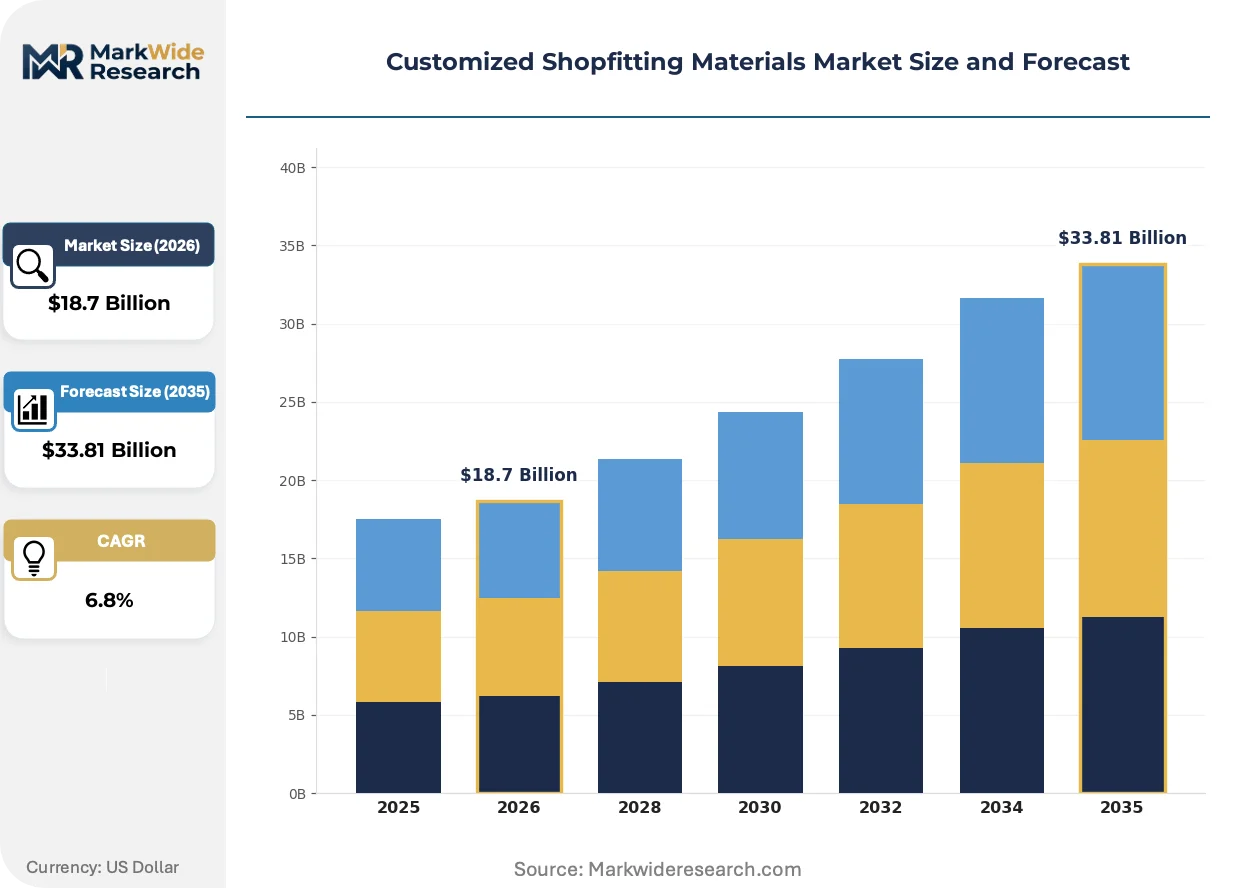
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Metal, Glass, Plastic Application: Retail Stores, Showrooms, Cafes, Exhibitions End User: Small Businesses, Corporations, Franchises, Design Firms Installation Type: DIY, Professional, Modular, Custom-Built |
| Companies Covered | Leggett & Platt Incorporated, Madix Inc., REHAU AG + Co, Jacobs Joinery and Shopfitters, Stylmark Inc., Wilsonart, HMY Group, Haworth Inc., Surteco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Customized Shopfitting Materials Market Emerging Trajectories
Digital fabrication workflows and circular material specifications are compressing traditional design-to-installation timelines while elevating performance requirements for substrate durability and end-of-life recoverability.
Photoluminescent powder coatings are expanding into emergency egress and wayfinding applications within high-traffic retail environments. Airport duty-free operators in Dubai and Singapore specify these finishes for 24-hour visibility without electrical backup. The technology is expanding into secondary safety-critical zones previously served by conventional illuminated signage, compressing specification cycles for integrated material-finish systems.
EU AI Act requirements for transparency in automated decision-making are reshaping smart fixture development. Sensor-enabled inventory displays must now document data processing logic to achieve CE marking, extending product development timelines for glass-integrated RFID systems. German and French luxury retailers are prioritizing compliant suppliers ahead of 2025 enforcement deadlines, creating first-mover certification advantages.
Franchise operators now bundle fixture procurement with ongoing refresh obligations rather than capitalizing single installations. Fast-fashion brands in India negotiate 36-month material service agreements covering reconfiguration and surface renewal. This model concentrates buying power with national account managers and displaces traditional project-based distributor relationships in Mumbai and Delhi NCR corridors.
Customized Shopfitting Materials Market Segmentation
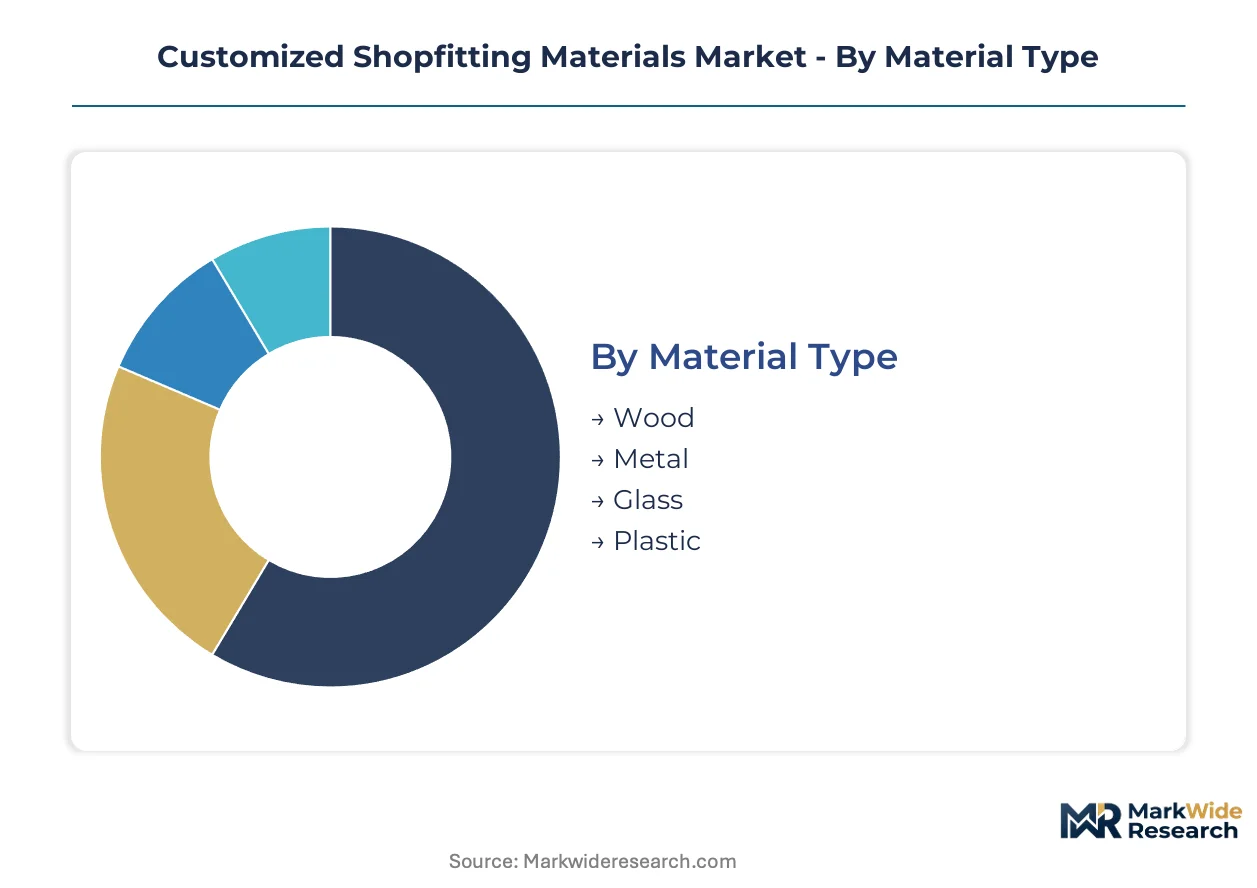
Shopfitting material selection cascades through specification chains where end-use durability, aesthetic tier, and installation speed create divergent procurement logics. Segmentation reveals how luxury flagship budgets, franchise standardization, and modular speed-to-open protocols fragment supplier addressable markets.
Material Type:
Cost tier separates commodity substrate buyers from specification-grade purchasers seeking circularity credentials and architectural tolerances.
- Metal:Recycled aluminum and powder-coated steel deliver millimeter-precision fabrication for bespoke brass and bronze fixtures. NEOM and Red Sea Project retail corridors in Saudi Arabia specify these substrates for flagship tenant spaces, though secondary smelter concentration in Germany and the UAE exposes fabricators to energy price volatility.
- Wood:Engineered timber and veneer-core panels dominate mid-market retail applications across volume-driven furniture chains. Mumbai and Bangalore mall developers specify wood for standardized fixture rollouts where installed cost compression outweighs bespoke tolerances.
- Glass:Tempered and laminated architectural glass enables transparent display cases with embedded RFID wiring channels for smart inventory systems. EU luxury retailers prioritize compliant suppliers ahead of enforcement deadlines for AI Act transparency requirements.
- Plastic:Polymer composites and edgebanding systems from REHAU AG + Co serve high-traffic commercial environments requiring impact resistance and surface renewal protocols.
Volume sits with Wood; growth tilts toward Glass.
Application:
Customer type determines whether fixtures prioritize experiential immersion or operational throughput.
- Retail Stores:Fast-fashion brands in India negotiate material service agreements covering 36-month reconfiguration and surface renewal cycles, concentrating buying power with national account managers.
- Showrooms:Automotive and luxury goods display environments demand photoluminescent powder coatings for 24-hour visibility without electrical backup, expanding into safety-critical zones at Dubai and Singapore airport duty-free operators.
- Cafes:Food-service fit-outs balance hygiene-certifiable surfaces with rapid installation protocols to minimize revenue downtime during refresh cycles.
- Exhibitions:Temporary installation contexts favor modular reconfigurable systems with ISO-standardized connection hardware for repeated assembly and disassembly.
Revenue concentrates in Retail Stores; margin expansion favors Showrooms.
End User:
Procurement scale and specification authority split between centralized franchise procurement and decentralized design-firm curation.
- Corporations:Enterprise retail chains leverage direct-to-contractor digital platforms in the UAE, bypassing traditional distributor networks through BIM-integrated material procurement portals that compress lead times.
- Franchises:Standardized brand manuals mandate pre-certified substrate and finish libraries, forcing material suppliers to pre-certify before bid submission rather than after contract award across Gulf Cooperation Council 90-day fit-out cycles.
- Design Firms:Architectural practices specify bespoke metal-glass composites with millimeter tolerances, though CNC metalworker shortages limit Gulf project delivery capacity.
- Small Businesses:Independent retailers accept standardized MDF units at lower installed cost, compressing margins for custom substrate producers.
Specification authority clusters with Design Firms; procurement volume aggregates under Franchises.
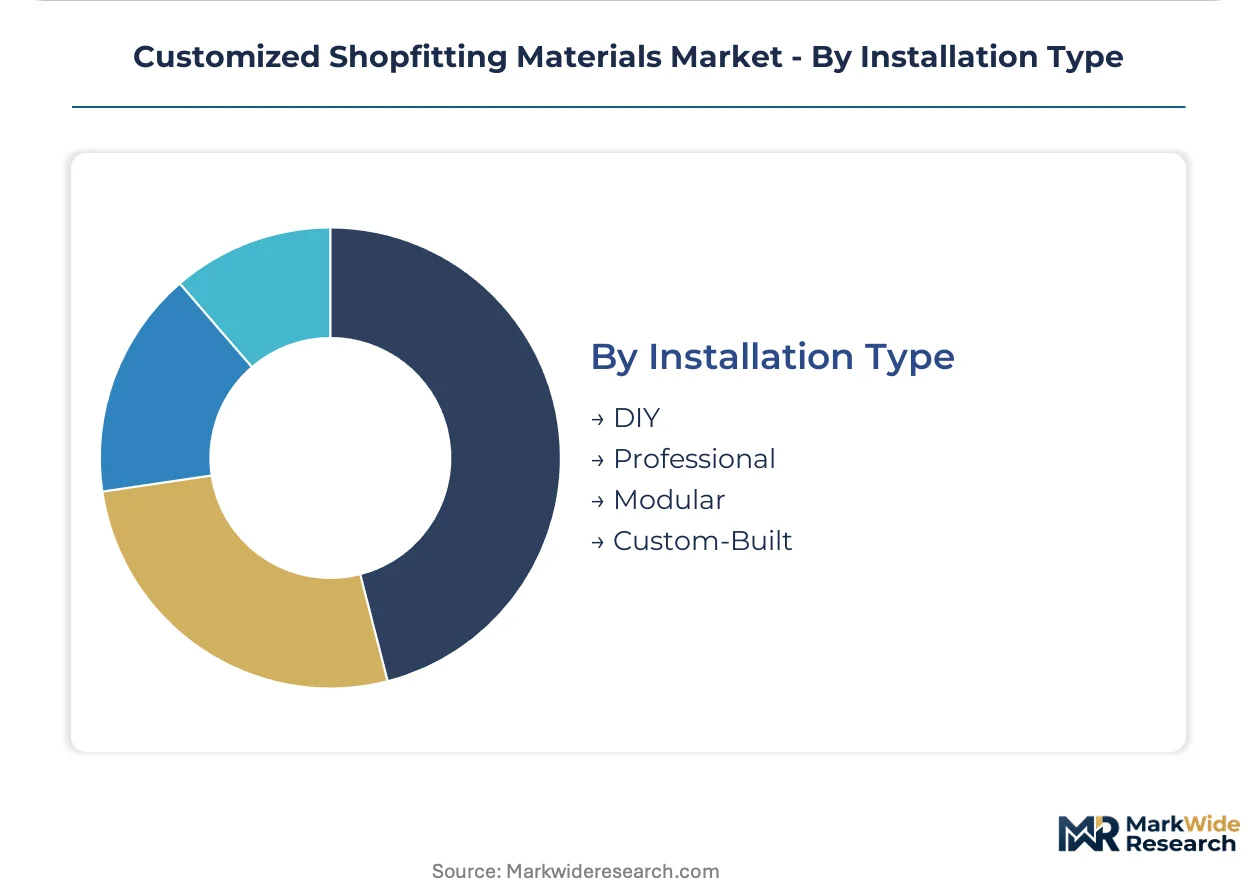
Installation Type:
Speed-to-open requirements and reconfiguration flexibility create divergent hardware and substrate specifications.
- Modular:ISO-standardized reconfigurable fixture systems capture disproportionate margin pools as design-build firms in India prioritize speed-to-open for premium mall developments. These systems require captive extrusion and powder-coating capacity to displace Chinese imports under BIS certification requirements.
- Professional:Turnkey installation contracts bundle labor with material procurement, extending quote-to-cash cycles for established fixture manufacturers facing legacy ERP integration friction with modular configurator software.
- Custom-Built:Bespoke fabrication for luxury flagship fit-outs demands parallel REACH and SASO conformity assessment streams, doubling compliance overhead for suppliers serving both EU and Saudi markets.
- DIY:Self-assembly flat-pack units serve cost-constrained independent retailers with particleboard substitution pressure from Southeast Asian mass-market chains.
Adoption velocity favors Modular; margin density concentrates in Custom-Built.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Design District and Riyadh's King Abdullah Financial District anchor the fastest-growing luxury retail fit-out corridors, where 90-day project cycles compress procurement timelines and elevate pre-certified substrate specifications.
United States
Flagship expansions by heritage department stores and direct-to-consumer brands drive specification-grade metal and glass demand. EPA VOC regulations under the Clean Air Act constrain coating chemistries, redirecting procurement toward low-emission powder-coating suppliers. Chicago's Merchandise Mart and Los Angeles Arts District concentrate design-firm specification authority for nationwide retail rollouts.
Germany
Automotive showroom refurbishments and airport retail concessions sustain demand for photoluminescent safety finishes and architectural-grade fixtures. ECHA REACH authorization timelines for isocyanate-based adhesives extend product recertification cycles, freezing specification updates. North Rhine-Westphalia's Ruhr industrial corridor hosts secondary aluminum smelters supplying recycled substrates to EU fabricators.
Saudi Arabia
NEOM and Red Sea Project retail corridors specify bespoke metal-glass composites for flagship tenant spaces, creating dedicated specification pipelines. SASO conformity assessment requirements mandate pre-certification before bid submission rather than after contract award. Riyadh's Diriyah Gate and Jeddah's Red Sea Mall cluster concentrate giga-project procurement volume.
India
Premium mall developments in Mumbai's Bandra Kurla Complex and Bangalore's Whitefield corridor adopt modular reconfigurable fixture systems for speed-to-open protocols. BIS certification and PLI scheme incentives reshape import substitution patterns for metal and polymer components. Maharashtra and Karnataka states concentrate captive extrusion and powder-coating capacity investments.
United Arab Emirates
Dubai International Airport duty-free expansions and Abu Dhabi Galleria mall developments specify 24-hour visibility finishes without electrical backup. MOHAP technical regulations govern commercial interior material safety standards. Dubai Design District and Al Quoz industrial zone cluster CNC fabrication capacity serving Gulf Cooperation Council fit-out projects.
Customized Shopfitting Materials Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent margin pools, with integrated fabricators controlling substrate supply and specification studios capturing architectural relationships. The vendor base separates into three tiers: multinational material systems houses with captive polymer and metal capacity, regional fixture fabricators serving national retail chains, and boutique metal-glass specialists delivering millimeter-tolerance bespoke work. Consolidation pressure concentrates among mid-scale European fabricators seeking Gulf project access, while technology licensing agreements spread modular configurator platforms across Indian design-build firms.
Within the multinational systems tier, Leggett & Platt Incorporated and REHAU AG + Co occupy positions defined by material science capabilities and surface engineering expertise. Among regional fixture specialists, Madix Inc. exemplifies channel control through dedicated retail distribution networks. These archetypes represent divergent competitive positions: substrate technology leadership versus procurement proximity and installation speed.
| Leading Market Players |
|---|
| Leggett & Platt Incorporated |
| Madix Inc. |
| REHAU AG + Co |
| Jacobs Joinery and Shopfitters |
| Stylmark Inc. |
| Wilsonart |
| HMY Group |
| Haworth Inc. |
| Surteco |
| Others |
Supply Flow & Price Mechanics
Captive extrusion and powder-coating capacity in India and the UAE anchors supply positions for fabricators serving Gulf Cooperation Council giga-projects, while simultaneously locking in pricing power through BIS certification barriers that exclude Chinese import competition. This backward integration into substrate production insulates certified suppliers from secondary aluminum smelter volatility in Germany, though it concentrates capital requirements among scale players.
Pricing Analysis
Speed-to-open guarantees for 90-day fit-out cycles anchor value-based pricing for modular installation contracts, with premium tiers commanding 40% spreads over commodity particleboard alternatives. Certification grade—REACH versus SASO conformity—drives price differentiation between EU and Gulf-bound specifications. Cost compression in mass-market MDF segments intensifies as Southeast Asian retailers accept standardized units, while luxury flagship budgets show minimal price sensitivity for millimeter-tolerance metal-glass composites.
Supply Chain Analysis
Direct-to-contractor digital platforms in the UAE bypass traditional distributor networks, compressing lead times for BIM-integrated procurement. Secondary aluminum supply clusters in Germany and the UAE, with polymer edgebanding feedstock drawing from REHAU AG + Co's captive European capacity. Single-source vulnerability concentrates around isocyanate-based adhesive suppliers facing ECHA REACH authorization delays, while tariff exposure on Chinese extrusions redirects Indian fabricators toward domestic PLI scheme incentives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in this market hinges on a vertical-integration race, with upstream control over recycled aluminum smelting and captive powder-coating capacity emerging as the decisive lever for margin defense.
For Market Incumbents: Anticipate specification freezes from ECHA REACH authorization timelines by pre-certifying alternative water-based adhesive formulations before candidate list expansions. Deepen backward integration into secondary aluminum supply through offtake agreements with Ruhr corridor smelters, insulating against energy price volatility that threatens German substrate competitiveness. For New Entrants and Emerging Players: India's PLI scheme for manufacturing opens a window for metal and polymer component localization, displacing Chinese imports under BIS certification requirements. Target modular reconfigurable fixture systems for Mumbai and Bangalore premium mall developments, leveraging ISO-standardized connection hardware to bypass entrenched distributor relationships through direct design-build firm engagement. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale European fabricators seeking Gulf project access through technology licensing or regional facility acquisition. Monitor CNC metalworker training pipeline expansion in Dubai Design District as an inflection indicator for bespoke fabrication capacity constraints easing across NEOM and Red Sea Project corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Powder-Coating Capacity Expansion | BIS certification compliance displaces Chinese import dependency for Indian fabricators. |
| Water-Based Adhesive Formulation Pivot | ECHA REACH authorization timelines force reformulation ahead of specification freezes. |
| BIM-Integrated Procurement Portal Development | UAE fit-out specialists compress lead times through direct-to-contractor digital platforms. |
| Secondary Aluminum Offtake Agreements | Ruhr corridor smelter contracts insulate against German energy price volatility exposure. |
| Smart Fixture Sensor Integration | EU AI Act transparency requirements extend development timelines for glass-embedded RFID systems. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated against primary interviews with fixture procurement managers at Gulf retail developers, CNC fabrication shop owners in Dubai Design District, and specification architects at Mumbai design-build firms. ECHA substance restriction databases, SASO conformity assessment protocols, and Indian BIS certification registries provided regulatory boundary conditions. Bottom-up project pipeline enumeration across NEOM, Red Sea Project, and Indian premium mall developments reconciled against top-down material consumption estimates from secondary aluminum smelter associations.
Data-stream reconciliation across the analysis window employed a segmentation framework spanning material type, installation protocol, and end-user procurement archetype. CAGRs derived from fitted growth curves applied to disclosed giga-project fit-out timelines and franchise rollout schedules. Industry-specific inputs included 90-day fit-out cycle compression rates and REACH authorization timeline probabilities from ECHA candidate list trajectories.
The model assumes a particular technology adoption path; alternative pathways for photoluminescent powder coating penetration into safety-critical retail zones would alter the outlook. Forecasts reflect base-case assumptions regarding Saudi giga-project execution pace and Indian PLI scheme uptake elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Exterior Wall Systems Market
Building & Construction Materials
GCC Faucet Market
Building & Construction Materials
North America Concrete Sealer Market
Building & Construction Materials
Precast Concrete Manufacturing Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Autoclaved Aerated Concrete (AAC) Blocks Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Cleanroom Flooring Market