
 Building and Construction Sheets Market | 2026-2036
Building and Construction Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Building and Construction Sheets Market Intelligence
Buyer concentration in the residential construction sector is restructuring as national homebuilders consolidate purchasing while regional contractors fragment specification authority. CertainTeed Corporation leverages captive gypsum reserves to sustain vertical integration across board and roofing sheet production. Owens Corning Corp. dominates fiberglass-reinforced sheet categories through manufacturing scale in North American insulation-grade materials. Etex anchors European fiber cement demand with specialized cladding systems engineered for fire resistance and moisture management.
Building and construction sheets comprise flat-panel materials manufactured to specified thicknesses—typically 6mm through 15mm—and installed via drywall, wet application, or pre-fabricated methods to form interior partitions, exterior envelopes, or structural substrates. Gypsum board, plywood, fiber cement board, and OSB each serve distinct load-bearing, fire-rating, or weatherproofing functions across residential, commercial, industrial, and institutional end uses. The residential segment leads volume consumption globally as housing starts and renovation cycles drive gypsum and OSB procurement, while the commercial segment generates higher margin pools through specification-grade fiber cement and custom thickness requirements. Pre-fabricated installation methods are expanding fastest where labor scarcity and schedule compression push builders toward panelized construction systems.
EPA guidelines govern VOC emissions and formaldehyde content in composite wood products, while the EU Green Deal and REACH framework restrict hazardous substances in construction materials and mandate embodied carbon disclosure. OSHA workplace exposure limits and the EU Construction Products Regulation shape installation method standards and product certification requirements for drywall and wet application systems. Stakeholders must monitor evolving building code harmonization between national fire-rating standards and emerging circular-economy material recovery mandates to anticipate specification shifts and compliance-driven product substitutions.
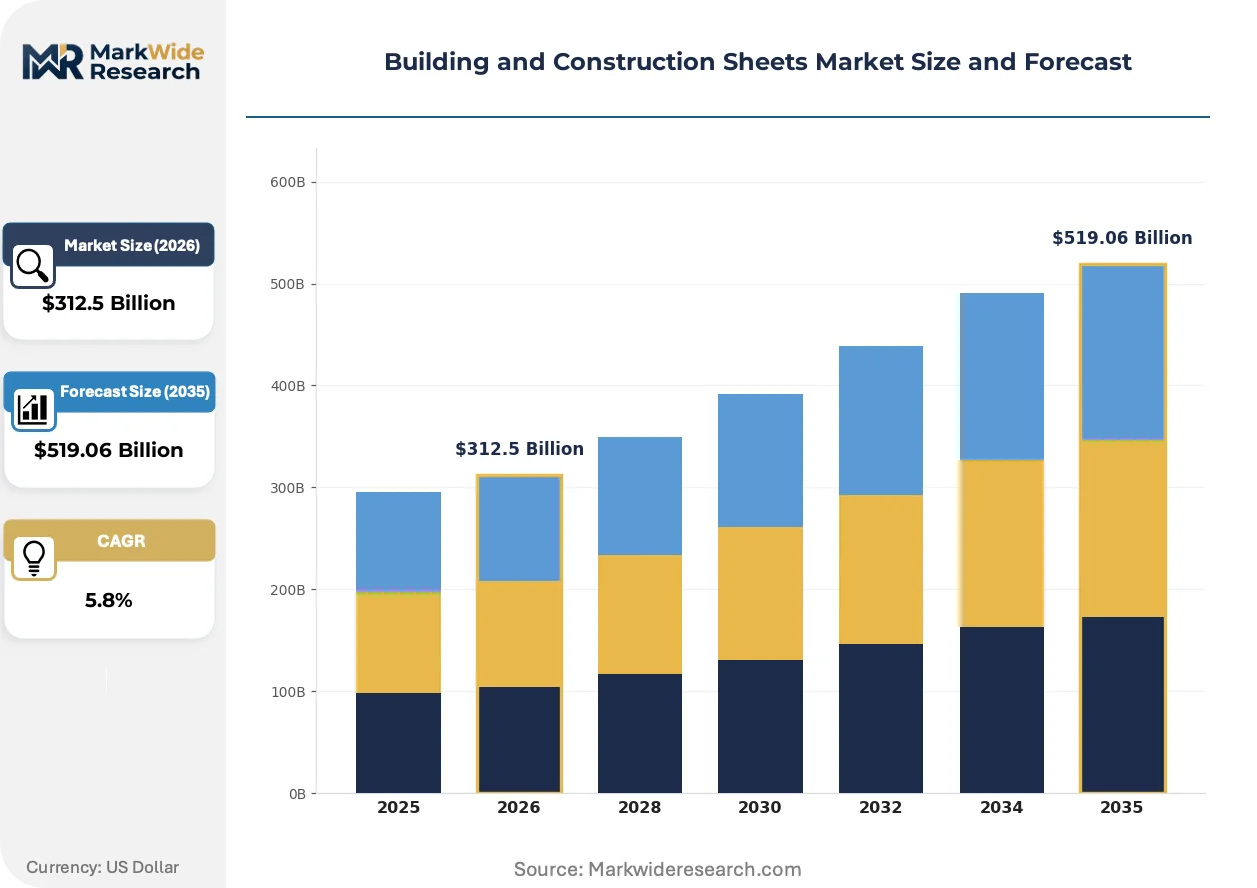
Market Dynamics
Residential retrofit cycles in North America and urban housing stock expansion across Asia are compressing specification timelines and forcing sheet manufacturers to integrate carbon disclosure into product certification workflows ahead of regulatory mandates.
Growth Catalysts
- EPA Emissions Guidelines:Tightening formaldehyde limits for composite wood products are accelerating substitution toward fiber cement and gypsum systems in US residential construction.
- EU Green Deal Embodied Carbon Mandates:Disclosure requirements for construction materials are pulling specification-grade fiber cement into commercial envelope retrofits across Germany and France.
- Urban Housing Density:Vertical residential construction in India and China is concentrating procurement volumes for fire-rated gypsum board and moisture-resistant cladding substrates.
Market Restraints
- Petrochemical Input Volatility:Resin and fiberglass feedstock price swings compress margin stability for OSB and fiberglass-reinforced sheet producers dependent on hydrocarbon derivatives.
- High-Purity Gypsum Concentration:Captive reserves held by integrated producers create supply bottlenecks for independent board manufacturers lacking backward integration into mining operations.
- Silica Dust Exposure Limits:OSHA permissible exposure thresholds for fiber cement cutting operations add compliance costs and slow adoption among small-scale regional contractors.
Strategic Opportunities
- Panelized Construction Methods:Pre-fabricated installation systems are expanding fastest in Australia and Canada where labor scarcity pushes builders toward off-site assembly of wall and roof panels.
- Circular Economy Material Recovery:EU Construction Products Regulation amendments mandating end-of-life recyclability create first-mover advantage for gypsum board producers developing closed-loop collection networks.
- Cross-Laminated Timber Hybrid Systems:Convergence of mass timber structural frames with gypsum fire-rated sheathing opens specification pathways in Nordic commercial mid-rise construction.
Industry Challenges
- Fire-Rating Certification Timelines:Extended testing protocols for multi-layer envelope assemblies delay product launches and tie up R&D capital for 18-24 month approval windows.
- Wet-Trade Skill Depreciation:Shrinking pools of qualified drywall installers in US Sun Belt markets force manufacturers to develop lighter panel formulations or mechanical fastening systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building and Construction Sheets Market |
| Market Size in 2026 | $312.5 Billion |
| Market Size in 2035 | $519.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gypsum Board, Plywood, Fiber Cement Board, OSB End User: Residential, Commercial, Industrial, Institutional Installation Method: Drywall, Wet Application, Formwork, Pre-fabricated Thickness: 6mm, 9mm, 12mm, 15mm |
| Companies Covered | CertainTeed Corporation, Etex, Paul Bauder GmbH & Co. KG, Fletcher Building Limited, North American Roofing Services Inc., GAF Materials Corporation, Owens Corning Corp., Icopal ApS, Atlas Roofing Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building and Construction Sheets Market Strategic Shifts & Innovations
Material science advances and installation method automation are compressing traditional trade boundaries between structural substrates and finished surfaces, rewiring how sheets are specified, procured, and deployed on job sites.
Cross-laminated timber (CLT) sheathing bonded with gypsum fire-resistant facings is expanding into mid-rise commercial construction in Sweden and Finland. Architects specify these hybrid panels to meet stringent fire codes while reducing structural dead load. The technology is expanding into specification territories previously dominated by cast-in-place concrete and steel frame systems.
REACH framework amendments restricting hazardous substance thresholds in construction materials are forcing reformulation of fiber cement binders and plywood adhesives across EU member states. Manufacturers must substitute phenol-formaldehyde resins with bio-based alternatives or face market exclusion. German and Dutch cladding specialists are most affected, accelerating partnerships with chemical suppliers to secure compliant resin streams before 2027 enforcement deadlines.
Builder procurement of sheet materials through integrated supply platforms is compressing traditional distributor markups in US residential construction. National homebuilders now contract directly with gypsum and OSB producers for volume commitments, bypassing regional lumber yards. This pattern is most visible in Texas and Florida markets where production home delivery schedules demand just-in-time panel drops coordinated with framing crews.
Building and Construction Sheets Market Segmentation
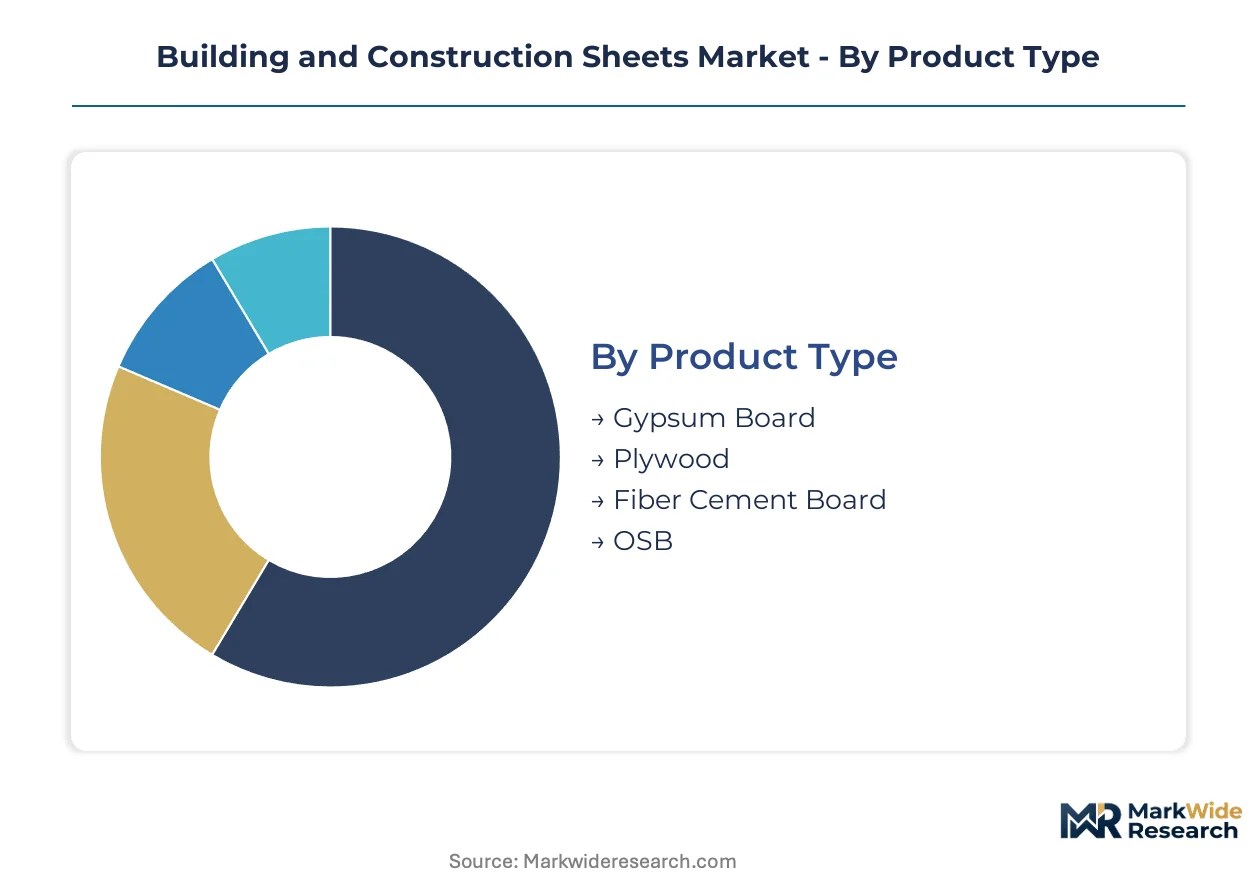
Segmentation in building and construction sheets reveals how material specifications fragment across structural demands, regulatory environments, and installation workflows. Understanding these divides exposes where procurement power concentrates and where specification authority shifts between architects, contractors, and building owners.
Product Type:
Integration depth varies sharply—gypsum and fiber cement operate as standalone finished surfaces, while plywood and OSB embed within multi-layer structural assemblies.
- Gypsum Board:Engineered from calcined gypsum sandwiched between paper facings, this panel dominates interior partition and ceiling systems. Residential retrofit cycles in the United States concentrate procurement for moisture-resistant and fire-rated variants as building codes tighten envelope performance standards. EPA formaldehyde regulations displace composite alternatives in multi-family housing.
- Fiber Cement Board:Portland cement, silica, and cellulose fiber composite delivers non-combustible cladding and backer board performance. Commercial envelope retrofits across Germany and France pull specification-grade volumes as EU Green Deal embodied carbon disclosure mandates favor inorganic substrates over petrochemical-derived alternatives. Silica dust exposure compliance adds installation cost friction.
- Plywood:Cross-laminated veneer construction provides structural sheathing and finished underlayment. Marine and exterior grades command premium positioning in Pacific Northwest residential markets.
- OSB:Oriented strand board compresses wood flakes with resin binders for load-bearing wall and roof sheathing. Volatile petrochemical input costs squeeze margin stability for independent producers lacking resin supply contracts.
Volume placements concentrate in gypsum board; the faster expansion belongs to fiber cement board.
End User:
Margin structures diverge—residential trades volume for scale economies while commercial and institutional segments reward specification-grade certification investments.
- Residential:Single-family and multi-family housing starts drive gypsum and OSB procurement through national homebuilder volume contracts. Texas and Florida markets exhibit just-in-time panel delivery coordination with framing crews, compressing traditional distributor roles.
- Commercial:Office, retail, and hospitality construction generates premium pricing for custom thickness fiber cement and fire-rated gypsum assemblies. Extended fire-rating certification timelines tie up manufacturer R&D capital for 18-24 month approval windows.
- Industrial:Manufacturing facilities and warehouses demand heavy-duty structural substrates with impact resistance. Specification authority fragments across engineering consultants and facility owners.
- Institutional:Schools, hospitals, and government buildings mandate stringent material certification and extended warranty terms. Procurement cycles stretch longer but lock in multi-year supply agreements.
Residential commands absolute volume dominance; institutional procurement is climbing the fastest as public infrastructure spending accelerates.
Installation Method:
Skill availability and labor cost trajectories determine method selection—wet trades depreciate in Sun Belt markets while pre-fabrication gains traction where schedule compression dominates.
- Drywall:Screw-attached gypsum panel systems remain the default for interior partition construction. Qualified installer shortages in US southern states force manufacturers toward lighter panel formulations.
- Wet Application:Plaster and stucco systems bond fiber cement or gypsum lath substrates for exterior envelope and decorative interior finishes. Traditional trade guilds control specification in Mediterranean European markets.
- Formwork:Plywood and engineered wood panels serve as temporary concrete casting molds in cast-in-place structural construction. Reuse cycles and surface quality grades differentiate pricing tiers.
- Pre-fabricated:Factory-assembled wall and roof panels integrate sheathing, insulation, and weather barriers for site-bolted installation. Australia and Canada exhibit steepest expansion trajectory where labor scarcity pushes builders toward off-site assembly.
Drywall retains volume supremacy; pre-fabricated methods are gaining share fastest as panelized construction penetrates mid-rise commercial segments.
Thickness:
Standardization at 12mm and 15mm supports inventory efficiency while thin gauges enable retrofit flexibility and thick panels address structural loads.
- 6mm:Curved surface applications and renovation overlays where weight and space constraints dominate. Limited structural contribution restricts use to non-load-bearing assemblies.
- 9mm:Standard ceiling and non-structural wall sheathing in residential construction. Balances material cost with adequate rigidity for finish coating.
- 12mm:Default specification for interior partitions and fire-rated assemblies in commercial and multi-family construction. Building code harmonization across US jurisdictions cemented this gauge as inventory baseline.
- 15mm:Structural subflooring, roof decking, and high-impact commercial wall systems. Premium positioning reflects enhanced load-bearing capacity and acoustic dampening performance.
Volume placements concentrate in 12mm gauges; the faster expansion belongs to 15mm specifications as structural panel demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the largest procurement volumes for gypsum board and fiber cement as urban housing stock expansion accelerates. India follows with vertical residential construction driving fire-rated sheathing demand. The United States, Germany, and Australia complete the top-tier demand centers where retrofit cycles and regulatory shifts reshape material specifications.
United States
Single-family housing starts in Texas and Florida compress delivery schedules for OSB and gypsum panels through just-in-time coordination with framing crews. EPA formaldehyde emission limits for composite wood products displace traditional plywood in multi-family envelope construction. The Sun Belt corridor from Atlanta to Phoenix faces acute drywall installer shortages that push manufacturers toward lighter panel formulations.
Germany
Commercial envelope retrofits in Berlin and Hamburg pull specification-grade fiber cement volumes as building owners pursue energy efficiency upgrades. EU Green Deal embodied carbon disclosure mandates favor inorganic substrates over petrochemical-derived alternatives in public procurement. The Rhine-Ruhr industrial cluster hosts specialized cladding fabricators engineering fire-resistant systems for mid-rise commercial mid-rise construction.
China
Urban housing density in Shanghai and Shenzhen concentrates procurement for moisture-resistant gypsum board and fiber cement cladding substrates. MIIT building material standards tighten fire-rating requirements for high-rise residential towers above 24 stories. The Yangtze River Delta manufacturing corridor supplies prefabricated wall panels integrating sheathing, insulation, and weather barriers for rapid site assembly.
India
Vertical residential construction in Mumbai and Delhi-NCR drives fire-rated gypsum board specifications as municipal codes align with international safety standards. BIS certification requirements for construction materials mandate third-party testing for load-bearing panel systems. The Gujarat industrial corridor hosts integrated producers with captive gypsum mining operations serving western and central housing markets.
Australia
Labor scarcity in Sydney and Melbourne pushes builders toward off-site panelized construction systems for mid-rise residential and commercial projects. The country's national building code harmonization efforts streamline fire-rating certification timelines across state jurisdictions. The Queensland construction corridor experiments with cross-laminated timber hybrid assemblies bonded with gypsum fire-resistant facings for structural dead load reduction.
Building and Construction Sheets Market Key Industry Players
North American producers anchor the scale-driven tier; European specialists hold the specification-grade premium segment. The vendor base stratifies across integrated mining-to-board operators, regional distributors with fabrication capabilities, and chemical suppliers providing compliant resin binders. Three archetypes dominate: captive reserve holders, fiberglass-reinforcement scale players, and fire-system engineering boutiques. Capacity expansion and backward integration into gypsum mining represent the prevailing competitive vectors as margin pressure intensifies on resin-dependent OSB producers.
Among North American integrated producers, CertainTeed Corporation and Owens Corning Corp. exemplify the scale archetype through captive mineral reserves and manufacturing breadth. Etex occupies a position within the European fire-system specialization tier, anchoring cladding demand through engineered envelope solutions. These three entities represent divergent strategic postures: mineral integration, fiberglass reinforcement scale, and specification-grade fire engineering.
| Leading Market Players |
|---|
| CertainTeed Corporation |
| Etex |
| Paul Bauder GmbH & Co. KG |
| Fletcher Building Limited |
| North American Roofing Services Inc. |
| GAF Materials Corporation |
| Owens Corning Corp. |
| Icopal ApS |
| Atlas Roofing Corporation |
| Others |
Cost & Logistics Intelligence
North American gypsum board price indices cascade through three distinct procurement tiers as captive reserve holders exploit upstream control over mining operations to dictate contract terms for national homebuilders. This mineral concentration compresses margin pools for independent producers lacking backward integration into extraction assets, forcing pricing stratification across specification-grade, standard inventory, and economy-grade gypsum systems.
Pricing Analysis
Volume placements in residential-grade gypsum board generate thin margins at scale while specification-grade fiber cement commands premium positioning in commercial retrofits. Price differentiation rests on certification grade and geographic delivery cost, with EU Green Deal compliance tiers adding margin layers for embodied carbon disclosure. Cost compression in OSB runs through petrochemical resin input volatility, squeezing independent producers most acutely. National homebuilders exhibit lowest price sensitivity through volume commitments, whereas small-scale regional contractors face acute budget constraints.
Supply Chain Analysis
Qualified drywall installer shortages in US Sun Belt manufacturing corridors constrain production throughput and inflate labor-loaded delivery costs for just-in-time panel systems. Supply concentrates in China, the United States, and Germany, with each hub feeding distinct specification standards. Raw material dependencies draw from high-purity gypsum deposits, phenol-formaldehyde resin streams, and cellulose fiber pulp. Single-source vulnerability around captive gypsum reserves creates supply bottlenecks when integrated producers prioritize internal board manufacturing. Distribution runs through national homebuilder direct contracts, bypassing traditional regional lumber yard intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA formaldehyde emission guidelines and EU Green Deal embodied carbon mandates erect compliance moats that favor incumbent producers with certification infrastructure and testing capital, raising barrier-to-entry thresholds for under-resourced challengers.
For Market Incumbents: Anticipate resin price volatility eroding OSB margin stability by securing long-term supply contracts or accelerating mineral-based product mix shifts toward gypsum and fiber cement systems. Defensive consolidation through captive gypsum reserve acquisition in India and China locks in procurement advantages as urban housing density intensifies regional demand concentration. For New Entrants and Emerging Players: Pre-fabricated panelized construction technology offers entry pathways into Australian and Canadian markets where labor scarcity pushes builders toward off-site assembly systems. Target mid-rise commercial segments in Nordic countries for cross-laminated timber hybrid specifications, partnering with mass timber fabricators to embed gypsum fire-rated facings into structural assemblies. For Investors and Strategic Acquirers: Distressed-cycle entries favor integrated producers with captive mineral reserves in the Yangtze River Delta and Gujarat industrial corridors as margin pressure squeezes resin-dependent independents. Long-term viability hinges on circular economy material recovery infrastructure, with closed-loop gypsum collection networks signaling durable competitive positioning. Watch for OSHA silica dust enforcement intensity as an inflection indicator for fiber cement adoption friction among small-scale contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Gypsum Reserve Acquisition | Backward integration into mining operations secures supply certainty for board manufacturing in China and India. |
| Pre-fabricated Panel System Partnership | Factory assembly integration captures labor-scarce markets in Australia and Canada through off-site construction. |
| EU Green Deal Certification Investment | Embodied carbon disclosure compliance opens specification-grade fiber cement procurement in Germany and France. |
| Closed-Loop Material Recovery Network | Circular economy infrastructure builds defensible positioning as EU Construction Products Regulation tightens recyclability mandates. |
| Lightweight Panel Formulation R&D | Mechanical fastening compatibility addresses qualified installer shortages across US Sun Belt residential markets. |
Research Approach
Trade association publications, customs and trade flow databases, and SEC filings from publicly traded building material producers formed the secondary backbone for market sizing and competitive positioning. Primary interviews with plant operations managers, procurement leads at national homebuilders, distribution channel partners, and technical R&D directors at fiber cement specialists combined with secondary validation through bottom-up and top-down triangulation.
Historical trendline analysis across installed base volumes and replacement cycle patterns anchored the projection framework. Segmentation modeling incorporated product type, end-use sector, installation method, and thickness gauge dimensions. CAGRs derived from regression analysis against housing starts, retrofit cycle intensity, and regulatory compliance phase-in schedules. Industry-specific forecast inputs included petrochemical resin price trajectories and municipal fire-code adoption timelines.
Several conditions sit outside the modeled scope, including abrupt tariff reconfigurations on cross-border gypsum trade and unanticipated OSHA silica exposure threshold revisions. Forecasts reflect documented assumptions about housing start continuity and regulatory enforcement pacing. Material deviation in resin input cost volatility or circular economy mandate acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Building Panels Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Pozzolana Cement Market
Building Materials
United States Architectural Coatings Market
Building Materials
Sanded Grout Market
Building Materials
Europe Concealed Cistern Market
Building Materials
US Cement Tiles Market
Building Materials
Glass Facade Market
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
North America Cement Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
HDG Steel Pipe Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Construction Coatings Market