
 North America Cement Market | 2026-2036
North America Cement Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cement Market Intelligence
Carbon capture integration at the kiln stage is narrowing the cost gap between ordinary Portland and blended cement variants across North American production sites. Heidelberg Materials leverages its European technology transfer to operate pilot capture installations at multiple U.S. plants. CEMEX sustains a dense terminal network along the Mississippi River system, anchoring barge-fed distribution into the Midwest. Martin Marietta controls integrated aggregate-cement positions in Texas and Colorado, extending its vertical reach into ready-mix concrete.
Cement is a hydraulic binder produced by calcining limestone, clay, and gypsum at approximately 1,450 degrees Celsius, then grinding the resulting clinker to a fineness of 3,000 to 5,000 square centimeters per gram to achieve specified compressive strength when mixed with water. Its primary commercial purpose is binding aggregates into concrete, mortar, and grout for load-bearing structures and surface applications. Portland cement occupies the dominant volume position across North American supply, though blended cement gains structural momentum as ASTM C595 specifications expand allowable supplementary cementitious material substitution rates. Infrastructure development commands the largest end-user value pool, while residential construction experiences cyclical contraction from elevated mortgage rates.
EPA enforcement of the National Emission Standards for Hazardous Air Pollutants shapes kiln upgrade timelines and fuel-switching investments across U.S. manufacturing assets. State-level Buy Clean policies in California, New York, and Colorado embed embodied carbon thresholds into public procurement, filtering market access for imported and domestic suppliers alike. Stakeholders must monitor how the Inflation Reduction Act's clean manufacturing tax credits interact with evolving ASTM standards to determine which product formulations qualify for federal-supported construction projects.
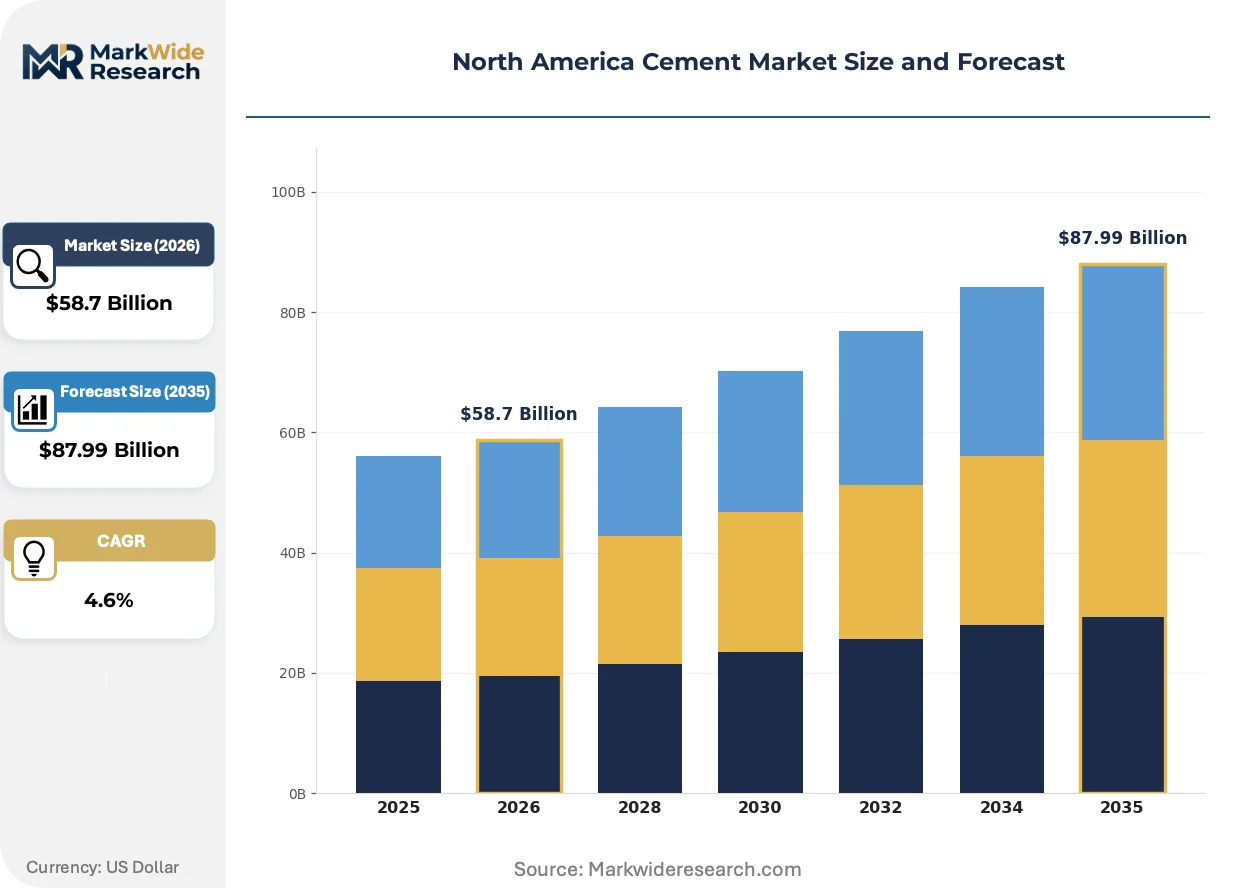
Market Dynamics
Federal infrastructure spending programs are redirecting cement procurement toward low-carbon formulations as state agencies embed embodied carbon thresholds into public works contracts. This policy-driven demand recalibration is compressing the traditional price premium for blended cements and forcing kiln operators to accelerate fuel-switching investments.
Growth Catalysts
- Inflation Reduction Act clean manufacturing tax credits:Federal incentives for carbon capture retrofits at U.S. production sites are narrowing the cost gap between ordinary Portland and blended cement variants.
- Texas Gulf Coast petrochemical expansion:LNG export terminal and downstream chemical facility construction is absorbing bulk cement volumes at scale unmatched elsewhere in the region.
- ASTM C595 specification expansion:Higher allowable substitution rates for supplementary cementitious materials are unlocking formulation flexibility for infrastructure contractors.
Market Restraints
- Petcoke price volatility:Cement kilns dependent on petroleum coke as primary fuel face margin compression when refining byproduct supply tightens.
- Clinker import concentration:U.S. coastal markets rely heavily on seaborne clinker from Turkey and Vietnam, exposing supply chains to freight rate spikes and currency fluctuation.
- Carbon capture capex burden:Retrofitting post-combustion capture systems requires capital outlays that strain mid-sized regional producers without parent-company balance sheet support.
Strategic Opportunities
- Colorado Buy Clean procurement rules:State-level embodied carbon thresholds for public construction are creating first-mover advantage for domestic low-carbon cement suppliers.
- Barge-fed terminal networks:Mississippi River distribution infrastructure offers untapped reach into Midwest markets currently served by higher-cost truck haulage.
- Carbon capture and sequestration hub integration:Proximity to developing CO2 pipeline networks in the Gulf Coast and Permian Basin is hybridizing production economics for participating plants.
Industry Challenges
- Kiln process engineering talent scarcity:The specialized knowledge required for alternative fuel co-firing and clinker chemistry optimization is concentrating at larger integrated producers.
- EPA NESHAP compliance timelines:Hazardous air pollutant standards are forcing capital allocation toward emission control upgrades rather than product innovation.
- Legacy ready-mix integration:Cement producers expanding downstream face operational friction unifying dispatch systems and quality control protocols across acquired concrete operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cement Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $87.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland Cement, Blended Cement, Hydrophobic Cement, White Cement End User: Residential Construction, Commercial Construction, Industrial Construction, Infrastructure Development Application: Concrete Production, Road Construction, Bridge Construction, Precast Components Distribution Channel: Direct Sales, Retail, Online Sales, Distributors |
| Companies Covered | Heidelberg Materials, Argos USA, Amrize, Eagle Materials, Ash Grove Cement, CEMEX, Buzzi Unicem, Martin Marietta, CRH America, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cement Market Strategic Shifts & Innovations
Calcination technology and fuel chemistry are converging to decarbonize clinker production without sacrificing compressive performance. Three developments are compressing the timeline for commercial-scale low-carbon cement deployment across the continent.
Portland-limestone cement (PLC) is hybridizing conventional binder chemistry with reduced clinker factor. State departments of transportation in California, Colorado, and New York are specifying PLC for highway pavement contracts. The formulation is compressing the cost premium for low-carbon alternatives to under five dollars per ton in competitive procurement markets.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is accelerating kiln fuel-switching from coal to natural gas and alternative fuels. The regulatory pressure is forcing capital deployment toward scrubber installations and precalciner upgrades. Texas and California manufacturing assets face the most compressed compliance timelines due to non-attainment zone designations.
Contractor procurement departments are consolidating cement buying through integrated supplier agreements that bundle ready-mix, aggregates, and cement volumes. The purchasing model shift is disintermediating traditional distributor relationships in metropolitan construction markets. Florida and Arizona urban corridors exhibit the most advanced consolidation of construction material procurement functions.
North America Cement Market Segmentation
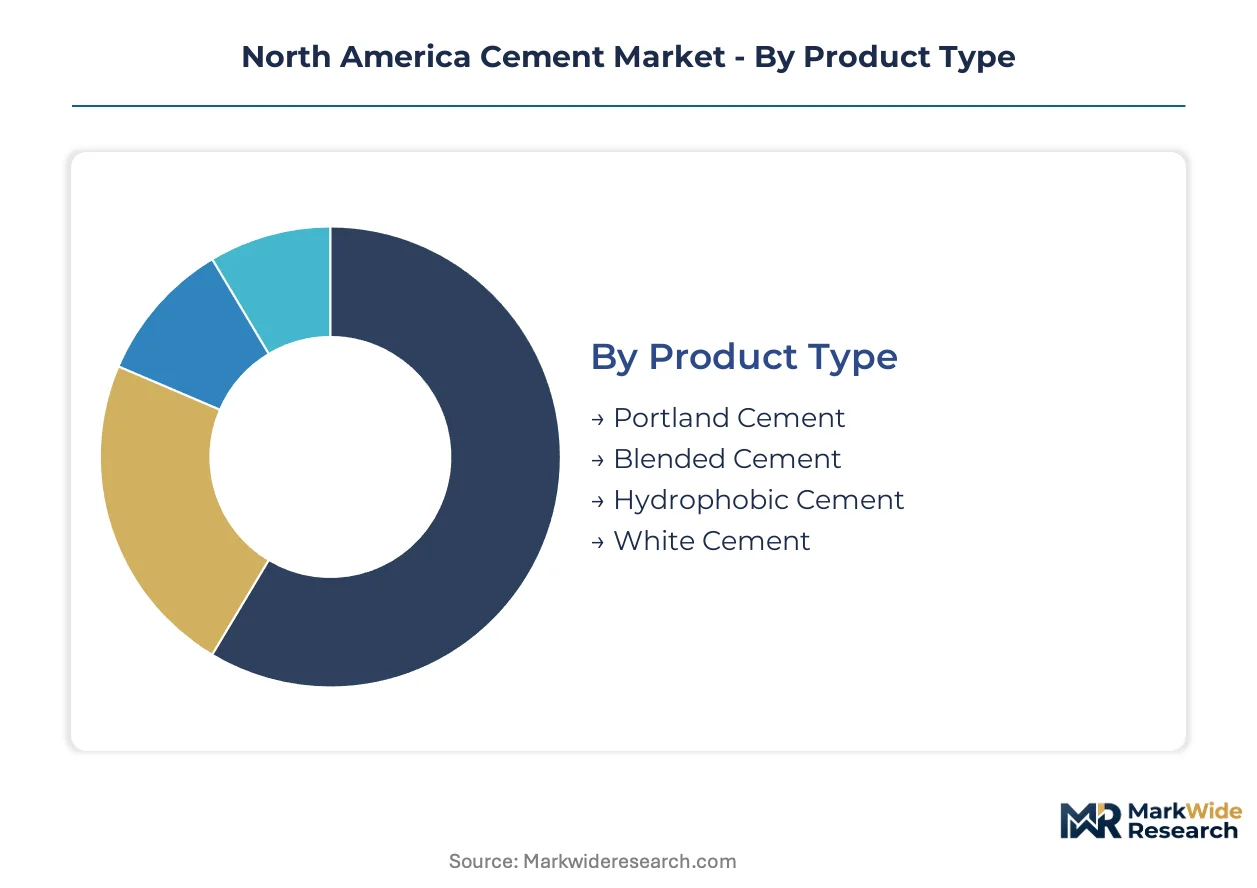
Cement segmentation across North America reflects divergent technical specifications and procurement economics. Product chemistry, end-use intensity, and channel configuration each create distinct competitive arenas with separate margin profiles and customer loyalty dynamics.
Product Type:
Cost tier differentiation separates commodity-grade binders from specialized formulations with premium pricing power.
- Portland Cement:Ordinary Portland cement contains 95% clinker with controlled gypsum addition for set-time regulation. Infrastructure contractors in Texas and California specify this grade for highway pavement where ASTM C150 strength benchmarks are mandatory. EPA emission standards are forcing kiln operators to absorb carbon capture costs that compress margins on this high-clinker product.
- Blended Cement:Portland-pozzolan and Portland-slag blends substitute 25-70% of clinker with supplementary cementitious materials. State DOT specifications in Colorado and New York are accelerating procurement of these formulations for public works. Buy Clean procurement thresholds embed embodied carbon limits that favor blended cement in competitive bidding.
- Hydrophobic Cement:Oleic acid or stearic acid additives create water-repellent properties for marine and subterranean applications. Gulf Coast offshore platform construction absorbs limited volumes of this specialty grade.
- White Cement:Low-iron clinker and pure gypsum yield decorative finishes with reflectivity specifications. Architectural precast producers in Florida and Arizona specify white cement for aesthetic concrete surfaces.
Portland cement holds installed capacity. Blended cement is rotating up the share rankings.
End User:
Application volume intensity varies dramatically across construction verticals, with infrastructure commanding the most predictable offtake cycles.
- Residential Construction:Single-family and multifamily housing foundations, slabs, and masonry walls absorb bagged and bulk cement through ready-mix intermediaries. Elevated mortgage rates in the United States are compressing new housing starts and redirecting contractor purchasing toward smaller batch volumes.
- Infrastructure Development:Federal highway, bridge, and transit programs specify high-volume bulk cement with strict performance testing protocols. The Inflation Reduction Act's clean manufacturing tax credits are filtering procurement toward low-carbon qualified suppliers in competitive bidding.
- Commercial Construction:Office towers, retail centers, and hospitality structures drive demand for high-early-strength formulations with accelerated curing schedules. Urban cores in Texas and Colorado exhibit the strongest commercial cement absorption.
- Industrial Construction:Manufacturing facilities, warehouses, and data centers require mass concrete placements with thermal control specifications. Petrochemical expansion along the Gulf Coast is anchoring industrial cement demand with multi-year offtake agreements.
Infrastructure development commands the most stable demand trajectory. Residential construction is climbing the fastest as rate environments shift.
Application:
Functional performance requirements dictate formulation selection and supplier qualification protocols.
- Concrete Production:Ready-mix and site-mixed concrete represents the dominant volume application, binding aggregates with cement paste to achieve specified compressive strength. ASTM C94 quality control protocols govern batch plant certification across the United States.
- Road Construction:Portland cement concrete pavement and cement-treated base layers require sulfate-resistant formulations for freeze-thaw durability. State DOT material engineers in California and Colorado specify PLC for highway rehabilitation contracts.
- Bridge Construction:Prestressed and precast bridge elements demand low-alkali cement with controlled heat of hydration. Federal Highway Administration inspection standards enforce material traceability for structural concrete.
- Precast Components:Factory-cast wall panels, beams, and utility structures require rapid-strength-gain cement for form turnover efficiency. Automated precast plants in Texas and Florida are consolidating supplier relationships to secure volume discounts.
Concrete production holds installed capacity. Precast components is rotating up the share rankings.
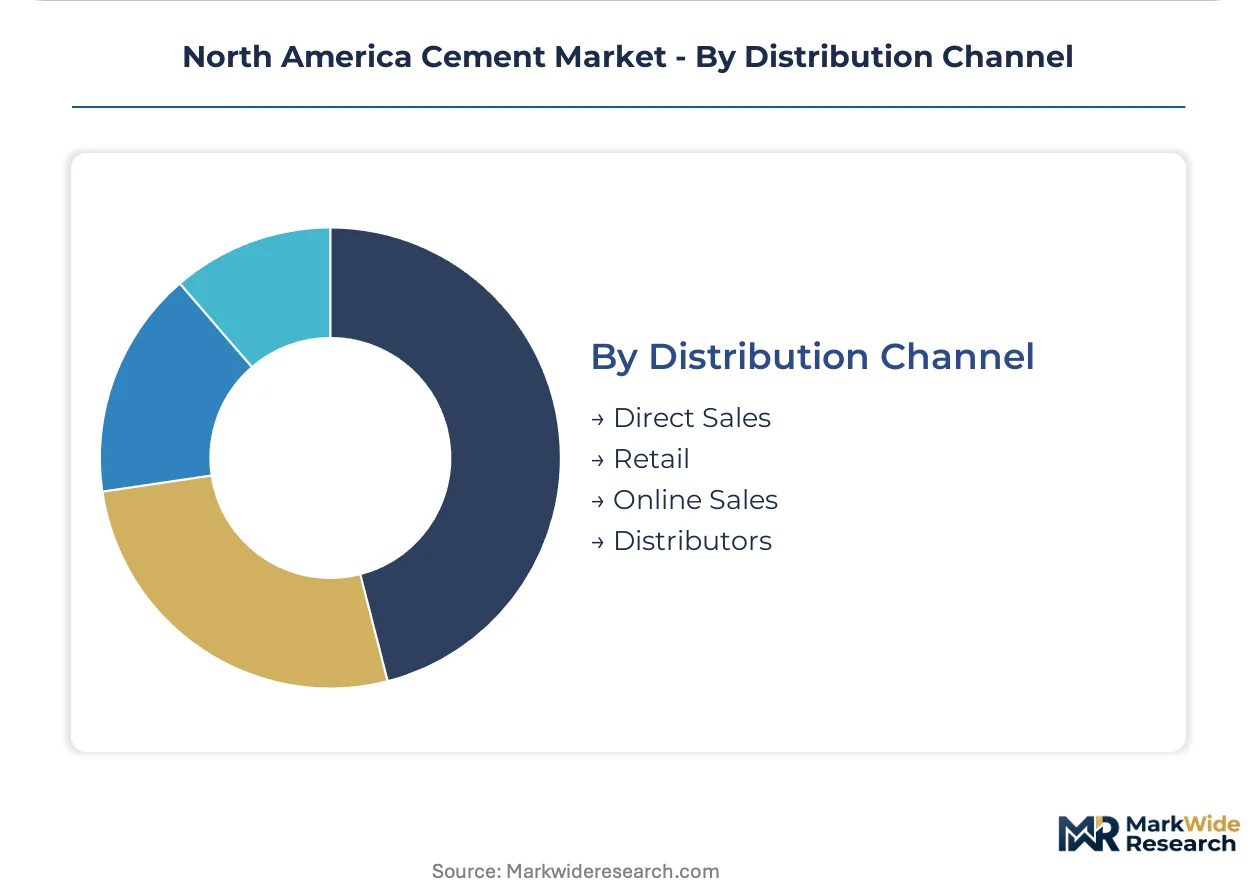
Distribution Channel:
Customer type and order scale determine channel economics, with bulk logistics favoring direct relationships.
- Direct Sales:Large-scale infrastructure contractors and ready-mix producers negotiate multi-year supply agreements with integrated cement manufacturers. Mississippi River barge terminals anchor direct distribution into Midwest markets.
- Distributors:Regional construction material wholesalers aggregate bagged cement with complementary products for smaller contractors. Inventory carrying costs and credit terms structure competitive positioning in this channel.
- Retail:Home improvement centers and lumber yards serve DIY and small-trade customers with 47-94 pound bagged product. Seasonal demand spikes around residential construction weather windows strain retail inventory planning.
- Online Sales:Digital procurement platforms are emerging for specification-grade cement with documented environmental product declarations. California and New York contractors pilot online sourcing for Buy Clean compliance documentation.
Direct sales holds installed capacity. Online sales is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican cement producers supply clinker and finished product to U.S. Gulf Coast terminals through dedicated maritime routes. Canadian limestone deposits feed grinding operations serving the Great Lakes construction corridor. Cross-border logistics integration shapes competitive positioning across the continent.
United States
The Inflation Reduction Act channels federal infrastructure spending into highway rehabilitation and bridge replacement programs. EPA NESHAP enforcement accelerates kiln fuel-switching investments at manufacturing assets in Texas and California. The Gulf Coast petrochemical corridor anchors multi-year cement offtake agreements for LNG export terminal construction.
Canada
Quebec and Ontario grinding plants process imported clinker for distribution into U.S. Midwest markets via Great Lakes shipping. Provincial carbon pricing mechanisms exceed federal benchmarks, favoring blended cement formulations with lower clinker factors. The St. Lawrence Seaway system enables cost-competitive bulk movement to Chicago and Detroit construction markets.
Mexico
Integrated producers along the Veracruz and Tamaulipas coastlines export bulk cement to Texas and Louisiana terminals. Mexican environmental regulators enforce progressively tighter particulate emission standards at kiln operations. The Monterrey industrial cluster supplies bagged product to northern border states through truck-based distribution networks.
California
Buy Clean procurement rules embed embodied carbon thresholds into state DOT highway contracts. CARB cap-and-trade compliance costs compress margins for high-clinker Portland cement production. The Central Valley agricultural processing and logistics corridor absorbs ready-mix volumes for warehouse and cold storage construction.
Texas
Permian Basin oilfield activity and Gulf Coast petrochemical expansion drive simultaneous demand for oilwell cement and construction grades. State environmental regulators coordinate with EPA on regional haze reduction timelines for kiln operations. The Houston Ship Channel anchors barge-fed distribution into inland markets from integrated coastal plants.
North America Cement Market Key Industry Players
Channel-controlling players compete with product-specialist players across differentiated procurement segments. The North American cement market exhibits consolidated structure at the production level, with integrated manufacturers operating kiln assets and terminal networks. Three archetypes dominate: multinational building materials conglomerates with cross-border manufacturing footprints, regional specialists with concentrated geographic presence, and vertically integrated aggregate-cement-concrete operators. Competitive dynamics center on terminal network density expansion and low-carbon product portfolio development.
Among multinational operators, Heidelberg Materials, CEMEX, and CRH America represent the scale-driven tier with integrated production and distribution assets across multiple jurisdictions. These entities anchor market structure through captive limestone reserves, river terminal networks, and downstream ready-mix operations. Mid-sized regional producers including Eagle Materials and Ash Grove Cement occupy positions defined by concentrated geographic focus and specialized product formulations. Martin Marietta exemplifies the vertically integrated archetype, combining aggregate mining with cement production and concrete batching operations.
| Leading Market Players |
|---|
| Heidelberg Materials |
| Argos USA |
| Amrize |
| Eagle Materials |
| Ash Grove Cement |
| CEMEX |
| Buzzi Unicem |
| Martin Marietta |
| CRH America |
| Others |
Cost & Logistics Intelligence
Mississippi River barge terminals anchor cement logistics economics, with freight rate volatility compressing margins for Midwest distributors while concentrating pricing power among coastal integrated producers with captive waterway access. This corridor cost dynamic forces inland buyers to absorb delivery premiums or accept blended cement formulations with lower clinker factors.
Pricing Analysis
Ordinary Portland cement, Portland-limestone cement, and emerging carbon-captured formulations stratify across three distinct price tiers in North American procurement markets. Three-tier pricing structure across premium, standard, and economy levels reflects clinker content, embodied carbon certification, and ASTM specification tier. Price differentiation stems from Buy Clean procurement thresholds in California and Colorado plus volume scale in multi-year infrastructure contracts. Cost compression in standard-grade Portland cement is intensifying because EPA NESHAP compliance investments are eroding margins without product differentiation. Residential contractors exhibit highest price sensitivity, while federal infrastructure programs demonstrate lowest sensitivity due to performance-specification mandates.
Supply Chain Analysis
Turkey and Vietnam export controls on clinker shipments are tightening seaborne supply availability for U.S. coastal grinding plants. Geographic supply concentration centers on the United States, Mexico, and Canada, with Mexican Veracruz terminals feeding Texas Gulf Coast demand. Raw material dependencies rest on limestone deposits, petroleum coke fuel supply, and supplementary cementitious materials from steel and coal power sectors. Single-source vulnerability runs through concentrated Turkish clinker exports to Florida and California markets. Distribution runs through river barge networks, direct rail to ready-mix plants, and regional distributor aggregators for bagged product.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cement market is entering a cyclical recovery phase as federal infrastructure spending programs absorb excess kiln capacity. Mortgage rate stabilization is rebuilding residential construction pipelines that contracted through recent tightening cycles.
For Market Incumbents: Build regulatory compliance moats by accelerating carbon capture retrofits at Texas and California kiln assets before EPA NESHAP deadlines compress competitor margins. Secure limestone reserves in the Permian Basin and Colorado Front Range to anchor vertical control over clinker production. Defend against import substitution threats by expanding Mississippi River terminal density into underserved Midwest construction corridors. For New Entrants and Emerging Players: Establish a beachhead in carbon-captured blended cement formulations for Colorado and California public works contracts where Buy Clean thresholds filter incumbent qualification. Target precast concrete component suppliers in Florida and Texas seeking documented environmental product declarations for LEED-adjacent projects. Deploy digital procurement platforms with embedded carbon accounting to disintermediate traditional distributor relationships in metropolitan markets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with carbon capture pilot installations and captive limestone reserves over pure-play grinding operations dependent on volatile clinker imports. Five-to-ten year viability hinges on proximity to developing CO2 pipeline networks and state-level low-carbon procurement adoption velocity. Acquisition focus should center on regional specialists with undervalued river terminal assets and EPA-compliant kiln upgrades already deployed. The signal to watch is ASTM C595 specification expansion rates across state departments of transportation.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | EPA NESHAP compliance and IRA tax credits compress the cost gap for low-carbon cement variants. |
| Limestone Reserve Acquisition | Captive quarry access in Texas and Colorado secures clinker production economics against import volatility. |
| River Terminal Network Expansion | Mississippi River barge infrastructure unlocks Midwest market reach from Gulf Coast production bases. |
| Blended Cement Formulation Scale-Up | ASTM C595 specification expansion enables higher supplementary cementitious material substitution rates. |
| Digital Procurement Platform Launch | Online sourcing with embedded environmental product declarations serves California and New York Buy Clean compliance. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with cement plant managers, state DOT procurement officers, ready-mix concrete batch operators, and bulk terminal logistics coordinators; and secondary validation through U.S. Geological Survey mineral commodity summaries, EPA enforcement databases, state transportation department specification documents, and SEC filings from publicly traded building materials conglomerates. Bottom-up volume estimates from kiln capacity utilization rates and top-down demand segmentation from construction spending data were cross-referenced for triangulation.
Forecast inputs considered clinker trade flow patterns, fuel-switching investment timelines, and state-level procurement rule adoption rates across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use construction vertical, application performance specification, and distribution channel configuration. CAGRs were derived from regression analysis of historical cement consumption against construction spending indices and infrastructure appropriation cycles. Industry-specific inputs incorporated EPA compliance deadline schedules and Inflation Reduction Act credit qualification pathways.
Macroeconomic conditions sit as an overlay; deviation in construction spending authorization levels, mortgage rate environments, and petrochemical capital expenditure cycles would shift the trajectory. Forecasts reflect documented assumptions regarding kiln fuel-switching compliance timelines and state procurement rule expansion. Material shifts in federal infrastructure appropriation continuity or carbon capture technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Concrete and Cement Market
Building Materials
Natural Stone Slab Market
Building Materials
India Concealed Cistern Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Global Pozzolan Market
Building Materials
Cement Tiles Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Dutch Brick Market
Building Materials
Spain Architectural Coatings Market
Building Materials
Blind Bolts Market
Building Materials
Exterior Doors Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Fiber Cement Market
Building Materials
Polymer-Modified Cementitious Mortar Market