
 Mechanically Fastened Cross-Laminated Timber Market | 2026-2036
Mechanically Fastened Cross-Laminated Timber Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanically Fastened Cross-Laminated Timber Market Insights
Austria's expanded spruce processing capacity is narrowing the supply gap for engineered timber feedstock across Central Europe. Stora Enso leverages its integrated forest-to-panel operations to secure raw material access. Binderholz anchors its position through dedicated mechanically fastened CLT lines serving Alpine markets. KLH Massivholz GmbH dominates Austrian output with specialized hardwood-compatible fastening systems.
Mechanically fastened cross-laminated timber consists of orthogonally layered solid wood boards joined by metal fasteners rather than adhesives, typically achieving structural performance through screw, dowel, or nail-laminated connections with specified penetration depths and spacing patterns. This construction system serves multi-story buildings seeking reduced embodied carbon and simplified end-of-life disassembly compared to glued alternatives. Panels command the largest volume share due to wall and floor system standardization, while modular construction represents the fastest-growing installation method as off-site fabrication reduces on-site labor dependencies. Connections capture disproportionate engineering attention because fastening detail design governs seismic performance and fire resistance ratings.
Germany's KBA building codes, Austria's ÖNORM timber standards, and the EU Green Deal's embodied carbon thresholds collectively shape product certification requirements and market access conditions for mechanically fastened systems. CE marking under the Construction Products Regulation mandates declared structural performance values that vary by member state implementation. Stakeholders must monitor evolving national interpretations of Eurocode 5 fasteners provisions and their divergence from adhesive-based CLT acceptance criteria.
Market Dynamics
The EU Green Deal's embodied carbon mandates are compressing specification timelines for mechanically fastened CLT, forcing structural engineers to abandon adhesive-based alternatives mid-project cycle. This regulatory pressure intersects with Austria's spruce processing expansion to reshape procurement patterns across Central European construction markets.
Growth Catalysts
- ÖNORM timber standards:Austria's updated fastening specifications now explicitly recognize screw-laminated systems for seismic zones, unlocking multi-story residential permits previously reserved for glued CLT.
- Baden-Württemberg construction cluster:Germany's southwestern state has concentrated prefabrication facilities within 150 kilometers of Alpine feedstock sources, reducing logistics friction for panel delivery.
- Self-tapping screw automation:CNC-guided fastening systems are cutting panel assembly labor hours by half, making mechanically fastened CLT cost-competitive with concrete on four-to-six story frames.
Market Restraints
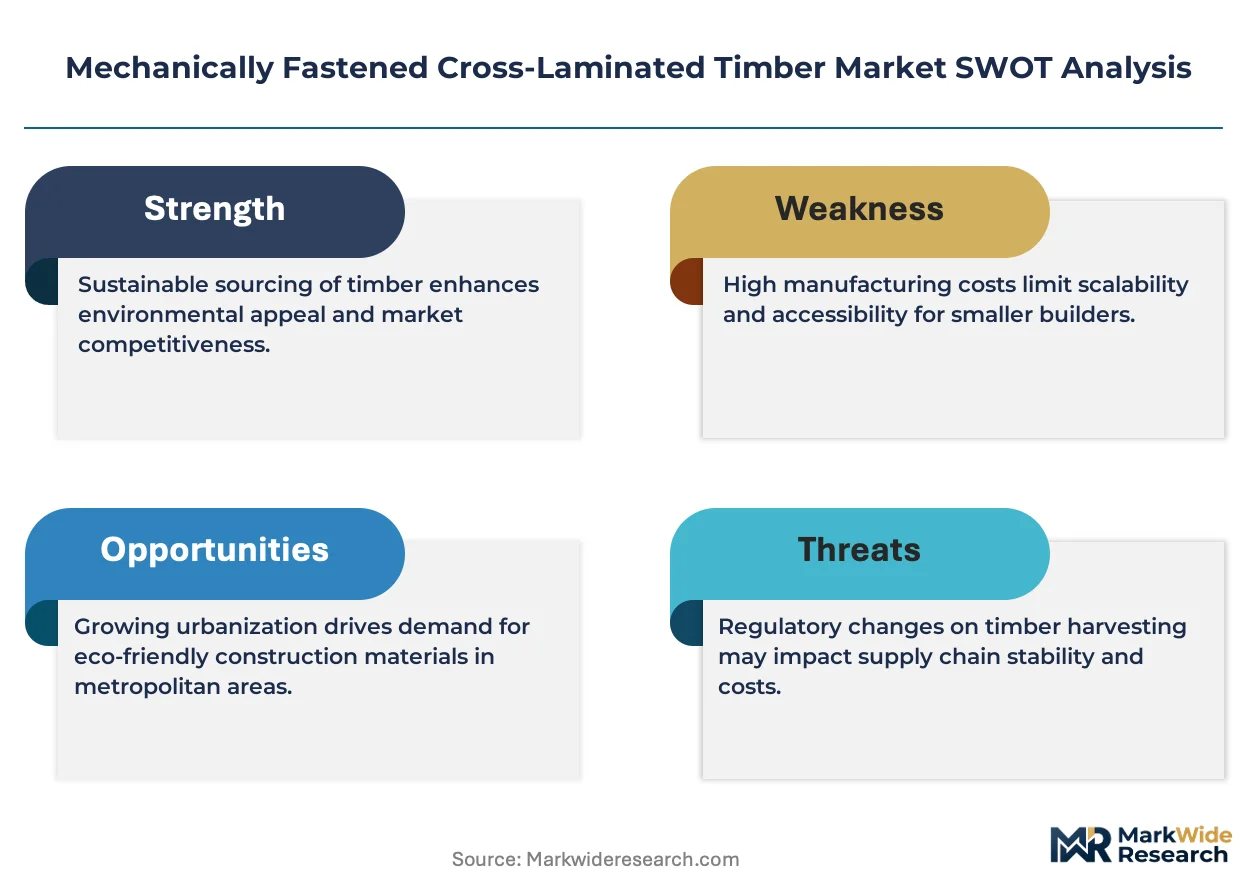
- Spruce supply concentration:Austrian sawmills control 60 percent of Central Europe's engineered timber feedstock, creating single-source vulnerability for German and Swiss panel producers.
- CE marking divergence:Member state interpretations of Eurocode 5 fastener spacing requirements vary by 15-20 percent, forcing manufacturers to maintain multiple certification portfolios.
- Glued CLT incumbent position:Established adhesive-based suppliers in Bavaria and northern Italy hold structural engineering relationships and existing building code precedents.
Strategic Opportunities
- Modular hospital construction:Healthcare developers in Germany are specifying demountable CLT wall systems for future reconfiguration, favoring mechanically fastened panels for end-of-life material recovery.
- EU taxonomy alignment:Green bond financing for construction projects now requires documented circularity credentials, which screw-laminated systems satisfy through simplified disassembly.
- Digital fabrication integration:BIM-to-CNC workflows are enabling mass-customized panel geometries without retooling, opening architect-driven premium segments.
Industry Challenges
- Fastener engineering specialization:Seismic design for multi-story timber requires hybrid steel-timber connection expertise that structural engineering programs in Austria and Germany have not yet scaled.
- Fire rating certification timelines:Obtaining European Technical Assessments for new fastening patterns takes 18-24 months, delaying product launches beyond typical construction cycle windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanically Fastened Cross-Laminated Timber Market |
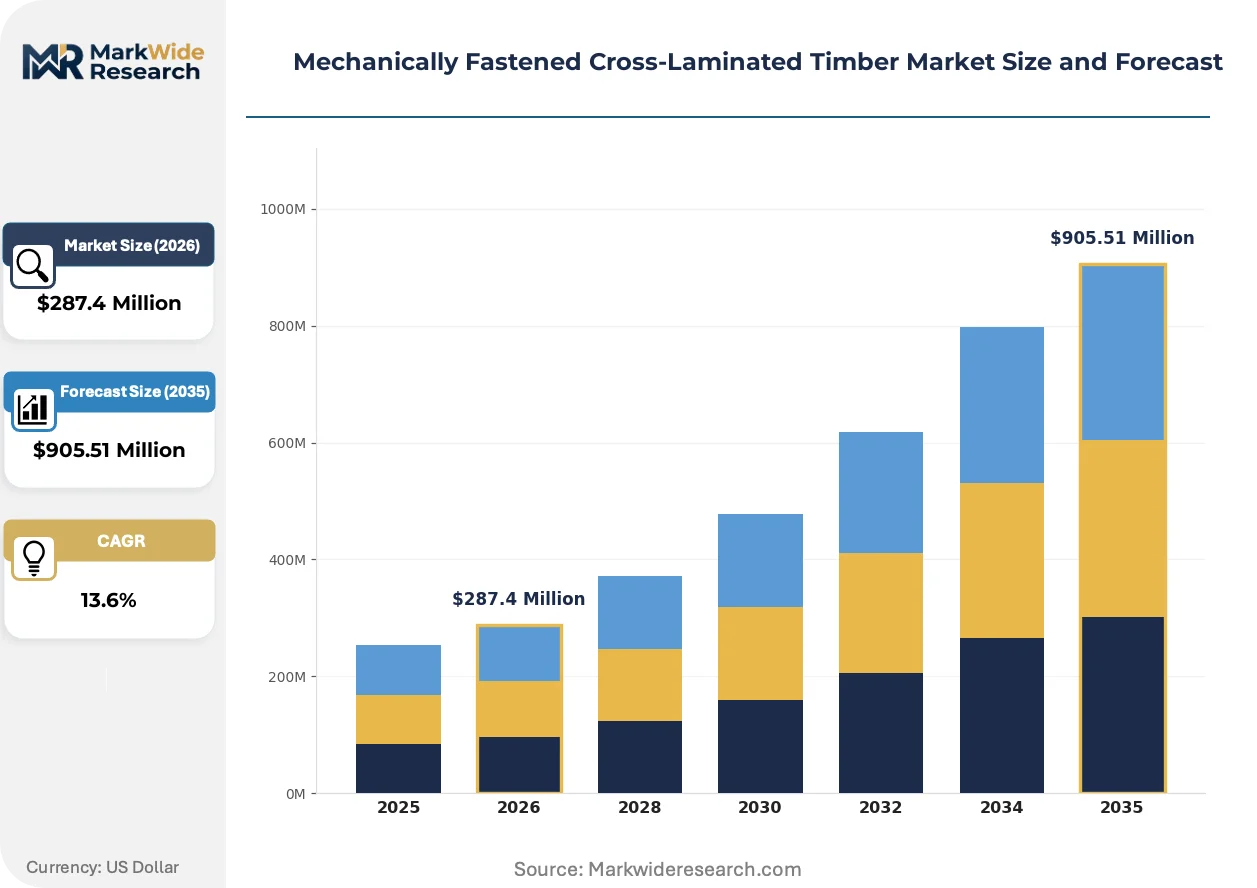
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $905.51 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panels, Beams, Columns, Connections Use Case: Residential Buildings, Commercial Structures, Public Facilities, Industrial Applications Installation Method: On-site Assembly, Off-site Fabrication, Modular Construction, Hybrid Approach End User: Builders, Architects, Contractors, Engineers |
| Companies Covered | ante-Group, Stora Enso, KLH Massivholz GmbH, Binderholz, Mayr-Melnhof Holz Holding AG, HASSLACHER Holding GmbH, Structurlam Mass Timber Corporation, Eugen Decker & WebMan, Schilliger Holz AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanically Fastened Cross-Laminated Timber Market Trends and Innovations
Mechanically fastened CLT is experiencing accelerated specification shifts as digital fabrication converges with tightening carbon accounting rules. Three developments are compressing traditional procurement and design cycles.
Continuous thread self-tapping screws with optimized withdrawal resistance are rendering obsolete traditional dowel-and-glue connection methods in mid-rise seismic zones. Austrian engineering firms are specifying these fasteners for six-to-eight story residential frames. The technology is compressing structural design cycles from months to weeks by eliminating adhesive curing delays from critical path scheduling.
The EU Green Deal's embodied carbon thresholds are mandating whole-life carbon declarations for public construction tenders above two million euros. German federal procurement offices now require Environmental Product Declarations that disclose end-of-life disassembly potential. Mechanically fastened systems capture preference in Baden-Württemberg and Bavaria because their material passports satisfy circularity scoring criteria that glued alternatives cannot match.
Design-build contracts are displacing traditional design-bid-award sequences for timber-framed projects over three stories. Austrian developers are bundling structural engineering with panel fabrication to compress liability chains and accelerate permit approvals. This consolidation is most visible in Vienna's Seestadt and Graz's Reininghaus quarters, where single-source timber contractors now dominate multi-residential procurement.
Mechanically Fastened Cross-Laminated Timber Market Segmentation
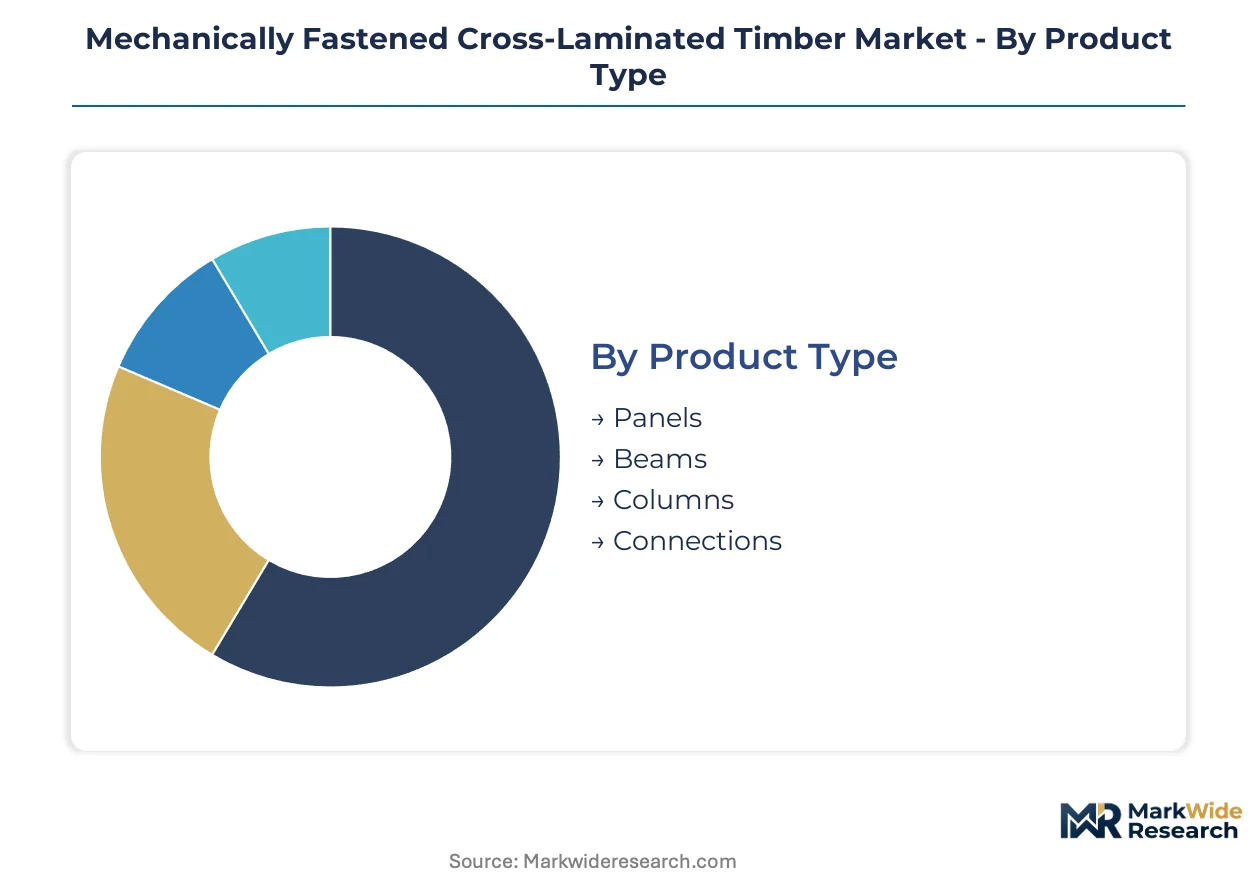
Mechanically fastened CLT serves divergent structural requirements across building heights, carbon compliance regimes, and disassembly mandates. Segmentation reveals how product form, use case, and installation method interact to determine specification patterns in Central European construction markets.
Product Type:
Wall and floor systems span load-bearing elements from simple planar panels to complex moment-resisting connections, each demanding distinct engineering validation under Eurocode 5.
- Panels:Orthogonally layered spruce boards fastened with self-tapping screws at specified penetration depths form standardized wall and floor elements. Demand concentrates in Baden-Württemberg multi-residential projects where panel standardization reduces engineering redundancy and accelerates permit approvals under KBA codes.
- Connections:Metal fasteners engineered for seismic load transfer and fire resistance ratings govern structural performance in multi-story frames. Austrian engineers specify these for Vienna's Seestadt district where ÖNORM seismic provisions now permit screw-laminated alternatives to glued systems.
- Beams:Long-span flexural members assembled from finger-jointed laminations with mechanical end connections.
- Columns:Axial load-bearing elements using clustered fastener patterns for buckling resistance.
Established volume favors panels; emerging adoption favors connections.
Use Case:
Carbon accounting intensity varies sharply across building types, with public procurement thresholds and private developer risk profiles reshaping specification patterns.
- Residential Buildings:Multi-story apartment frames in Alpine markets drive panel standardization for repeatable floor plates. Graz's Reininghaus quarter demonstrates how design-build contractors bundle structural engineering with fabrication to compress liability chains in six-to-eight story timber construction.
- Public Facilities:German federal procurement above two million euros now mandates whole-life carbon declarations and end-of-life disassembly documentation. Healthcare developers specify demountable wall systems for future reconfiguration, with mechanically fastened panels satisfying EU taxonomy circularity scoring.
- Commercial Structures:Office and retail frames seeking premium green certification.
- Industrial Applications:Warehousing and light manufacturing with lower architectural finish requirements.
Residential commands current volume; public facilities are expanding most quickly.
Installation Method:
Labor cost trajectories and schedule compression pressures determine whether fabrication occurs in controlled factory conditions or exposed construction sites.
- Modular Construction:Volumetric units complete with MEP rough-in are fabricated off-site and crane-set into position. This method gains share fastest in Germany's southwestern prefabrication cluster where facilities within 150 kilometers of Alpine feedstock sources minimize logistics friction.
- Off-site Fabrication:Panelized wall and floor elements produced in factory conditions with CNC-guided fastening systems that cut assembly labor hours by half.
- On-site Assembly:Traditional stick-built erection requiring extended crane time and weather-dependent scheduling.
- Hybrid Approach:Combinations of pre-assembled panels with field-installed connections for complex geometries.
Off-site fabrication holds current margin; modular construction shows steepest expansion trajectory.
End User:
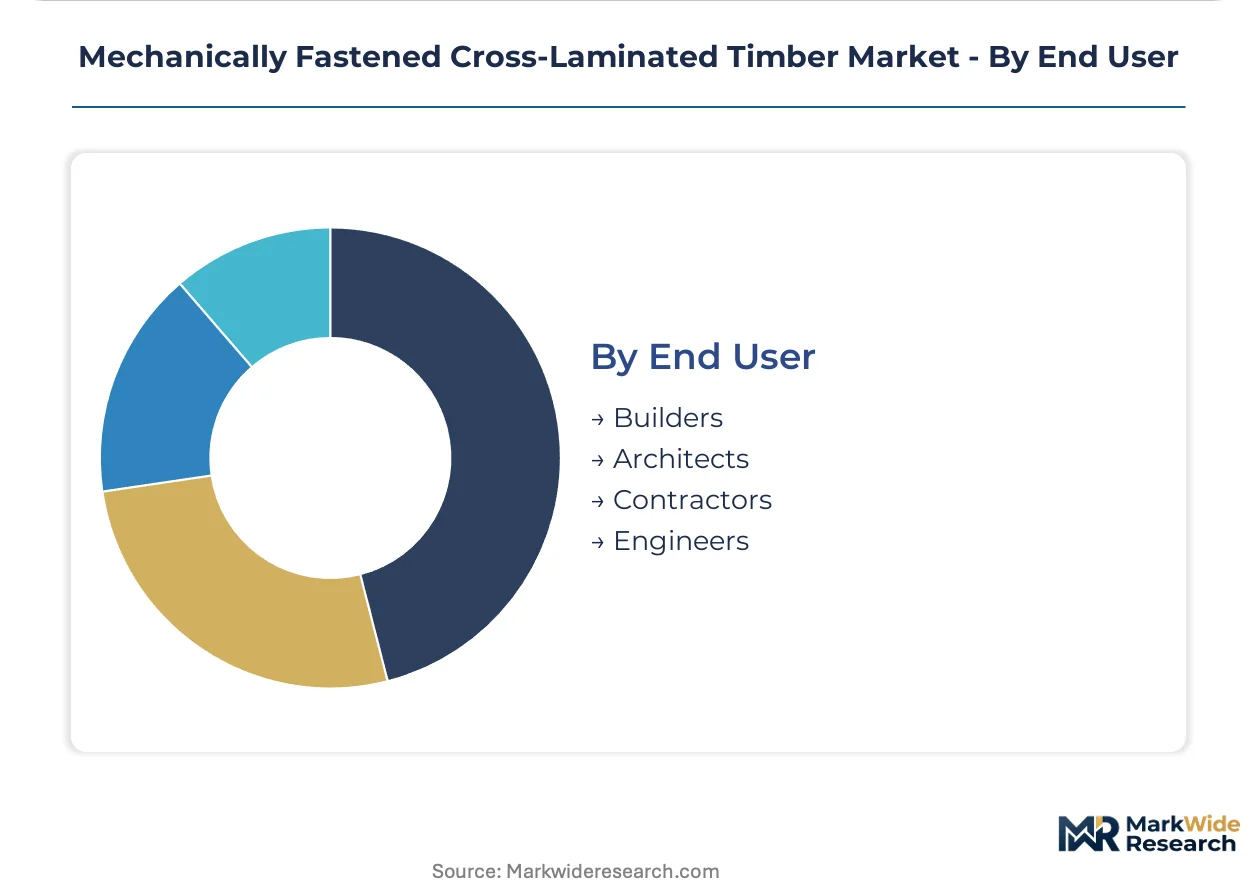
Technical decision authority fragments across project phases, with early-stage architects and late-stage contractors holding divergent preferences for system complexity.
- Builders:Developer-operators prioritizing speed-to-occupancy and end-of-life asset recovery value. Their procurement patterns favor mechanically fastened systems for simplified disassembly and material passport documentation required by green bond financing.
- Engineers:Structural designers navigating Eurocode 5 fastener spacing interpretations that vary by 15-20 percent across member states. Their specification authority is growing as seismic design for multi-story timber requires hybrid steel-timber connection expertise.
- Architects:Design-phase influencers seeking mass-customized geometries through BIM-to-CNC workflows.
- Contractors:Construction-phase executors managing installation risk and warranty exposure.
Builders dominate current procurement; engineers are gaining specification authority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Austrian sawmills control the majority of Central Europe's engineered timber feedstock, creating a supply axis that radiates into Germany and Switzerland. This concentration shapes procurement patterns, code harmonization efforts, and cross-border logistics networks for mechanically fastened CLT systems.
Austria
Multi-story residential construction in Vienna's Seestadt and Graz's Reininghaus quarters drives specification volume for screw-laminated panels. ÖNORM timber standards now explicitly recognize mechanically fastened systems for seismic zones, unlocking permits previously reserved for glued CLT. KLH Massivholz GmbH anchors domestic production capacity through specialized hardwood-compatible fastening lines serving Alpine markets.
Germany
The Baden-Württemberg construction cluster concentrates prefabrication facilities within 150 kilometers of Alpine feedstock sources, compressing logistics friction for panel delivery. KBA building codes shape product certification requirements, with member state interpretations of Eurocode 5 fastener spacing varying by 15-20 percent across federal jurisdictions. Healthcare developers in this southwestern state specify demountable CLT wall systems for future reconfiguration.
Switzerland
Swiss timber engineering firms source the majority of mechanically fastened panel feedstock from Austrian spruce processors, creating cross-border supply dependencies. The country's seismic design requirements favor screw-laminated connections for multi-story frames in Alpine fault zones. Schilliger Holz AG represents domestic fabrication capacity serving premium architectural segments with mass-customized geometries.
Italy
Northern Italian glued CLT incumbents in Bavaria-adjacent provinces hold established structural engineering relationships and building code precedents that slow mechanically fastened adoption. The EU Green Deal's embodied carbon thresholds are nonetheless compressing specification timelines for public construction tenders above two million euros. Regional procurement offices increasingly require Environmental Product Declarations disclosing end-of-life disassembly potential.
Canada
Structurlam Mass Timber Corporation anchors North American mechanically fastened CLT capacity, serving Pacific Northwest and British Columbia multi-story timber markets with panel systems. Canadian federal procurement guidelines for green building materials are beginning to mirror EU taxonomy circularity scoring criteria. The country's building code development process is evaluating Austrian ÖNORM seismic provisions for potential adoption.
Mechanically Fastened Cross-Laminated Timber Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on fastener engineering and connection design. The vendor base organizes around three archetypes: integrated forest-to-panel operators controlling raw material access, specialized fabricators with dedicated mechanically fastened production lines, and engineering-led design-build contractors bundling structural design with fabrication. Dominant competitive moves include backward integration into captive spruce supply and CNC-guided fastening automation to compress assembly labor hours.
Among Austrian-based producers, KLH Massivholz GmbH and Binderholz exemplify the specialized fabricator archetype, each occupying positions defined by their geographic proximity to expanded spruce processing capacity. Stora Enso represents the integrated forest-to-panel model, leveraging upstream control over feedstock sources to secure raw material access across Nordic and Central European markets. These three companies anchor the competitive structure through their respective positions in supply chain configuration, production specialization, and vertical integration depth.
| Leading Market Players |
|---|
| ante-Group |
| Stora Enso |
| KLH Massivholz GmbH |
| Binderholz |
| Mayr-Melnhof Holz Holding AG |
| HASSLACHER Holding GmbH |
| Structurlam Mass Timber Corporation |
| Eugen Decker & WebMan |
| Schilliger Holz AG |
| Others |
Pricing and Supply Chain Analysis
Austrian sawmills commanding sixty percent of Central Europe's engineered timber feedstock concentrate margin capture upstream, forcing downstream panel producers in Germany and Switzerland to absorb logistics premiums or surrender pricing power to integrated forest-to-panel operators.
Pricing Analysis
The EU Green Deal's embodied carbon mandates dictate the pricing tier structure across mechanically fastened CLT procurement. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified mass-customized panels from commodity wall systems and basic structural connections. Price differentiation hinges on CE marking tier and CNC fabrication precision. Cost compression in standard-grade panels is intensifying because Baden-Württemberg prefabrication clusters are automating screw-lamination assembly. Public facility developers show least price sensitivity due to green bond circularity scoring requirements; small residential contractors exhibit highest sensitivity to per-panel delivered cost.
Supply Chain Analysis
Binderholz and KLH Massivholz GmbH hold dedicated mechanically fastened CLT production capacity, anchoring fabrication concentration in Austria's Alpine corridor. Geographic supply concentrates in Austria, Germany's Baden-Württemberg region, and Switzerland's northern cantons. Raw material dependencies rest on spruce feedstock, self-tapping screw hardware, and CNC machining equipment. Single-source vulnerability runs through Austrian sawmill concentration for engineered timber input. Distribution runs through design-build contractors bundling structural engineering with panel fabrication, compressing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanically fastened CLT represents a service-attach opportunity where engineering consulting and end-of-life material passport documentation expand faster than commodity panel fabrication, rewarding vendors who bundle structural design with circularity certification.
For Market Incumbents: Entrench market position through captive spruce supply agreements in Austria's expanded processing corridor and accelerated CNC automation to halve panel assembly labor hours. Defend against emerging design-build contractors consolidating specification authority by investing in ÖNORM seismic certification for hardwood-compatible fastening systems. Prioritize backward integration into Alpine feedstock sources over geographic expansion. For New Entrants and Emerging Players: Modular hospital construction in Germany's southwestern states represents the most penetrable entry point, given healthcare developers' mandated disassembly documentation and green bond financing requirements. Mid-market commercial buildings seeking EU taxonomy alignment offer secondary white-space. Pursue go-to-market partnerships with BIM-to-CNC workflow providers to bypass established structural engineering relationships held by glued CLT incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward engineering-led design-build contractors with demonstrated multi-story timber permitting velocity and established relationships with Austrian feedstock suppliers. Long-term viability across the next decade rests on circularity credentialing capabilities that satisfy evolving EU Green Deal procurement thresholds. Watch for inflection in European Technical Assessment approval timelines for novel fastening patterns, as eighteen-to-twenty-four month delays currently constrain product launch cadence.| Strategic Initiative | Industry Significance |
|---|---|
| CNC-Guided Fastening Automation | Halves assembly labor hours, enabling cost parity with concrete in four-to-six story frames. |
| Backward Integration into Spruce Supply | Secures raw material access against Austrian sawmill concentration and logistics friction. |
| EU Taxonomy Circularity Certification | Unlocks green bond financing for public construction tenders above two million euros. |
| Design-Build Contract Consolidation | Compresses liability chains and accelerates permit approvals under KBA and ÖNORM codes. |
| Modular Hospital Construction Partnerships | Captures healthcare developer demand for demountable wall systems with material passports. |
Research Methodology
Initial hypotheses were tested against primary input from structural engineering directors, timber procurement managers at multi-residential developers, CNC fabrication technicians, and building code officials at KBA and ÖNORM standard bodies and refined through secondary validation against CE marking databases, Eurocode 5 fastener spacing interpretations, EU Green Deal procurement guidelines, and Austrian spruce processing capacity reports. Bottom-up panel demand estimates from Baden-Württemberg and Vienna construction permits were triangulated against top-down engineered timber consumption forecasts.
Demand-supply balance dynamics across the projection horizon anchored the analytical framework, with segmentation modeled by product type, use case, installation method, and end user authority. CAGRs were derived from installation volume trajectories and carbon compliance intensity shifts. Forecast inputs incorporated ÖNORM seismic provision adoption curves and EU taxonomy alignment velocity in public procurement.
Stress conditions across Austrian feedstock supply disruption, CE marking divergence across member states, and glued CLT incumbent pricing responses were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of European Technical Assessment approval timelines and Baden-Württemberg prefabrication cluster capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
PU Waterstops Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Sawn and Profiled Wood Products Market
Building & Construction Materials
Softwood Lumber Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
North America Ready-Mix Concrete Market