
 Pozzolana Cement Market | 2026-2036
Pozzolana Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Pozzolana Cement Market Outlook
The EU Green Deal's embodied carbon thresholds for construction materials is rebalancing procurement specifications across European public infrastructure tenders. HeidelbergCement leverages its vertical integration into pozzolana sourcing to secure consistent feedstock quality across Nordic markets. Holcim sustains technology leadership in clinker substitution ratios, while UltraTech Cement Limited anchors South Asian supply through dedicated grinding units in Gujarat and Maharashtra.
Pozzolana cement is a hydraulic binder produced by intergrinding Portland cement clinker with reactive siliceous or aluminous materials such as volcanic ash, calcined clay, or fly ash, typically achieving 15-40% pozzolanic content by mass. Its primary industrial purpose is to reduce embodied carbon in concrete while enhancing sulfate resistance and long-term compressive strength in aggressive environments. Artificial Pozzolana and fly ash categories dominate volume flows where coal combustion residuals or calcined clay supply chains achieve scale, while natural pozzolana commands premium positioning in volcanic regions with limited clinker access. Infrastructure Development as an end user concentrates margin pools in long-diameter pipeline and hydropower contracts where durability specifications justify higher-grade blended formulations.
REACH regulation in Europe governs chemical safety in construction material additives, while India's BIS certification mandates IS 1489 standards for Portland pozzolana cement strength grades, and the EPA in the United States monitors coal ash utilization under subtitle D of the Resource Conservation and Recovery Act. These frameworks collectively determine feedstock eligibility, product labeling, and cross-border shipment compliance for pozzolanic blends. Stakeholders must monitor evolving clinker-factor caps in national building codes and pre-qualify alternative pozzolanic sources before supply disruptions force specification switches.
Market Dynamics
Clinker substitution mandates embedded in national building codes are compressing formulation margins while forcing rapid feedstock diversification across cement producers. The EU Green Deal's embodied carbon thresholds and India's BIS certification requirements are accelerating specification switches before supply chains achieve scale.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:Public infrastructure tenders across Germany, France, and the Netherlands now require supplementary cementitious materials, redirecting procurement volumes toward pozzolanic blends.
- Coastal infrastructure durability specifications:Marine structures in Vietnam, Indonesia, and the Philippines specify sulfate-resistant formulations, pulling natural pozzolana into premium-grade contracts.
- Calcined clay activation technology:Flash calcination processes for kaolinitic clay are achieving reactivity parity with fly ash, expanding feedstock options beyond coal-dependent regions.
Market Restraints
- Fly ash supply concentration:Coal power plant retirements in the United States and Western Europe are constraining residual availability, forcing specification switches to unproven alternatives.
- Natural pozzolana geographic lock:Volcanic deposit quality varies sharply between Italian, Greek, and Kenyan sources, creating batch consistency risks for marine-grade contracts.
- Clinker factor floor limits:Structural concrete applications under EN 197-1 and IS 1489 maintain minimum clinker thresholds that cap substitution economics.
Strategic Opportunities
- Underpenetrated African markets:Ethiopia, Kenya, and Tanzania lack domestic clinker capacity yet possess untapped volcanic pozzolana deposits suitable for regional export positioning.
- Geopolymer binder convergence:Alkali-activated metakaolin systems are crossing into mainstream concrete applications, opening formulation partnerships between cement and chemical producers.
- India's PLI scheme for green construction:Production-linked incentives for low-carbon building materials are subsidizing grinding unit investments in Gujarat and Maharashtra.
Industry Challenges
- Pozzolanic reactivity certification timelines:BIS and EN 196-5 testing protocols require 28-day strength validation, delaying product launches by six to nine months.
- Multi-source feedstock integration:Blending natural pozzolana with calcined clay or fly ash demands real-time quality control systems that legacy grinding units lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pozzolana Cement Market |
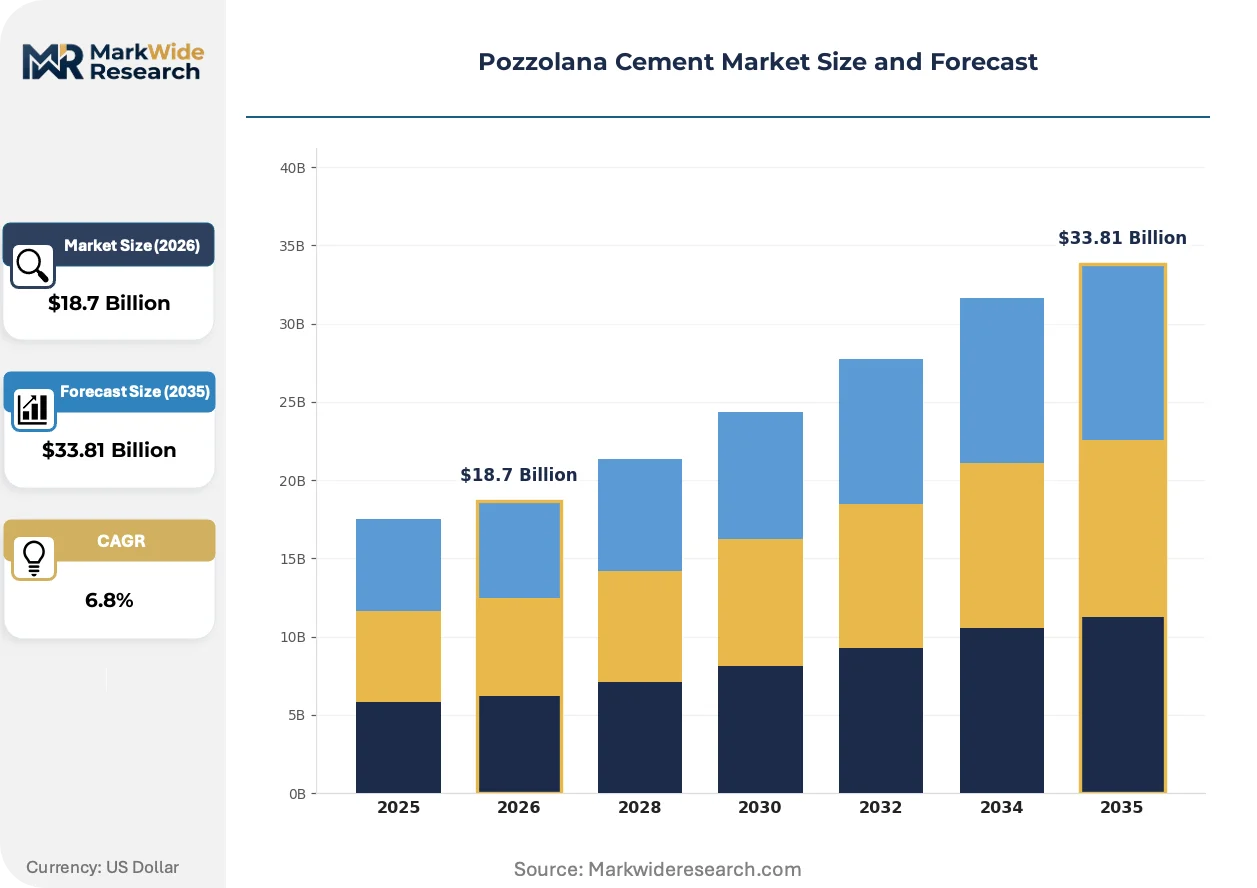
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Pozzolana, Artificial Pozzolana, Blended Pozzolana, Fly Ash End User: Residential Construction, Commercial Construction, Infrastructure Development, Precast Concrete Application: Building Materials, Road Construction, Structural Repairs, Grouting Distribution Channel: Direct Sales, Online Sales, Retail Stores, Distributor Networks |
| Companies Covered | HeidelbergCement, Holcim, China National Building Material Group, Siam Cement Group, UltraTech Cement Limited, Anhui Conch Cement, CEMEX, Vicat Group, LafargeHolcim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pozzolana Cement Market Strategic Shifts
Calcined clay activation is compressing the performance gap between artificial and natural pozzolanic sources, while regulatory frameworks harden around embodied carbon disclosure. Procurement specifications are fragmenting across public infrastructure, commercial construction, and marine applications.
Flash calcination of kaolinitic clay is consolidating the artificial pozzolana segment around reactivity-controlled outputs. Dam and hydropower contractors in Vietnam and Indonesia are specifying calcined clay blends for sulfate resistance. This technology is consolidating supply chain control among integrated producers with captive clay deposits.
REACH regulation in Europe is tightening chemical safety documentation for construction material additives. ECHA's expanded substance evaluation obligations are forcing pozzolana importers to pre-register feedstock origins. Marine concrete specifications in Nordic markets are responding with third-party chain-of-custody certifications.
Engineering-procurement-construction firms are unbundling cement specification from general contracting, creating direct relationships with pozzolana blend suppliers. Large-scale hydropower developers in India and Southeast Asia are bypassing traditional distributor networks. This disintermediation concentrates margin capture with specification-capable producers in Gujarat and Maharashtra.
Pozzolana Cement Market Segmentation
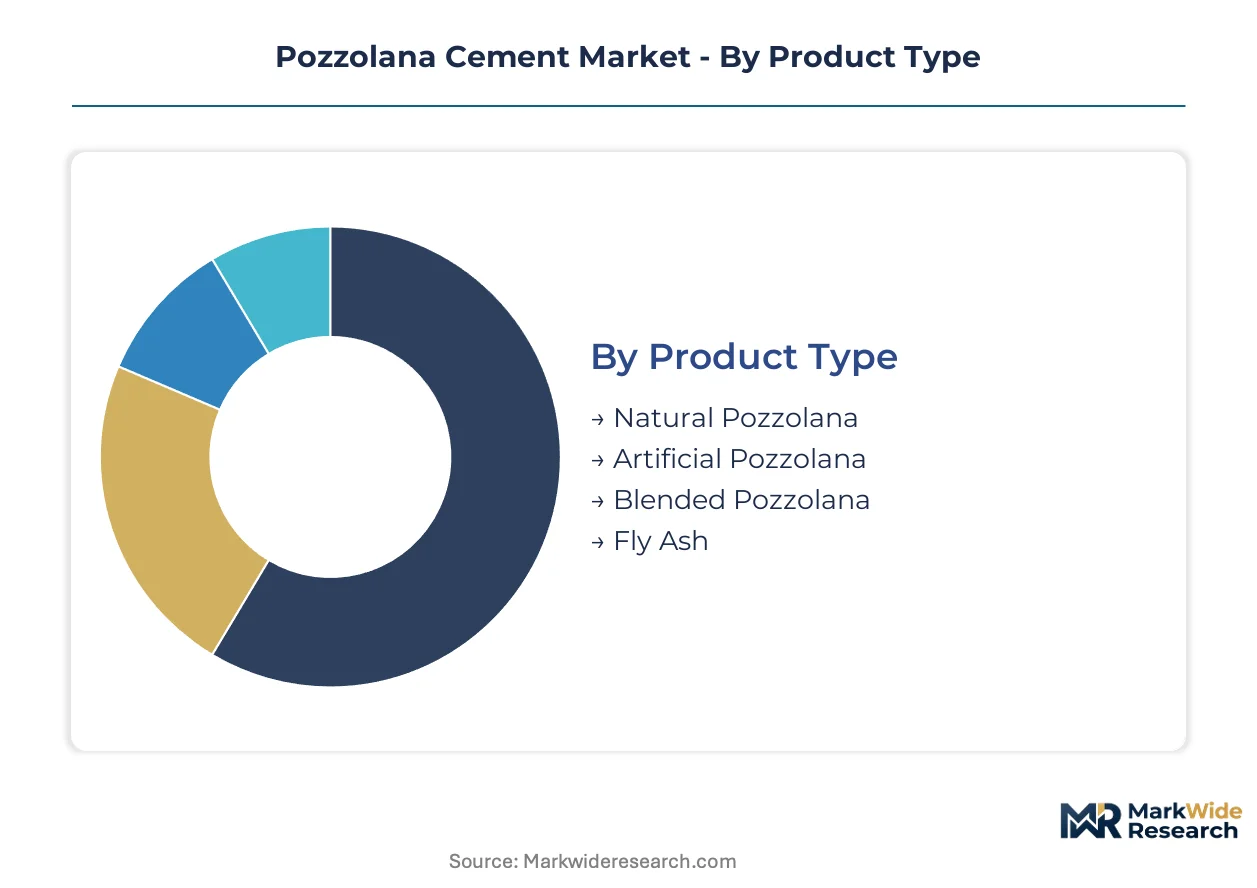
Pozzolana cement procurement decisions fragment across technical specifications, project scale, and supply chain reliability. Each segmentation dimension reveals distinct margin pools and capital requirements for producers positioning across infrastructure, commercial, and residential verticals.
Product Type:
Natural pozzolana extraction demands the heaviest upfront geological surveying and mining infrastructure, while artificial pozzolana production centers on kiln and calcination technology investments.
- Natural Pozzolana:Volcanic ash or sedimentary deposits with reactive silica content above 70% by mass enable clinker substitution rates reaching 35-40%. Marine concrete contractors in Italy and Greece specify this grade for sulfate resistance in coastal infrastructure. Geographic lock to volcanic regions constrains supply chain expansion.
- Artificial Pozzolana:Flash-calcined kaolinitic clay achieves reactivity parity with fly ash through controlled thermal activation. Dam and hydropower developers in Vietnam and Indonesia are specifying calcined clay blends for aggressive groundwater environments. Technology licensing costs dominate capital deployment for new entrants.
- Blended Pozzolana:Interground combinations of multiple pozzolanic sources optimize performance-cost ratios for regional specifications.
- Fly Ash:Coal combustion residuals processed to IS 3812 or EN 450 standards constitute the volume backbone in coal-dependent economies.
Most installed capacity flows through artificial pozzolana. Expansion is steepest in natural pozzolana as marine-grade premiums justify extraction investments.
End User:
Project scale and specification stringency separate margin tiers, with infrastructure contracts commanding the longest durability warranties and tightest quality documentation.
- Infrastructure Development:National highway authorities in India mandate Portland pozzolana cement under Ministry of Road Transport and Highways guidelines. Long-diameter pipelines and hydropower structures require 50-100 year service life guarantees that justify premium blended formulations. BIS certification timelines and 28-day strength validation protocols extend procurement cycles.
- Commercial Construction:High-rise concrete specifications in urban India and Southeast Asia prioritize pumpability and early strength development. Shopping mall and office tower contractors balance embodied carbon targets with construction schedule pressures. Ready-mix concrete suppliers dominate channel relationships in this segment.
- Residential Construction:Individual housing projects and small-scale developments drive volume in price-sensitive rural markets.
- Precast Concrete:Factory-controlled curing environments enable higher pozzolanic content without compromising early strength requirements.
Revenue concentration sits with infrastructure. Residential construction is expanding most quickly as affordable housing programs accelerate in India.
Application:
Performance requirements and exposure severity determine formulation complexity, with marine and chemical environments demanding the highest substitution ratios.
- Road Construction:Pavement and highway base courses utilize fly ash blends for mass concrete applications where heat of hydration control matters. National highway projects in Gujarat and Maharashtra specify controlled low-strength material for embankment fills. Volume scale compensates for thinner margins per ton.
- Building Materials:Masonry cement and plastering applications tolerate lower reactivity pozzolans, expanding feedstock options beyond premium grades. Block and brick manufacturers in Kenya and Tanzania source volcanic ash for cost-competitive regional supply. Quality consistency challenges fragment procurement across small-scale producers.
- Structural Repairs:Patch materials and overlay systems require compatibility with existing concrete substrates.
- Grouting:Tunnel backfill and soil stabilization applications demand fluidity retention and controlled setting characteristics.
Building materials absorb the largest volume share. Road construction is gaining share fastest as highway kilometer targets expand across India.
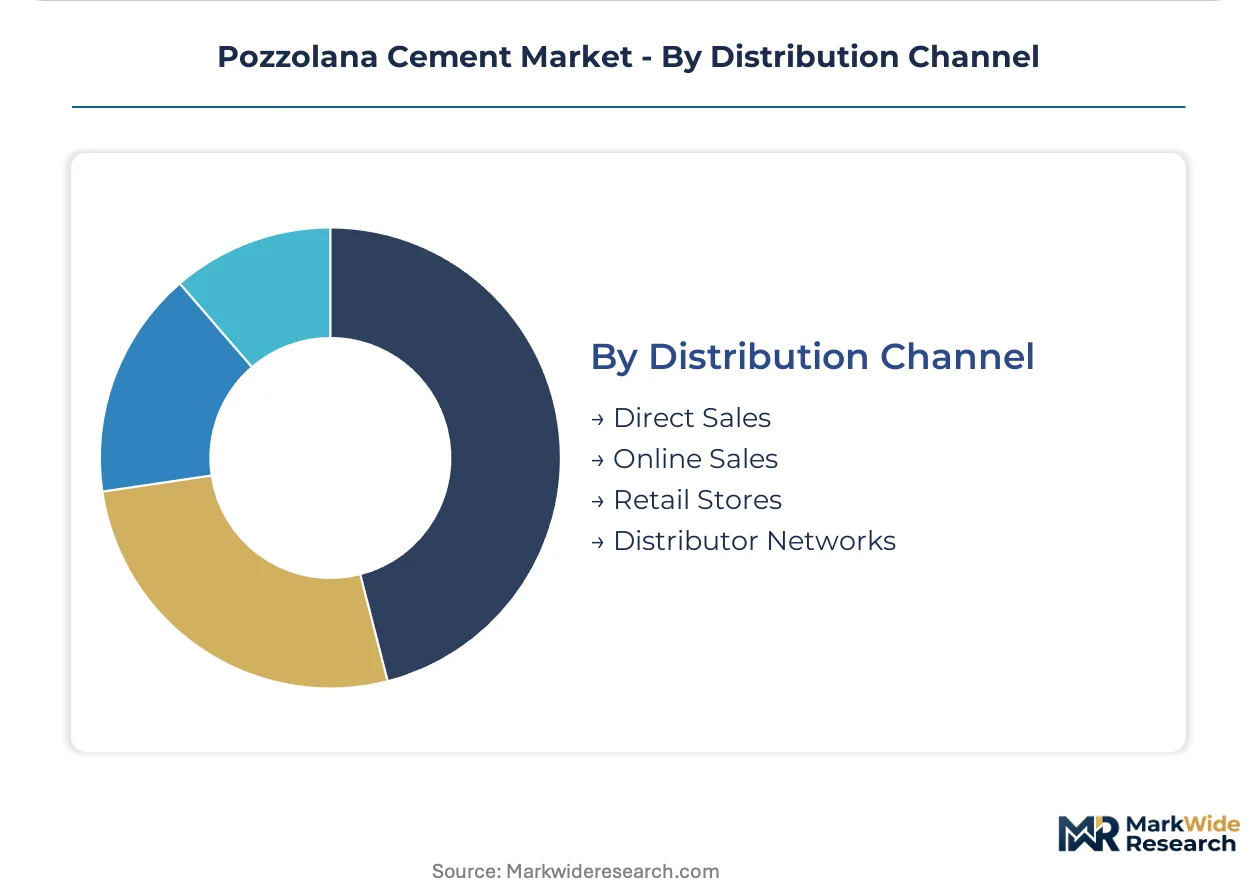
Distribution Channel:
Customer scale and specification capability separate channel economics, with direct relationships capturing margin from technically demanding projects.
- Direct Sales:Engineering-procurement-construction firms and large hydropower developers negotiate directly with grinding unit operators in Gujarat and Maharashtra. Disintermediation concentrates margin capture with specification-capable producers capable of batch certification and chain-of-custody documentation. Relationship maintenance costs exceed distributor commissions for accounts above threshold volumes.
- Distributor Networks:Regional stockists aggregate fragmented demand from smaller contractors and hardware retailers across secondary cities. Credit terms and last-mile logistics justify markup layers that compress producer margins. Network density determines competitive positioning in rural India.
- Retail Stores:Bagged cement sales to individual builders and small contractors dominate rural and semi-urban penetration.
- Online Sales:Digital platforms for bulk procurement and price discovery remain nascent in construction materials.
Distributor networks handle the majority of volume tonnage. Direct sales are climbing the fastest as infrastructure project scale concentrates procurement authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cement chemists and materials engineers cluster around volcanic deposit regions and coastal infrastructure corridors, anchoring technical capability where pozzolanic sourcing meets marine-grade specification demand.
India
National highway expansion and hydropower dam construction consume the majority of Portland pozzolana cement output. The Ministry of Road Transport and Highways mandates blended formulations for all trunk road projects under BIS IS 1489 standards. Grinding unit concentration in Gujarat and Maharashtra supplies western and central infrastructure corridors with specification-certified material.
Germany
Public infrastructure tenders under the EU Green Deal require embodied carbon disclosures that favor supplementary cementitious materials. The country's national building code enforces clinker-factor caps through DIN EN 197-1 compliance protocols. Industrial clusters along the Rhine corridor integrate pozzolanic blending into low-carbon concrete supply chains for federal transport projects.
Italy
Marine concrete contractors source natural pozzolana from volcanic deposits in the Campania and Lazio regions for sulfate-resistant harbor structures. REACH regulation through ECHA mandates pre-registration of feedstock origins for construction material additives. The Naples-Salerno industrial zone processes premium-grade volcanic ash for Mediterranean coastal infrastructure contracts.
Vietnam
Hydropower developers specify calcined clay blends for aggressive groundwater environments in the Central Highlands dam complexes. The country's national construction standards align with regional durability specifications for sulfate resistance. Da Nang and Ho Chi Minh City serve as formulation hubs where flash calcination technology reaches reactivity parity with traditional fly ash.
United States
Coal power plant retirements constrain fly ash availability for concrete producers in the Ohio River Valley and Southeast. EPA subtitle D of the Resource Conservation and Recovery Act monitors coal ash utilization for environmental compliance. Houston and Los Angeles metropolitan areas pivot toward calcined clay and natural pozzolana imports as residual supplies contract.
Pozzolana Cement Market Competitive Environment
Capital-heavy producers compete with asset-light blenders across the pozzolana cement value chain, with integrated kiln operators controlling upstream clinker supply while independent grinding units capture specification-driven margin pools. The market structures around three tiers: multinational building materials conglomerates with captive pozzolana sourcing, regional specialists leveraging volcanic deposit proximity, and project-specific blenders serving engineered infrastructure contracts. Dominant competitive moves include backward integration into calcined clay deposits and technology licensing partnerships for flash calcination reactivation.
Among European-anchored building materials groups, HeidelbergCement and Holcim occupy positions within the integrated multinational tier, each representing archetypes of upstream control over supplementary cementitious material feedstocks. UltraTech Cement Limited anchors the South Asian specialist segment with concentrated grinding capacity in Gujarat and Maharashtra. These three entities exemplify divergent strategic postures: European conglomerates leverage regulatory-driven specification shifts, while the Indian specialist captures production-linked incentive subsidies for green construction materials.
| Leading Market Players |
|---|
| HeidelbergCement |
| Holcim |
| China National Building Material Group |
| Siam Cement Group |
| UltraTech Cement Limited |
| Anhui Conch Cement |
| CEMEX |
| Vicat Group |
| LafargeHolcim |
| Others |
Value Chain & Pricing Dynamics
Flash calcination technology for kaolinitic clay is compressing production costs while redistributing supply power toward integrated producers with captive mineral deposits. This thermal activation method simultaneously reduces dependency on coal combustion residuals and concentrates margin capture among kiln operators in Gujarat and Maharashtra.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates marine-grade natural pozzolana from artificial calcined clay and residual fly ash categories. Price differentiation hinges on BIS IS 1489 certification grade and clinker substitution ratio, with infrastructure contractors in India showing lowest sensitivity due to durability warranty requirements. Cost compression in economy-tier fly ash blends is intensifying because coal power plant retirements in the United States and Western Europe are constraining residual availability.
Supply Chain Analysis
Freight costs from volcanic extraction sites in Italy, Greece, and Kenya to coastal infrastructure projects compress margins for natural pozzolana suppliers. Raw material flows draw from calcined clay deposits in Vietnam, fly ash reservoirs in India, and volcanic ash quarries in East Africa. Single-source vulnerability around coal-dependent fly ash regions feeds supply chain risk as utilities accelerate plant closures. Distribution runs through direct sales channels for large hydropower developers and distributor networks for fragmented rural construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement specifications are hardening around 50-100 year durability warranties for marine and hydropower concrete. Infrastructure authorities in India and Vietnam are redirecting volume toward certified blended formulations with documented reactivity performance.
For Market Incumbents: Acquire calcined clay mineral concessions in kaolinite-rich regions before technology licensing costs escalate. Secure BIS and EN 196-5 pre-certification for multi-source pozzolanic blends to defend against emerging flash calcination specialists. Backward integration into captive clay deposits anchors feedstock quality for premium marine-grade contracts. For New Entrants and Emerging Players: Enter via specification-capable grinding unit partnerships in Ethiopia, Kenya, and Tanzania where domestic clinker capacity gaps meet untapped volcanic pozzolana deposits. Target dam and hydropower contractors in the Central Highlands of Vietnam demanding sulfate-resistant formulations. Lead with third-party chain-of-custody documentation to bypass established distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among independent grinding unit operators in Maharashtra lacking calcination technology but possessing BIS certification infrastructure. Long-term viability centers on clinker-factor cap compliance across national building codes in India, Germany, and Italy. Watch for India's PLI scheme subsidy expansion as the inflection signal for green construction material capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Calcined Clay Deposits | Captive mineral supply secures reactivity consistency for EN 197-1 compliant blends in Nordic markets. |
| Flash Calcination Technology Licensing | Controlled thermal activation achieves fly ash parity for hydropower contractors in Vietnam and Indonesia. |
| BIS IS 1489 Pre-Certification Investment | 28-day strength validation protocols accelerate procurement cycles for Ministry of Road Transport and Highways projects. |
| Direct Sales Channel Development | Engineering-procurement-construction relationships capture margin from large-scale pipeline and dam contracts. |
| Geographic Expansion to East African Deposits | Volcanic pozzolana extraction in Kenya and Tanzania addresses regional clinker shortage for infrastructure buildout. |
Study Parameters
Direct dialogue with cement plant managers, procurement leads at hydropower developers, BIS certification officers, and distribution channel partners in Gujarat and Maharashtra grounded qualitative findings. Secondary validation drew from customs and trade data, Ministry of Road Transport and Highways project disclosures, EPA coal ash utilization reports, and ECHA REACH substance evaluations. Bottom-up grinding unit capacity assessments and top-down infrastructure spending projections were triangulated to cross-verify volume estimates.
Segmentation outputs across product type, end user, application, and distribution channel were modeled across the analysis window. CAGRs were derived from regression analysis against clinker substitution mandates and embodied carbon threshold trajectories. Forecast inputs incorporated EU Green Deal procurement specifications, India's PLI scheme subsidy trajectories, and coal power plant retirement schedules affecting fly ash availability.
Inputs from BIS certification databases and ECHA pre-registration records were available through the study window; gaps in real-time pozzolanic reactivity testing data introduce uncertainty bands around substitution ratio assumptions. Forecasts reflect documented assumptions about regulatory enforcement timelines and calcination technology diffusion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
India Construction Ornamental Stone Market
Building Materials
Concrete Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Rubbing Bricks Market
Building Materials
Construction Materials Market
Building Materials
Composite Rebar Market
Building Materials
Qatar Facade Market
Building Materials
Basalt Rock Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Glass Facade Market
Building Materials
Latin America Facade Market
Building Materials
West Africa Cement Market
Building Materials
Natural Stone Slab Market
Building Materials
Plaster Accelerator Market
Building Materials
Dutch Brick Market