
 Roofing Underlayment Market | 2026-2036
Roofing Underlayment Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing Underlayment Market Analysis
Multi-source procurement among residential builders is recalibrating how underlayment volumes flow through distribution. Owens Corning leverages its integrated building materials platform to bundle underlayment with shingle systems. CertainTeed Corporation anchors its position through specialized synthetic formulations that target high-wind zones. GAF Materials competes on manufacturing scale, operating one of the largest asphaltic underlayment production networks serving the replacement segment.
Roofing underlayment is a secondary water-shedding barrier installed between the roof deck and primary covering, typically manufactured from organic felt saturated with asphalt, polypropylene, or rubberized polymers in thicknesses ranging from 15 mil to 40 mil. Its primary purpose is to protect the structure from wind-driven rain and ice dam infiltration when the outer roof covering is compromised or displaced. Synthetic underlayment leads in new construction applications due to lighter roll weights and extended UV exposure tolerance, while self-adhesive variants command premium positioning in steep-slope and cold-climate installations where ice dam protection is mandatory. Felt remains entrenched in renovation and repair channels where contractors prioritize material familiarity and lower per-square cost.
ASTM International sets the baseline material specifications through D226 and D6757, while the International Code Council incorporates these into model building codes that municipalities adopt with local amendments. The EPA's stormwater management guidelines and state-level wind uplift requirements in Florida and Texas shape product selection criteria for moisture barrier performance. Stakeholders must monitor evolving code harmonization between ASTM standards and insurance industry loss mitigation incentives that increasingly tie premium reductions to specific underlayment performance tiers.
Market Dynamics
Hurricane-resistant building codes across the southeastern United States are compressing specification cycles and forcing rapid product upgrades. ASTM D226 and ASTM D6757 standards now mandate higher tear resistance and UV stability thresholds than legacy felt materials can achieve.
Growth Catalysts
- Florida Building Code wind uplift mandates:Coastal counties now require self-adhering underlayment on all new steep-slope residential construction. Contractors stock premium synthetic grades to avoid inspection delays.
- Residential re-roofing volume:Homeowners in storm-damaged regions accelerate replacement cycles after insurance loss settlements. This shortens the traditional 20-year replacement interval.
- Synthetic polymer formulations:Polypropylene and rubberized asphalt blends deliver 180-day UV exposure tolerance. Builders in Texas and Louisiana specify these for extended construction timelines.
Market Restraints
- Asphalt feedstock volatility:Refinery output fluctuations in the Gulf Coast region create 15-30 day price swings for saturated felt manufacturers. Smaller mills lack hedging capacity.
- Mid-Atlantic distribution concentration:Three regional distributors control 60% of synthetic underlayment throughput from Baltimore to Atlanta. Disruption at any hub stalls contractor availability.
- Felt familiarity lock-in:Renovation crews in the Midwest resist synthetic training requirements. Labor productivity drops 20% during the first three jobs with unfamiliar roll handling.
Strategic Opportunities
- Texas Hill Country wildland-urban interface:Unincorporated counties lack adopted building codes. Fire-resistant underlayment manufacturers can establish specification before municipal adoption.
- Insurance premium reduction programs:Florida's My Safe Florida Home initiative ties wind mitigation credits to underlayment performance tiers. Contractors bundle documentation services with installation.
- Direct-to-roofer digital platforms:Regional distributors launch contractor apps with same-day delivery. This bypasses traditional two-step distribution through lumberyards.
Industry Challenges
- ASTM D6757 certification backlog:Third-party testing labs operate on 12-week queues. Manufacturers delay regional launches while awaiting formal compliance letters.
- Synthetic-to-felt crew retraining:Steep-slope specialists require 40 hours of supervised installation before warranty coverage activates. Labor shortages extend onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing Underlayment Market |
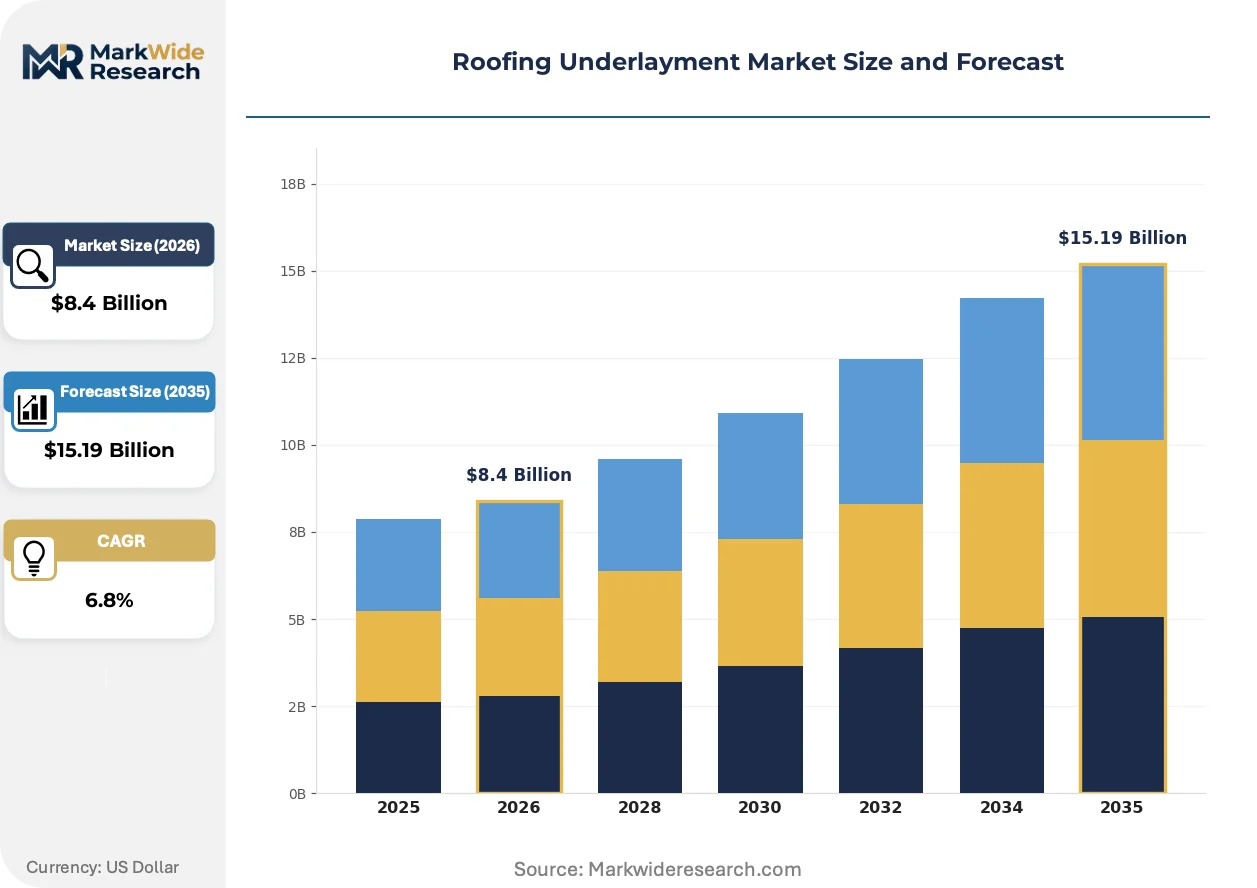
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Felt, Synthetic, Self-Adhesive, Rubberized End User: Homeowners, Contractors, Builders, Architects Installation Type: New Construction, Renovation, Repair, Retrofitting Thickness: 30 mil, 15 mil, 20 mil, 40 mil |
| Companies Covered | GAF Materials, Owens Corning, DuPont de Nemours, Inc., CertainTeed Corporation, Johns Manville, Carlisle Companies Inc., Atlas Roofing Corporation, IKO Industries, Inc., Tamko Building Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing Underlayment Market Emerging Trajectories
Material science advances and code harmonization pressures are collapsing the traditional felt-synthetic segmentation. Manufacturers now engineer hybrid products that bridge cost and performance tiers.
Synthetic polymer underlayment with embedded fiberglass scrim is rewriting contractor expectations for walkability and fastener retention. Production homebuilders in Florida and coastal Texas specify these grades for 6-month build cycles. The technology is compressing felt's residual share in new construction by enabling labor crews to maintain familiar installation speeds.
ASTM International's accelerated harmonization with ICC model codes is tightening performance verification requirements. Manufacturers must now submit continuous UV exposure data beyond the previous 30-day threshold. High-wind zone jurisdictions in Miami-Dade and Broward counties are the first to adopt the stricter testing protocols.
Multi-source procurement patterns among national builders are fragmenting traditional distributor relationships. Large residential developers now contract directly with underlayment mills for project-specific formulations. This disintermediation is most visible in Texas, where volume homebuilders bypass regional roofing suppliers for captive supply arrangements.
Roofing Underlayment Market Segmentation
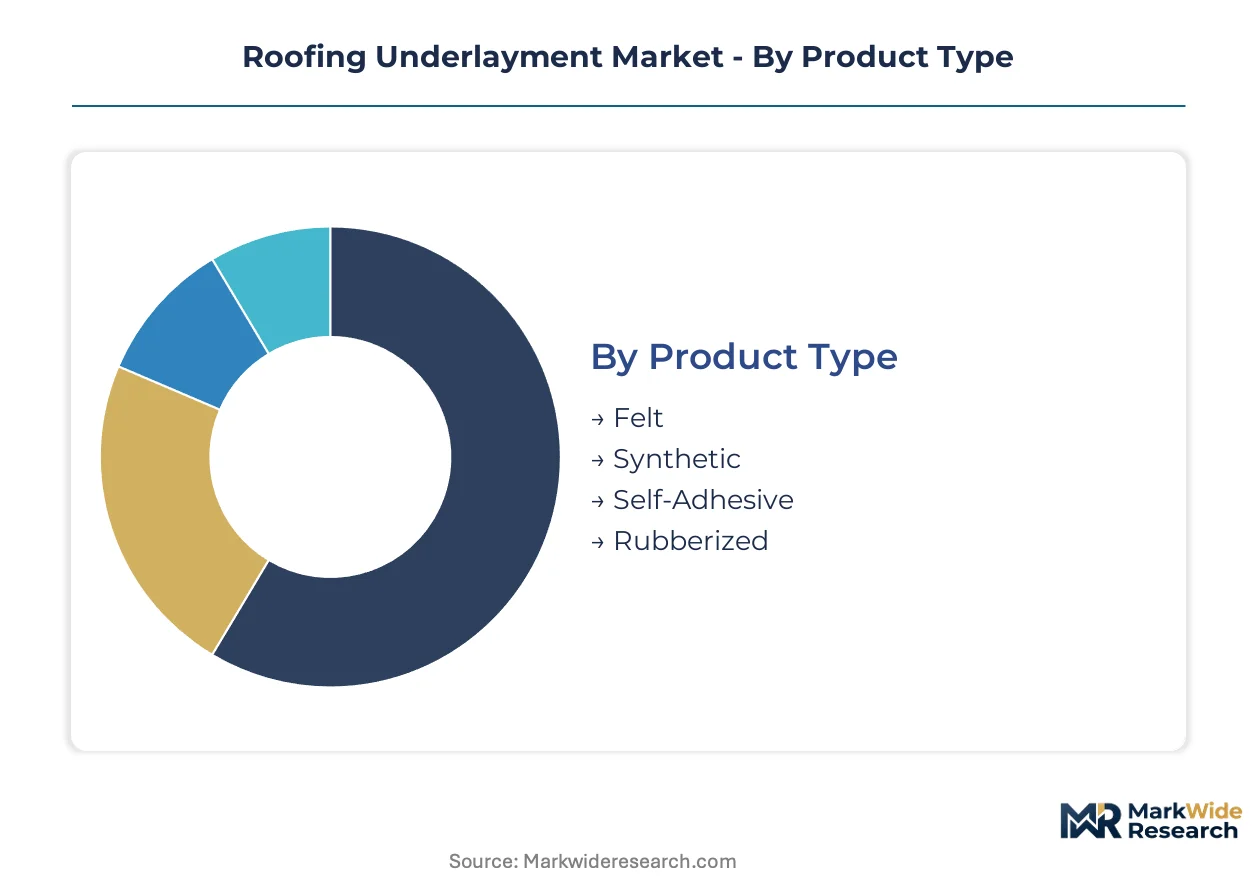
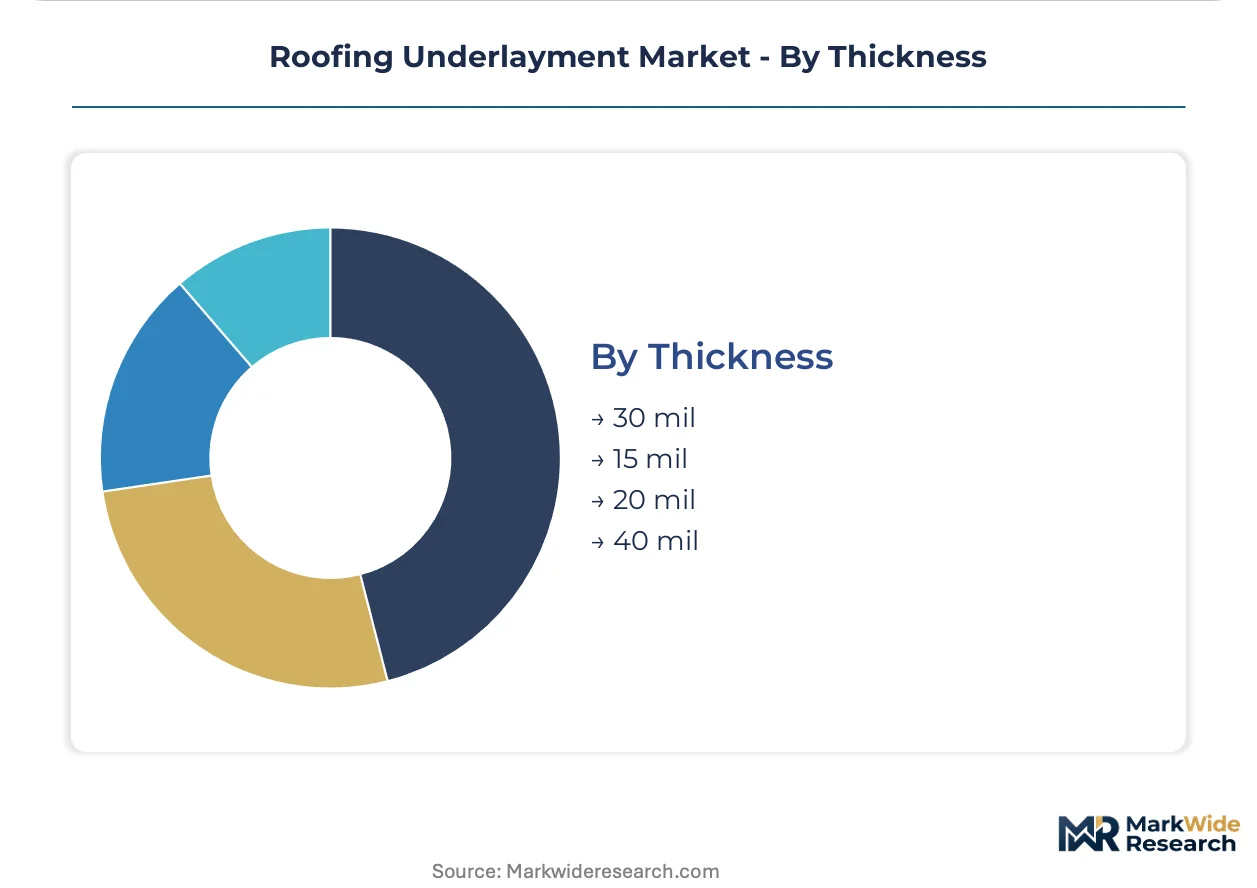
Roofing underlayment segmentation reveals divergent performance requirements across installation contexts. Product specifications vary sharply between hurricane-code coastal zones and standard inland applications, while thickness grades align with warranty tiers and insurance mitigation incentives.
Product Type:
Material chemistry determines whether underlayment functions as a standalone moisture barrier or integrates with specialized roof systems for enhanced protection.
- Synthetic:Polypropylene and polyethylene woven substrates deliver 180-day UV exposure tolerance and lighter roll weights for steep-slope handling. Florida and Texas coastal builders specify synthetic grades to satisfy extended construction timelines without degradation.
- Self-Adhesive:Rubberized asphalt compounds with release-film backing create monolithic seals around fasteners and penetrations. Miami-Dade County mandates this technology for all new residential steep-slope construction in high-velocity hurricane zones.
- Felt:Organic substrates saturated with asphalt remain dominant in renovation channels where contractors prioritize material familiarity and lower per-square procurement cost.
- Rubberized:Modified asphalt blends with synthetic rubber additives enhance low-temperature flexibility for cold-climate ice dam protection applications.
Felt leads volumes today; synthetic is gaining share fastest.
End User:
Procurement authority shifts dramatically based on project scale and regulatory complexity, fragmenting traditional distribution pathways.
- Contractors:Steep-slope specialists in southeastern states stock premium synthetic and self-adhesive inventories to avoid inspection delays and warranty disputes. Their purchasing decisions respond directly to ASTM D226 and ASTM D6757 certification status.
- Builders:Production homebuilders in Texas Hill Country and Florida subdivisions negotiate direct mill contracts for project-specific formulations, bypassing regional distributors.
- Homeowners:Insurance loss settlements in storm-damaged regions accelerate replacement cycles, with policyholders selecting underlayment grades tied to wind mitigation premium reductions.
- Architects:Commercial and institutional project specifications increasingly require 40 mil thickness and extended UV exposure documentation for extended construction phases.
Contractors dominate current procurement volume; builders are expanding share fastest through disintermediation.
Installation Type:
Application context dictates performance thresholds, with code-mandated upgrades compressing specification cycles in coastal jurisdictions.
- New Construction:Florida Building Code wind uplift mandates and Texas coastal amendments require self-adhering underlayment on all steep-slope residential builds, eliminating felt from permitted specifications.
- Renovation:Insurance-driven re-roofing in storm-affected counties shortens traditional replacement intervals, with contractors bundling documentation services for wind mitigation credits.
- Repair:Spot remediation in Midwest markets maintains felt demand where crews resist synthetic retraining requirements and labor productivity concerns.
- Retrofitting:Wildland-urban interface counties in Texas without adopted building codes present specification opportunities for fire-resistant underlayment before municipal adoption.
New construction commands premium pricing tiers; renovation delivers the steepest volume expansion trajectory.
Thickness:
Gauge selection correlates with warranty duration, fastener retention requirements, and walkability demands during extended construction schedules.
- 30 mil:Embedded fiberglass scrim variants balance cost and performance for production homebuilders in Florida and coastal Texas with 6-month build cycles.
- 40 mil:Maximum walkability and fastener retention for commercial applications and high-wind residential zones requiring extended UV exposure tolerance.
- 15 mil:Economy-grade felt for temporary protection and repair applications where immediate shingle coverage is planned.
- 20 mil:Mid-tier synthetic grades for standard residential new construction in non-coastal jurisdictions with moderate wind exposure.
30 mil specifications anchor current volume; 40 mil is climbing the fastest as code harmonization tightens performance verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The southeastern United States concentrates the most intensive roofing underlayment specification activity globally, driven by hurricane-resistant building codes and elevated re-roofing volumes from storm damage settlements.
United States
Florida and Texas coastal counties mandate self-adhering underlayment for all new steep-slope residential construction under amended wind uplift codes. The EPA's stormwater management guidelines shape product selection criteria for moisture barrier performance. Miami-Dade and Broward counties operate as the primary testing grounds for stricter ASTM D6757 protocols.
Canada
Cold-climate ice dam protection requirements in Ontario and Quebec drive rubberized asphalt formulation demand for steep-slope installations. Health Canada guidelines influence material safety standards for polymer-based underlayment products. The Greater Toronto Area anchors synthetic underlayment distribution networks serving the broader Great Lakes region.
Germany
Energy-efficient building envelope standards under the EU Green Deal accelerate high-performance underlayment specification for residential retrofits. ECHA REACH regulations govern chemical composition of bituminous and polymer-based moisture barriers. The Rhine-Ruhr industrial corridor hosts specialized testing facilities for European wind uplift certification.
China
Rapid urbanization in the Yangtze River Delta and Pearl River Delta generates volume demand for synthetic underlayment in high-rise residential construction. GB standards under MIIT oversight establish baseline performance requirements for moisture barrier materials. Shenzhen and Shanghai municipalities pilot stricter local amendments for typhoon-resistant building envelopes.
Australia
Bushfire-prone construction zones in New South Wales and Victoria mandate fire-resistant underlayment grades for wildland-urban interface development. The Australian Building Codes Board incorporates AS/NZS standards for wind uplift and moisture protection. Sydney and Melbourne metropolitan areas concentrate specification authority for premium synthetic formulations.
Roofing Underlayment Market Vendor Landscape
Global majors compete with regional champions across manufacturing scale and specialized formulation capabilities. The market structure tilts toward consolidated production networks with tiered differentiation between premium synthetic grades and economy felt products. Three archetypes dominate: integrated building materials platforms, specialized synthetic formulators, and scale-driven asphaltic producers. Capacity expansion in hurricane-code corridors and backward integration into polymer resin supply represent the dominant competitive moves.
Within the integrated platform tier, Owens Corning and GAF Materials exemplify scale-driven positioning through captive distribution networks and bundled roofing system offerings. CertainTeed Corporation anchors the specialized formulation archetype with targeted synthetic grades for high-wind zone applications. DuPont de Nemours, Inc. occupies a distinct position leveraging material science heritage in polymer substrate development.
| Leading Market Players |
|---|
| GAF Materials |
| Owens Corning |
| DuPont de Nemours, Inc. |
| CertainTeed Corporation |
| Johns Manville |
| Carlisle Companies Inc. |
| Atlas Roofing Corporation |
| IKO Industries, Inc. |
| Tamko Building Products, Inc. |
| Others |
Supply Flow & Price Mechanics
Florida Building Code wind uplift mandates forcing self-adhesive underlayment specifications are compressing supplier response times and concentrating pricing power among mills with ASTM D6757 certification capacity. Contractors absorbing premium material costs pass through to homeowners via bundled installation services, while felt manufacturers face margin compression from asphalt feedstock volatility.
Pricing Analysis
Asphalt feedstock fluctuations in Gulf Coast refineries transmit directly into saturated felt production costs, compressing margins for non-integrated mills. Three-tier pricing structure across premium synthetic, mid-grade rubberized, and economy felt levels stratifies by certification grade and UV exposure tolerance. Pricing pressure stems from polymer resin supply constraints affecting synthetic grades. Renovation contractors in the Midwest exhibit highest price sensitivity, while production homebuilders in Florida accept premium positioning for code compliance assurance.
Supply Chain Analysis
Freight costs from polymer resin producers in Texas and Louisiana to underlayment mills in the southeastern United States anchor landed cost structures for synthetic grades. Manufacturing concentrates in the United States, Canada, and China, with raw material sourcing drawing from Gulf Coast asphalt refineries, polypropylene producers, and synthetic rubber suppliers. Single-source vulnerability runs through regional distributors controlling Baltimore-to-Atlanta throughput. Distribution runs through contractor-focused suppliers and direct mill contracts with national builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roofing underlayment procurement patterns favor geographic arbitrage between hurricane-code coastal zones requiring premium self-adhesive grades and inland markets where felt familiarity sustains lower-cost positioning. The regulatory differential between Florida's mandatory wind uplift specifications and Texas Hill County's unincorporated code gaps creates divergent margin profiles.
For Market Incumbents: Cement specification authority in Miami-Dade and Broward counties by accelerating ASTM D6757 certification investments ahead of harmonized ICC adoption. Defend against disintermediation threats from direct mill contracts by deepening contractor app platforms with same-day delivery guarantees. Capacity addition in Texas coastal corridors captures production homebuilder volume shifts.
For New Entrants and Emerging Players: Begin with wildland-urban interface counties in Texas lacking adopted building codes, where fire-resistant formulation specification precedes municipal adoption. Target renovation channels in storm-damaged southeastern states where insurance loss settlements accelerate replacement cycles. Go-to-market leverage centers on bundling wind mitigation documentation services with installation training.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized synthetic formulators holding proprietary polymer substrate technology and established high-wind zone certification. Long-term viability hinges on backward integration into polymer resin supply and captive distribution networks. Signal to monitor: ASTM D6757 certification backlog resolution rates as inflection indicator for regional launch capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Owens Corning and GAF Materials secure captive feedstock for synthetic grades against Gulf Coast refinery volatility. |
| Direct-to-Roofer Digital Platform Launch | Regional distributors bypass lumberyard intermediaries with contractor apps enabling same-day delivery scheduling. |
| ASTM D6757 Certification Acceleration | Manufacturers clear 12-week testing lab queues to unlock Miami-Dade County specification eligibility. |
| Fire-Resistant Formulation Development | Specialized producers establish specification in Texas Hill Country wildland-urban interface before code adoption. |
| Wind Mitigation Documentation Services | Contractors bundle Florida My Safe Florida Home credit paperwork with premium underlayment installation. |
Methodological Framework
Direct dialogue with roofing contractors, production homebuilder procurement directors, regional distribution channel managers, and ASTM International technical committee members grounded qualitative findings. Secondary validation drew from ICC model code adoption tracking, EPA stormwater management guideline updates, Florida Building Code amendment records, and insurance industry loss mitigation program documentation. Bottom-up volume estimates triangulated against top-down construction spending allocations across residential re-roofing and new construction segments.
Bottom-up modeling aggregated product-type, end-user, installation-type, and thickness-grade volumes across the projection horizon. Top-down cross-checks applied construction spending elasticities and roofing square footage coefficients. CAGRs derived from segment-level growth drivers including code mandate adoption curves, insurance settlement patterns, and material substitution dynamics. Industry-specific inputs incorporated ASTM D226 and D6757 standard revision timelines and hurricane-season damage frequency assumptions.
Caveats apply where third-party testing lab capacity constraints, refinery output disruptions, or code harmonization delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Steel Casing Pipes Market
Building & Construction Materials
Bed Headwall Systems Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
India Ready-Mix Concrete Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market