
 Construction Machinery Telematics Market | 2026-2036
Construction Machinery Telematics Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Machinery Telematics Market Outlook
Cellular connectivity modules are replacing satellite-only hardware configurations and is restructuring total cost structures for fleet operators. Caterpillar Inc leverages its dealer network density to sustain aftermarket telematics attachment rates across North American mining corridors. Komatsu Ltd anchors its Smart Construction platform with machine learning diagnostics that differentiate uptime guarantees in Japanese and Australian quarry markets. Verizon Connect competes on software stack openness, allowing third-party fleet management integrations that extend platform utility beyond single-OEM environments.
Construction machinery telematics encompasses GPS tracking, sensor integration, and data analytics systems installed on excavators, loaders, and haulers to transmit operational parameters including engine hours, fuel burn, hydraulic pressure, and geofence breaches to centralized platforms. These systems enable remote equipment monitoring, theft recovery, and predictive maintenance scheduling across dispersed job sites where physical supervision proves impractical. Fleet management applications currently dominate value capture given rental company requirements for utilization optimization and billing accuracy, while predictive maintenance segments show the fastest structural expansion as OEMs bundle telematics with extended warranty programs. Cloud-based deployment architectures command margin concentration due to recurring subscription economics and lower incremental delivery costs compared with on-premises installations requiring localized server infrastructure.
The EPA's Tier 4 Final emissions enforcement and the EU's Stage V non-road regulations shape product design by mandating onboard diagnostic data logging that telematics platforms must transmit for compliance audits. Japan's MLIT construction machinery safety standards and the FCC's broadband spectrum allocations for IoT further determine hardware certification requirements and communication protocol availability across major supply markets. Stakeholders must monitor evolving cybersecurity mandates for connected heavy equipment as regulatory bodies in multiple jurisdictions draft incident reporting obligations and encryption standards that will reshape platform architecture investments and vendor qualification criteria.
Market Dynamics
Cellular connectivity modules are restructuring fleet operator economics by displacing satellite-only hardware configurations and collapsing per-unit data transmission costs across dispersed job sites. This connectivity shift is concentrating margin capture among platform providers while fragmenting hardware vendor positions.
Growth Catalysts
- EU Stage V emissions standards:Mandatory onboard diagnostic data logging for non-road machinery is accelerating OEM bundling of telematics with extended warranty programs. Fleet operators in Germany and France face compliance audit requirements that telematics platforms satisfy.
- Earthmoving equipment fleets:Contractors managing excavators and loaders are prioritizing fuel efficiency optimization and uptime guarantees. Equipment rental companies in Japan and the United States require utilization tracking for billing accuracy.
- Machine learning diagnostics:Predictive maintenance algorithms are reducing unplanned downtime in quarry and mining operations. Australian and Japanese markets show concentrated deployment of AI-enabled failure prediction systems.
Market Restraints
- Semiconductor supply concentration:Cellular modem and GPS chipset fabrication concentrates in East Asian foundries, exposing telematics hardware vendors to input cost volatility and allocation constraints.
- Cybersecurity compliance friction:Evolving encryption standards and incident reporting obligations under draft regulations in multiple jurisdictions are extending platform certification timelines.
- Legacy fleet integration costs:Retrofitting pre-2015 construction equipment with compatible sensor arrays and communication modules requires substantial capital expenditure per unit.
Strategic Opportunities
- Indian infrastructure renewal:Central government capital expenditure programs for highways and urban transit are creating concentrated deployment opportunities for telematics-enabled fleet management.
- Cloud-native platform architectures:Subscription economics and lower incremental delivery costs compared with on-premises installations are capturing margin concentration among software-first vendors.
- 5G IoT spectrum allocation:FCC broadband spectrum designations for industrial IoT are enabling real-time video diagnostics and remote equipment control in North American mining corridors.
Industry Challenges
- Embedded systems engineering talent scarcity:Shortage of firmware developers with heavy equipment sensor integration experience is constraining OEM in-house platform development timelines.
- Multi-OEM data standardization delays:Proprietary telematics protocols from major equipment manufacturers prevent unified fleet dashboards, forcing rental operators to maintain fragmented software environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Machinery Telematics Market |
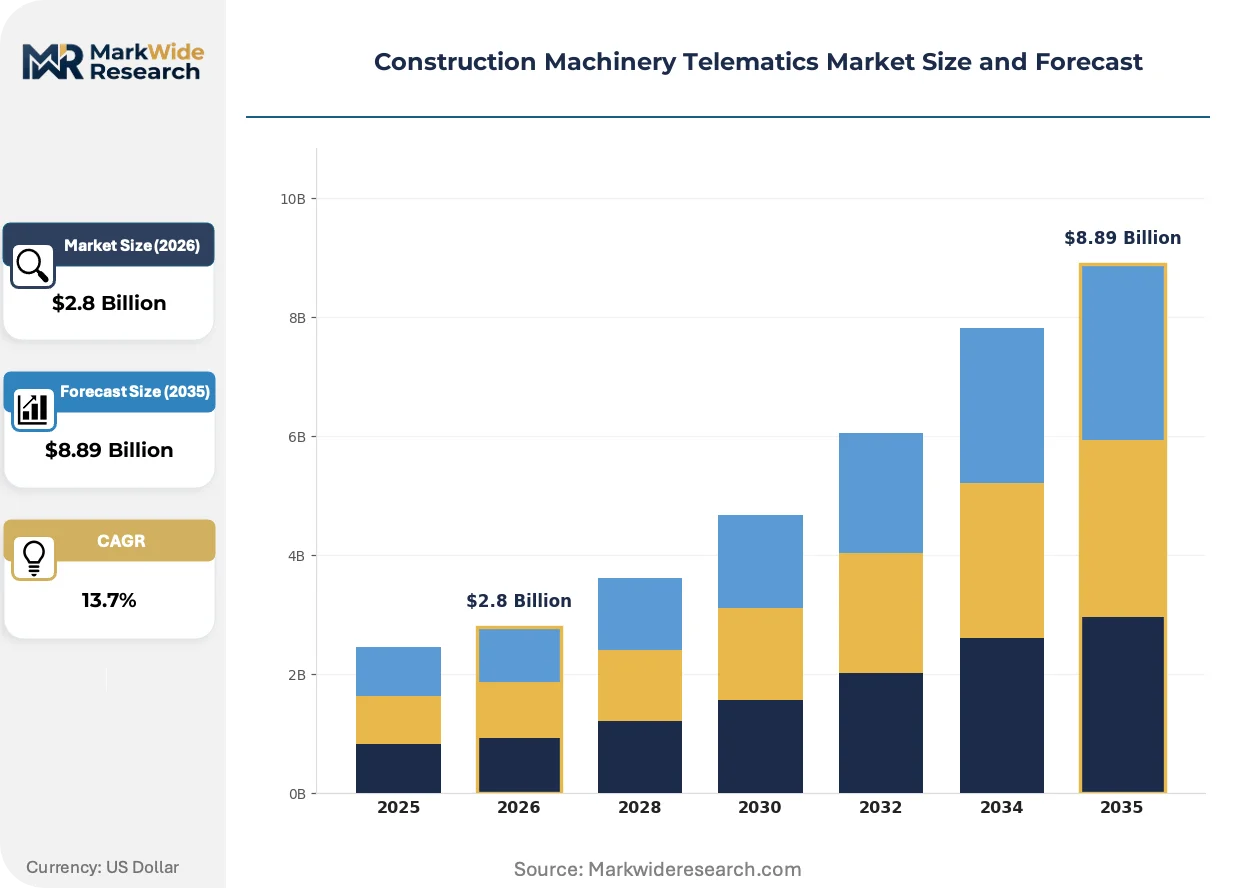
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: GPS Tracking, Data Analytics, Remote Monitoring, Sensor Integration Application: Fleet Management, Equipment Monitoring, Predictive Maintenance, Asset Optimization End User: Contractors, Rental Companies, Construction Firms, Equipment Manufacturers Deployment: On-premises, Cloud-based, Hybrid, Mobile Solutions |
| Companies Covered | Volvo Construction Equipment, Hitachi Construction Machinery, Caterpillar Inc, Liebherr Group, Kubota Corporation, Komatsu Ltd, CNH Industrial, Verizon Connect, John Deere, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Machinery Telematics Market Strategic Shifts
Edge computing architectures are relocating data processing from centralized cloud servers to onboard machinery controllers, compressing latency for real-time safety interventions and enabling autonomous operation pilots in controlled environments.
Multi-protocol sensor fusion is integrating hydraulic pressure transducers, engine telemetry modules, and geolocation arrays into unified hardware stacks. Large mining contractors in Western Australia are deploying these integrated systems at scale. The technology is integrating vibration analysis and fuel consumption monitoring into single-platform uptime optimization, collapsing the vendor stack that previously required separate subscriptions.
Japan's MLIT construction machinery safety standards are mandating remote monitoring capabilities for equipment above specified weight thresholds. OEMs serving the Japanese domestic market must certify platforms for encrypted data transmission and fail-safe communication protocols. Quarry operators in Hokkaido and Kyushu are responding by accelerating fleet replacement cycles to meet compliance deadlines.
Rental companies are unbundling telematics subscriptions from base equipment rates and pricing connectivity as a separate line item. Equipment lessors in Germany and the United States are adopting this model to improve margin transparency and capture recurring software revenue. This shift is most visible among multi-brand rental fleets where platform-agnostic telematics providers compete on integration flexibility.
Construction Machinery Telematics Market Segmentation
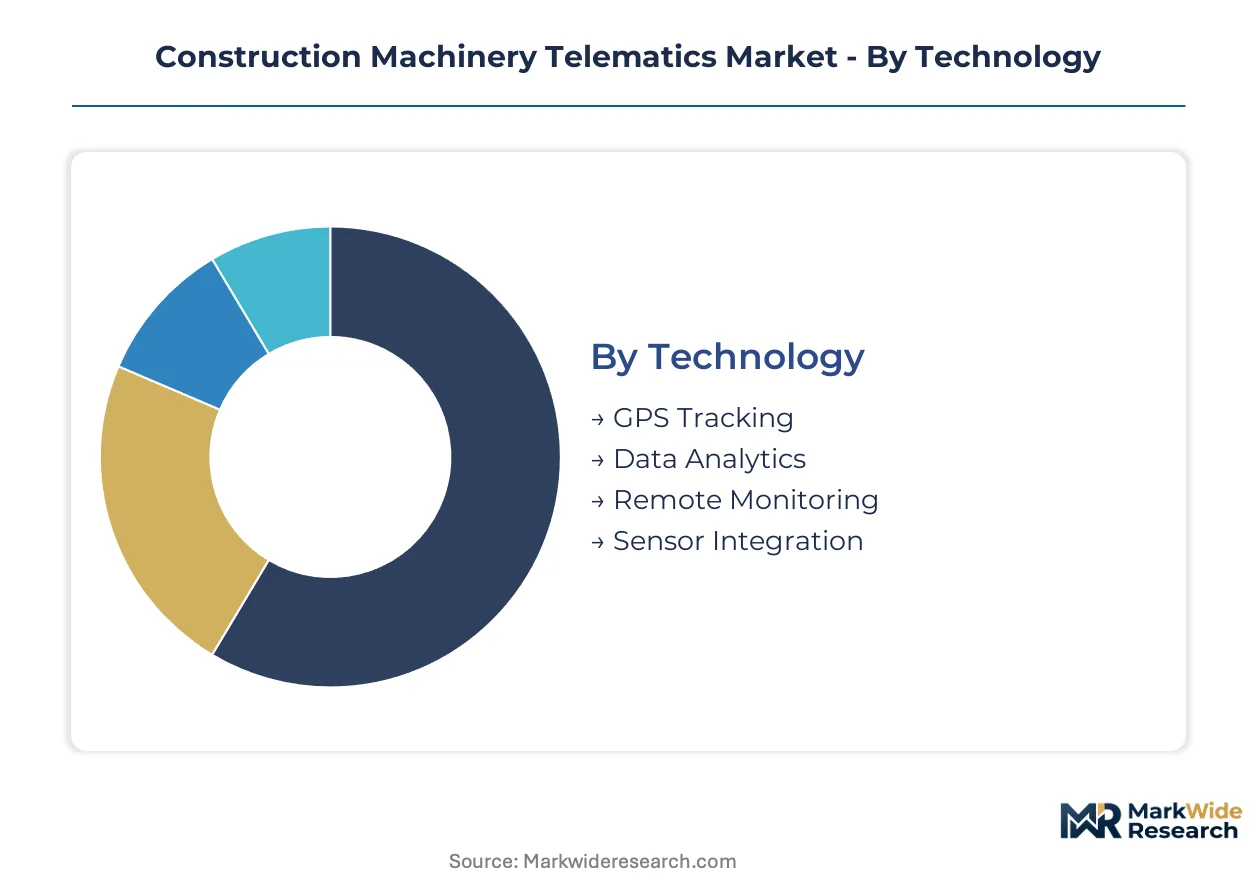
Telematics adoption patterns diverge sharply across technology maturity and operational use cases. Fleet operators prioritize connectivity architectures that minimize retrofit costs while maximizing data utility across dispersed job sites.
Technology:
Equipment replacement cycles determine which connectivity layers operators can justify installing on new versus legacy fleets.
- GPS Tracking:Satellite and cellular triangulation modules provide location verification, geofence enforcement, and theft recovery. German rental fleets mandate GPS logging for insurance compliance, driving concentrated deployment across earthmoving equipment.
- Data Analytics:Cloud-based processing engines transform raw sensor streams into utilization dashboards and fuel efficiency benchmarks. Japanese quarry operators leverage these platforms to optimize haul cycle timing and reduce idle hours.
- Remote Monitoring:Real-time parameter transmission enables off-site diagnostics and operator coaching. Australian mining contractors deploy these systems to supervise equipment across remote Pilbara sites.
- Sensor Integration:Multi-protocol hardware stacks consolidate hydraulic pressure, engine telemetry, and vibration data. Integration complexity limits adoption to OEM factory installations and large fleet retrofits.
GPS Tracking sits at the top of the volume ranking, with Data Analytics climbing the fastest.
Application:
Software procurement decisions follow distinct budget approval pathways depending on whether the use case reduces operating expense or generates incremental revenue.
- Fleet Management:Utilization tracking, maintenance scheduling, and billing automation dominate rental company procurement. United States equipment lessors require these platforms to manage multi-brand deployments across state lines.
- Predictive Maintenance:Machine learning models forecast component failures from vibration and thermal patterns. Japanese OEMs bundle these capabilities with extended warranty programs to differentiate service contracts.
- Equipment Monitoring:Real-time alerts for engine faults, hydraulic leaks, and operator safety violations. German contractors deploy these systems to satisfy EU Stage V emissions audit requirements.
- Asset Optimization:Cross-fleet dispatch algorithms match machine specifications to job site requirements. Large infrastructure contractors in India pilot these tools for highway construction coordination.
Fleet Management commands the largest installed base, while Predictive Maintenance shows the steepest expansion trajectory.
End User:
Procurement authority concentrates differently across organizational structures, with rental companies wielding disproportionate platform selection influence.
- Rental Companies:Multi-brand fleets require platform-agnostic telematics to unify billing and maintenance across OEM silos. German and United States lessors lead adoption of subscription-unbundled pricing models.
- Contractors:Project-based operators prioritize theft recovery and fuel monitoring over advanced analytics. Japanese earthmoving specialists drive demand for MLIT-compliant remote monitoring.
- Construction Firms:Large integrated builders negotiate OEM telematics bundles with new equipment purchases. Australian infrastructure developers mandate connected equipment for remote site supervision.
- Equipment Manufacturers:OEMs embed telematics as standard features to capture recurring service revenue and warranty compliance data. Factory integration reduces per-unit installation costs versus aftermarket retrofit.
Rental Companies sit at the top of the volume ranking, with Equipment Manufacturers climbing the fastest.
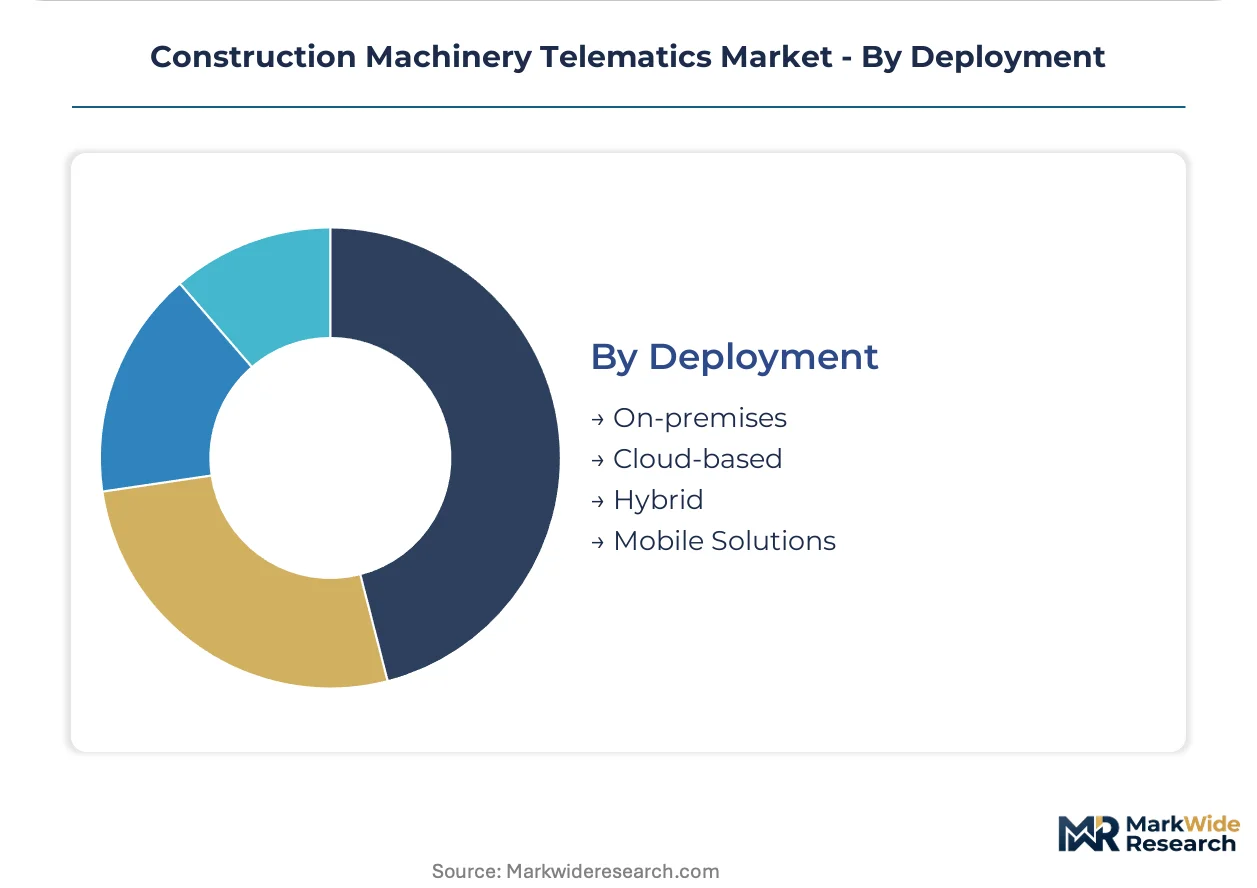
Deployment:
Total cost of ownership calculations favor architectures that eliminate on-site server maintenance and accelerate software update delivery.
- Cloud-based:Subscription economics and centralized data lakes enable predictive analytics at scale. Margin concentration attracts software-first vendors competing against OEM captive platforms.
- Hybrid:Edge processing for latency-critical safety functions with cloud aggregation for longitudinal analysis. Mining operators in Western Australia deploy these architectures for autonomous haulage pilots.
- On-premises:Localized server infrastructure satisfies data sovereignty requirements in regulated industries. High incremental delivery costs limit adoption to security-sensitive government contractors.
- Mobile Solutions:Smartphone-dependent interfaces reduce hardware costs for small fleet operators. Limited sensor integration constrains functionality to location tracking and basic alerts.
Cloud-based deployment sits at the top of the volume ranking, with Hybrid architectures climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial machinery corridor concentrates telematics deployment for emissions compliance and rental fleet optimization. Contractors across Bavaria and North Rhine-Westphalia negotiate OEM bundles that embed connectivity as standard factory equipment.
Germany
Earthmoving contractors in Bavaria prioritize fuel efficiency tracking for excavator fleets. The EU Stage V emissions standards mandate onboard diagnostic data logging that telematics platforms transmit for compliance audits. Rental companies in Munich and Stuttgart deploy unified fleet dashboards across multi-brand equipment pools.
United States
Infrastructure renewal programs in Texas and California drive concentrated telematics procurement for highway construction coordination. The EPA Tier 4 Final enforcement requires diagnostic data transmission for emissions verification. Mining contractors across the Mountain West deploy remote monitoring for dispersed Pilbara-equivalent site supervision.
Japan
Quarry operators in Hokkaido and Kyushu accelerate fleet replacement to meet MLIT construction machinery safety standards. The country's remote monitoring mandates for equipment above weight thresholds reshape OEM platform certification requirements. Smart Construction platforms with machine learning diagnostics differentiate service contracts in Kansai and Chubu industrial zones.
Australia
Western Australian mining contractors deploy integrated sensor fusion systems at scale across autonomous haulage pilots. The country's concentrated iron ore extraction operations demand real-time parameter transmission for remote site supervision. Perth-based fleet operators negotiate predictive maintenance bundles that reduce unplanned downtime in Pilbara corridor operations.
India
Central government capital expenditure for highways and urban transit creates deployment opportunities in Maharashtra and Gujarat. The country's infrastructure renewal programs concentrate telematics procurement among large integrated construction firms. Contractors in Delhi-NCR pilot cross-fleet dispatch algorithms for equipment coordination across dispersed job sites.
Construction Machinery Telematics Market Competitive Environment
Global majors compete with regional champions across platform architecture and dealer network density. The vendor structure organizes around OEM captive platforms, independent software providers, and telecommunications carriers with industrial IoT divisions. Three archetypes dominate: integrated equipment manufacturers bundling telematics with new sales, software-first vendors competing on API openness, and connectivity specialists leveraging spectrum access for data transmission economics. Competitive moves concentrate on strategic partnerships between hardware vendors and cloud infrastructure providers, plus vertical integration of sensor manufacturing to secure semiconductor supply.
Within the integrated equipment manufacturer tier, Caterpillar Inc and Komatsu Ltd exemplify archetypes that embed telematics as standard factory features. Caterpillar leverages its North American dealer network density to sustain aftermarket attachment rates across mining corridors. Komatsu anchors its platform with machine learning diagnostics that differentiate uptime guarantees in Japanese and Australian quarry markets. Among independent software providers, Verizon Connect occupies a position competing on stack openness that allows third-party fleet management integrations beyond single-OEM environments.
| Leading Market Players |
|---|
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Caterpillar Inc |
| Liebherr Group |
| Kubota Corporation |
| Komatsu Ltd |
| CNH Industrial |
| Verizon Connect |
| John Deere |
| Others |
Value Chain & Pricing Dynamics
Silicon wafer spot indices cascading from East Asian foundries compress hardware margins for cellular modem assemblies and GPS chipsets, forcing telematics vendors to stratify subscription tiers around data throughput volumes and sensor integration depth. OEMs absorbing these input shocks bundle connectivity as factory-standard features to capture recurring service revenue, while aftermarket providers compete on retrofit economics for legacy fleet segments.
Pricing Analysis
Input-cost pass-through from semiconductor fabrication runs through subscription pricing tiers, with cellular module shortages elevating hardware attachment costs for independent platform providers. Three-tier pricing structure across premium, standard, and economy levels separates OEM-integrated factory installations from dealer-network retrofits and self-install cellular dongles. Price differentiation rests on sensor fusion complexity and MLIT-compliant encryption certification. Cost compression in economy-tier hardware is intensifying because rental fleet operators negotiate volume-scale procurement contracts. Small contractor segments show highest price sensitivity, deferring predictive maintenance upgrades until warranty expiration.
Supply Chain Analysis
Regional distribution centers in Singapore, Rotterdam, and Los Angeles anchor hub-and-spoke patterns for cellular modem and GPS chipset inventory, with final assembly concentrating in Taiwan, South Korea, and Vietnam. Hardware stacks draw from semiconductor foundries, lithium-ion cell manufacturers, and ruggedized enclosure fabricators. Single-source vulnerability in cellular baseband processor supply exposes vendors to allocation constraints during demand surges. Distribution runs through OEM captive dealer networks for factory-integrated units, while independent providers leverage direct-to-fleet e-commerce channels and third-party installer partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
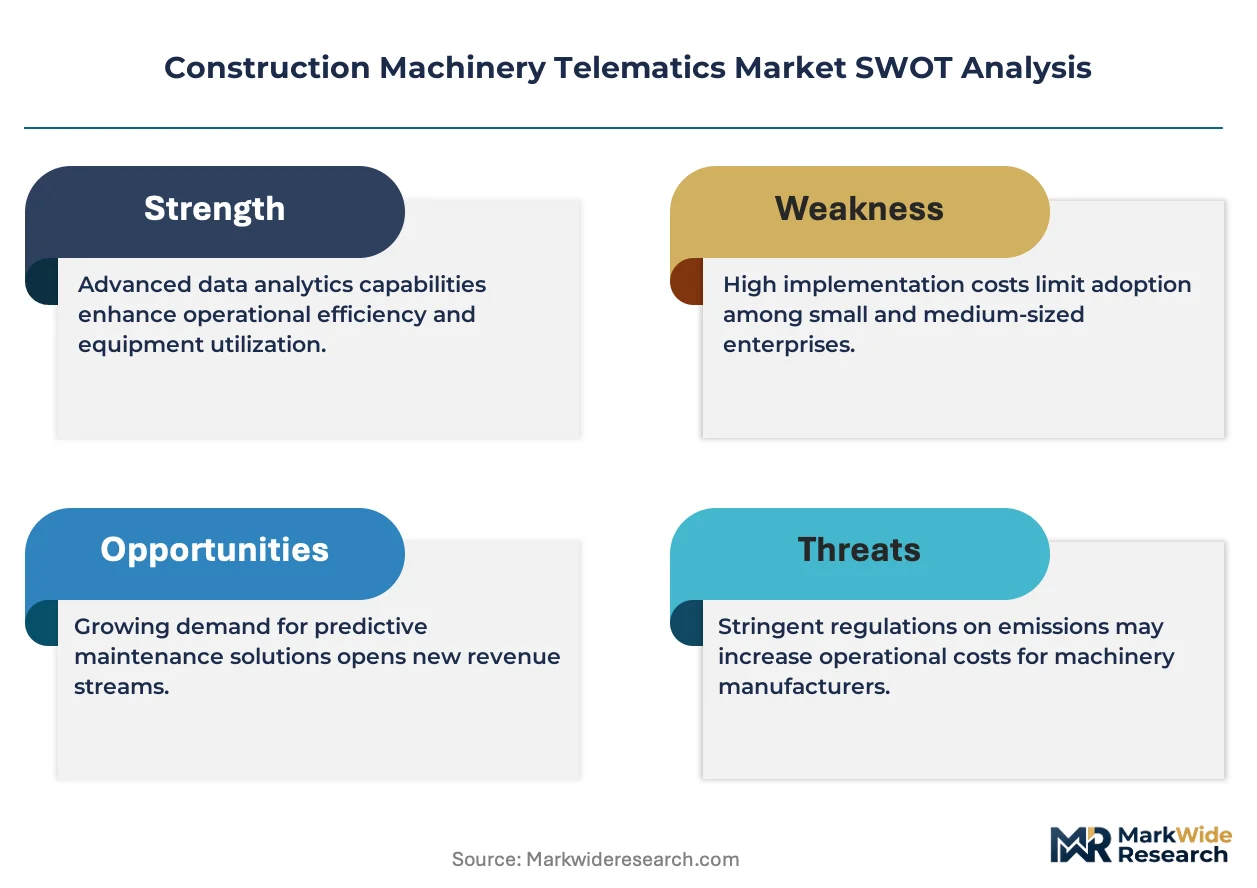
The EU Stage V compliance cost differential against Japanese MLIT certification requirements creates arbitrage opportunities for platform vendors optimizing certification investment across regulatory clusters. Fleet operators in Germany face stricter audit documentation burdens than Australian mining contractors, shifting procurement authority toward software-first vendors with multi-jurisdictional compliance architectures.
For Market Incumbents: Anticipate margin erosion from software-first entrants by deepening backward integration into sensor manufacturing and securing captive semiconductor allocation agreements. Prioritize certification investment for emerging cybersecurity mandates in multiple jurisdictions. Defensive consolidation through dealer network exclusivity agreements in North American mining corridors protects aftermarket attachment rates against platform-agnostic competitors.
For New Entrants and Emerging Players: API-first distribution channels bypass OEM captive salesforces and reach multi-brand rental fleets through direct integration partnerships. White-space targets include Indian highway construction coordination tools and small-fleet mobile solutions with smartphone-dependent interfaces. The most penetrable segment sits with mid-size earthmoving contractors in Germany seeking Stage V compliance without full OEM platform commitment. Go-to-market execution emphasizes subscription-unbundled pricing transparency against bundled OEM offerings.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platform providers with demonstrated API ecosystem traction and recurring revenue concentration. Long-term viability over the projection horizon favors vendors controlling edge-computing firmware stacks rather than hardware-dependent installation businesses. Acquisition target archetype: software-first vendors with multi-OEM integration capabilities and established rental fleet customer relationships. The signal to watch is 5G IoT spectrum auction participation indicating industrial IoT commitment depth among telecommunications carriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Architecture Deployment | Onboard data processing reduces latency for autonomous haulage pilots in Western Australian mining corridors. |
| API Ecosystem Expansion | Third-party fleet management integrations extend platform utility beyond single-OEM rental environments. |
| Semiconductor Supply Agreement | Cellular modem allocation security protects hardware margins against foundry capacity constraints. |
| Cybersecurity Certification Investment | Encryption standard compliance accelerates platform qualification for draft EU incident reporting mandates. |
| Multi-Protocol Sensor Fusion Integration | Unified hardware stacks collapse vendor complexity for large mining contractors deploying at scale. |
Study Parameters
Direct dialogue with fleet operations directors, OEM telematics product managers, cellular carrier IoT specialists, and rental company procurement leads grounded qualitative findings in operational constraints and purchasing authority patterns. Secondary validation drew from EPA enforcement documentation, EU Stage V regulatory filings, FCC spectrum allocation records, and Japanese MLIT safety standard certifications. Bottom-up equipment installation estimates and top-down subscription revenue aggregation triangulated market sizing across deployment models.
Segment-level projections across technology layers, application use cases, end-user archetypes, and deployment architectures structured the analytical framework throughout the forecast period. CAGRs derived from equipment replacement cycle timing, regulatory compliance deadline clustering, and cellular connectivity adoption curves in target geographies. Industry-specific inputs included mining contractor fleet utilization benchmarks, rental company billing automation penetration rates, and OEM warranty bundling contract structures.
Semiconductor supply disruption, cybersecurity mandate acceleration, and infrastructure program funding volatility are the dominant revision risks that could compress or extend adoption timelines. Forecasts reflect documented assumptions around equipment replacement rates and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Wire Mesh Welding Machines Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Hydraulic Rotary Drilling Rig Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market