
 US Cement Tiles Market | 2026-2036
US Cement Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
US Cement Tiles Market Outlook
Skilled artisan availability is unwinding manufacturing capacity expansion across the US cement tiles industry. Original Mission Tile sustains its position through deep vertical integration into hand-pouring operations. Granada Tile leverages proprietary color-mixing techniques to differentiate its portfolio. Arizona Tile controls distribution through an extensive network of design-center showrooms in the Southwest.
US cement tiles are hydraulically pressed concrete products composed of Portland cement, fine aggregates, and mineral pigments, typically measuring eight inches square and cured under water to develop structural density. These tiles serve primarily as decorative surfacing materials for interior floors, exterior patios, and vertical wall applications where moisture resistance and design flexibility outweigh the cost of natural stone. Hexagonal and custom shapes capture expanding specification interest from commercial designers seeking geometric visual impact. Residential flooring remains the dominant application channel, though decorative walls represent the fastest-growing segment as open-concept interiors emphasize accent surfaces. Traditional styling occupies the largest share of current installations, while modern aesthetics are gaining traction in urban multifamily developments.
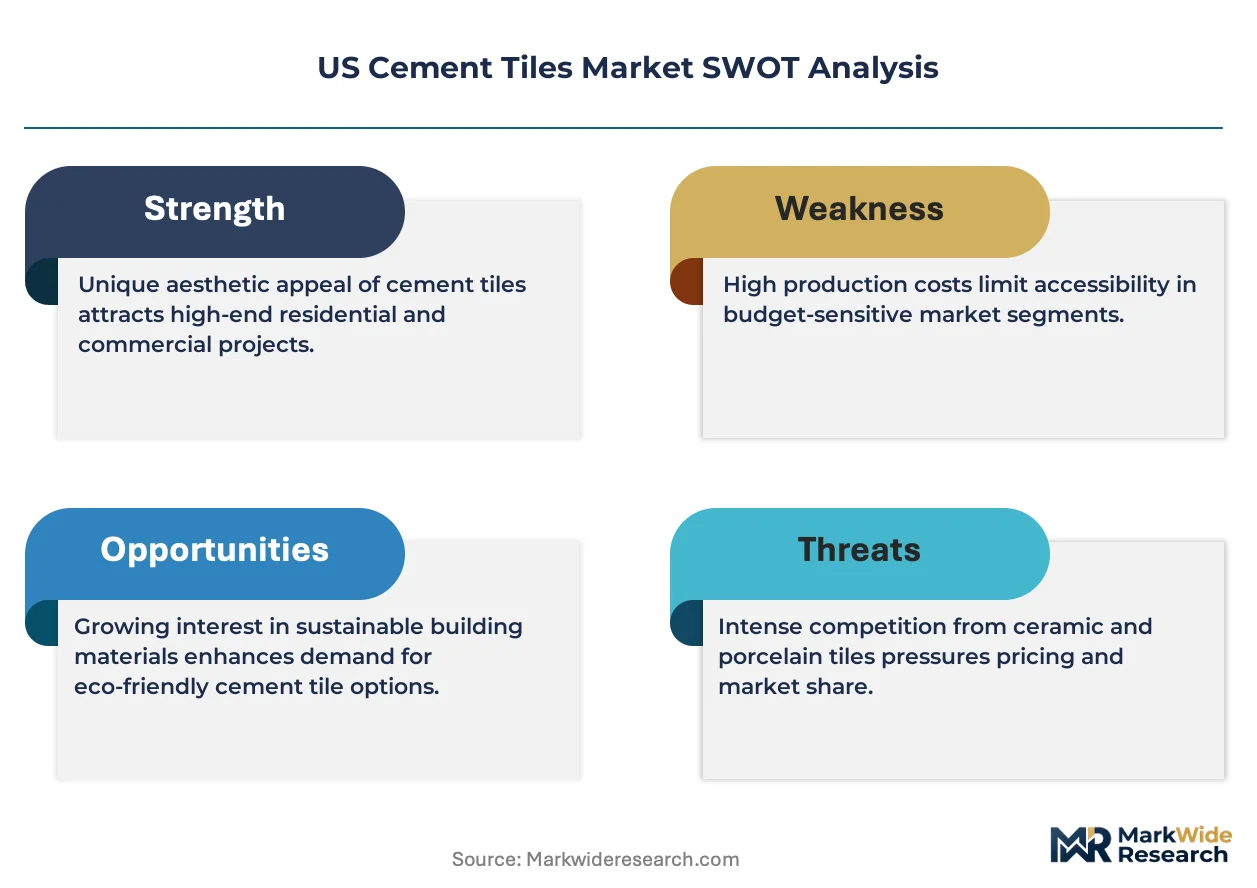
EPA regulations on volatile organic compound emissions directly constrain the solvent-based sealants and adhesives paired with cement tile installations. OSHA workplace safety standards govern silica dust exposure during cutting and grinding operations, elevating capital requirements for fabrication shops. The FTC Green Guides shape how manufacturers communicate sustainability claims about recycled content and local sourcing. Stakeholders must monitor evolving state-level building codes in California and Florida that increasingly reference embodied carbon thresholds for interior finish materials.
Market Dynamics
Skilled artisan scarcity is constraining US cement tile manufacturing capacity expansion, forcing producers to choose between automation investment and authentic hand-pouring heritage. EPA VOC regulations are simultaneously reshaping sealant pairing requirements and installation protocols.
Growth Catalysts
- Luxury Residential Construction:Design-forward homebuilding in California, Texas, and Florida metropolitan corridors is pulling specification volume for decorative flooring and accent walls.
- EPA Indoor Air Quality Standards:Stricter VOC emission limits on interior finish materials are favoring cement tiles over synthetic alternatives in certified green building projects.
- Geometric Specification Interest:Commercial designers specifying hexagonal and custom shapes for visual impact are expanding addressable surface area per project.
Market Restraints
- Portland Cement Price Volatility:Energy-intensive clinker production and carbon pricing exposure create input cost instability that compresses fabricator margins.
- Artisan Labor Concentration:Hand-pouring expertise clusters in specific regional craft communities, limiting geographic scalability of authentic production.
- Natural Stone Substitution:Travertine and porcelain alternatives with lower installation complexity capture price-sensitive specification decisions.
Strategic Opportunities
- Embodied Carbon Thresholds:California and Florida state building codes referencing interior finish carbon intensity create first-mover positioning for low-carbon formulation.
- Decorative Wall Applications:Open-concept interior design emphasizing vertical accent surfaces opens faster-growing specification channel than traditional flooring.
- Design-Center Distribution:Direct-to-specifier showroom networks bypass traditional distributor markup and capture higher-margin project involvement.
Industry Challenges
- Silica Dust Compliance:OSHA workplace exposure standards for cutting and grinding operations elevate capital requirements for fabrication shop ventilation and PPE systems.
- FTC Green Claims Scrutiny:Sustainability marketing around recycled content and local sourcing faces heightened enforcement risk under updated Green Guides.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Cement Tiles Market |
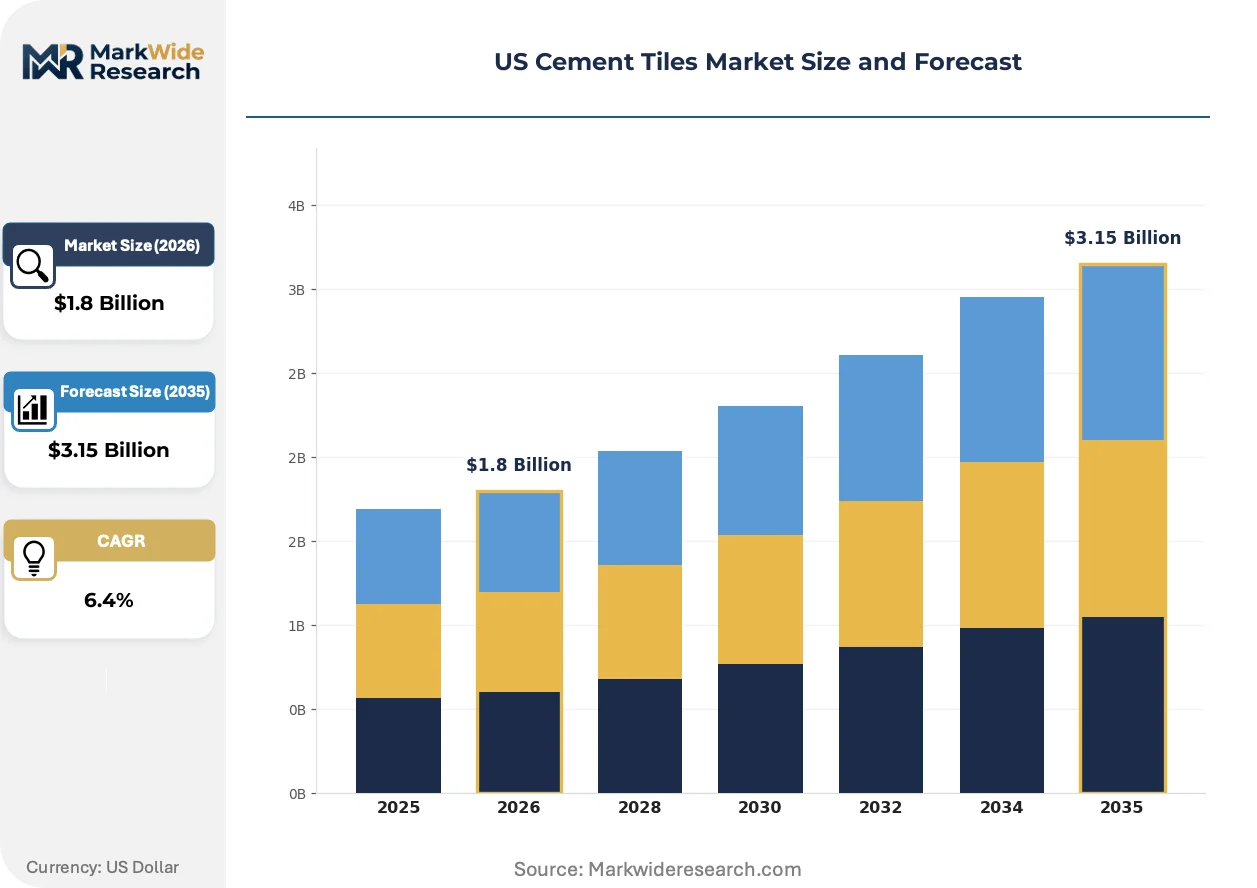
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hexagonal, Square, Rectangular, Custom Shapes Application: Residential Flooring, Commercial Flooring, Outdoor Spaces, Decorative Walls Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Style: Traditional, Modern, Vintage, Artistic |
| Companies Covered | Granada Tile, Sabine Hill, Original Mission Tile, Villa Lagoon Tile, Arizona Tile, Florida Tile, Mosaic del Sur, CemTile Industries, Lili Cement Tile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Cement Tiles Market Strategic Shifts
Digital color-matching systems and water-based sealant chemistry are converging to reshape how US cement tile producers balance artisan authenticity with scalable quality consistency.
Water-based penetrating sealants formulated without aromatic solvents are displacing traditional solvent-based topical coatings in commercial and residential installations. High-end multifamily developers in urban corridors are specifying these systems to meet LEED v4.1 interior air quality prerequisites. The shift is compressing margins for sealant suppliers locked into legacy petrochemical formulations while rewarding coating innovators with compliant chemistry pipelines.
EPA enforcement of TSCA Section 6 restrictions on formaldehyde-emitting composite wood products is tightening adjacent interior finish specifications. Cement tile producers benefit as specifiers seek non-emitting alternatives for wet areas and high-humidity zones. California Air Resources Board (CARB) Phase 2 compliance documentation now routinely accompanies tile submittals for state-funded institutional projects.
Designers are consolidating specification authority through direct mill relationships rather than distributor intermediaries. Boutique hospitality and restaurant clients in Miami, Los Angeles, and Austin are sourcing custom colorways through showroom appointments with production managers. The channel compression rewards producers with captive design-center footprints and penalizes those dependent on third-party dealer networks for project visibility.
US Cement Tiles Market Segmentation
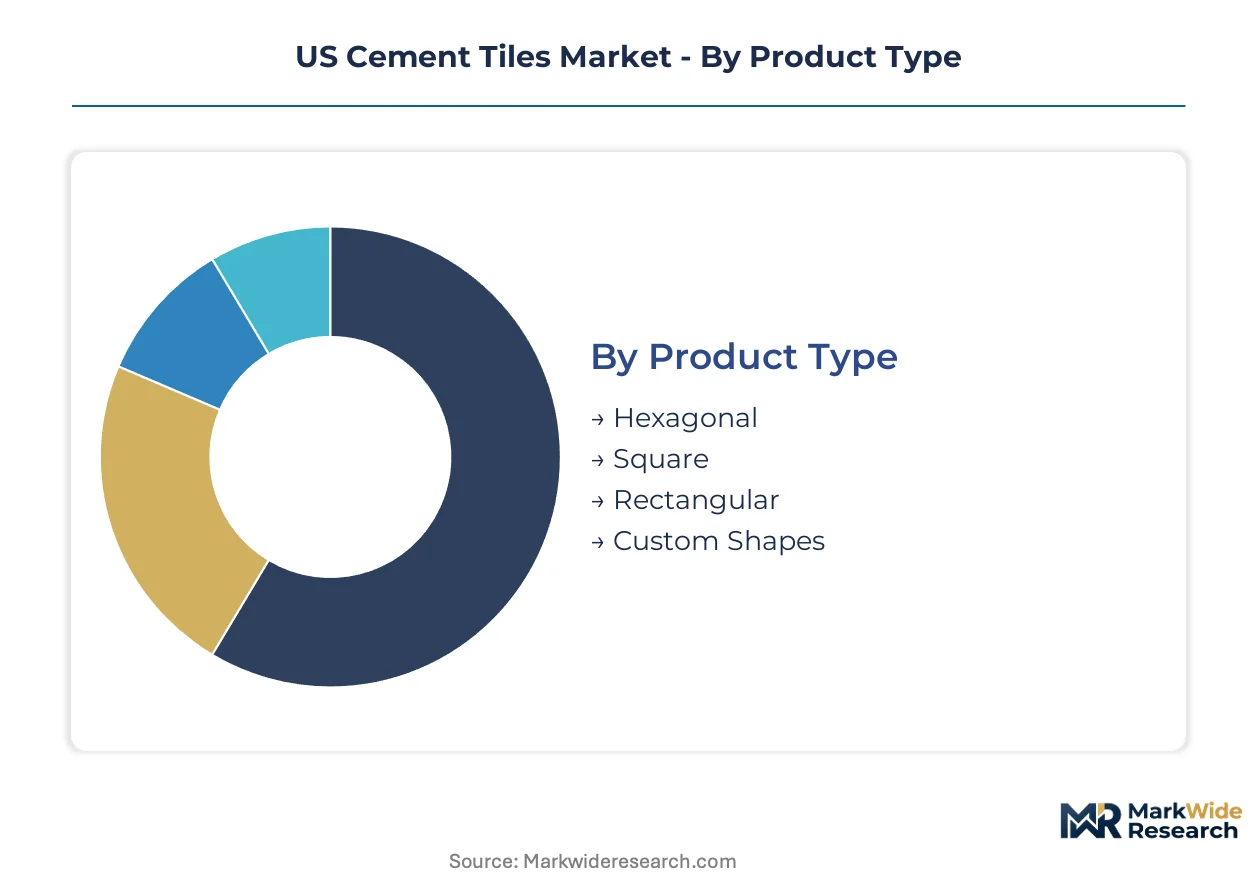
Cement tile producers segment their portfolios to match specification authority with fabrication capability. Product geometry, installation environment, and aesthetic positioning each create distinct margin profiles and customer acquisition costs.
Product Type:
Domestic demand concentrates on domestically fabricated square formats, while export-oriented producers push hexagonal and custom geometries toward international hospitality specification.
- Square:The eight-inch square format dominates residential flooring specifications due to modular installation efficiency and lower waste rates. California and Florida luxury homebuilders specify this geometry for cost-predictable large-format installations.
- Hexagonal:Six-sided tiles create visual complexity for commercial designers seeking geometric impact. Austin, Miami, and Los Angeles hospitality projects drive specification volume for this higher-fabrication-complexity format.
- Rectangular:Plank-format tiles suit linear spatial layouts in contemporary multifamily developments.
- Custom Shapes:Bespoke geometries serve boutique restaurant and retail clients requiring brand-specific visual identity.
Square formats hold the largest share; momentum sits with hexagonal specifications.
Application:
Cost tier separation is pronounced: flooring applications command premium installation labor and sealant chemistry, while wall applications run thinner material profiles with lower structural load requirements.
- Residential Flooring:Interior floor surfaces in luxury single-family construction require highest-density hydraulic pressing and moisture-resistant curing. Texas and Florida metropolitan corridors concentrate demand for this application channel.
- Decorative Walls:Vertical accent surfaces in open-concept interiors use lighter-weight tile bodies with enhanced pigment saturation. Commercial designers in California specify these for visual impact without foot-traffic durability requirements.
- Commercial Flooring:High-traffic retail and hospitality installations demand enhanced abrasion resistance and slip-resistant surface treatments.
- Outdoor Spaces:Patio and pool deck applications require freeze-thaw resistant formulations and UV-stable colorants for exposed conditions.
Residential flooring retains volume leadership; decorative walls are climbing the fastest.
Distribution Channel:
Volume concentration favors wholesale and direct sales to large developers, while margin capture concentrates in design-center direct relationships with boutique specifiers.
- Direct Sales:Producer-to-specifier relationships bypass distributor markups and enable custom colorway development. Arizona Tile's showroom network exemplifies this channel's margin advantages.
- Wholesale:Volume contractors and regional flooring retailers source through distributor intermediaries for standardized product lines and predictable lead times.
- Retail Stores:Big-box and specialty flooring retailers serve renovation-driven homeowners with limited custom capability.
- Online Platforms:Digital specification tools support remote color-matching and sample ordering for geographically dispersed design firms.
Wholesale channels dominate volume; direct sales gain share fastest among premium producers.
Style:
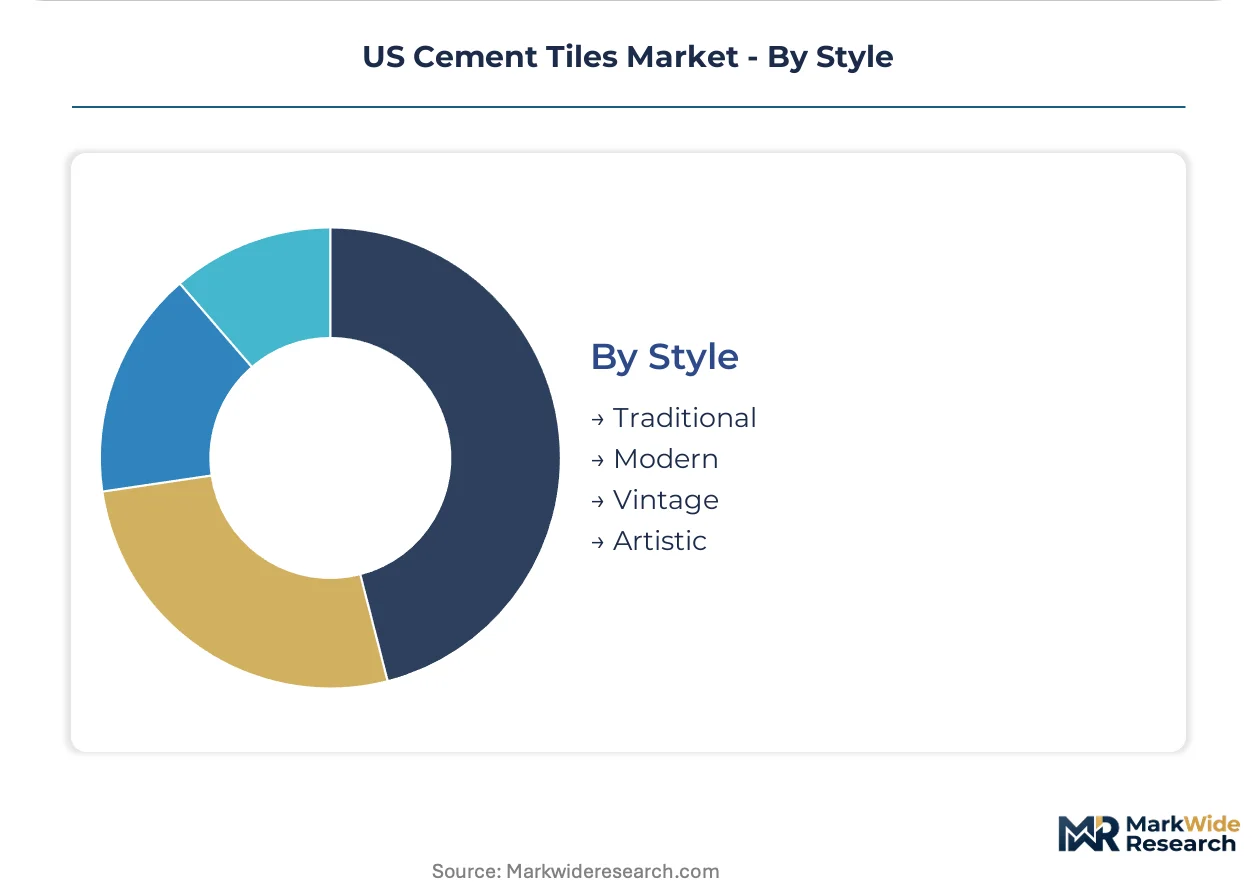
Maturity gradients separate established traditional aesthetics from emerging modern specifications, with vintage and artistic styles occupying niche positioning.
- Traditional:Encaustic patterns and Mediterranean color palettes dominate current installation stock. Florida and California residential markets specify these for established luxury neighborhood continuity.
- Modern:Minimalist geometries and monochromatic palettes gain traction in urban multifamily developments. Austin and Los Angeles designers specify these for contemporary visual differentiation.
- Vintage:Aged-look finishes and period-accurate reproductions serve historic renovation and boutique hospitality projects.
- Artistic:Limited-edition collaborations with individual designers command premium positioning for statement installations.
Traditional styling commands the largest installed base; modern aesthetics show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulations on indoor air quality and VOC emissions are reshaping specification patterns across US metropolitan construction corridors. Cement tile demand concentrates in states where design-forward residential and commercial activity intersects with stringent environmental standards.
California
Luxury residential construction in Los Angeles and San Francisco metropolitan areas drives specification volume for decorative flooring and accent walls. CARB Phase 2 compliance documentation accompanies tile submittals for state-funded institutional projects. The Los Angeles design district anchors direct-to-specifier showroom networks serving boutique hospitality clients.
Texas
Metropolitan construction corridors in Austin, Dallas, and Houston accelerate adoption for residential flooring applications in luxury homebuilding. State energy efficiency codes for residential construction indirectly favor durable interior finish materials with extended lifecycle performance. Austin's hospitality sector concentrates specification authority for hexagonal and custom geometric formats.
Florida
Miami and Tampa metropolitan areas sustain elevated demand for traditional Mediterranean styling in luxury neighborhood continuity. State building codes addressing humidity resistance and moisture management favor cement tiles over composite alternatives in wet-area applications. Miami's restaurant and retail design community sources custom colorways through direct mill relationships.
Southwest
Arizona and New Mexico construction activity emphasizes outdoor patio and pool deck applications requiring freeze-thaw resistant formulations. Regional distribution networks control specification access through design-center showroom footprints. Phoenix and Santa Fe architectural communities specify UV-stable colorants for exposed conditions.
Southeast
Atlanta and Charlotte metropolitan corridors exhibit specification interest for modern aesthetic formats in urban multifamily developments. Regional wholesale distributors serve volume contractors with standardized product lines and predictable lead times. Atlanta's commercial design firms consolidate authority through consolidated specification packages.
US Cement Tiles Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the US cement tiles industry. The vendor base fragments across hand-pouring heritage producers, digitally-enabled color specialists, and scale-driven distribution platforms. Three strategic archetypes dominate: vertically integrated artisan houses, design-forward color innovators, and showroom-network distributors. Competitive moves concentrate on geographic expansion of direct sales channels and backward integration into captive pigment and sealant supply.
Among heritage-focused producers, Original Mission Tile exemplifies deep backward integration into hand-pouring operations. Granada Tile occupies a position within the color innovation tier, leveraging proprietary mixing techniques. Arizona Tile anchors the distribution-platform archetype through extensive design-center showroom networks in the Southwest. These three represent contrasting strategic postures on the artisan-authenticity versus scalable-quality spectrum.
| Leading Market Players |
|---|
| Granada Tile |
| Sabine Hill |
| Original Mission Tile |
| Villa Lagoon Tile |
| Arizona Tile |
| Florida Tile |
| Mosaic del Sur |
| CemTile Industries |
| Lili Cement Tile |
| Others |
Value Chain & Pricing Dynamics
Sixty-day pigment procurement lead times from European specialty chemical suppliers concentrate pricing power with producers holding captive color-mixing capability, compressing margins for fabricators dependent on spot-market mineral sourcing. This inventory exposure shapes how US cement tile manufacturers balance artisan labor premiums against automated pressing investments.
Pricing Analysis
Coastal-to-interior price spreads of 15-20 percent separate California design-center showrooms from Texas wholesale channels serving volume contractors. Three-tier pricing structure across premium hand-poured, standard hydraulic-pressed, and economy imported tiers reflects artisan labor intensity and customization depth. Pricing pressure stems from Portland cement input cost volatility tied to carbon pricing exposure in clinker production. Price-sensitive regional flooring retailers in the Southeast compete primarily on installed cost, while Los Angeles boutique specifiers prioritize color-matching precision over unit economics.
Supply Chain Analysis
Container availability constraints on the Asia-Pacific trade lane elevate inbound logistics costs for Vietnamese and Mexican producers serving US specification markets. Geographic supply concentration clusters in Mexico, Vietnam, and domestic Southwest production hubs drawing from regional aggregate deposits. Raw material dependencies rest on Portland cement from domestic kilns, mineral pigments from European specialty chemical houses, and water-based sealant chemistry from US coating formulators. Single-source vulnerability concentrates in artisan labor pools clustered in specific craft communities. Distribution runs through design-center showroom networks for premium specification and wholesale distributor intermediaries for volume residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-based sealant specification and installation service contracts expand recurring revenue attachment faster than tile unit sales, reframing producer economics around lifecycle surface performance rather than transactional product delivery.
For Market Incumbents: Fortify backward integration into captive pigment supply and in-house sealant formulation to defend margin compression from European specialty chemical price volatility. Deepen design-center showroom footprints in Austin and Miami to capture specification authority before boutique hospitality projects consolidate mill-direct relationships. EPA VOC enforcement on solvent-based coatings threatens legacy sealant pairings; accelerate water-based chemistry pipeline investment. For New Entrants and Emerging Players: Differentiate on low-carbon formulation credentials targeting California and Florida state building code thresholds for embodied carbon in interior finish materials. White-space opportunity concentrates in decorative wall applications for urban multifamily developers seeking LEED v4.1 air quality compliance without flooring-grade structural density premiums. Go-to-market angle: direct-to-developer digital specification tools bypassing traditional distributor markups. For Investors and Strategic Acquirers: Long-term, this sits as a craft-capability consolidation play because artisan labor scarcity constrains scalable authentic production while design-forward construction demand accelerates. Acquisition target archetype: regionally concentrated hand-pouring houses with established showroom networks in Texas or Florida metropolitan corridors. Signal to watch: California Air Resources Board expansion of interior finish carbon intensity standards to private residential construction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pigment Supply | Captive mineral sourcing insulates margin from European specialty chemical price volatility. |
| Design-Center Network Expansion | Direct-to-specifier showrooms in Miami and Austin capture higher-margin project involvement. |
| Water-Based Sealant Pipeline Investment | EPA VOC compliance enables specification for LEED v4.1 certified green building projects. |
| Low-Carbon Formulation Development | California and Florida embodied carbon thresholds create first-mover positioning advantage. |
| Artisan Training Program Scale-Up | Workforce pipeline expansion addresses skilled labor scarcity constraining manufacturing capacity. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA enforcement actions, OSHA silica exposure guidance, and state building code amendments. Primary interviews engaged cement tile production managers, commercial interior designers, flooring contractor procurement leads, and sealant chemistry R&D directors. Secondary validation drew from CARB compliance documentation, FTC Green Guides enforcement records, and construction permit databases in California, Texas, and Florida metropolitan areas. Bottom-up fabrication capacity estimates triangulate against top-down specification volume tracking.
Segmentation dimensions modeled include product geometry, installation environment, aesthetic positioning, and distribution channel structure across the projection horizon. CAGRs derive from installation volume trajectories by application channel and specification authority consolidation patterns. Forecast inputs incorporate Portland cement price indices, artisan labor availability surveys, and state-level green building code adoption timelines.
Material uncertainties — regulatory enforcement intensity, carbon pricing implementation schedules, and artisan labor migration patterns — sit outside the modeled envelope. Forecasts reflect assumptions about continued EPA VOC trajectory and state building code harmonization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
HDG Steel Pipe Market
Building Materials
Cementitious Waterproofing Market
Building Materials
Southeast Asia Concrete Admixtures Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Shotcrete Market
Building Materials
Ductile Iron Pipe Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Engineered Stone Market
Building Materials
Building and Construction Sheets Market
Building Materials
Cellular Concrete Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Construction Stone Market