
 North America Cast-In-Place Concrete Flooring Market | 2026-2036
North America Cast-In-Place Concrete Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cast-In-Place Concrete Flooring Market Analysis
Self-consolidating concrete with embedded fiber reinforcement is tilting installation economics toward faster pour cycles and reduced labor hours. LafargeHolcim leverages its vertically integrated cement-to-finish network across the Great Lakes corridor. Sika AG anchors the high-performance admixture segment with proprietary shrinkage-reducing chemistry. CRH plc competes through dense ready-mix plant coverage in the Sun Belt metropolitan zones.
Cast-in-place concrete flooring refers to slabs poured and cured directly at the construction site, typically achieving compressive strengths of 3,000 to 5,000 psi with thicknesses ranging from four to eight inches depending on load requirements. The method delivers monolithic structural decks for warehouses, manufacturing plants, and retail distribution centers where flatness tolerances and point-load capacity govern operational performance. Polymer-modified technology leads value generation due to superior chemical resistance and faster return-to-service intervals. Reinforced systems command premium positioning where heavy rack loading and forklift traffic dominate facility specifications. Traditional methods still occupy the residential and light commercial perimeter where cost sensitivity outweighs performance thresholds.
OSHA enforces crystalline silica exposure limits during concrete cutting and grinding operations, compelling contractors toward wet methods and vacuum-equipped tools. The EPA regulates VOC content in concrete curing compounds and form-release agents, filtering product formulations available to the North American supply base. State-level building codes in California and Florida impose seismic and hurricane-resistant design standards that elevate reinforcement density and connection detailing. Stakeholders must monitor how evolving embodied carbon disclosure rules under the Buy Clean initiatives reshape material sourcing and mix design decisions across public procurement channels.
Market Dynamics
Self-consolidating concrete with embedded fiber reinforcement is compressing pour cycles and reshaping labor economics across warehouse and logistics construction. The EPA's tightening VOC emissions standards for concrete additives are forcing rapid formulation shifts toward low-emission chemistry.
Growth Catalysts
- EPA VOC Regulations:Tightening emissions standards for concrete curing compounds and form-release agents are accelerating technology shifts toward low-emission formulations across the supply base.
- Warehouse Construction:E-commerce fulfillment center expansion across Texas, California, and Florida is driving demand for high-tolerance slabs with superior point-load capacity.
- Self-Consolidating Concrete:Advanced rheology modifiers are enabling faster placement with reduced vibration requirements, cutting labor hours per pour.
Market Restraints
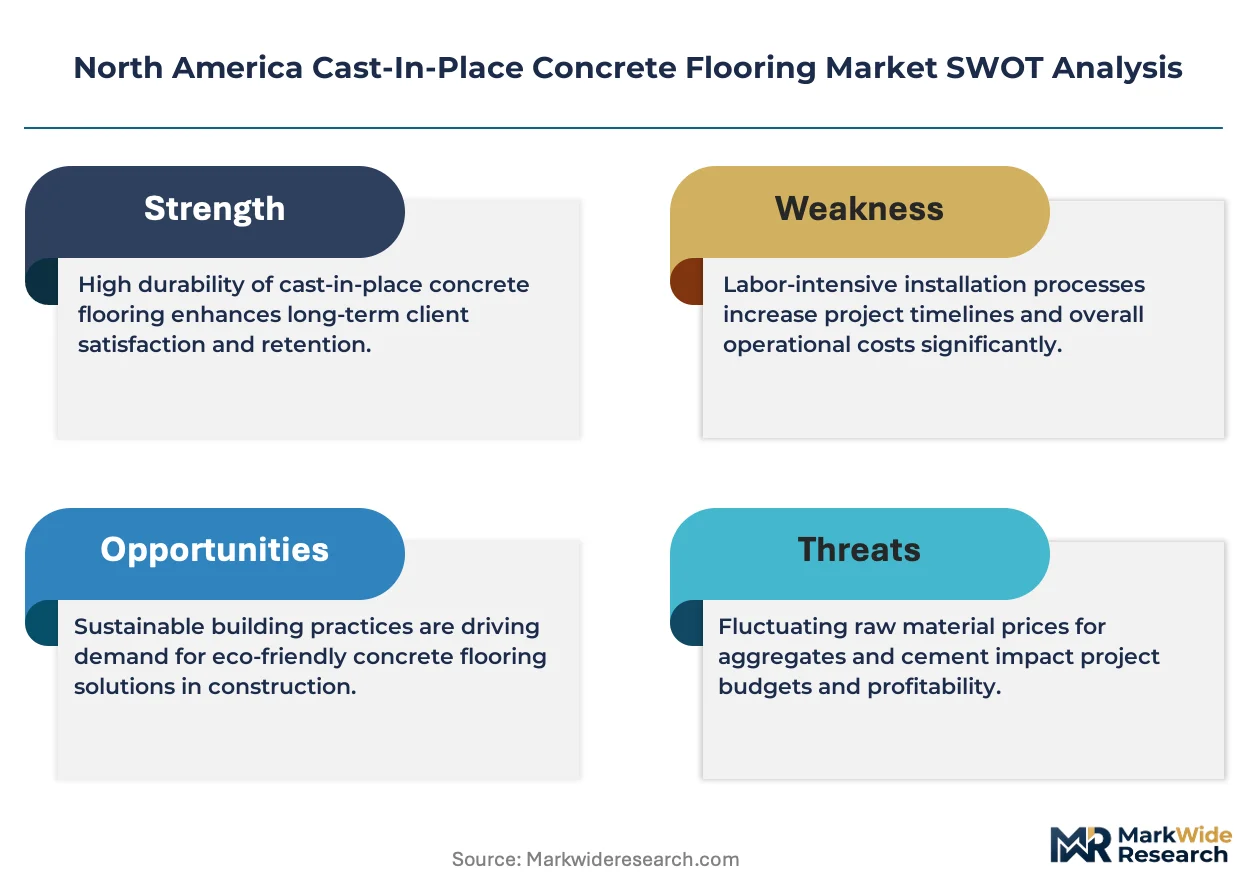
- Cement Price Volatility:Energy-intensive clinker production faces input cost swings that compress margins for ready-mix suppliers serving price-sensitive residential segments.
- Great Lakes Supply Concentration:Vertically integrated cement networks dominate bulk material flows, creating bottleneck risks for independent contractors outside major metropolitan corridors.
- Technical Limitation:Standard cast-in-place methods struggle to achieve the ultra-flat tolerances required for automated warehouse robotics without premium grinding overlays.
Strategic Opportunities
- Florida Hurricane Codes:Seismic and wind-resistant design standards are elevating reinforcement density requirements, creating premium positioning for engineered slab systems.
- Buy Clean Procurement:Embodied carbon disclosure rules under state-level initiatives are reshaping material sourcing decisions across public infrastructure channels.
- Polymer-Modified Overlays:Convergence of rapid-cure resin technology with concrete substrates is enabling faster return-to-service intervals for high-traffic distribution floors.
Industry Challenges
- Silica Compliance:OSHA crystalline silica exposure limits during cutting and grinding operations are compelling capital investment in wet methods and vacuum-equipped tool fleets.
- Skilled Labor Scarcity:Shortage of experienced finishers capable of achieving F-min flatness tolerances is extending project timelines and elevating wage pressure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cast-In-Place Concrete Flooring Market |
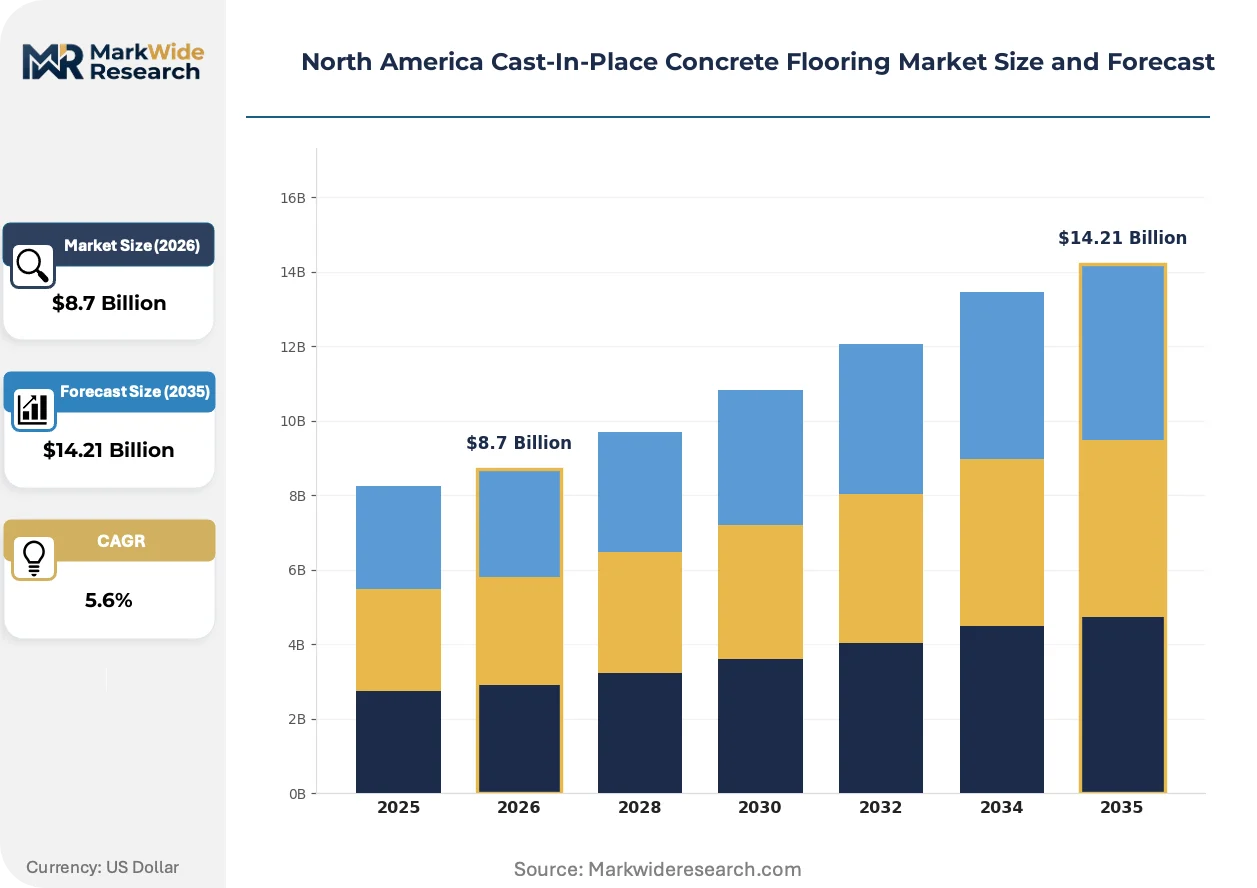
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential, Commercial, Industrial, Infrastructure Technology: Traditional, Polymer-Modified, Self-Leveling, Reinforced Application: Flooring, Pavements, Parking Lots, Driveways End User: Contractors, Builders, Architects, Homeowners |
| Companies Covered | BASF SE, Cemex, CRH plc, Heidelberg Cement Group, LafargeHolcim, Sika AG, Vulcan Materials Company, Martin Marietta Materials, Forterra, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cast-In-Place Concrete Flooring Market Emerging Trajectories
Material science advances and regulatory pressure are converging to redefine performance benchmarks and installation economics across commercial flooring applications. Three developments are reshaping competitive positioning.
Fiber-reinforced self-consolidating concrete is hybridizing traditional steel mesh reinforcement with synthetic macro-fibers to eliminate placement bottlenecks. Cold storage and food processing facilities in the Midwest are adopting these systems for crack control under thermal cycling. The technology is hybridizing project timelines by collapsing forming, pouring, and finishing into compressed sequences that reduce site labor by double-digit percentages.
California's Title 24 building efficiency standards are mandating lower embodied carbon in structural materials for state-funded projects. The regulation is filtering admixture portfolios toward supplementary cementitious materials and alternative binders that reduce clinker content. Public procurement channels across the Pacific Coast are responding by embedding environmental product declarations into bid evaluation criteria.
Integrated design-build contracts are consolidating slab specification authority away from general contractors toward specialized flooring subcontractors with in-house engineering capability. Large distribution developers in Texas are bypassing traditional bid processes to lock in performance guarantees for flatness and durability metrics. This consolidation is most visible in speculative warehouse construction where early contractor involvement compresses design iteration cycles.
North America Cast-In-Place Concrete Flooring Market Segmentation
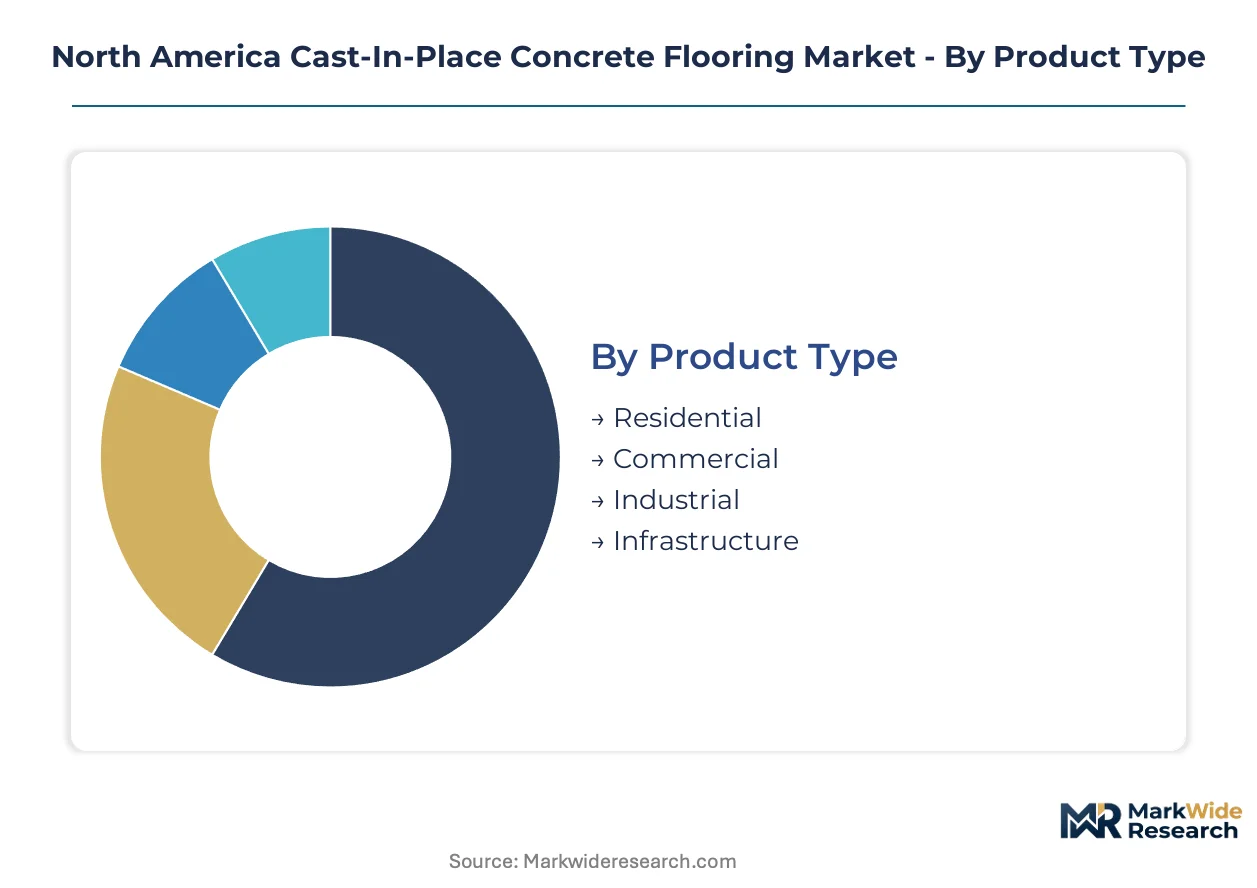
Segmentation in the North America cast-in-place concrete flooring market reveals distinct performance requirements across construction verticals. Each category carries unique specification pressures from regulators, end-users, and project delivery models that reshape material selection and installation protocols.
Product Type:
After-sales service intensity varies sharply across construction verticals, with industrial and infrastructure segments demanding multi-year performance warranties and scheduled maintenance protocols that residential projects rarely require.
- Residential:Standard 3,000 psi mixes dominate single-family foundations and basement slabs where cost sensitivity overrides performance premiums. Demand clusters in Texas and Florida suburban corridors where housing permits remain elevated despite mortgage rate pressure.
- Commercial:Higher tolerance specifications for retail and office buildings drive specification of polymer-modified systems with faster return-to-service intervals. California's Title 24 efficiency standards are elevating embodied carbon disclosure requirements for state-funded commercial projects.
- Industrial:Warehouse and distribution center construction across the Great Lakes and Sun Belt corridors demands 5,000+ psi slabs with F-min flatness ratings for automated material handling systems.
- Infrastructure:Highway bridge decks, airport runways, and port terminals require specialized mix designs with air entrainment and corrosion inhibitors for freeze-thaw durability.
By volume, Industrial leads. By growth pace, Commercial is ahead.
Technology:
Technology selection maps directly to project margin structures, with premium formulations capturing value in time-constrained applications while traditional methods defend share in price-sensitive segments.
- Traditional:Conventional Portland cement mixes with standard reinforcement maintain cost competitiveness in residential and light commercial perimeter markets. EPA VOC regulations on curing compounds are forcing gradual reformulation of traditional product lines.
- Polymer-Modified:Latex and epoxy-modified systems deliver superior chemical resistance and bond strength for food processing and pharmaceutical cleanrooms. Cold storage facilities in the Midwest are adopting these systems for thermal cycling performance.
- Self-Leveling:High-flow formulations with embedded fibers are collapsing pour cycles in warehouse construction across Texas metropolitan zones. The technology reduces vibration labor and accelerates project schedules by double-digit percentages.
- Reinforced:Steel fiber and macro-synthetic hybrid systems command premium positioning where heavy rack loading and forklift traffic dominate facility specifications. Florida hurricane codes are elevating reinforcement density requirements for structural slabs.
By installed base, Traditional dominates. By specification momentum, Self-Leveling is climbing the fastest.
Application:
Application type determines the regulatory exposure profile, with pavements and parking lots facing stormwater management rules that interior flooring escapes.
- Flooring:Interior slab systems for warehouses, manufacturing plants, and distribution centers where flatness tolerances govern operational performance. E-commerce fulfillment center expansion is concentrating demand in California, Texas, and Florida.
- Pavements:Municipal roadways and highway shoulders require durability mixes with air entrainment for freeze-thaw cycling. State DOT procurement channels are embedding Buy Clean carbon disclosure rules into material sourcing decisions.
- Parking Lots:Commercial and retail surface parking demands moderate-strength slabs with sealant integration for weatherproofing. OSHA silica exposure limits during joint cutting operations are compelling wet method adoption.
- Driveways:Residential concrete driveways represent the most price-sensitive segment, with homeowners prioritizing initial cost over performance longevity. Independent contractors outside major metropolitan corridors face supply bottleneck risks from concentrated cement networks.
By square footage, Flooring leads. By public investment growth, Pavements is gaining share fastest.
End User:
End-user type shapes procurement authority and technical specification depth, with architects and contractors diverging on performance-versus-cost trade-offs.
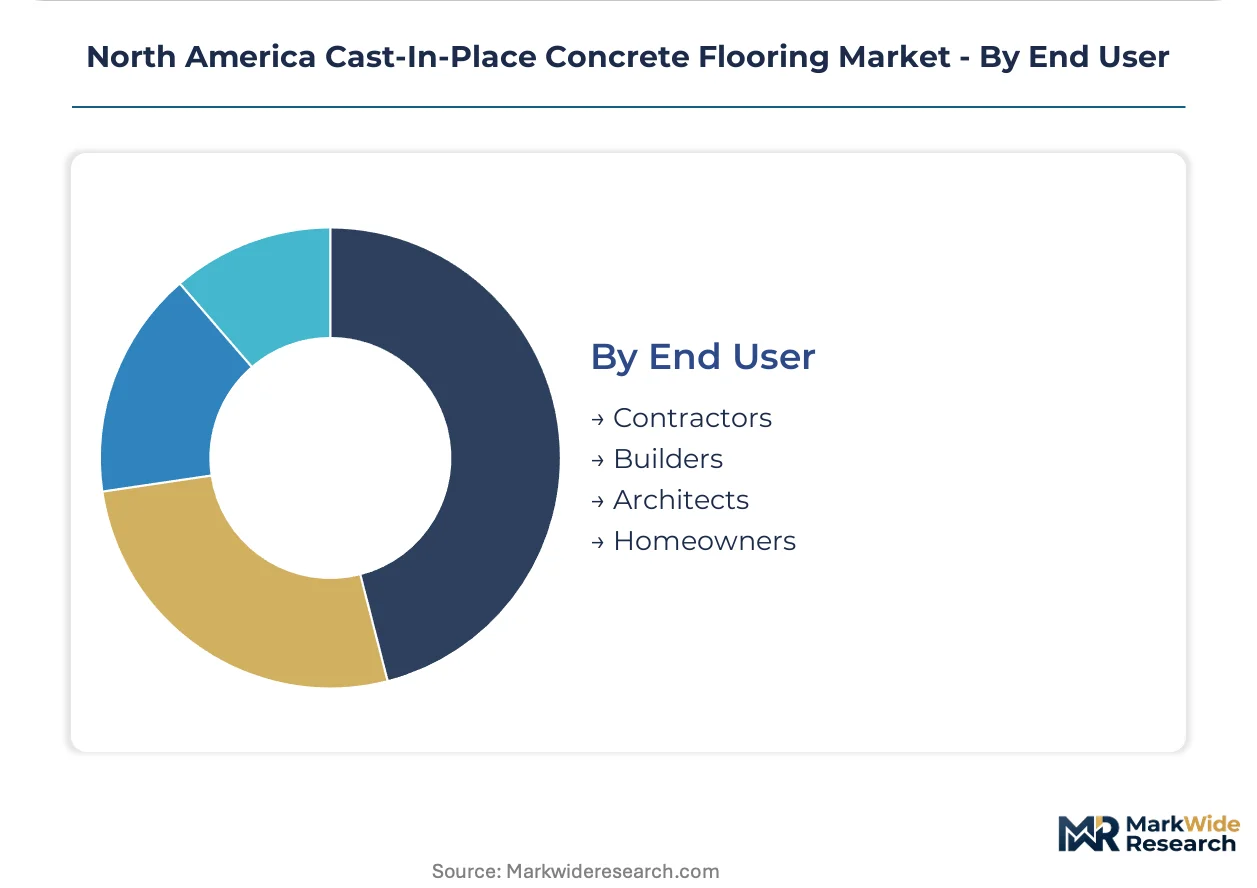
- Contractors:General and specialty concrete contractors control material selection for speculative warehouse and light commercial projects. Skilled labor scarcity for F-min flatness finishing is extending project timelines and elevating wage pressure.
- Builders:Production homebuilders and commercial developers prioritize volume procurement relationships with ready-mix suppliers. Vertically integrated cement-to-finish networks dominate bulk material flows in the Great Lakes corridor.
- Architects:Design professionals specify high-performance systems for institutional and corporate clients with sustainability mandates. California's embodied carbon disclosure requirements are filtering admixture portfolios toward supplementary cementitious materials.
- Homeowners:Individual residential buyers represent fragmented demand with minimal technical specification involvement. Cost sensitivity outweighs performance thresholds in this perimeter segment.
By project count, Contractors lead. By specification influence, Architects is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian cement and admixture suppliers route bulk materials through Great Lakes distribution networks into the United States industrial corridor. Cross-border trade flows concentrate around Chicago, Detroit, and Buffalo hubs where integrated logistics networks compress delivery cycles for warehouse construction projects.
United States
E-commerce fulfillment center construction in Texas, California, and Florida drives specification of high-tolerance slabs for automated material handling systems. OSHA enforces crystalline silica exposure limits during concrete cutting operations, compelling wet method adoption and vacuum-equipped tool investment. Dallas-Fort Worth and Houston metropolitan zones anchor demand concentration where speculative warehouse development accelerates pour cycle requirements.
Canada
Infrastructure rehabilitation and commercial development in Ontario and Quebec sustain steady demand for durable pavement and industrial flooring systems. Provincial environmental regulators enforce emissions standards on concrete production facilities that elevate low-carbon mix design adoption. The Greater Toronto Area concentrates ready-mix capacity where vertically integrated suppliers coordinate material flows into cross-border industrial projects.
Mexico
Manufacturing facility expansion across Nuevo León and the Bajío Region generates demand for heavy-duty industrial slabs with seismic reinforcement specifications. Federal environmental standards under SEMARNAT regulate quarry operations and cement plant emissions, filtering supplier compliance requirements. Monterrey anchors northern industrial construction where nearshoring trends accelerate warehouse and logistics facility development.
North America Cast-In-Place Concrete Flooring Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a structure shaped by bulk material logistics and formulation chemistry differentiation. Vertically integrated cement-to-finish networks dominate the Great Lakes and Sun Belt corridors where captive aggregate reserves and plant density create distribution moats. Three archetypes define competitive positioning: multinational building materials conglomerates with captive cement supply, specialized admixture and chemical formulators with proprietary technology, and regional ready-mix operators with dense metropolitan coverage. Capacity expansion and backward integration into aggregate sourcing represent the dominant competitive moves as margin pressure intensifies on commodity-grade mixes.
Among the multinational conglomerates, LafargeHolcim and CRH plc exemplify channel-controlling archetypes with integrated networks spanning cement production through finished slab installation. Heidelberg Cement Group occupies a parallel position with concentrated plant coverage in key metropolitan zones. Sika AG and BASF SE represent the formulation-specialist tier, anchoring high-performance admixture segments where proprietary chemistry commands specification authority on premium commercial and industrial projects.
| Leading Market Players |
|---|
| BASF SE |
| Cemex |
| CRH plc |
| Heidelberg Cement Group |
| LafargeHolcim |
| Sika AG |
| Vulcan Materials Company |
| Martin Marietta Materials |
| Forterra |
| Others |
Supply Flow & Price Mechanics
Cement price volatility from energy-intensive clinker production determines both the spread between premium polymer-modified systems and commodity-grade mixes and the geographic shape of ready-mix distribution networks. Contractors in price-sensitive residential segments absorb margin compression while industrial buyers lock in long-term offtake agreements that bypass spot market exposure.
Pricing Analysis
The technology-generation pricing gap between traditional Portland cement mixes, current polymer-modified systems, and emerging low-carbon formulations structures contract negotiations across the North American market. Three-tier pricing separates premium self-consolidating concrete with embedded fiber reinforcement from standard ready-mix and economy-grade residential pours. Price differentiation hinges on F-min flatness certification and EPA-compliant low-VOC admixture portfolios. Pricing pressure stems from skilled labor scarcity extending pour timelines and elevating wage costs. Homeowners in suburban Texas and Florida corridors exhibit highest price sensitivity, while e-commerce developers in California prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from general contractors to ready-mix suppliers now stretch 60-90 days, compressing working capital for independent operators outside vertically integrated networks. Geographic supply concentration centers on the United States Great Lakes corridor, Ontario's Greater Toronto Area, and northern Mexico's Monterrey industrial zone. Raw material dependencies include Portland cement clinker, synthetic macro-fibers, and shrinkage-reducing admixtures. Single-source vulnerability runs through captive aggregate reserves controlled by multinational building materials conglomerates. Distribution runs through metropolitan ready-mix plants with 50-mile delivery radii, supplemented by cross-border bulk material flows through Chicago, Detroit, and Buffalo logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America cast-in-place concrete flooring market sits at a regulatory inflection where EPA VOC tightening and California embodied carbon disclosure rules are simultaneously compressing legacy formulation margins and opening premium positioning for low-emission chemistry innovators.
For Market Incumbents: Harden specification authority in automated warehouse corridors by embedding performance guarantees for F-min flatness directly into design-build contracts. Deepen backward integration into supplementary cementitious material sourcing to defend margin position against clinker price volatility. Lock in multi-year offtake agreements with Texas and California e-commerce developers before low-carbon procurement mandates reshape bid evaluation criteria.
For New Entrants and Emerging Players: Mid-market commercial buildings in secondary Sun Belt metropolitan zones outside Dallas-Fort Worth and Houston represent the most penetrable entry point for specialized flooring subcontractors with in-house engineering capability. Cold storage facilities in the Midwest seeking thermal cycling performance offer specification momentum for fiber-reinforced self-consolidating concrete. Pursue integrated design-build contracting authority to bypass traditional general contractor gatekeeping and capture early involvement premiums.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors formulation-specialist targets with proprietary low-VOC chemistry and established specification relationships with California architects. Long-term viability over the next decade hinges on positioning for public procurement channels as Buy Clean initiatives expand beyond pilot programs. Monitor state-level embodied carbon disclosure rulemaking as the primary signal for timing capacity investments in alternative binder production.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SCM Sourcing | Captive supply of fly ash and slag reduces clinker dependency and EPA compliance costs. |
| Low-VOC Admixture Portfolio Expansion | Proprietary curing compounds secure specification authority on California Title 24 projects. |
| Design-Build Contracting Authority | Early contractor involvement compresses iteration cycles for speculative warehouse developers. |
| Metropolitan Ready-Mix Capacity Addition | Plant density in Texas corridors captures e-commerce fulfillment center construction velocity. |
| Cross-Border Logistics Network Optimization | Great Lakes distribution hubs reduce delivery cycles for Chicago-Detroit industrial corridors. |
Methodological Framework
Cross-validation between primary interviews with ready-mix plant managers, concrete contractors, specification architects, and EPA compliance officers and secondary validation anchors the qualitative findings. Bottom-up and top-down triangulation incorporates customs and trade data from USITC and Statistics Canada, SEC 10-K filings from building materials conglomerates, state-level building permit databases from Texas and California, and American Concrete Institute technical standards. The analysis draws from field-level conversations with 40+ stakeholders across the cement-to-finish value chain.
Calibration against historical volume trajectories and macroeconomic drivers shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application vertical, and end-user procurement authority, with regional regulatory clusters as an overlay dimension. CAGRs derive from regression analysis of permit issuance, construction spending, and material intensity coefficients. Forecast inputs incorporate clinker price elasticity, skilled labor availability indices, and e-commerce fulfillment center pipeline data.
Practitioners should monitor EPA VOC rulemaking timelines, California Buy Clean procurement expansion, and cement industry consolidation announcements for early signals of forecast deviation. The analysis reflects assumptions about regulatory enforcement continuity and construction labor market stability. Macroeconomic recession, accelerated low-carbon mandate adoption, or breakthrough precast displacement technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Corrugated Polycarbonate Panels Market
Building & Construction Materials
Global Fiber Cement Board Market
Building & Construction Materials
North America Concrete Conditioner Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
US Ceiling Tiles Market
Building & Construction Materials
Roofing Underlayment Market