
 HDG Steel Pipe Market | 2026-2036
HDG Steel Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
HDG Steel Pipe Market Insights
The EU Green Deal is shifting procurement criteria for steel-intensive infrastructure across member states. ArcelorMittal leverages its integrated European flat steel capacity to supply certified low-emission galvanized sections for public works tenders. Nippon Steel Corporation anchors its position through advanced furnace controls that reduce zinc consumption rates below regional averages. POSCO competes on scale, operating some of the largest continuous galvanizing lines serving Korean shipbuilders and export markets.
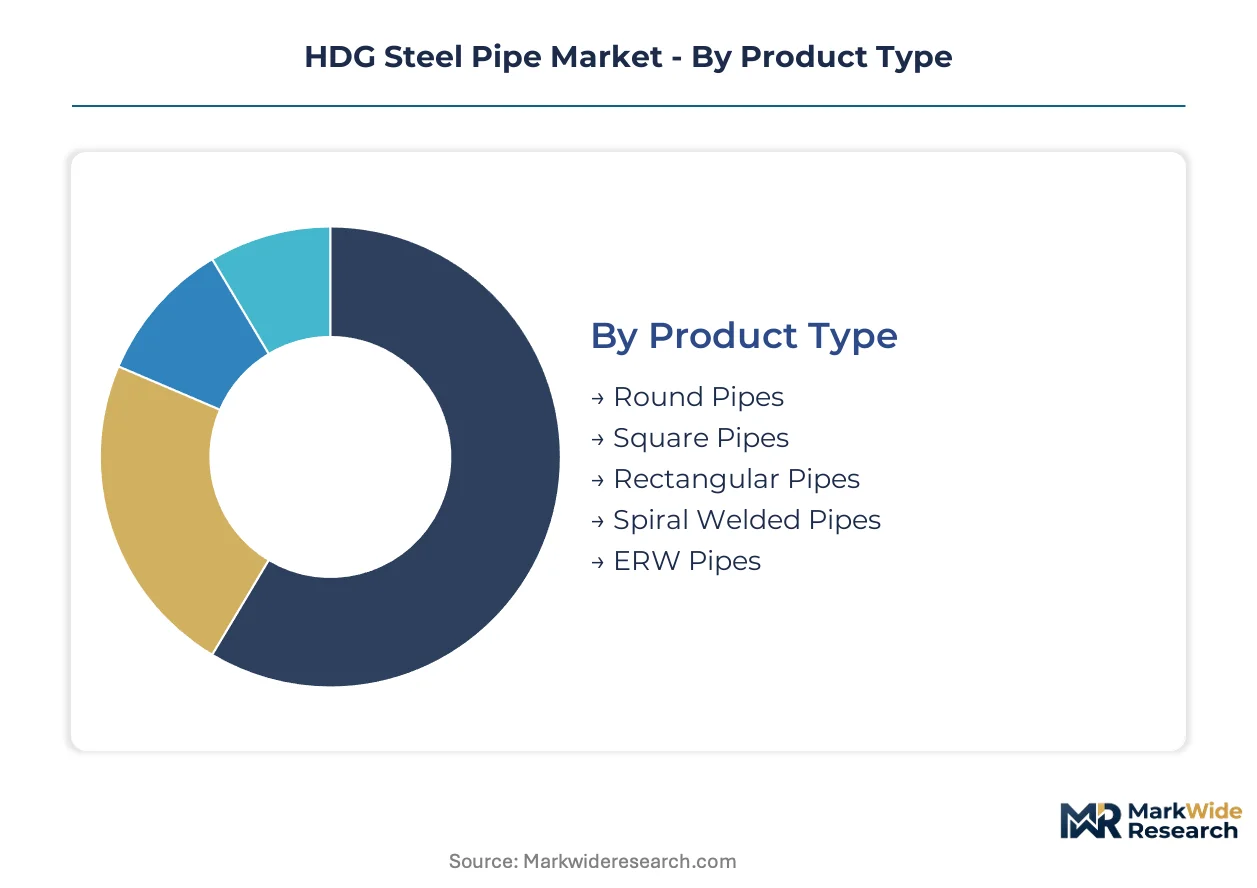
Hot-dip galvanized steel pipe is carbon or alloy steel tubing immersed in molten zinc to form a metallurgically bonded coating typically ranging from 35 to 200 microns, providing sacrificial corrosion protection for buried or exposed service environments. Round pipes dominate volume for pressurized fluid conveyance while square and rectangular profiles command premium positioning in structural framework applications where dimensional tolerance and aesthetic finish determine specification. Spiral welded and ERW variants split the large-diameter segment, with spiral welded pipes occupying infrastructure-scale water transmission projects and ERW pipes leading in standardized construction and conduit runs where coil-fed efficiency drives unit economics.
ASTM A53 and EN 10255 standards govern dimensional and mechanical properties for pressure and structural service, while EPA stormwater regulations and the EU Construction Products Regulation shape material selection for municipal and environmental applications. China's GB/T 3091 and India's BIS IS 1239 impose additional testing protocols that filter market access for imported pipe stock. Stakeholders must monitor evolving zinc alloy specifications and carbon intensity disclosure requirements as green procurement clauses harden across public infrastructure contracts.
Market Dynamics
China's dual carbon goals are forcing hot-dip galvanizing furnaces to cut emissions intensity, while Southeast Asian infrastructure developers accelerate coated steel procurement for water transmission networks. This regulatory squeeze on production methods collides with concentrated demand expansion in India's western industrial corridor.
Growth Catalysts
- EU Green Deal procurement clauses:Public works tenders across member states now require carbon intensity disclosure for galvanized sections, redirecting specification toward certified low-emission supply chains.
- India's industrial corridor buildouts:Gujarat and Maharashtra states are accelerating water transmission and structural framework deployment, concentrating procurement of ASTM A53 and BIS IS 1239 compliant pipe stock.
- Zinc alloy specification evolution:Advanced furnace controls reducing zinc consumption rates below regional benchmarks are improving unit economics for continuous galvanizing operations serving Korean shipbuilders.
Market Restraints
- Input cost volatility:Zinc price swings and energy tariffs for molten bath maintenance compress margins for independent galvanizing job shops dependent on spot metal purchases.
- Supply concentration risk:Integrated flat steel producers in Europe and East Asia control certified low-emission coil feedstock, limiting market access for secondary processors lacking backward integration.
- Technical limitation:Coating thickness uniformity below 50 microns remains difficult to achieve on spiral welded large-diameter pipe for infrastructure-scale water transmission projects.
Strategic Opportunities
- Underpenetrated geography:Vietnam and Indonesia municipal water authorities are expanding procurement of EN 10255 certified galvanized conduit for stormwater management systems.
- Regulatory tailwind:EPA stormwater regulations are mandating corrosion-resistant materials for municipal drainage, expanding specification of hot-dip galvanized pipe in US public infrastructure.
- Technology convergence:Digital furnace monitoring combined with predictive zinc bath chemistry management is enabling real-time coating optimization for ERW pipe producers.
Industry Challenges
- Certification timeline compression:BIS IS 1239 and GB/T 3091 testing protocols require extended batch validation, delaying market entry for imported pipe stock into India and China.
- Skill gap in furnace control:Operators capable of managing continuous galvanizing line parameters for alloy coating specifications remain scarce in emerging production hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDG Steel Pipe Market |
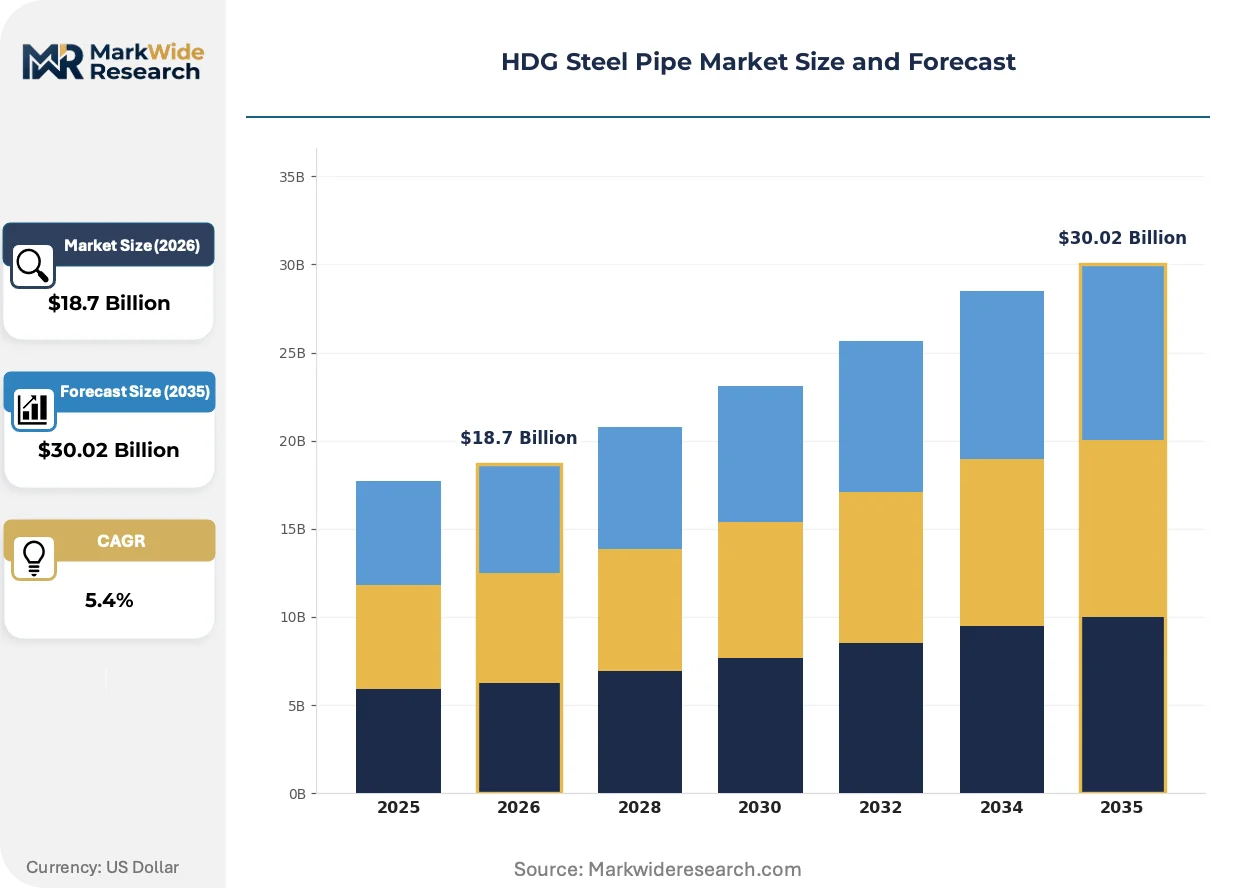
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Round Pipes, Square Pipes, Rectangular Pipes, Spiral Welded Pipes, ERW Pipes Coating Thickness: Light, Medium, Heavy, Extra Heavy, Custom Application: Construction Framework, Water Transmission, Electrical Conduits, Agricultural Fencing, Marine Structures End User: Building Contractors, Municipal Utilities, Irrigation Companies, Shipbuilders, Infrastructure Developers |
| Companies Covered | ArcelorMittal, Nippon Steel Corporation, POSCO, Tata Steel, United States Steel Corporation, JFE Steel Corporation, Tenaris, Steel Authority of India Limited, Jiangsu Changbao Steel Pipe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDG Steel Pipe Market Trends and Innovations
Hot-dip galvanized steel pipe production is undergoing methodical process refinement rather than disruptive technology substitution. Furnace efficiency, coating chemistry control, and procurement data integration are converging to reshape competitive positioning.
Continuous galvanizing line automation with real-time zinc bath monitoring is consolidating quality consistency across high-volume ERW pipe production. Korean and Japanese producers are deploying these systems most aggressively. The technology is consolidating mid-tier job shops into toll-processing relationships with integrated coil suppliers who control furnace capex and metallurgical expertise.
REACH and the EU Construction Products Regulation are tightening disclosure requirements for embedded carbon in steel-intensive infrastructure. Contractors bidding on public works must now document coating process emissions alongside base metal provenance. German and Dutch municipal water authorities are rejecting tenders lacking Environmental Product Declaration coverage for galvanized pipe stock.
Buyers are consolidating supplier relationships around full-service coating-to-fabrication partnerships. Large construction groups in India's western corridor now specify single-source responsibility for cutting, threading, and corrosion protection of structural pipe. This bundling is displacing fragmented procurement of bare steel and separate galvanizing services, compressing the vendor base for standardized construction runs.
HDG Steel Pipe Market Segmentation
HDG steel pipe procurement hinges on dimensional tolerance, coating durability, and compliance with project-specific standards. Buyers weigh unit economics against performance requirements across pressure service, structural framework, and environmental exposure applications.
Product Type:
Buyers select profiles based on load-bearing geometry, fluid pressure requirements, and fabrication compatibility with end-use specifications.
- Round Pipes:Circular cross-sections optimize pressure containment for fluid conveyance and mechanical tubing. ASTM A53 compliance dominates procurement for building contractors in India's western corridor, where Gujarat and Maharashtra infrastructure developers specify certified stock for water transmission networks.
- Square Pipes:Uniform wall thickness and right-angle geometry deliver dimensional precision for structural frameworks. Premium positioning in commercial construction reflects aesthetic finish requirements and tighter tolerance specifications that command price premiums over round equivalents.
- Rectangular Pipes:Asymmetric profiles suit architectural and mechanical support applications requiring directional load distribution.
- Spiral Welded Pipes:Helical seam construction enables large-diameter production for infrastructure-scale water transmission. Coating thickness uniformity below 50 microns remains technically challenging on these diameters, constraining specification for critical buried service.
- ERW Pipes:Coil-fed electric resistance welding delivers cost efficiency for standardized construction runs and electrical conduit. Korean producers deploy continuous galvanizing automation to consolidate quality consistency across high-volume output.
Round pipes lead on scale; ERW pipes lead on momentum.
Coating Thickness:
Service environment severity and design life expectations drive specification across zinc coating mass categories.
- Light:35-50 micron coatings serve indoor or low-corrosion exposure with cost-minimized protection. Indoor electrical conduit and temporary structural applications concentrate demand where replacement cycles tolerate shorter service life.
- Heavy:85-200 micron specifications target buried water transmission, marine atmospheric exposure, and aggressive soil conditions. Municipal utilities in Vietnam and Indonesia are expanding procurement of heavy-coated EN 10255 certified stock for stormwater management infrastructure.
- Medium:Intermediate protection balances cost and durability for general outdoor construction.
- Extra Heavy:Maximum coating mass addresses extreme environments including tidal zones and industrial chemical exposure.
- Custom:Application-specific thickness and alloy formulations serve niche performance requirements.
Heavy coatings dominate specification value; custom coatings are gaining share fastest.
Application:
End-use performance requirements determine pipe geometry, coating grade, and certification standards.
- Construction Framework:Structural steel tubing for commercial and industrial buildings requires dimensional tolerance and aesthetic surface finish. Indian building contractors are consolidating procurement around single-source cutting, threading, and coating partnerships.
- Water Transmission:Pressure-rated pipe for municipal distribution and drainage networks demands coating integrity and long-term corrosion resistance. EPA stormwater regulations are mandating corrosion-resistant materials for US municipal drainage expansion.
- Electrical Conduits:Protective raceway systems require consistent internal diameter and smooth zinc surfaces for wire pulling.
- Agricultural Fencing:Post and rail systems prioritize cost efficiency over precision tolerance for rural property boundaries.
- Marine Structures:Coastal and offshore platforms specify heavy coating mass and alloy compositions for salt spray resistance.
Construction framework leads on volume concentration; water transmission leads on regulatory tailwinds.
End User:
Procurement scale, technical expertise, and compliance obligations differentiate buyer segments.
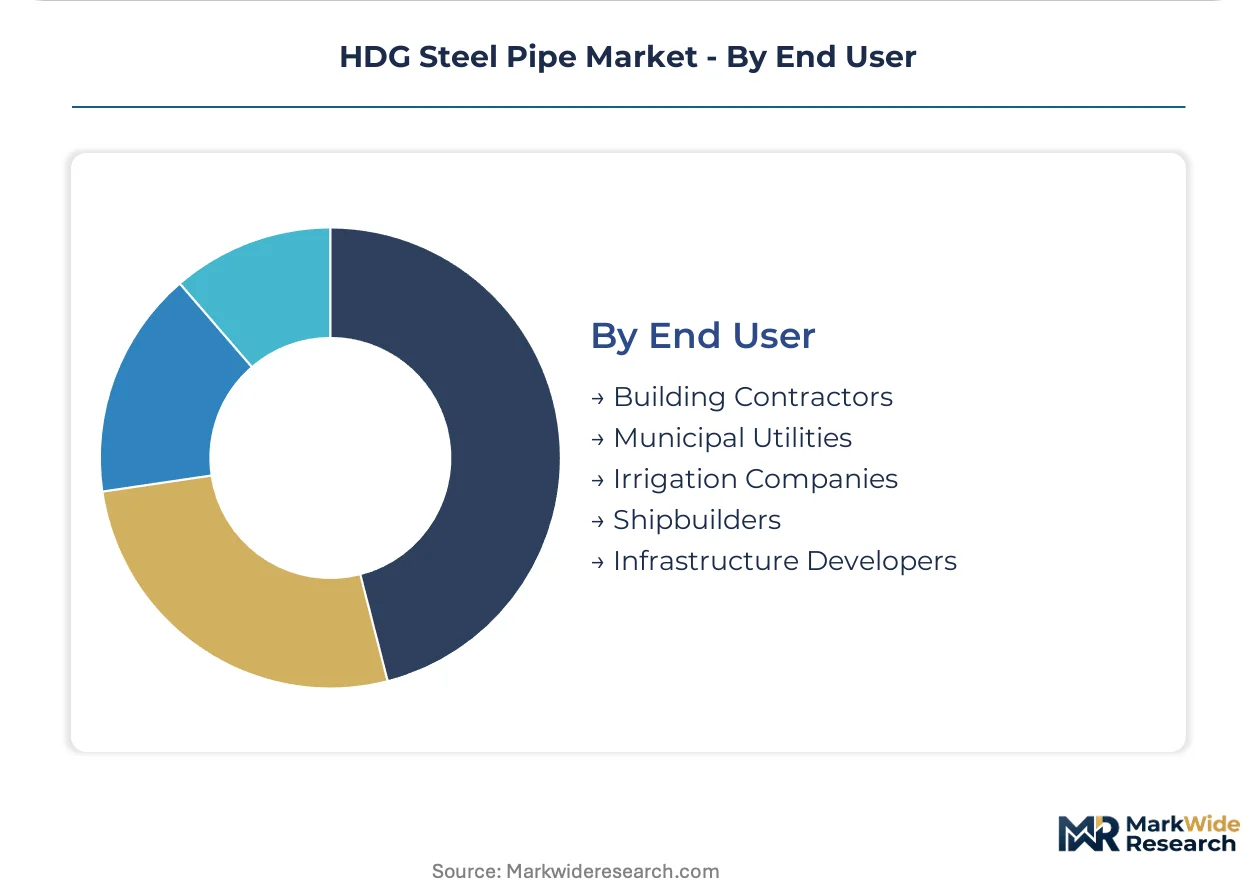
- Municipal Utilities:Public water authorities operate under strict specification regimes and extended asset life requirements. German and Dutch municipal water authorities now reject tenders lacking Environmental Product Declaration coverage for embedded carbon disclosure.
- Infrastructure Developers:Large-scale project sponsors bundle civil works procurement across multiple material categories. Southeast Asian developers are accelerating coated steel procurement for regional water transmission network expansion.
- Building Contractors:Fragmented construction market participants purchase standardized stock through distributor channels.
- Irrigation Companies:Agricultural water system installers prioritize cost efficiency and rapid availability over premium specifications.
- Shipbuilders:Korean shipyards source certified coil feedstock from integrated producers operating large-scale continuous galvanizing lines.
Municipal utilities lead on specification stringency; infrastructure developers lead on expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hot-dip galvanized steel pipe production scaled through integrated flat steel mills in Europe and East Asia during the mid-20th century. Today procurement patterns concentrate in infrastructure corridors where water transmission networks and industrial construction drive specification.
China
Dual carbon goals from MEE are forcing hot-dip galvanizing furnaces to cut emissions intensity across Shandong and Hebei provinces. GB/T 3091 testing protocols filter market access for imported pipe stock. Yangtze River Delta manufacturers are upgrading continuous galvanizing lines to meet tightening benchmarks.
India
Gujarat and Maharashtra states are accelerating industrial corridor buildouts concentrating demand for BIS IS 1239 compliant pipe. The PLI scheme for specialty steel is incentivizing domestic coating capacity expansion. Western corridor infrastructure developers are bundling procurement of ASTM A53 certified stock for water transmission networks.
Germany
REACH and the EU Construction Products Regulation mandate Environmental Product Declaration coverage for galvanized pipe in public works tenders. Dutch and German municipal water authorities reject bids lacking embedded carbon disclosure. Ruhr Valley integrated producers supply certified low-emission sections for regional infrastructure.
United States
EPA stormwater regulations mandate corrosion-resistant materials for municipal drainage expansion. Gulf Coast petrochemical construction and Midwest agricultural irrigation drive specification of heavy-coated pipe. Texas and Louisiana distributors are consolidating supplier relationships around full-service coating-to-fabrication partnerships.
South Korea
POSCO operates large-scale continuous galvanizing lines serving domestic shipbuilders and export markets. Korean producers deploy real-time zinc bath monitoring systems most aggressively for ERW pipe quality consistency. Busan-Ulsan industrial cluster anchors coating-to-fabrication capacity for marine structural applications.
HDG Steel Pipe Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and coating specification complexity. The market structure consolidates around integrated flat steel producers controlling certified low-emission coil feedstock, while independent galvanizing job shops occupy fragmented toll-processing relationships. Three archetypes dominate: integrated steel majors with captive coating capacity, specialized pipe fabricators with furnace expertise, and regional distributors bundling fabrication services. Dominant competitive moves include backward integration into zinc alloy supply and geographic expansion into underpenetrated municipal water authority procurement.
Within the integrated steel major tier, ArcelorMittal and Nippon Steel Corporation exemplify archetypes leveraging European and Japanese flat steel capacity respectively. POSCO occupies a position among Korean scale-driven producers serving export-oriented shipbuilding demand. Tata Steel represents the emerging market integrated archetype with western India corridor exposure. These anchors demonstrate how furnace control expertise and coil feedstock certification separate premium-tier positioning from commodity-margin competition.
| Leading Market Players |
|---|
| ArcelorMittal |
| Nippon Steel Corporation |
| POSCO |
| Tata Steel |
| United States Steel Corporation |
| JFE Steel Corporation |
| Tenaris |
| Steel Authority of India Limited |
| Jiangsu Changbao Steel Pipe |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal procurement clauses now gate qualified supply access and premium-tier pricing power across public infrastructure tenders. Contractors lacking Environmental Product Declaration coverage face exclusion from German and Dutch municipal water authority contracts, compressing the vendor base for certified low-emission galvanized pipe stock.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates integrated producers with captive coil feedstock from toll-processing job shops and bare steel distributors. Price differentiation rests on certification grade for embedded carbon disclosure and furnace control precision for coating uniformity. Pricing pressure stems from zinc price volatility and energy tariffs for molten bath maintenance, squeezing margins for spot metal purchasers. Municipal utilities exhibit lowest price sensitivity due to extended asset life requirements, while irrigation companies and agricultural fencing buyers prioritize unit cost minimization above specification compliance.
Supply Chain Analysis
Scrap pipe collection and zinc bath residue recovery flow through secondary metal processors in Shandong province and the Ruhr Valley, feeding back into alloy formulation for fresh coating cycles. Geographic supply concentration centers on China, South Korea, and Germany, where integrated flat steel mills control certified low-emission coil output. Raw material dependencies draw from zinc concentrate smelters, natural gas feedstock for furnace heating, and specialized alloy additives for corrosion performance. Single-source vulnerability concentrates in European coil supply for EPD-certified sections. Distribution runs through full-service coating-to-fabrication partnerships that displace fragmented procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual carbon mandates in China impose stricter emissions benchmarks than India's PLI incentive structure, creating cost-arbitrage opportunities for coating capacity relocation toward western India corridor demand.
For Market Incumbents: Anticipate regulatory timeline compression for BIS IS 1239 and GB/T 3091 batch validation by securing pre-certified coil inventory in advance of tender deadlines. Defend furnace utilization rates through toll-processing contracts with secondary job shops lacking backward integration into metallurgical expertise. Prioritize real-time zinc bath monitoring capex to sustain coating consistency premiums as Korean and Japanese producers automate most aggressively. For New Entrants and Emerging Players: Enter via Vietnam and Indonesia municipal water authority procurement for EN 10255 certified stormwater conduit, where specification regimes remain less stringent than German or Dutch EPD requirements. Target heavy-coated spiral welded pipe for infrastructure-scale transmission projects, where coating thickness uniformity below 50 microns constrains incumbent capacity. Pursue single-source cutting, threading, and coating bundling partnerships with Indian western corridor construction groups. For Investors and Strategic Acquirers: Roll-up economics work for regional distributors with fabrication capabilities because fragmented procurement of bare steel and separate galvanizing services is consolidating around full-service vendors. Long-term viability hinges on exposure to municipal utility specification regimes with extended asset life requirements. Watch for EPA stormwater regulation expansion as signal for US public infrastructure corrosion-resistant material mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Alloy Supply | Captive alloy formulation secures coating consistency against spot metal price volatility for continuous galvanizing lines. |
| Continuous Galvanizing Line Automation | Real-time bath monitoring consolidates quality consistency for Korean ERW pipe producers serving shipbuilder export demand. |
| Environmental Product Declaration Certification | EPD coverage unlocks German and Dutch municipal water authority tender access under EU Green Deal procurement clauses. |
| Geographic Expansion into Western India Corridor | Gujarat and Maharashtra industrial buildouts concentrate ASTM A53 and BIS IS 1239 compliant pipe procurement. |
| Full-Service Coating-to-Fabrication Partnerships | Single-source bundling displaces fragmented procurement for Indian construction contractors seeking threaded and cut structural pipe. |
Research Methodology
Bottom-up infrastructure project modeling reconciled against top-down flat steel capacity tracking forms the analytical core of this study. Primary interviews with continuous galvanizing line operators, municipal utility procurement officers, EPC contractors, and zinc alloy suppliers were validated against secondary sources including customs trade data, EPA stormwater regulation filings, EU Construction Products Regulation disclosure databases, and BIS certification registries. Triangulation across stakeholder inputs and documentary sources ensures dimensional consistency across product type, coating thickness, and end-use segmentation.
Input-output matrices map zinc consumption rates, furnace throughput parameters, and coil feedstock certification tiers to volume and value outputs across the projection horizon. Segmentation dimensions modeled include pipe geometry, coating mass category, application intensity, and regional regulatory cluster. CAGRs were derived from infrastructure investment pipeline analysis and steel-intensive construction spend patterns. Forecast inputs incorporate dual carbon compliance timelines for Chinese galvanizing furnaces and PLI scheme disbursement trajectories for Indian specialty steel capacity.
Inputs from customs databases and certification registries were available through the study window; gaps in real-time zinc bath chemistry disclosure from proprietary furnace systems introduce uncertainty bands around coating uniformity assumptions. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and infrastructure tender award velocities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Granite Market
Building Materials
Cement Board Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Spain Cement Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Fireproof Cladding Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Building Asphalt Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
India Cement Market
Building Materials
Aluminum Door and Window Market
Building Materials
Global White Cement Market
Building Materials
Portland Cement Market