
 United States Architectural Coatings Market | 2026-2036
United States Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United States Architectural Coatings Market Analytics
Water-based resin systems is restructuring cost structures across the United States architectural coatings supply chain, displacing solvent-borne alternatives in premium interior and exterior segments. The Sherwin-Williams Company leverages its captive retail network and professional contractor loyalty programs to sustain pricing power in the pro channel. PPG Industries, Inc. anchors its position through backward integration into titanium dioxide and specialty additives manufacturing. Benjamin Moore & Co. differentiates via exclusive dealer relationships and architect-specified color systems in the luxury residential segment.
Architectural coatings are liquid or powder film-forming materials applied to building substrates for protection, decoration, or both, typically comprising binders, pigments, solvents or carriers, and functional additives that cure through evaporation, oxidation, or cross-linking to yield durable surface finishes. Acrylic formulations lead volume due to UV resistance and color retention in exterior applications across humid and high-sun regions. Water-based systems represent the fastest-growing formulation category as EPA VOC limits and state air quality regulations tighten solvent-borne market access. Matte and satin finish types occupy the largest share of residential interiors where hiding power and touch-up ease drive contractor preference.
EPA VOC regulations under 40 CFR Part 59, California Air Resources Board Suggested Control Measures, and OSHA worker exposure standards collectively constrain solvent-based product lines while accelerating low-VOC and zero-VOC certification requirements. The Federal Trade Commission Green Guides further shape marketing claims around environmental performance, influencing specifier and consumer trust. Stakeholders must monitor state-level regulatory divergence between California's stricter thresholds and federal baseline standards when allocating R&D and manufacturing capacity across their US footprint.
Market Dynamics
Water-based resin migration is compressing solvent-borne capacity utilization while redistributing formulation R&D budgets across the United States architectural coatings supply chain. EPA VOC limits under 40 CFR Part 59 and California's Suggested Control Measures are accelerating capital redeployment toward low-emission production assets.
Growth Catalysts
- Sun Belt Housing Renovation:Texas, Florida, and California homeowners are driving repaint cycles on aging residential stock built during the 1980s construction boom, sustaining above-average coating consumption per housing unit.
- 40 CFR Part 59 VOC Limits:Federal architectural coatings standards are forcing solvent-borne product line rationalization and opening shelf space for zero-VOC certified alternatives in big-box retail channels.
- Humidity-Driven Coating Cycles:Gulf Coast and Southeastern climate patterns accelerate exterior substrate degradation, compressing recoating intervals and expanding annual addressable volume in high-moisture metro corridors.
Market Restraints
- Titanium Dioxide Supply Concentration:Pigment production clusters in Mississippi and Louisiana create input cost volatility when hurricane disruptions idle chloride-process capacity, squeezing gross margins on white-base formulations.
- Freeze-Thaw Performance Gap:Water-based exterior systems still fail accelerated durability testing against solvent-borne alkyd benchmarks in Northern tier states, limiting year-round application windows and contractor willingness to switch.
- California-Only Formulation Complexity:CARB Suggested Control Measures enforce stricter VOC thresholds than federal baselines, forcing dual-SKU manufacturing and inventory duplication that inflates working capital requirements.
Strategic Opportunities
- Mountain West New Construction:Colorado, Utah, and Idaho permit volumes are outpacing national averages while coating penetration rates lag Sun Belt saturation, offering whitespace for specification capture in custom home segments.
- Infrared-Reflective Pigment Systems:Cool roof and cool wall coating demand is converging with energy code adoption across Arizona, Nevada, and Texas municipalities seeking urban heat island mitigation.
- Pro-Channel Digital Procurement:Contractor mobile ordering platforms are disintermediating traditional distributor call-in workflows, enabling direct manufacturer relationship building with mid-sized painting crews.
Industry Challenges
- Formulation Chemist Talent Pipeline:Waterborne polymer expertise is scarce among mid-career chemists trained on solvent-borne alkyd and urethane systems, extending new product development timelines by 12-18 months.
- Zero-VOC Certification Testing Backlogs:Third-party validation queues at certifying bodies are stretching launch schedules, delaying revenue recognition on reformulated product lines already manufactured.
- Legacy Distributor System Integration:ERP connectivity between manufacturer order management and independent dealer inventory systems remains fragmented, causing stockout miscommunication and lost specification opportunities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Architectural Coatings Market |
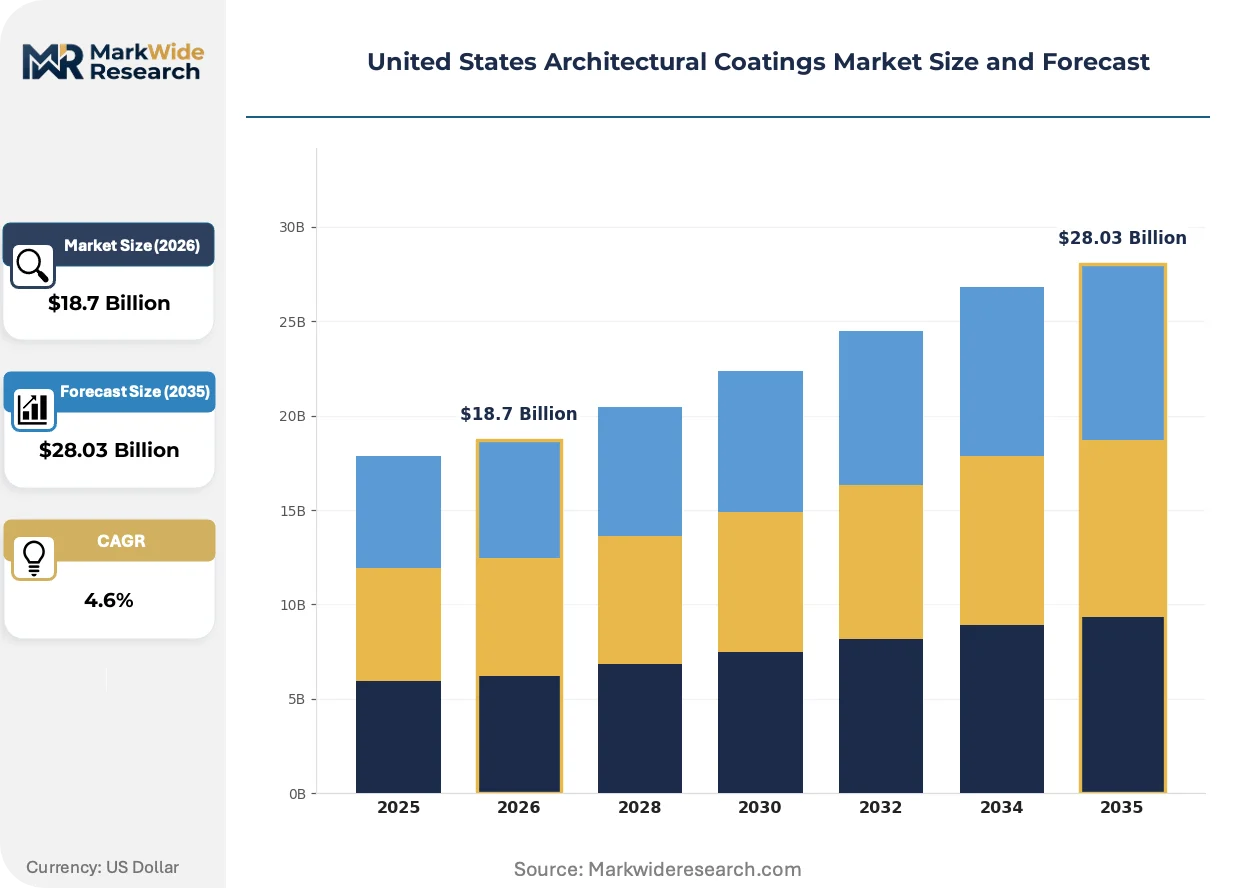
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Alkyd, Polyester, Polyurethane Application: Residential, Commercial, Industrial, Institutional Finish Type: Matte, Satin, Gloss, Semi-Gloss Formulation: Water-Based, Solvent-Based, Hybrid, Powder |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc., Benjamin Moore & Co., Behr Process Corporation, RPM International Inc., Masco Corporation, Axalta Coating Systems, Dunn-Edwards Corporation, AkzoNobel N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Architectural Coatings Market Evolving Landscape
Formulation chemistry, regulatory compliance architecture, and contractor procurement behavior are simultaneously transforming how coating value flows through the United States market. Three distinct vectors are compressing legacy competitive advantages while opening new specification pathways.
Self-crosslinking acrylic emulsion technology is decentralizing the performance hierarchy between water-based and solvent-borne exterior finishes. Custom home builders in Dallas-Fort Worth and Phoenix metro markets are specifying these systems for high-UV exposure elevations where alkyd dominance once seemed unassailable. The technology is decentralizing premium performance claims away from oil-based incumbents and toward specialty resin suppliers with patented ambient-cure chemistry.
California Air Resources Board Suggested Control Measures are tightening VOC thresholds for flat, non-flat, and specialty coatings on staggered implementation schedules. Manufacturers are consolidating California-dedicated production lines at fewer facilities to amortize compliance capital across higher throughput volumes. Southern California commercial repaint contractors are absorbing price premiums on compliant products and passing through costs to property management clients with limited alternative sourcing.
Large painting contractors are consolidating material procurement through manufacturer-direct rebate programs that bypass traditional distributor markup layers. Multi-crew operators in Houston and Miami-Dade are negotiating annual volume commitments in exchange for dedicated color-matching support and job-site delivery logistics. This concentration is visible most acutely in the Sun Belt where Hispanic-owned contracting businesses have scaled to 50-plus employee operations with centralized purchasing authority.
United States Architectural Coatings Market Segmentation
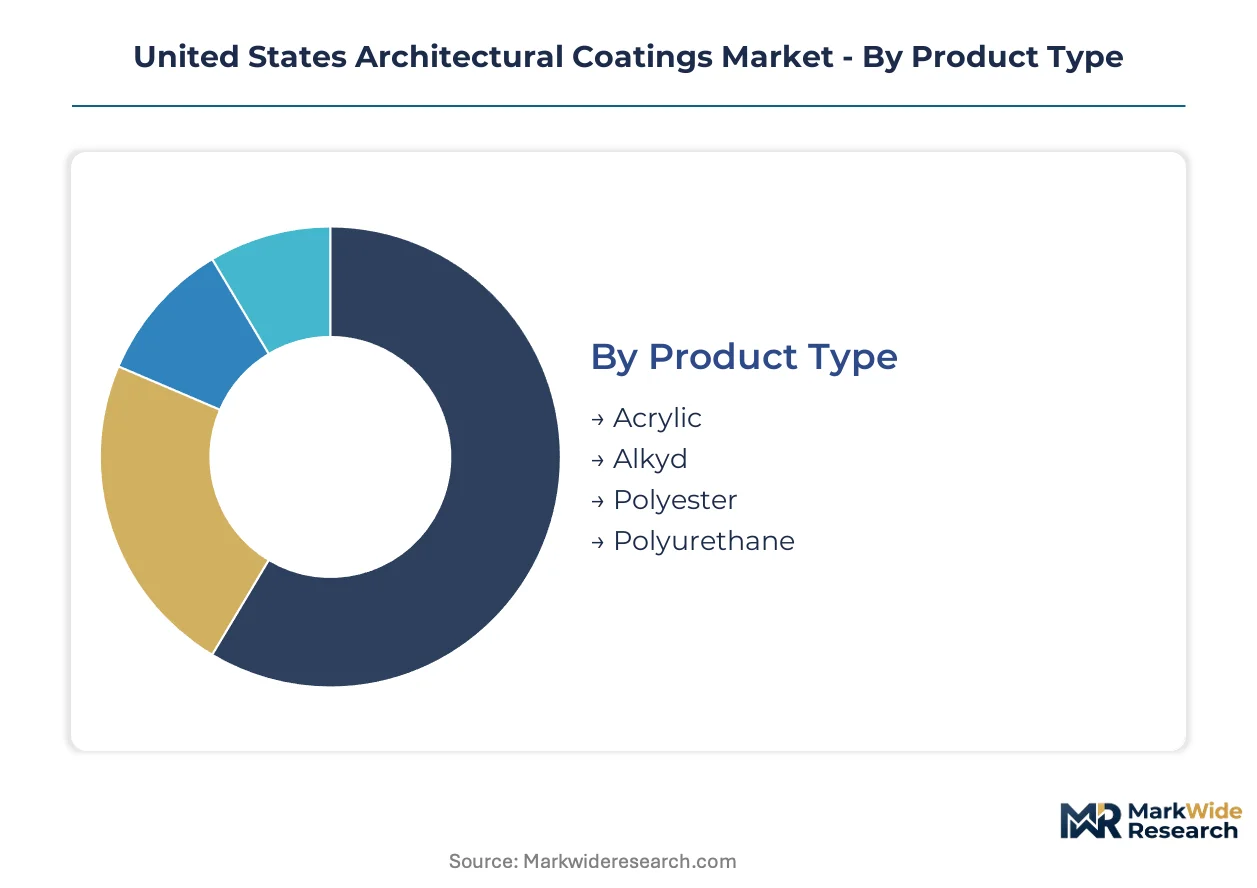
Architectural coatings segmentation reveals how formulation chemistry, substrate requirements, and aesthetic preferences fragment demand across distinct procurement channels. Understanding these divisions exposes where specification power concentrates and where margin compression threatens incumbent positions.
Product Type:
Upgrade cycles on aging residential stock in Sun Belt states are redistributing volume across resin chemistries as contractors balance durability claims against application windows.
- Acrylic:Thermoplastic resin systems deliver UV stability and color retention through oxidative crosslinking without yellowing. Demand clusters in Florida and Arizona exterior applications where intense solar exposure degrades alkyd alternatives prematurely.
- Alkyd:Oil-modified polyester binders cure through oxidation to form hard, solvent-resistant films. Texas and Gulf Coast contractors specify these for trim and door applications where waterborne systems still fail humidity-resistance benchmarks.
- Polyester:Saturated backbone resins provide chemical resistance in institutional maintenance coatings.
- Polyurethane:Two-component systems dominate industrial floor and high-traffic commercial specifications.
Acrylic sits at the top of the volume ranking, with waterborne acrylic emulsions climbing the fastest as EPA VOC limits tighten.
Application:
Customer procurement scale and specification authority vary dramatically across building types, concentrating margin in channels with centralized purchasing.
- Residential:Single-family repaint and new construction absorb the majority of gallons, with Sun Belt homeowners driving above-average consumption per housing unit. California's aging 1980s housing stock sustains recoating intervals below national averages.
- Commercial:Property management firms and retail chains negotiate national accounts with manufacturers, bypassing distributor markups through direct rebate structures.
- Industrial:Factory maintenance departments specify high-performance systems for corrosion protection.
- Institutional:School districts and healthcare facilities mandate low-odor, zero-VOC certifications for occupied-space applications.
Residential commands absolute volume leadership, while commercial procurement consolidation is gaining share fastest through pro-channel direct relationships.
Finish Type:
Sheen selection reflects the tension between aesthetic preference and substrate condition, with hiding power requirements dominating contractor specification behavior.
- Matte:Low-sheen films minimize surface defect visibility and touch-up lap marks. Interior residential walls in rental properties and mass-market housing rely on matte finishes where cost-conscious landlords prioritize maintenance ease over washability.
- Satin:Eggshell luster balances scrub resistance with forgiving application on imperfect drywall. Professional painters in suburban Atlanta and Phoenix metro markets specify satin as the default for owner-occupied homes.
- Gloss:High-sheen enamel systems dominate trim, cabinetry, and moisture-prone environments.
- Semi-Gloss:Moderate reflectance suits bathrooms, kitchens, and high-touch surfaces.
Matte holds the volume crown in residential interiors, with satin expanding most quickly as custom home specifications elevate sheen preferences.
Formulation:
Regulatory pressure and performance convergence are collapsing the traditional hierarchy between waterborne and solvent-borne systems.
- Water-Based:Acrylic and vinyl-acrylic emulsions displace solvent alternatives as self-crosslinking technology closes durability gaps. CARB Suggested Control Measures and EPA 40 CFR Part 59 are accelerating shelf-space reallocation in California and federal retail channels.
- Solvent-Based:Alkyd and urethane systems retreat to specialty exterior and industrial segments where waterborne freeze-thaw performance remains inadequate.
- Hybrid:Water-reducible alkyd and co-solvent systems bridge performance gaps in Northern tier climates.
- Powder:Thermoset coatings serve architectural metal and pre-finished building component applications.
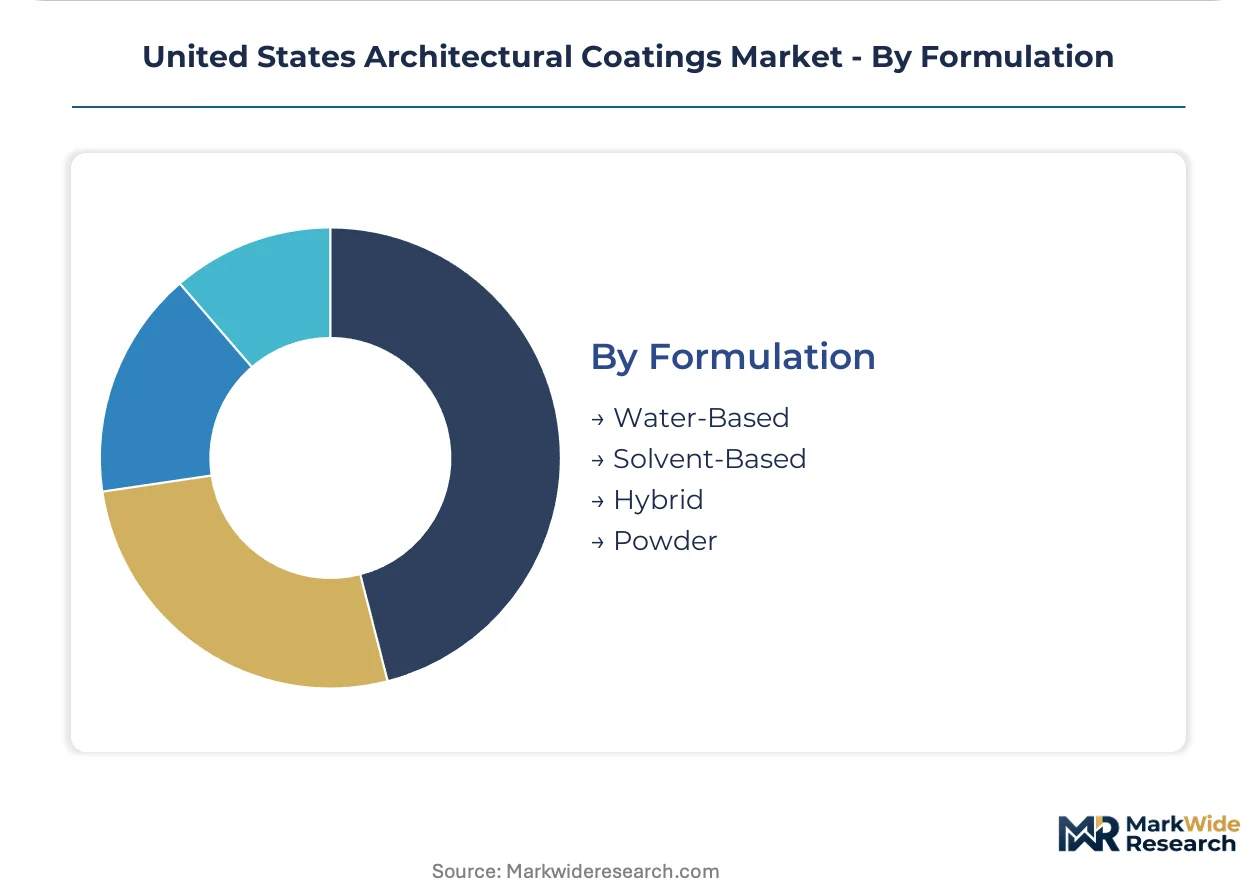
Water-based formulations dominate current volume, with hybrid systems showing the steepest expansion trajectory as manufacturers target climate-specific performance gaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gulf Coast petrochemical corridor anchors domestic resin supply for architectural coatings, with Texas and Louisiana housing the majority of acrylic emulsion and titanium dioxide production capacity that feeds downstream formulators nationwide.
Texas
Houston and Dallas-Fort Worth metro areas drive residential repaint demand from 1980s housing stock while permitting activity in Austin and San Antonio sustains new construction volume. EPA 40 CFR Part 59 compliance costs are accelerating water-based formulation adoption among regional contractors. The Houston Ship Channel chemical complex supplies captive acrylic monomer to local coating manufacturers.
California
Los Angeles and San Francisco Bay Area property owners sustain below-average recoating intervals on aging stucco and wood substrates exposed to marine air and seismic stress. CARB Suggested Control Measures enforce stricter VOC thresholds than federal baselines, forcing dedicated production lines and inventory segmentation. San Diego and Orange County commercial repaint contractors absorb price premiums on zero-VOC certified systems.
Florida
Miami-Dade and Tampa Bay humidity cycles compress exterior coating lifespans, driving above-average annual consumption per housing unit. State-level air quality mandates align with federal EPA standards but local building codes emphasize mold-resistant formulations for coastal applications. Orlando and Jacksonville new construction permits sustain volume growth in the pro-channel segment.
Illinois and Michigan
Chicago and Detroit metro markets present distinct seasonal constraints, with freeze-thaw performance gaps in water-based systems limiting winter application windows. OSHA worker exposure standards govern contractor safety protocols during indoor commercial repaint projects. Cleveland and Milwaukee distributor networks maintain hybrid inventory mixes serving Northern tier climate requirements.
Arizona and Nevada
Phoenix and Las Vegas extreme UV exposure and thermal cycling drive specification toward infrared-reflective pigment systems for cool roof and cool wall applications. Municipal energy codes in Tucson and Reno mandate solar reflectance index thresholds for commercial building envelopes. Regional formulators partner with resin suppliers on self-crosslinking acrylic emulsions targeting high-elevation durability benchmarks.
United States Architectural Coatings Market Competitive Landscape
Capacity redeployment toward low-VOC production assets dominates the current landscape as manufacturers rationalize legacy solvent-borne infrastructure. The market structure concentrates around three tiers: integrated chemical conglomerates with captive raw material supply, specialty coating formulators with regional specification relationships, and private-label suppliers serving big-box retail channels. Strategic archetypes include backward-integrated pigment producers, pro-channel direct sellers with contractor loyalty programs, and exclusive dealer network operators. Competitive moves center on manufacturing footprint consolidation and digital procurement platform development.
Within the integrated chemical tier, The Sherwin-Williams Company and PPG Industries, Inc. exemplify divergent route-to-market strategies. The former anchors position through captive retail infrastructure and professional contractor direct relationships, while the latter leverages upstream control over titanium dioxide and specialty additives manufacturing. Benjamin Moore & Co. occupies the exclusive dealer network archetype, sustaining specification influence through architect-directed color systems and limited distribution geography.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| Benjamin Moore & Co. |
| Behr Process Corporation |
| RPM International Inc. |
| Masco Corporation |
| Axalta Coating Systems |
| Dunn-Edwards Corporation |
| AkzoNobel N.V. |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap formulators with multi-generational dealer relationships anchor supply discipline across the United States architectural coatings market, translating captive distribution loyalty into pricing power that resists big-box commoditization. Their concentrated ownership structures enable long-term contract negotiations with titanium dioxide suppliers that insulate margin positions from spot-market volatility.
Pricing Analysis
Input-cost pass-through from titanium dioxide and acrylic monomer suppliers dominates pricing behavior, with Gulf Coast petrochemical disruptions immediately transmitting to white-base formulation premiums. Three-tier pricing structure across premium, standard, and economy levels separates architect-specified systems from contractor-grade bulk purchases and private-label retail offerings. Pricing pressure stems from water-based formulation R&D amortization costs as manufacturers recoup compliance capital deployed under EPA 40 CFR Part 59. Commercial property management firms exhibit lowest price sensitivity due to national account rebate structures, while residential DIY consumers in mass-market channels absorb price increases most reluctantly.
Supply Chain Analysis
Zero-VOC certification requirements under CARB Suggested Control Measures and EPA standards gate supplier qualification, compressing the approved vendor list for resin and additive sourcing. Production clusters in Texas, Louisiana, and Mississippi feed acrylic emulsion and titanium dioxide supply that draws from Gulf Coast chemical complexes. Raw material dependencies center on petroleum-derived monomers, chloride-process pigment, and specialty functional additives. Single-source vulnerability concentrates in hurricane-exposed titanium dioxide capacity on the Louisiana coast. Distribution runs through independent dealer networks in the pro channel and big-box retail partnerships for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States architectural coatings market offers margin-expansion pathways through water-based formulation scale economies and premium-tier specification capture in architect-directed channels. Manufacturers that consolidate California-dedicated production lines can amortize compliance costs across higher throughput volumes.
For Market Incumbents: Anticipate pro-channel digital procurement consolidation by accelerating mobile ordering platform deployment before mid-sized contractors centralize purchasing authority. Defensive moves require captive retail infrastructure reinforcement against distributor disintermediation and self-crosslinking acrylic emulsion R&D investment to close remaining solvent-borne performance gaps. Waterborne polymer chemist scarcity represents the critical talent bottleneck threatening new product launch timelines. For New Entrants and Emerging Players: Regional formulators in the Mountain West present the most penetrable white-space opportunity, with Colorado and Utah permitting activity outpacing coating penetration rates. Target custom home segments where specification relationships remain unsettled and infrared-reflective pigment systems offer differentiation against incumbent commodity offerings. A go-to-market angle anchored in cool roof and cool wall energy code compliance can bypass entrenched contractor loyalty programs. For Investors and Strategic Acquirers: Specialty chemical conglomerates with captive resin supply are the most active acquirer in this space, seeking regional formulators with established pro-channel relationships. Long-term viability rests on water-based technology transition completion and regulatory compliance architecture durability. Acquisition target archetypes include California-dedicated production facilities with CARB-validated product lines and Hispanic-owned contracting businesses with scaled purchasing authority. The signal to watch is third-party zero-VOC certification testing queue length as a real-time indicator of new product launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide | Captive pigment supply insulates margin positions from Gulf Coast hurricane disruptions. |
| California Production Line Consolidation | Dedicated CARB-compliant capacity amortizes compliance capital across higher throughput volumes. |
| Pro-Channel Digital Procurement Platform | Mobile ordering disintermediates distributor markups and builds direct contractor relationships. |
| Self-Crosslinking Acrylic Emulsion R&D | Ambient-cure chemistry closes durability gaps against solvent-borne alkyd benchmarks. |
| Infrared-Reflective Pigment System Launch | Cool roof and cool wall specifications align with Arizona and Nevada municipal energy codes. |
Research Methodology
Direct dialogue with coating plant managers, professional painting contractors, architectural specification consultants, and independent dealer owners grounded qualitative findings in operational reality. Secondary validation drew from EPA 40 CFR Part 59 regulatory filings, California Air Resources Board enforcement data, SEC 10-K disclosures from publicly traded manufacturers, and American Coatings Association industry statistics. Bottom-up volume modeling triangulated against top-down market sizing approaches.
Bottom-up demand modeling segmented the United States architectural coatings market by resin chemistry, formulation type, finish sheen, and regional climate zone across the projection horizon. Analytical frameworks incorporated housing permit velocity, recoating interval compression in humid regions, and regulatory implementation schedules. CAGRs derived from regression analysis against construction activity indices and VOC compliance cost curves. Forecast inputs included Sun Belt demographic migration patterns and water-based technology adoption S-curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA regulatory enforcement intensity and hurricane frequency disrupting Gulf Coast chemical production. Model assumptions reflect current CARB Suggested Control Measures thresholds and federal baseline standards. A model refresh is warranted upon material change in titanium dioxide supply concentration or self-crosslinking acrylic emulsion performance certification benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Basalt Rock Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Foam Concrete Market
Building Materials
Earthen Plasters Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
United Kingdom White Cement Market
Building Materials
Fiber Cement Market
Building Materials
Steel Sleepers Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
India Cement Market
Building Materials
East Africa White Cement Market
Building Materials
Rubbing Bricks Market
Building Materials
West Africa Cement Market
Building Materials
Africa Aluminum Door and Window Market