
 Building and Construction Sealants Market | 2026-2036
Building and Construction Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Building and Construction Sealants Market Intelligence
High-performance hybrid formulations is reorganizing competitive dynamics across the building and construction sealants industry. Sika AG leverages its integrated supply chain for silyl-modified polymers to dominate specification-grade commercial projects. BASF SE anchors its position through captive production of specialty acrylic monomers that feed water-based sealant lines.
Building and construction sealants are elastomeric compounds, typically formulated from silicone, polyurethane, or hybrid polymers, that cure to flexible solids capable of accommodating joint movement from negative twenty to plus one hundred eighty degrees Celsius while maintaining adhesion and impermeability. Their primary function is to prevent air and moisture infiltration at building envelope interfaces, thereby protecting structural integrity and thermal performance. Silicone sealants command the largest share of facade and glazing applications due to superior UV resistance and movement accommodation. Water-based acrylics compete aggressively in interior wall segments where low odor and paintability offset modest elasticity. Silyl-modified and hybrid technologies represent the fastest-expanding technology category as manufacturers bridge the performance gap between polyurethanes and silicones.
The EPA regulates VOC emissions under architectural coatings rules, while REACH and the EU Green Deal impose substance restrictions and carbon-footprint disclosure requirements on sealant formulations sold in Europe. China's MEE enforces GB standards for formaldehyde and VOC limits in construction materials, compelling domestic producers to reformulate solvent-based products. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and secure type-approval for next-generation low-carbon chemistries.
Market Dynamics
The EU F-Gas Regulation and REACH substance restrictions are decomposing incumbent solvent-based sealant portfolios, compelling manufacturers to reconfigure formulation pipelines around water-based and silyl-modified chemistries.
Growth Catalysts
- Retrofit mandates:Germany's Building Energy Act and parallel efficiency programs in China and the United States are accelerating procurement of high-performance hybrid sealants for window-to-wall joint remediation in aging commercial envelopes.
- REACH Phase-In Substances:European substance restriction timelines are pulling forward demand for compliant low-VOC alternatives, compressing specification windows for reformulated products.
- Hybrid polymer R&D:Silyl-modified polymer platforms are bridging the performance gap between polyurethanes and silicones, opening specification-grade bridge and tunnel projects previously reserved for silicone.
Market Restraints
- Petrochemical feedstock volatility:Polyether polyol and silicone precursor costs swing with crude and natural gas indices, compressing margin stability for mid-tier producers without captive supply.
- Technical performance ceiling:Water-based acrylics remain limited to interior applications due to poor UV resistance and movement accommodation below fifty percent, capping addressable share in facade systems.
- Regulatory fragmentation:Divergent VOC limits between EPA architectural coatings rules, EU F-Gas Regulation, and China's GB standards strand inventory and multiply type-approval costs.
Strategic Opportunities
- Underpenetrated prefabrication:Modular construction adoption in the United States and Germany creates demand for factory-applied sealant systems with controlled-cure specifications.
- Carbon disclosure tailwinds:EU Green Deal embodied carbon reporting requirements favor low-carbon silyl-modified formulations with verified lifecycle data.
- Digital specification channels:Building information modeling platforms are displacing traditional distributor relationships, enabling direct manufacturer-to-architect engagement on performance data.
Industry Challenges
- Formulation chemist scarcity:Expertise in hybrid polymer synthesis and regulatory-compliant solvent substitution concentrates at a handful of specialized suppliers.
- Certification timeline compression:Accelerated EU F-Gas phase-down schedules compress testing and approval windows for replacement chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Building and Construction Sealants Market |
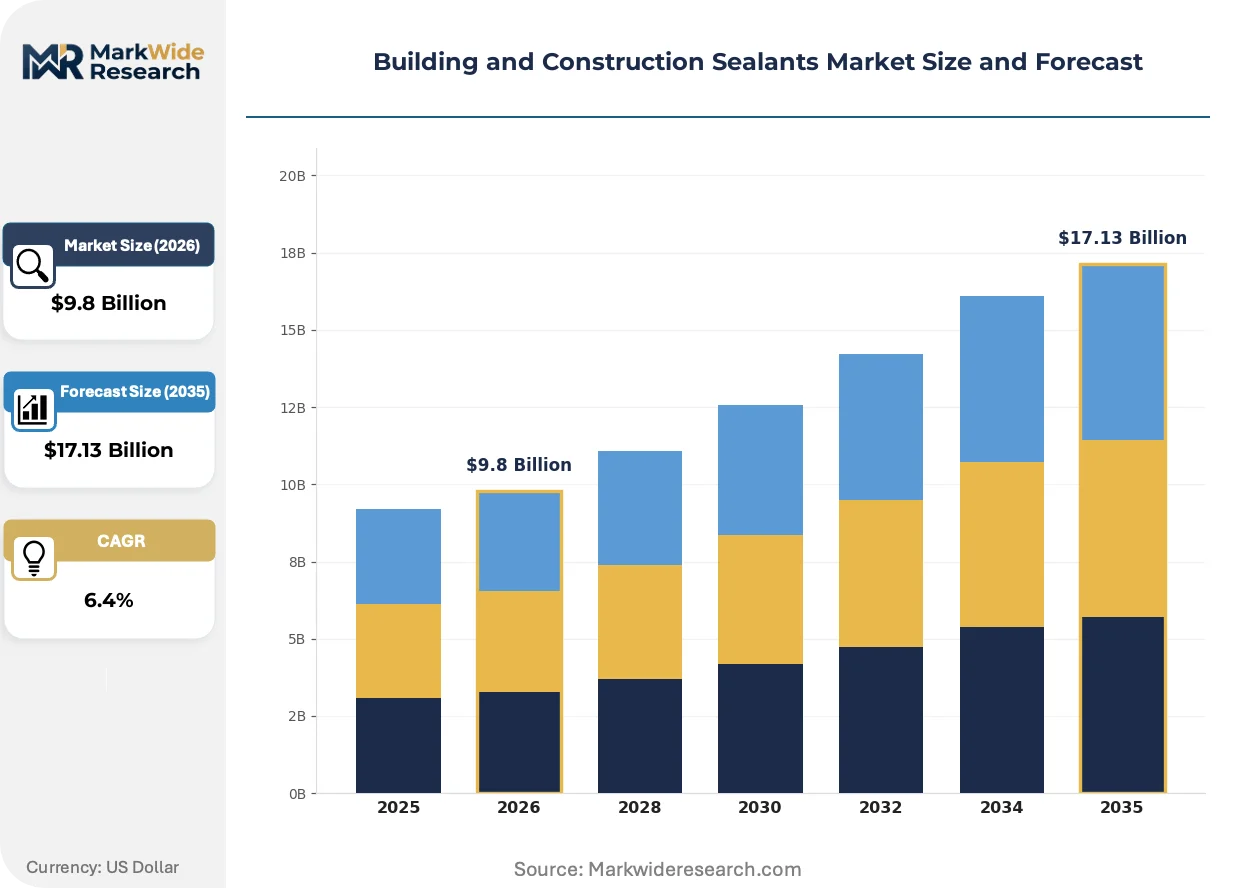
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone, Polyurethane, Acrylic, Polysulfide, Butyl, Epoxy Technology: Solvent-Based, Water-Based, Hybrid, Hot Melt, Silyl Modified, Reactive Application: Facade Sealants, Expansion Joints, Interior Wall, Floor & Roof, Glazing, Plumbing End User: Commercial Contractors, Residential Builders, Infrastructure Developers, Renovation Specialists |
| Companies Covered | 3M Company, H.B. Fuller Company, Sika AG, Bostik, Mapei S.p.A., Henkel AG & Co. KGaA, BASF SE, Wacker Chemie AG, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Building and Construction Sealants Market Strategic Shifts & Innovations
Reformulation pressure is fragmenting technology roadmaps across the building and construction sealants industry, with manufacturers diverging toward water-based, silyl-modified, and bio-based platforms rather than converging on a single successor chemistry.
Hybrid polymer technology is decomposing the traditional silicone-polyurethane duopoly in structural glazing and expansion joint applications. Façade engineers specify silyl-modified systems for movement accommodation exceeding one hundred percent with paint compatibility silicone cannot match. The technology is compressing specification premiums previously commanded by high-modulus silicones in commercial high-rise envelopes.
REACH authorization requirements and the EU F-Gas Regulation are eliminating hydrofluorocarbon blowing agents and certain isocyanate precursors from polyurethane sealant formulations. European manufacturers face reformulation deadlines that outpace alternative raw material qualification cycles. Water-based acrylic and hybrid lines capture specification share in interior and light commercial segments where solvent-based polyurethanes previously dominated.
Building information modeling workflows are displacing traditional distributor-led specification processes for commercial envelope sealants. Architects and contractors embed performance data directly into digital twins, compressing the role of regional distributors in technical consultation. Germany and the United States exhibit the fastest channel transformation as large commercial developers mandate BIM compliance for supplier qualification.
Building and Construction Sealants Market Segmentation
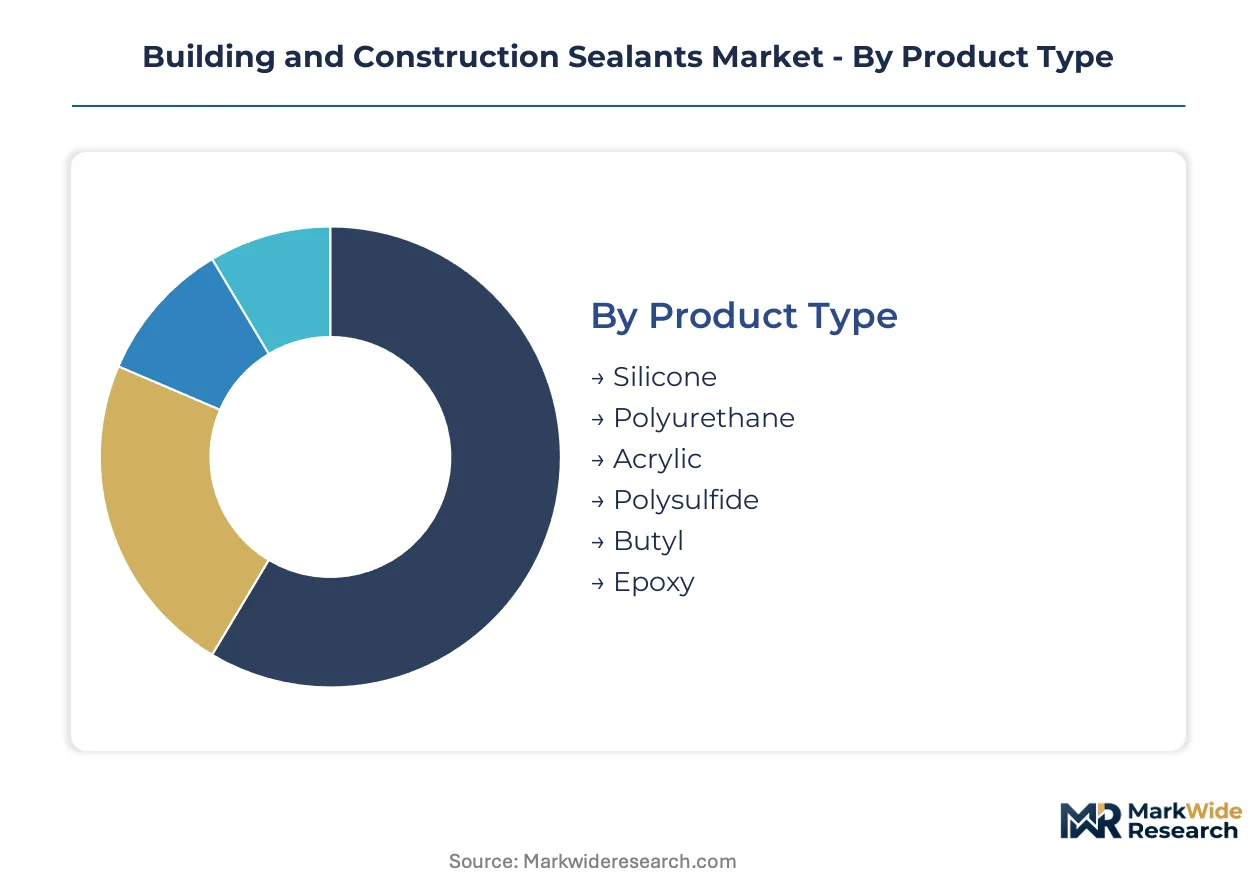
Segmentation in building and construction sealants reveals how formulation chemistry, cure technology, and application environment intersect to determine procurement patterns. Specification-grade commercial envelopes demand hybrid and silicone systems with validated movement accommodation, while residential and renovation channels trade performance for cost and ease of application.
Product Type:
Domestic production concentrates silicone and polyurethane in Germany, China, and the United States for regional building envelope specifications. Export-led segments like polysulfide and butyl serve specialized infrastructure and industrial markets with concentrated demand in Gulf states and Southeast Asian tunnel projects.
- Silicone:Formulated from polydimethylsiloxane polymers with tin or platinum cure systems, delivering UV stability and movement accommodation exceeding one hundred percent. Demand clusters in German and Chinese commercial high-rise glazing where the EU Green Deal and MEE carbon disclosure rules favor verified lifecycle performance. Sika AG and Dow dominate specification through captive siloxane supply.
- Polyurethane:Isocyanate-terminated prepolymers crosslink with atmospheric moisture to form elastomeric solids with high tensile strength and abrasion resistance. Infrastructure developers in the United States specify polyurethane for bridge expansion joints subject to AASHTO load cycles, though REACH isocyanate restrictions are compressing European specification windows.
- Acrylic:Water-based emulsions of acrylic and methacrylic monomers cure through evaporation to form paintable, low-odor films with modest elasticity. Interior wall remediation in German residential retrofits under the Building Energy Act drives volume.
- Polysulfide:Liquid polysulfide polymers with manganese dioxide cure chemistry deliver exceptional fuel and chemical resistance. Export demand from Saudi Arabian airport and fueling infrastructure projects sustains specialized production.
- Butyl:Isobutylene-isoprene copolymers remain permanently tacky, providing vapor barriers and bedding compounds. Prefabricated panel manufacturers in the United States specify factory-applied butyl tapes for controlled-cure assembly lines.
- Epoxy:Bisphenol-A or novolac resins with amine hardeners form rigid, high-strength bonds with negligible movement accommodation. Industrial flooring and structural anchoring in Chinese manufacturing facilities consume volume despite brittleness constraints.
Silicone commands the established base. The steepest expansion runs through hybrid-modified acrylic and silyl-terminated polyurethane bridges.
Technology:
Cost tier stratification separates specification-grade reactive and silyl-modified systems from commodity water-based and hot-melt alternatives. Premium tiers carry three to fivefold formulation cost multiples justified by performance guarantees and warranty extension.
- Solvent-Based:Hydrocarbon or ester carriers dissolve high-solids polyurethane and acrylic resins for deep substrate penetration and rapid tack. EPA architectural coatings VOC limits and EU F-Gas Regulation are decomposing this category in Germany and the United States, stranding inventory and forcing reformulation.
- Water-Based:Acrylic and polyurethane dispersions in aqueous phase deliver low odor, easy cleanup, and paint compatibility. German interior contractors specify water-based systems for occupied building retrofits under strict worker exposure protocols.
- Hybrid:Silyl-modified polyurethane or polyether backbones combine silicone UV resistance with polyurethane mechanical strength. Chinese infrastructure developers specify hybrid systems for high-speed rail tunnel joints requiring fifty-year service life under GB durability standards.
- Hot Melt:Thermoplastic polyamide and polyolefin formulations applied molten and cooling to flexible solids. Prefabricated construction in the United States adopts hot-melt butyl and polyisobutylene systems for factory-controlled application consistency.
- Silyl Modified:Trimethoxysilyl-terminated polymers cure by moisture to release methanol, forming silicone-like networks without tin catalysts. BASF and Sika anchor European production for REACH-compliant commercial facades.
- Reactive:Two-component epoxy and polyurethane systems requiring metered mixing and controlled cure windows. Structural glazing and high-movement expansion joints in German and US commercial towers specify reactive systems for performance-critical applications.
Silyl-modified and hybrid platforms are gaining share fastest. Solvent-based lines retain residual volume in price-sensitive export markets with lagging regulatory enforcement.
Application:
Volume concentration tracks new construction intensity, with facade and glazing dominating Chinese and US commercial starts. Margin concentration sits in expansion joints and specialized remediation where engineering specification commands premium pricing.
- Facade Sealants:Exterior weatherproofing of curtain wall and cladding interfaces demands UV-stable, dirt-resistant elastomers with validated movement cycling. German commercial retrofits under the Building Energy Act accelerate procurement of low-carbon hybrid formulations with EPD certification.
- Expansion Joints:Structural gaps accommodating thermal and seismic movement require high-modulus, fatigue-resistant compounds. US infrastructure developers specify polyurethane and silicone hybrids for bridge decks subject to AASHTO thermal cycling protocols.
- Interior Wall:Paintable, low-odor acrylic emulsions seal perimeters and penetrations in occupied buildings. German residential renovation specialists drive volume through efficiency program mandates.
- Floor & Roof:Traffic-bearing polyurethane and polysulfide systems waterproof podium decks and parking structures. Chinese mixed-use developments in tier-one cities specify solvent-free polyurethane for podium waterproofing under MEE VOC enforcement.
- Glazing:Structural and weatherseal silicones bond glass to framing while accommodating wind load deflection. US commercial high-rise construction sustains demand for high-modulus structural silicones with ASTM C1184 validation.
- Plumbing:Sanitary-grade silicones and hybrid sealants resist mold growth and maintain adhesion in wet conditions. Residential builders in Germany specify biocide-free formulations under BfR recommendations for indoor air quality.
Facade and glazing anchor revenue concentration. Expansion joints represent the steepest margin expansion trajectory as infrastructure age accumulates.
End User:
Customer type determines specification authority and procurement channel. Commercial contractors and infrastructure developers wield direct manufacturer engagement through BIM platforms, while residential builders and renovation specialists route through distributor networks with compressed technical consultation.
- Commercial Contractors:Envelope specialists managing curtain wall, glazing, and cladding installation for office, retail, and institutional projects. US and German general contractors mandate BIM-compliant sealant specification with embedded performance data and EPD transparency.
- Residential Builders:Single-family and multifamily construction firms prioritizing cost, availability, and code-minimum performance. Chinese residential developers specify commodity silicone and acrylic through consolidated procurement platforms serving tier-two and tier-three cities.
- Infrastructure Developers:Public and private entities delivering transportation, water, and energy infrastructure with century-scale durability requirements. German federal transport infrastructure specifications favor silyl-modified hybrids with verified carbon footprints under EU Green Deal procurement rules.
- Renovation Specialists:Contractors focused on energy retrofit, envelope remediation, and interior refresh of existing building stock. German renovation specialists capture Building Energy Act subsidies for window-to-wall joint remediation using low-VOC hybrid sealants.
Commercial contractors command specification-grade volume. Infrastructure developers are expanding procurement fastest as bridge and tunnel age accumulates across Germany, China, and the United States.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in construction sealants track regional regulatory divergence, with surplus capacity in Germany and China meeting deficit demand in infrastructure-heavy markets. Trade patterns increasingly favor low-carbon formulations as EU Green Deal carbon-border adjustments reshape procurement calculus.
United States
Bridge and tunnel rehabilitation drives specification-grade polyurethane and hybrid sealant demand across the Interstate Highway System. EPA architectural coatings rules enforce VOC limits that compress solvent-based product windows. Infrastructure clusters in Texas and California concentrate procurement for seismic expansion joint systems under AASHTO protocols.
Germany
The Building Energy Act mandates window-to-wall joint remediation in commercial retrofits, accelerating hybrid sealant specification. EU F-Gas Regulation and REACH substance restrictions eliminate hydrofluorocarbon blowing agents from polyurethane formulations. Industrial concentration in North Rhine-Westphalia and Bavaria anchors silyl-modified polymer production for compliant facade systems.
China
High-speed rail tunnel construction and tier-one city commercial development sustain silicone and hybrid sealant volume. MEE enforcement of GB standards for formaldehyde and VOC limits compels reformulation of solvent-based construction materials. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta dominate domestic supply for infrastructure and glazing applications.
Saudi Arabia
Airport, fueling infrastructure, and NEOM megaproject development sustain polysulfide and specialty sealant imports. SFDA and SASO construction material standards regulate chemical emissions in enclosed transportation environments. Eastern Province industrial cities concentrate demand for fuel-resistant jointing systems in petroleum handling facilities.
India
Urban metro expansion and commercial high-rise construction in Mumbai and Bangalore drive silicone and hybrid sealant procurement. BIS certification requirements for construction chemicals create compliance barriers for imported formulations. Gujarat and Maharashtra industrial corridors concentrate domestic manufacturing capacity for water-based acrylic interior systems.
Building and Construction Sealants Market Key Industry Players
Listed leaders compete with private specialists across formulation technology and specification authority in the building and construction sealants market. The competitive structure stratifies into three tiers: integrated chemical conglomerates with captive polymer supply, regional specialists with application engineering depth, and commodity formulators competing on price and availability. Strategic moves concentrate on hybrid polymer R&D partnerships and backward integration into silyl-modified resin production to secure margin stability against petrochemical feedstock volatility.
Among European-based chemical conglomerates, Sika AG and BASF SE exemplify the integrated archetype, anchoring competitive positioning through captive supply chains for performance polymers. Dow Inc. occupies a parallel position among North American players with siloxane production integration. These three companies represent the specification-grade tier where formulation expertise and regulatory compliance capabilities determine architect and contractor procurement decisions.
| Leading Market Players |
|---|
| 3M Company |
| H.B. Fuller Company |
| Sika AG |
| Bostik |
| Mapei S.p.A. |
| Henkel AG & Co. KGaA |
| BASF SE |
| Wacker Chemie AG |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Capacity utilization at German and Chinese siloxane plants shapes margin floors across specification-grade sealant tiers, concentrating pricing power with integrated producers while forcing mid-tier formulators into commodity water-based segments. This scale asymmetry compresses returns for non-integrated competitors and accelerates consolidation around captive polymer supply.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with specification-grade hybrid and silyl-modified systems commanding multiples justified by ASTM C1184 certification and warranty extension. Price differentiation stems from performance tier and volume scale, with bulk infrastructure contracts eroding list prices by fifteen to twenty percent. Cost compression in solvent-based tiers is intensifying because EPA architectural coatings rules and EU F-Gas Regulation strand inventory and force reformulation. Residential builders exhibit highest price sensitivity, while infrastructure developers accept premium positioning for verified fifty-year service life guarantees.
Supply Chain Analysis
BASF's Ludwigshafen complex and Dow's Midland siloxane facilities anchor global supply concentration for specialty monomers and prepolymers. Raw material flows draw from Saudi Arabian petrochemical feedstocks, Chinese methanol derivatives, and German specialty chemical intermediates. Single-source vulnerability concentrates in silyl-modified polymer platforms where formulation expertise clusters at Sika and Wacker Chemie. Distribution runs through specification-grade distributor networks for commercial contractors, while residential channels consolidate through big-box retail and direct procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Building and construction sealants are entering a cyclical recovery phase as deferred infrastructure maintenance accumulates across German, Chinese, and US transportation networks. Bridge and tunnel rehabilitation backlogs provide the demand floor for this upswing.
For Market Incumbents: Compound defensive positioning through backward integration into silyl-modified resin production and capacity addition in Yangtze River Delta manufacturing clusters. REACH authorization timelines and EU F-Gas phase-down schedules compress reformulation windows, threatening stranded inventory for non-compliant portfolios. Certification investment in EPD transparency and carbon disclosure protocols secures specification authority in EU Green Deal procurement.
For New Entrants and Emerging Players: Anchor in underpenetrated prefabricated construction segments in Germany and the United States, where factory-applied sealant systems lack established supplier relationships. Modular builders represent the most penetrable buyer archetype, with demand for controlled-cure hot-melt and butyl tape systems outpacing qualified supply. A direct-to-architect specification strategy through BIM platform integration bypasses entrenched distributor networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid polymer specialists with demonstrated regulatory compliance pathways and captive raw material access. Long-term viability hinges on five-to-ten year durability of silyl-modified platforms against bio-based alternatives. Watch MEE enforcement intensity on GB standards as the inflection signal for Chinese market access conditions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silyl-Modified Resins | Captive supply of hybrid polymer precursors insulates margin stability against petrochemical volatility. |
| EPD Certification Investment | Verified lifecycle data satisfies EU Green Deal embodied carbon reporting for commercial facade specifications. |
| BIM Platform Partnership | Direct manufacturer-to-architect engagement displaces traditional distributor-led specification processes. |
| Prefabrication Channel Development | Factory-applied sealant systems capture modular construction growth in Germany and the United States. |
| REACH-Compliant Formulation Pipeline | Alternative chemistry qualification ahead of substance restriction deadlines secures European market access. |
Research Approach
Operator-level perspectives from plant managers at sealant manufacturing facilities, procurement leads at commercial envelope contractors, distribution channel partners, and technical R&D directors anchored the qualitative base. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ASTM certification databases. Bottom-up volume modeling triangulated against top-down market sizing across product type, technology, application, and end-user segmentation dimensions.
Sensitivity analysis tested forecast robustness across petrochemical price scenarios, regulatory enforcement intensity variations, and infrastructure spending cycle assumptions. The analytical framework modeled silicone, polyurethane, acrylic, polysulfide, butyl, and epoxy product categories alongside water-based, solvent-based, hybrid, hot-melt, silyl-modified, and reactive technology tiers. CAGRs were derived from regression analysis of historical consumption patterns against construction starts and retrofit program funding levels. Key inputs included MEE GB standards enforcement timelines and German Building Energy Act subsidy allocation rates.
Underlying assumptions cover sustained infrastructure rehabilitation spending, stable REACH authorization timelines, and gradual MEE enforcement intensification, with deviation risk concentrated in petrochemical feedstock volatility and trade policy disruption. Practitioners should keep alternative scenarios live as EU carbon-border adjustment mechanisms and Chinese dual carbon policy implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Door System Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Bollard Market
Building & Construction Materials
Italy Oriented Strand Board Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market