
 Fire Hydrant System Market | 2026-2036
Fire Hydrant System Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Hydrant System Market Foresight
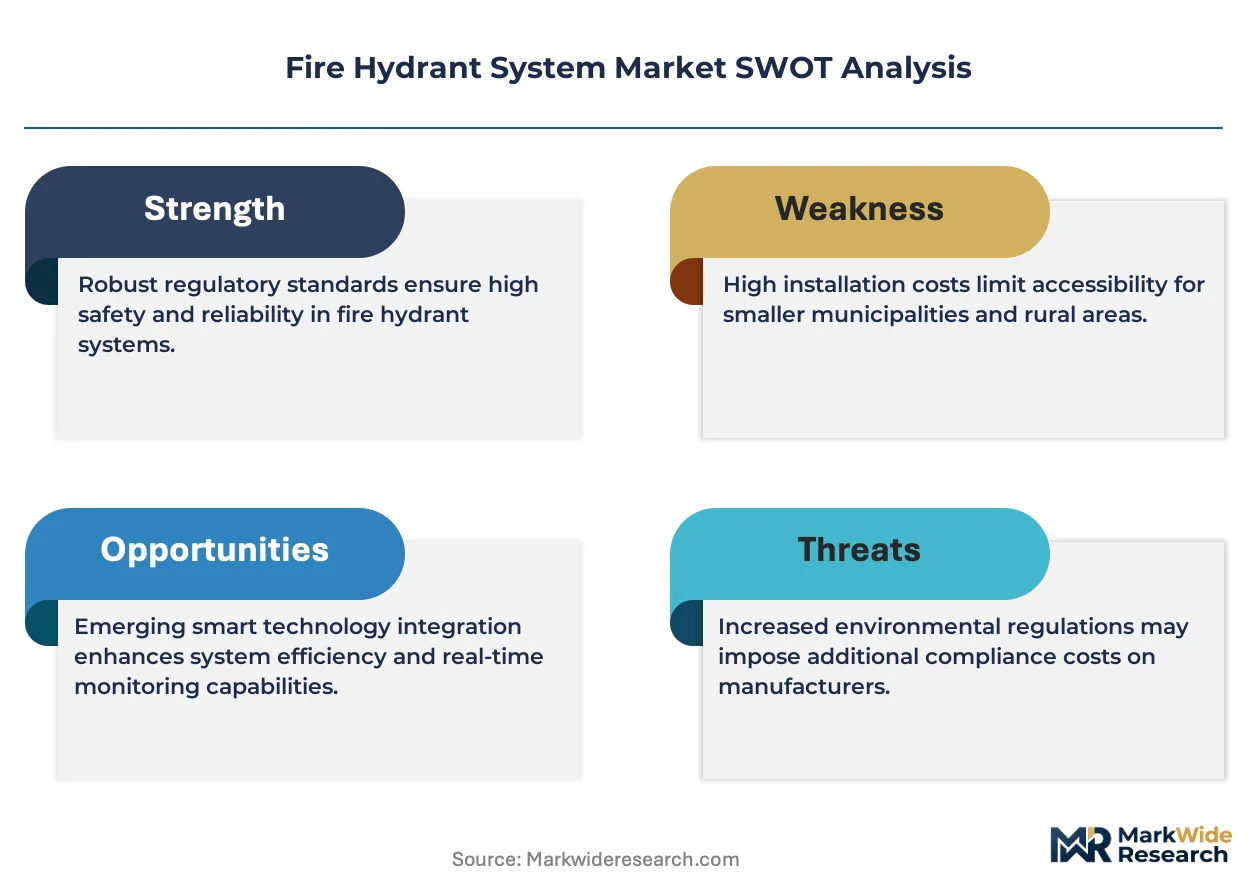
Smart pressure-monitoring and IoT-enabled leak detection is rewriting how fire hydrant networks are maintained and capitalized. Mueller Co. leverages its century-old foundry infrastructure to dominate ductile-iron casting for wet-barrel hydrants across the American Southwest. AVK International A/S competes through specialized coating technologies that extend corrosion resistance in coastal environments. Kupferle Foundry Company differentiates by concentrating on automatic flushing and monitoring attachments that retrofit legacy hydrants with telemetry capability.
A fire hydrant system comprises pressurized water delivery terminals, valve assemblies, and connecting mains engineered to provide instantaneous flow rates exceeding one thousand gallons per minute for fire suppression operations. Wet-barrel configurations dominate temperate climates where freezing is absent, while dry-barrel designs anchor cold-weather installations through drainable barrel construction that prevents ice damage. Industrial facilities and commercial buildings represent the fastest-growing application segments, driven by insurance-mandated upgrades and stricter local water authority inspections. New construction installations capture premium margin pools, though retrofit demand sustains volume across mature urban cores with century-old cast-iron networks.
NFPA standards, AWWA Manual M17, and EPA Lead and Copper Rule revisions collectively shape product specifications, material substitutions, and procurement timelines across North American utilities. Municipalities now disqualify hydrants with leaded bronze components, redirecting specification authority toward stainless-steel and no-lead brass alternatives that comply with Safe Drinking Water Act amendments. Stakeholders must monitor how federal infrastructure funding disbursement rules affect municipal bidding cycles and whether proposed AWWA flow-test digitization mandates accelerate telemetry attachment adoption.
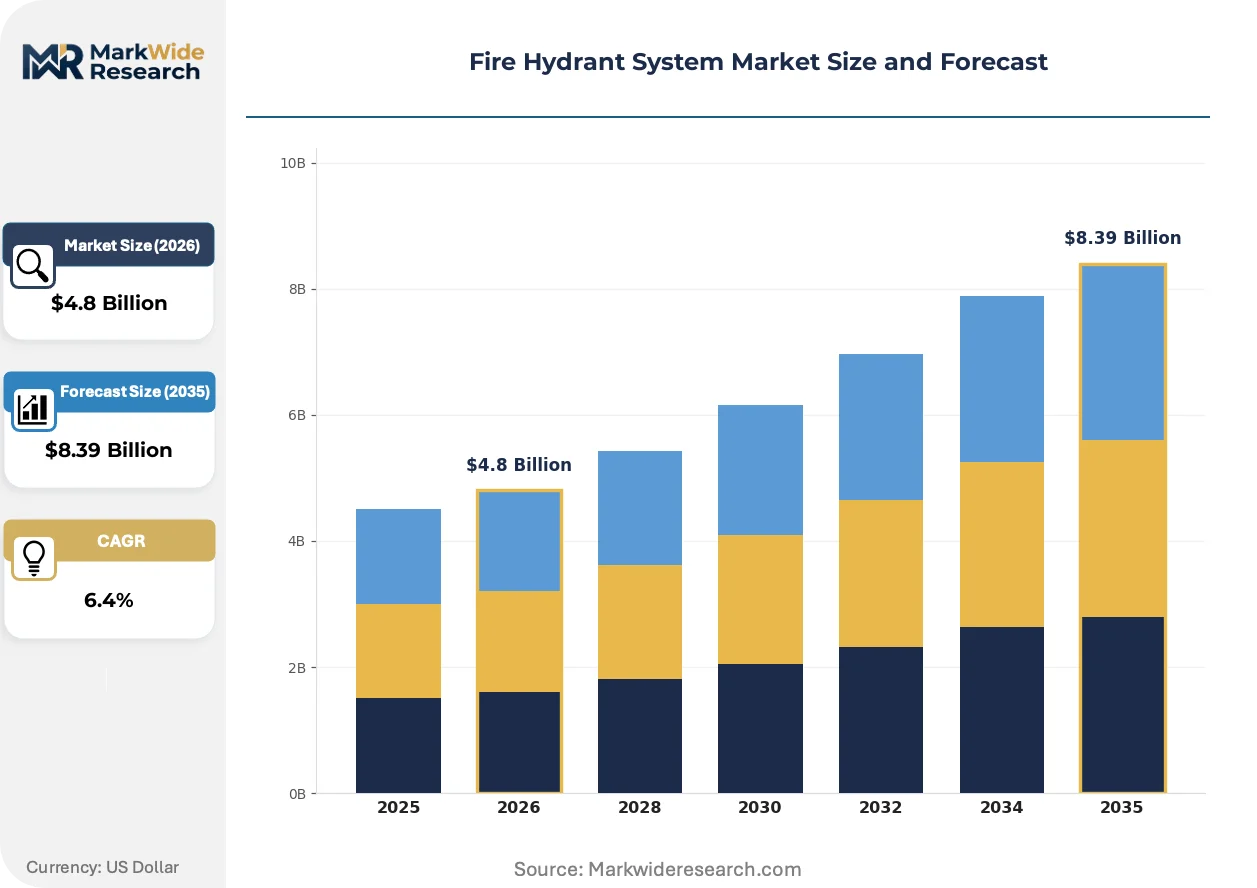
Market Dynamics
Municipal utilities across the United States face a convergence of aging cast-iron infrastructure and tightening AWWA flow-test digitization mandates, forcing capital allocation toward telemetry-enabled hydrant replacements rather than incremental repairs.
Growth Catalysts
- NFPA 291 Revisions:Stricter flow-test documentation requirements are compelling water authorities to replace obsolete hydrants with models capable of standardized digital reporting.
- Sun Belt Suburban Expansion:Rapid residential development in Texas, Arizona, and Florida is outpacing legacy fire protection capacity and driving new installation contracts.
- Lead-Free Material Mandates:EPA Lead and Copper Rule amendments are disqualifying leaded bronze components and redirecting procurement toward stainless-steel and no-lead brass alternatives.
Market Restraints
- Ductile-Iron Input Volatility:Foundry energy costs and scrap metal pricing swings compress margin predictability for wet-barrel hydrant manufacturers.
- Municipal Procurement Cycles:Federal infrastructure funding disbursement delays and multi-year bidding timelines extend revenue recognition periods.
- Technical Limitation of Legacy Mains:Century-old cast-iron connecting infrastructure in mature urban cores restricts pressure ratings for modern high-flow hydrant designs.
Strategic Opportunities
- Retrofit Telemetry Attachments:Automatic flushing and pressure-monitoring devices that upgrade existing hydrants without full replacement address budget-constrained utilities.
- Industrial Facility Insurance Mandates:Commercial property underwriters are requiring documented fire suppression capacity upgrades, creating specification authority outside municipal procurement.
- Coastal Corrosion-Resistant Coatings:Specialized epoxy and metallization technologies extend service life in salt-air environments where standard hydrants degrade prematurely.
Industry Challenges
- Certified Welder Shortage:AWWA-certified fabrication technicians are scarce in regions with concentrated replacement demand, extending lead times for custom barrel assemblies.
- Legacy System Integration:Telemetry-enabled hydrants must interface with heterogeneous SCADA architectures across fragmented municipal water districts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Hydrant System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wet Barrel, Dry Barrel, Post Indicator Valve, Hydrant Extension Application: Urban Areas, Industrial Facilities, Commercial Buildings, Educational Institutions End User: Fire Departments, Municipalities, Construction Companies, Property Managers Installation Type: Above Ground, Below Ground, Retrofit, New Construction |
| Companies Covered | Kennedy Valve Company, Clow Valve Company, Mueller Co., McWane International, EJ Group, American Cast Iron Pipe Company, Kupferle Foundry Company, Rapidrop Global, AVK International A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Hydrant System Market Shifts & Advancements
Digital instrumentation is embedding intelligence into passive infrastructure assets. Utilities now expect real-time pressure visibility and predictive maintenance alerts as standard procurement criteria.
Pressure transducers and cellular telemetry modules are virtualizing hydrant maintenance workflows. Water authorities in California and Texas are deploying these sensors at scale, replacing manual flow-test crews with continuous remote monitoring. This compression of inspection labor is reallocating municipal budgets toward preventive replacement programs.
AWWA Manual M17 updates and EPA corrosion control mandates are tightening material traceability requirements. Foundries must now document alloy composition through production lots, extending quality assurance timelines. Stainless-steel valve components are capturing specification share from traditional bronze in districts with aggressive lead-reduction targets.
Service contracts are unbundling from equipment sales as utilities seek operational expenditure flexibility. Third-party maintenance providers are assuming responsibility for flow-test compliance and telemetry calibration, displacing in-house municipal crews. This shift is most pronounced in mid-sized cities where staffing constraints limit technical specialization.
Fire Hydrant System Market Segmentation
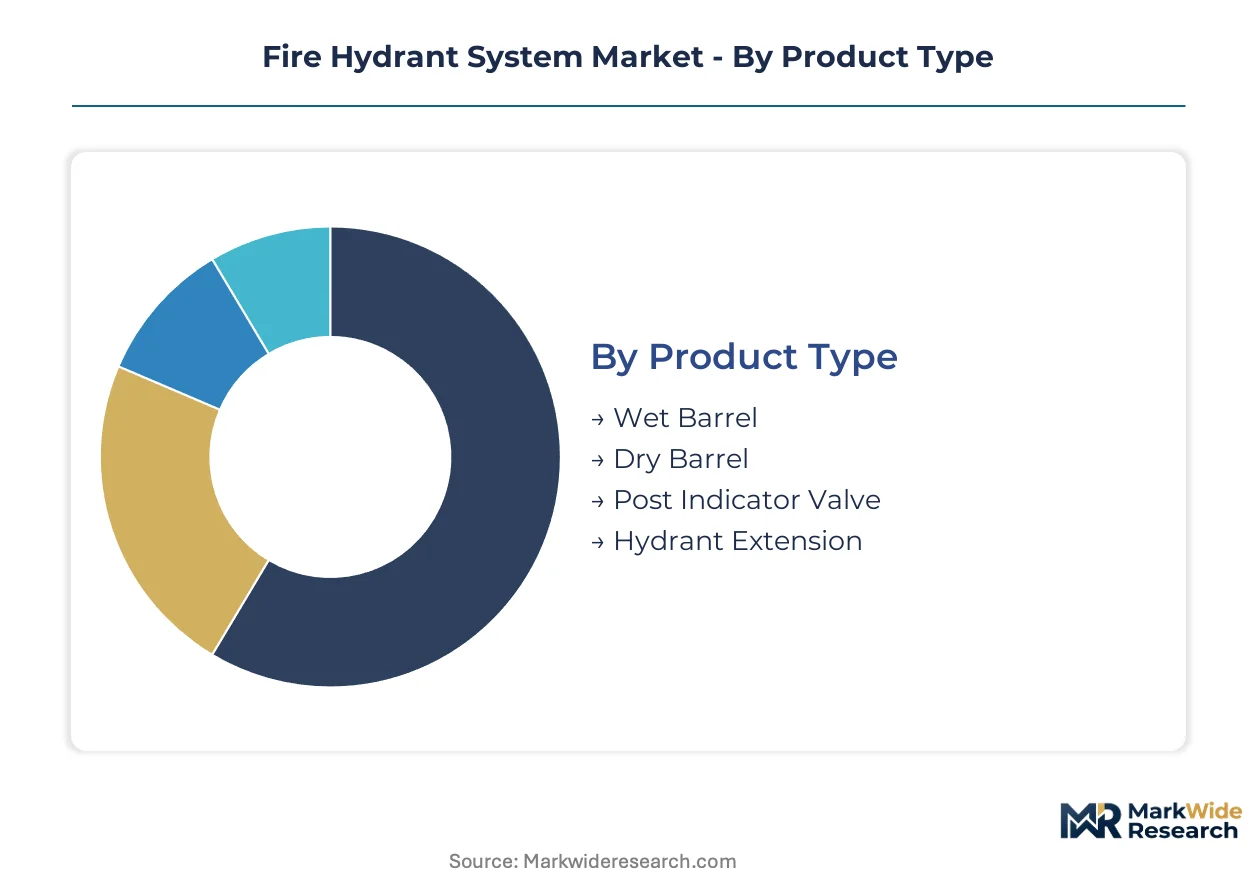
Fire hydrant system segmentation reveals distinct procurement patterns across climate zones, regulatory jurisdictions, and infrastructure maturity levels. Specification authority varies dramatically between municipal utilities, industrial risk managers, and commercial property underwriters, creating parallel demand channels with divergent technical priorities.
Product Type:
Mature wet-barrel designs anchor temperate-region volume while emerging smart-hydrant configurations reshape capital allocation in digitizing utilities.
- Wet Barrel:Non-draining valve assemblies with pressurized barrels maintain continuous water presence for instantaneous discharge. Municipal utilities in Texas, Arizona, and Florida specify these for new suburban developments where freeze risk is absent and response speed is paramount.
- Dry Barrel:Drainable construction evacuates standing water through weep holes to prevent ice damage in cold climates. Water authorities in Minnesota, Wisconsin, and upstate New York prioritize these for replacement programs where AWWA freeze-protection mandates apply.
- Post Indicator Valve:Exterior-mounted valve position indicators enable remote status verification without excavation. Industrial facilities with NFPA 24 compliance requirements specify these for fire protection loop isolation.
- Hydrant Extension:Riser assemblies elevate outlet elevation where grade changes or resurfacing projects alter finished ground levels. Highway departments and airport authorities deploy these for pavement reconstruction compatibility.
Wet Barrel retains volume leadership; Hydrant Extension holds the steepest expansion curve.
Application:
Cost-tier stratification separates municipal baseline specifications from premium industrial configurations driven by insurance-mandated performance guarantees.
- Urban Areas:Dense network deployments prioritize standardized components for maintenance interoperability. Cities with century-old cast-iron water mains face pressure-rating constraints that limit modern high-flow hydrant adoption.
- Industrial Facilities:Petrochemical plants, data centers, and logistics hubs specify high-capacity outlets exceeding 1,500 gallons per minute. Underwriters at FM Global and AIG require documented flow-test compliance for property coverage renewal.
- Commercial Buildings:Retail complexes and office parks integrate hydrants with private fire service mains per NFPA 14. Property managers in Sun Belt metropolitan areas drive specification for aesthetic shrouds and bollard protection.
- Educational Institutions:Campus environments with dispersed building portfolios favor telemetry-enabled models for centralized monitoring. University facilities departments in California and Texas are early adopters of pressure-transducer retrofits.
Urban Areas command procurement volume; Industrial Facilities generate the highest specification premiums.
End User:
Customer-type fragmentation splits authority between public-sector procurement offices and private-sector risk managers with divergent budget cycles.
- Fire Departments:Operational end-users influence specification through flow-test data and incident response feedback. Chief officers in rapidly growing counties are demanding digital pressure visibility for pre-incident planning.
- Municipalities:Water utilities control capital allocation for street-level infrastructure through multi-year CIP programs. Federal infrastructure funding disbursement rules are compressing bidding timelines in mid-sized cities.
- Construction Companies:Site contractors procure temporary hydrants for dust suppression and emergency access during development phases. Master-planned community builders in suburban Dallas and Phoenix represent concentrated seasonal demand.
- Property Managers:Commercial real estate portfolios outsource specification to third-party fire protection engineers. REITs with national footprints are standardizing on specific manufacturers for maintenance interoperability.
Municipalities dominate absolute unit volume; Property Managers are expanding specification influence fastest.
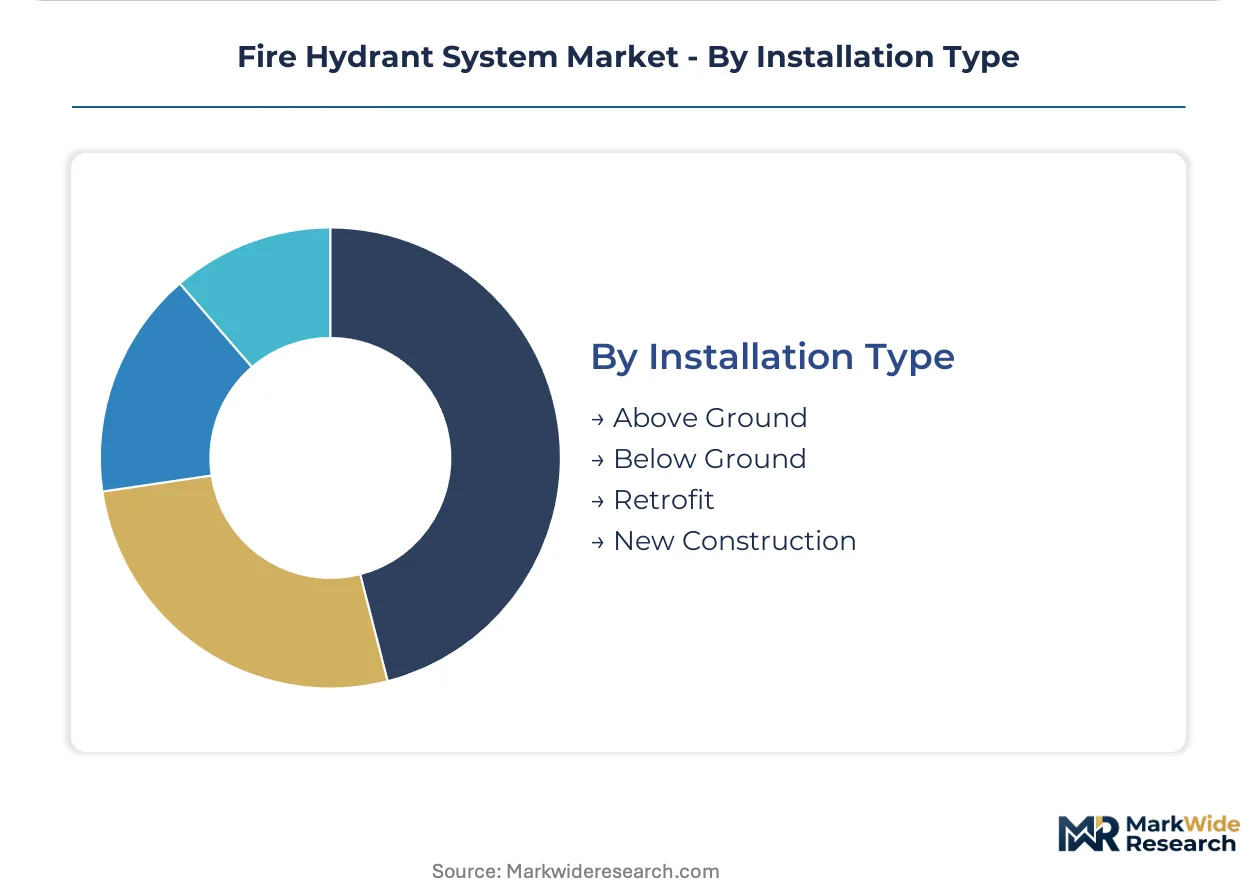
Installation Type:
Volume concentration favors new construction in expanding Sun Belt metros while margin pools concentrate in retrofit telemetry attachments.
- Above Ground:Exposed barrel configurations simplify maintenance access and flow-test execution. Temperate-climate utilities specify these where vandalism risk is manageable and freeze protection is unnecessary.
- Below Ground:Buried valve assemblies with surface-level outlets reduce collision damage and aesthetic intrusion. European urban cores and historic districts mandate these for streetscape compatibility.
- Retrofit:Telemetry attachments and automatic flushing devices upgrade legacy hydrants without full replacement. Budget-constrained utilities in rust-belt cities are prioritizing these for AWWA compliance at reduced capital outlay.
- New Construction:Integrated installations with contemporary water mains achieve optimal pressure ratings and flow characteristics. Suburban expansion corridors in Florida and Texas represent concentrated demand.
New Construction captures volume leadership; Retrofit installations are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented foundries in Germany and China supply ductile-iron castings to utilities worldwide, while import-dependent markets in Australia and the Middle East rely on foreign fabrication for large-diameter hydrant assemblies. Trade flows concentrate in standardized wet-barrel and dry-barrel configurations, with regional climate dictating product mix.
United States
Sun Belt suburban expansion in Texas and Arizona drives new installation contracts, while rust-belt cities accelerate replacement schedules for century-old cast-iron networks. EPA Lead and Copper Rule amendments disqualify leaded bronze components, redirecting procurement toward stainless-steel alternatives. Municipal water utilities in Florida face insurance-mandated upgrades for commercial property coverage.
Germany
Industrial facility insurance requirements from Munich Re and Allianz propel specification premiums for high-capacity hydrant systems. REACH compliance and EU corrosion control mandates tighten material traceability for foundry exports. The Ruhr industrial corridor concentrates demand from petrochemical and logistics hubs requiring documented fire suppression capacity.
China
Urbanization in the Yangtze River Delta and Pearl River Delta generates volume demand for new construction installations. GB standards for fire protection infrastructure align with international AWWA specifications for export markets. Local foundries in Shandong Province supply ductile-iron castings to Southeast Asian utilities through Belt and Road infrastructure contracts.
Australia
Import dependence on North American and European manufacturers persists for high-pressure hydrant assemblies exceeding local foundry capacity. Water authorities in New South Wales and Victoria deploy telemetry-enabled retrofits for remote monitoring of dispersed rural networks. The country's national building code amendments tighten flow-test documentation requirements for commercial developments.
United Arab Emirates
NEOM and other giga-project developments in the Western Region specify corrosion-resistant coatings for salt-air environments. MOHAP building safety regulations mandate private fire service mains for industrial zones and data centers. Dubai Municipality procurement favors below-ground installations for streetscape compatibility in dense urban cores.
Fire Hydrant System Market Competitive Landscape
On the supply side, the industry is moderately consolidated around established foundry operators with century-old casting infrastructure and regional specialists with coating or telemetry expertise. Strategic archetypes separate ductile-iron volume producers, corrosion-resistant coating specialists, and smart-hydrant telemetry integrators. Competitive moves center on retrofit attachment partnerships and geographic expansion through municipal bidding networks.
Within the foundry-dominated tier, Mueller Co. and McWane International exemplify scale-driven operators with captive ductile-iron supply chains. AVK International A/S occupies a position among coating specialists addressing coastal degradation challenges. Kupferle Foundry Company represents the telemetry-attachment vector, converting legacy hydrants into monitored assets without full replacement.
| Leading Market Players |
|---|
| Kennedy Valve Company |
| Clow Valve Company |
| Mueller Co. |
| McWane International |
| EJ Group |
| American Cast Iron Pipe Company |
| Kupferle Foundry Company |
| Rapidrop Global |
| AVK International A/S |
| Others |
Supply & Pricing Matrix
Commodity volatility in ductile-iron scrap and foundry energy inputs compresses margin predictability for wet-barrel hydrant manufacturers while simultaneously widening spreads between premium stainless-steel configurations and economy-grade cast-iron alternatives. This input-cost instability forces procurement officers at municipal utilities to lock in multi-year contract pricing or absorb spot-market swings through contingency reserves.
Pricing Analysis
Technology-generation pricing gaps separate legacy mechanical hydrants from telemetry-enabled smart configurations and next-generation predictive-maintenance platforms. Three-tier pricing structure across premium, standard, and economy levels reflects material grade differentiation—stainless-steel valve assemblies command specification premiums over no-lead brass, while standard ductile-iron barrels anchor municipal volume contracts. Cost compression in economy tiers is intensifying because foundries pass through scrap-metal volatility, and construction companies procuring temporary site hydrants exhibit highest price sensitivity whereas industrial risk managers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts cost structures for utilities dependent on imported valve components and specialized coating systems. Foundry capacity concentrates in the United States, Germany, and China, with the American Southwest and Shandong Province anchoring ductile-iron casting for wet-barrel production. Raw material dependencies rest on scrap steel pricing, epoxy resin formulations, and cellular telemetry modules. Single-source vulnerability pervades certified AWWA fabrication where certified welder shortages extend lead times for custom barrel assemblies. Distribution runs through municipal procurement offices and third-party maintenance providers assuming service-contract responsibilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from telemetry-attachment specialists converting legacy hydrants into monitored assets without full replacement, threatening traditional equipment-sales margins.
For Market Incumbents: Pre-empt telemetry-attachment encroachment by acquiring smart-hydrant technology providers or developing in-house pressure-transducer integration capabilities. Backward integration into captive ductile-iron foundry capacity insulates margin structures from scrap-metal volatility. Certification investment in AWWA Manual M17 compliance documentation accelerates procurement access in digitizing utilities. For New Entrants and Emerging Players: Establish a beachhead in retrofit telemetry attachments for rust-belt municipalities with budget-constrained replacement cycles. Automatic flushing devices and pressure-monitoring retrofits represent the most penetrable segment given century-old cast-iron infrastructure requiring AWWA compliance without capital-intensive full replacement. Channel partnerships with third-party maintenance providers displace traditional municipal procurement routes. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated foundry operators with telemetry capability over pure-play equipment vendors. Long-term viability hinges on recurring service-contract revenue streams displacing transactional equipment sales. The signal to watch is federal infrastructure funding disbursement velocity compressing municipal bidding timelines and accelerating replacement-cycle activation.| Strategic Initiative | Industry Significance |
|---|---|
| Telemetry Platform Integration | Converts passive hydrants into monitored assets generating recurring service revenue for utilities. |
| Foundry Capacity Expansion | Captive ductile-iron supply insulates Mueller Co. and McWane International from scrap-metal volatility. |
| Coating Technology Licensing | AVK International A/S extends corrosion-resistant formulations to salt-air environments through partnership structures. |
| Retrofit Attachment Partnership | Kupferle Foundry Company integrates automatic flushing devices with heterogeneous SCADA architectures. |
| AWWA Certification Investment | Documentation compliance accelerates procurement access in utilities facing digitized flow-test mandates. |
Research Methodology
Initial hypotheses were tested against primary input from water utility capital planning directors, fire protection engineers, municipal procurement officers, and third-party maintenance providers and refined through secondary validation against AWWA technical standards, EPA regulatory filings, NFPA code revision documentation, and municipal capital improvement program disclosures. Bottom-up unit demand estimates triangulated with top-down infrastructure spending allocations.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type configuration, climate-zone application, end-user procurement authority, and installation methodology. CAGRs were derived from replacement-cycle velocity in mature urban cores and new-installation rates in Sun Belt expansion corridors. Industry-specific forecast inputs incorporated federal infrastructure funding disbursement rules and insurance-mandated upgrade specifications from FM Global and AIG underwriters.
Macroeconomic conditions sit as an overlay; deviation in municipal bond financing costs and foundry energy pricing would shift the trajectory. Forecasts reflect assumptions regarding regulatory enforcement timelines and material substitution rates. Material shifts in EPA Lead and Copper Rule amendment implementation velocity or AWWA flow-test digitization mandate adoption would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gypsum Board Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Carbon Textile Reinforced Concrete Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Door System Market