
 Ceramic Wall Tiles Market | 2026-2036
Ceramic Wall Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Wall Tiles Market Analytics
Project finance for distributed manufacturing is rewriting competitive entry rules in ceramic wall tiles. Mohawk Industries, Inc. leverages captive raw-material reserves across North American quarry networks. Kajaria Ceramics Limited anchors its position through deep backward integration into vitrified body formulation. RAK Ceramics competes via asset-light licensing arrangements that extend its brand into emerging markets without capital-heavy plant commitments.
Ceramic wall tiles are thin, flat slabs of fired clay body, typically measuring 5–12 mm thickness, with water absorption rates below 10% for glazed varieties and under 0.5% for porcelain grades, produced through single- or double-firing kiln processes primarily for interior and exterior vertical surface cladding. Porcelain commands the dominant margin pool due to its sub-0.5% porosity and frost resistance, while large format slabs above 1200 mm represent the fastest-growing dimensional tier as fabricators adopt CNC cutting for seamless installations. Residential application sustains the volume base across housing booms, though commercial specification—hotels, healthcare, retail—generates premium realizations through project-specific batch customization.
EMA's REACH protocols govern heavy-metal leaching thresholds for tiles sold across Europe, while India's BIS certification mandates IS 15622 conformance for dimensional stability and crazing resistance in domestic trade. China's MEE enforces emission caps on tunnel kiln operations under GB 25464 standards, compelling producers to retrofit deNOx systems or consolidate. Stakeholders must monitor how carbon-border adjustment mechanisms reshape export competitiveness for kiln-intensive production before committing to new capacity locations.
Market Dynamics
Kiln electrification under China's MEE dual carbon mandate is compressing the cost structure for ceramic wall tile production while fragmenting competitive advantage across energy-access geographies.
Growth Catalysts
- MEE Emission Caps:China's GB 25464 enforcement accelerates tunnel kiln retrofits and deNOx system deployment, consolidating capacity among compliant producers.
- Large Format Slab Demand:CNC-enabled fabricators in premium residential and hospitality verticals specify slabs exceeding 1200 mm for seamless vertical cladding.
- Gujarat-Rajasthan Cluster Expansion:India's western ceramic belt deepens vitrified body formulation capabilities to serve domestic housing stock growth and export channels.
Market Restraints
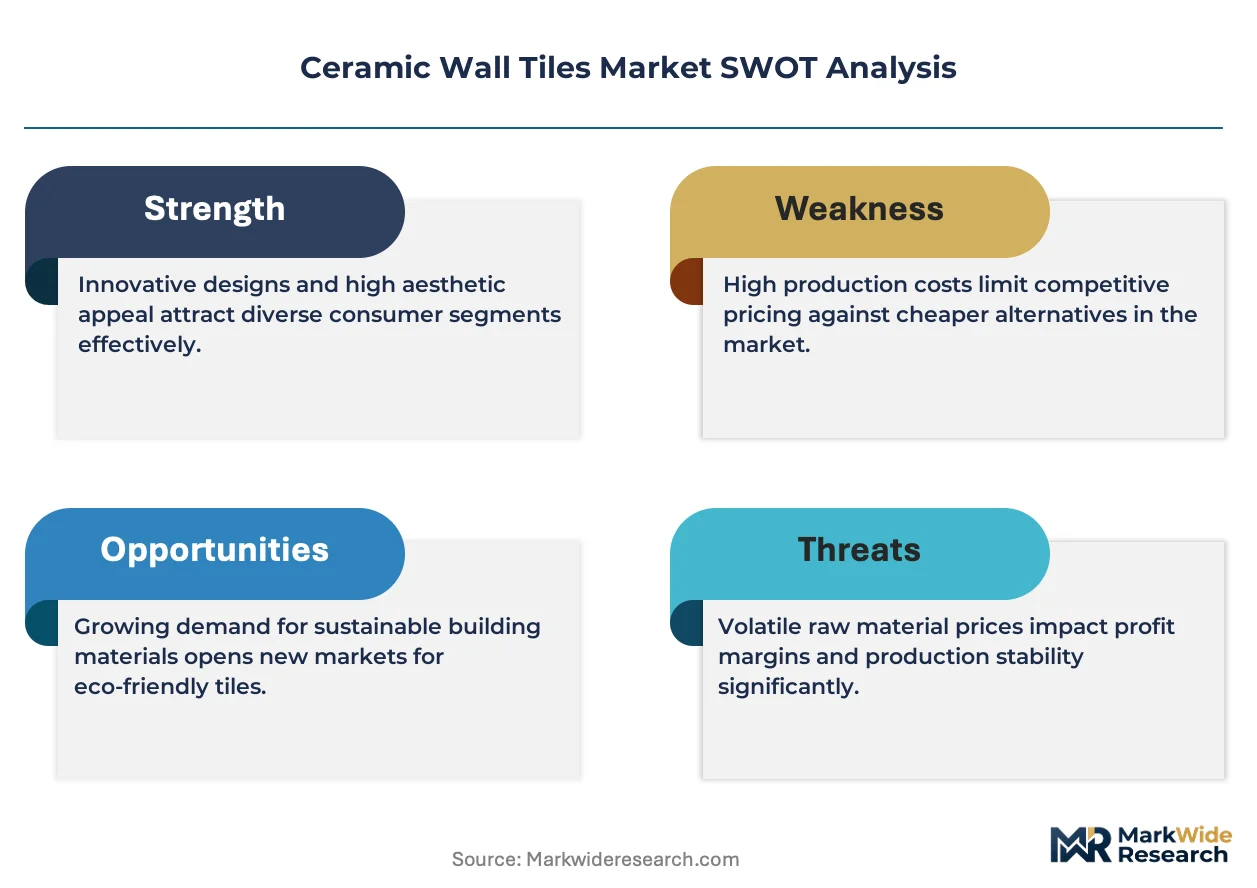
- Natural Gas Price Volatility:Tunnel kiln operations remain tethered to fossil fuel input costs, exposing margin compression during energy price spikes.
- Heavy Metal Leaching Compliance:EMA's REACH protocols impose testing and certification burdens on European-bound shipments, extending time-to-market.
- Thin-Set Mortar Substitution:Alternative cladding systems including fiber-cement panels and engineered stone reduce specification frequency in commercial facades.
Strategic Opportunities
- Waste-Heat Recovery Integration:Captive energy recapture systems align with China's dual carbon goals while lowering per-unit firing costs.
- Asset-Light Licensing Models:Brand extension through manufacturing partnerships enables emerging market presence without greenfield kiln investment.
- Healthcare Specification Growth:Antimicrobial glaze formulations target hospital and clinic verticals where hygiene certification commands premium realizations.
Industry Challenges
- Electrified Kiln Engineering Talent:Scarcity of process engineers capable of retrofitting gas-fired tunnel kilns to electric or hybrid configurations constrains compliance timelines.
- BIS Certification Backlogs:India's IS 15622 testing queues for dimensional stability and crazing resistance delay commercial launches for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Wall Tiles Market |
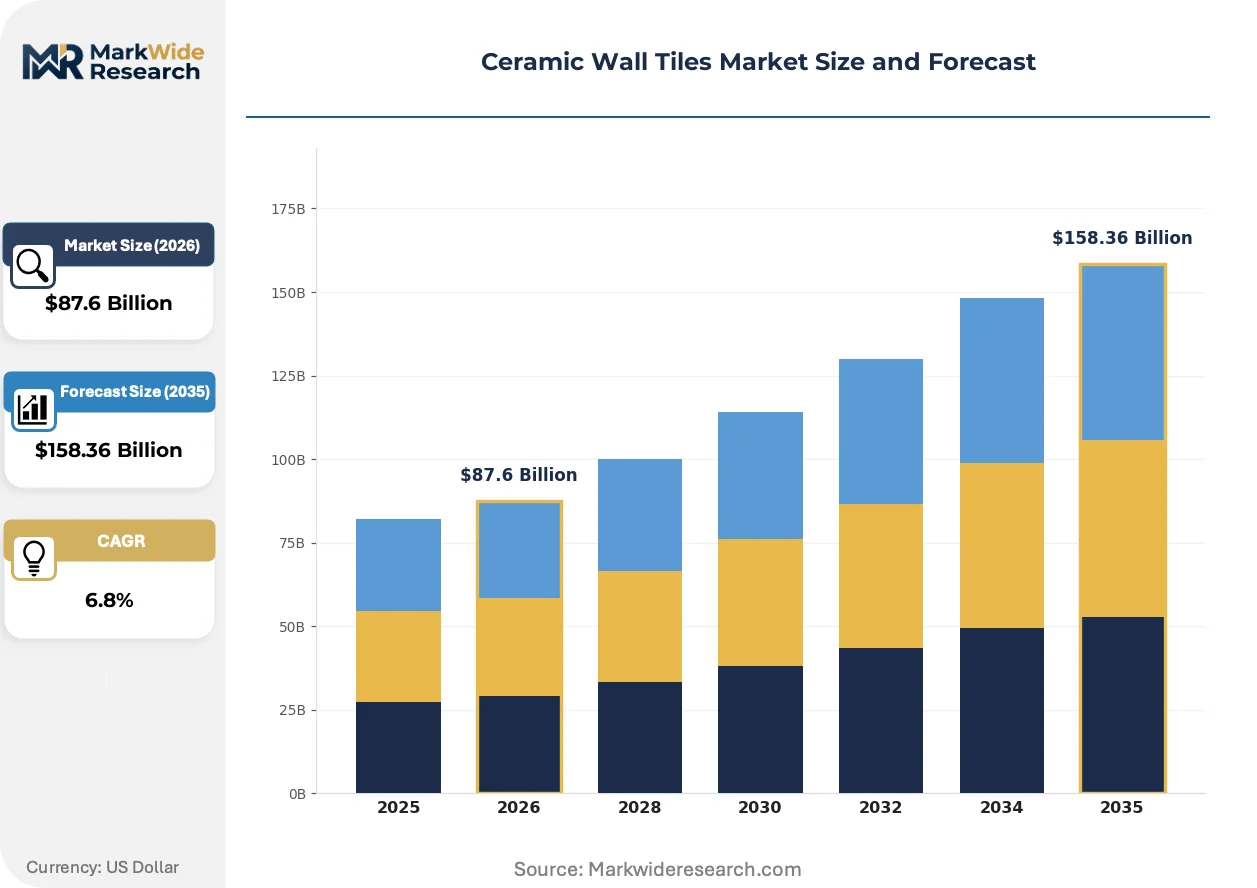
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glazed, Unglazed, Porcelain, Stoneware Application: Residential, Commercial, Institutional, Industrial Design Style: Traditional, Contemporary, Rustic, Minimalist Size: Small Format, Medium Format, Large Format, Custom Size |
| Companies Covered | Mohawk Industries, Inc., Porcelanosa Grupo, Kajaria Ceramics Limited, RAK Ceramics, Grupo Lamosa, Panariagroup Industrie Ceramiche S.p.A., SCG Ceramics, China Ceramics Co., Ltd., Pamesa Ceramica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Wall Tiles Market Evolving Landscape
Digitization of surface decoration and firing control systems is compressing batch customization lead times while enabling specification-grade output from distributed manufacturing footprints.
Digital inkjet decoration is migrating from accent and niche applications to standard production across mid-tier porcelain grades. Hospitality and retail specification buyers now expect photorealistic stone and wood grain replication at sub-premium price points. This capability compression is eroding the historical premium commanded by Italian surface design houses.
EMA's REACH protocols are tightening heavy-metal leaching thresholds for glazed ceramic wall tiles sold across European Union member states. Manufacturers must reformulate frit compositions and expand third-party testing budgets to maintain market access. Italian and Spanish exporters face the steepest compliance cost increases given their historical reliance on legacy glaze chemistries.
Project-specific batch customization is displacing stock-and-sell distribution in commercial verticals. Hotel and healthcare developers now specify color-matched runs tied to interior design palettes, forcing distributors to hold smaller inventories and coordinate directly with manufacturer scheduling systems. This pattern concentrates in Southeast Asian urban housing booms where design-build procurement dominates.
Ceramic Wall Tiles Market Segmentation
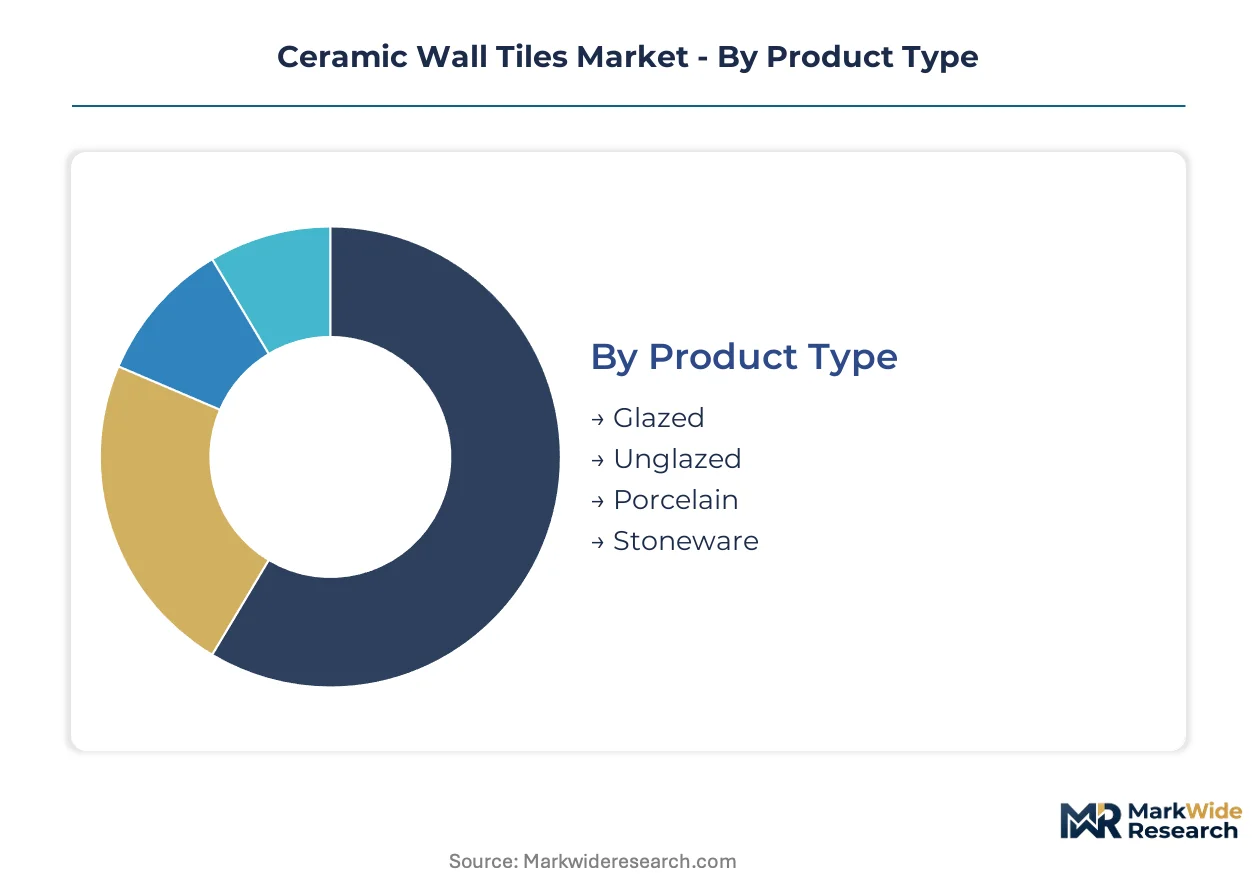
Ceramic wall tile procurement patterns diverge sharply across technical specifications, end-use environments, and dimensional requirements. Specification-grade buyers prioritize water absorption thresholds and frost resistance ratings, while residential developers optimize for installation speed and inventory availability.
Product Type:
Cost tier stratification separates commodity clay bodies from premium vitrified formulations with distinct margin profiles.
- Glazed:Fired clay body receives liquid glass coating, yielding decorative surface variety with 3-10% water absorption. Residential bathroom and kitchen renovations in India's western states absorb rising volumes as housing stock expands. EMA REACH compliance costs compress margins for European-bound shipments.
- Porcelain:Sub-0.5% porosity achieved through higher firing temperatures and refined kaolin content, delivering frost resistance and structural density. Hotel and healthcare specification buyers in Southeast Asia specify porcelain for high-traffic vertical surfaces where durability commands premium realizations. China's MEE emission caps favor compliant producers with electrified kiln capacity.
- Unglazed:Natural clay surface without glass coating, relying on body color and texture for aesthetic effect.
- Stoneware:Dense, vitrified body with intermediate porosity between earthenware and porcelain grades.
Glazed tiles command the established base. The steepest expansion runs through porcelain as commercial specification intensifies.
Application:
End-use environment dictates performance certification requirements and procurement channel selection.
- Residential:Single-family and multi-family housing drives volume absorption through distributor and retail channels. Urban housing booms across Southeast Asia concentrate demand in high-rise bathroom and kitchen applications. Project-specific batch customization is displacing stock-and-sell distribution in design-build procurement.
- Commercial:Hotels, retail, and office developments generate premium realizations through specification-grade output and color-matched production runs. Hospitality developers in Southeast Asia now coordinate directly with manufacturer scheduling systems for palette-specific batches.
- Institutional:Healthcare and education facilities require antimicrobial glaze formulations and hygiene certification.
- Industrial:Manufacturing and warehouse environments prioritize chemical resistance and mechanical durability.
Residential application anchors volume throughput. Commercial specification climbs fastest as hospitality development accelerates.
Design Style:
Aesthetic positioning determines surface decoration technology investment and inventory risk exposure.
- Contemporary:Clean lines and neutral palettes dominate premium residential and commercial specification. Digital inkjet decoration enables photorealistic stone and wood grain replication at mid-tier price points, eroding Italian design house premiums.
- Minimalist:Monochromatic large-format surfaces with minimal grout lines. CNC-enabled fabricators specify slabs exceeding 1200 mm for seamless vertical cladding in luxury hospitality.
- Traditional:Ornamented patterns and historical references for heritage restoration and classical residential.
- Rustic:Textured surfaces and earth tones targeting farmhouse and Mediterranean architectural styles.
Traditional styling retains the installed base. Contemporary aesthetics gain share fastest as digital decoration compresses capability gaps.
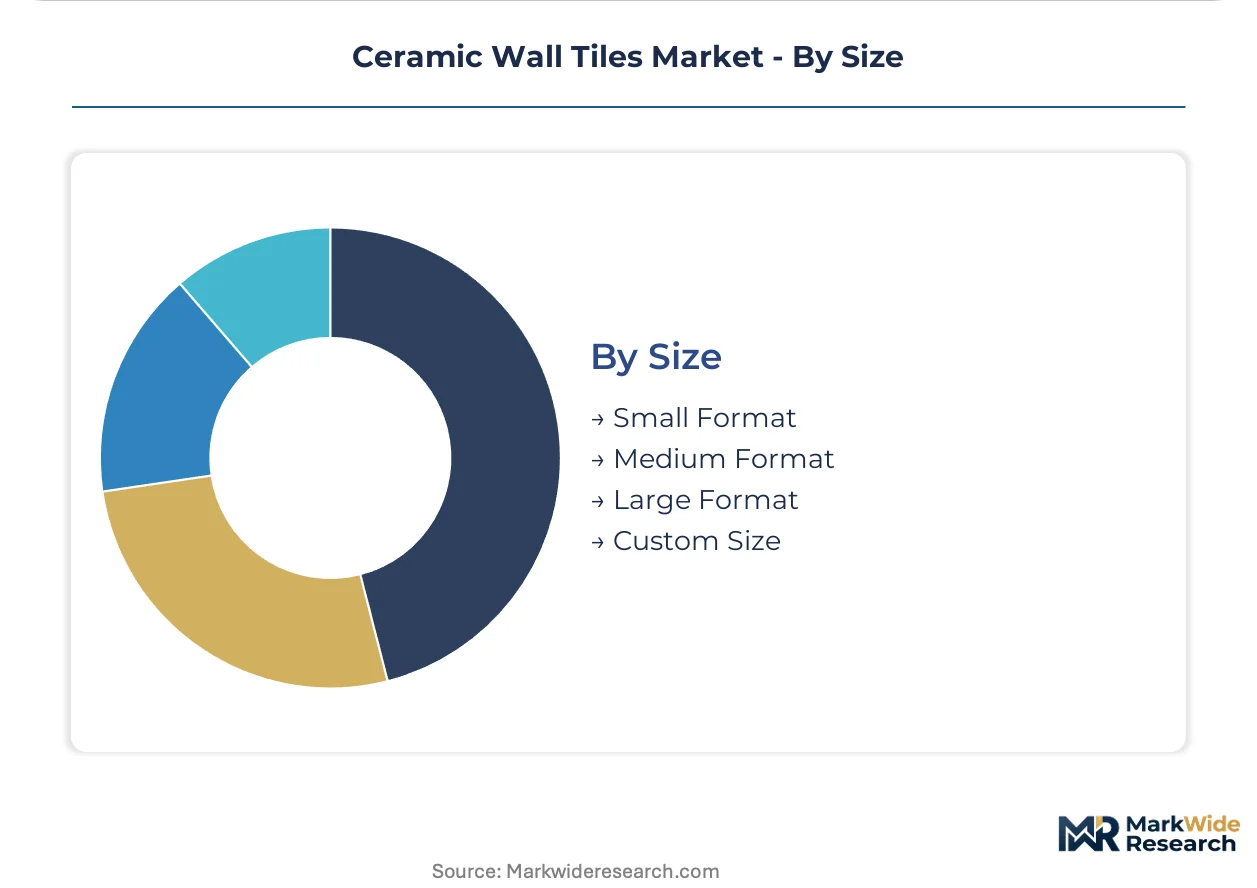
Size:
Dimensional tier selection shapes fabrication methods, logistics costs, and installation labor requirements.
- Large Format:Slabs exceeding 1200 mm enable seamless vertical cladding with reduced grout maintenance. Southeast Asian hospitality developers specify large format for lobby and corridor applications where visual continuity commands premium positioning.
- Medium Format:300-600 mm dimensions balance installation efficiency with design flexibility for residential bathrooms and kitchens.
- Small Format:Sub-300 mm tiles for mosaic applications, accent walls, and curved surface adaptation.
- Custom Size:Project-specific dimensions requiring direct manufacturer coordination and extended lead times.
Medium format commands the established base. Large format posts the steepest expansion trajectory as CNC cutting adoption spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Italian and Spanish export corridors while Southeast Asian production basins compete on volume throughput. China's electrified kiln investments under MEE mandates are compressing regional cost differentials. India's western ceramic belt deepens formulation capabilities to bridge this gap.
China
Urban housing stock expansion in tier-two and tier-three cities absorbs rising glazed tile volumes for bathroom and kitchen renovations. MEE enforces GB 25464 emission caps on tunnel kiln operations, compelling producers to retrofit deNOx systems or consolidate capacity. Foshan and Zibo ceramic clusters lead electrification pilots with waste-heat recovery integration.
India
Residential construction across Gujarat and Rajasthan drives vitrified body formulation demand for domestic and export channels. BIS certification mandates IS 15622 conformance for dimensional stability and crazing resistance, creating testing queue backlogs for new product launches. Morbi ceramic cluster deepens backward integration into raw material beneficiation.
Italy
Hospitality and retail specification buyers in premium commercial verticals command photorealistic surface replication through digital inkjet decoration. EMA REACH protocols tighten heavy-metal leaching thresholds, forcing frit composition reformulation and expanded third-party testing. Sassuolo ceramic district faces steepest compliance cost increases from legacy glaze chemistry dependencies.
Spain
Large format slab demand from Southeast Asian hospitality developers sustains export volume through CNC-enabled fabrication partnerships. EMA REACH alignment extends time-to-market for European-bound shipments. Castellón ceramic corridor concentrates porcelain production for frost-resistant exterior cladding specifications.
Vietnam
High-rise residential construction in Ho Chi Minh City and Hanoi absorbs medium-format glazed tiles through distributor channels. National technical regulations on building materials enforce quality benchmarks for imported ceramic products. Binh Duong and Dong Nai provinces attract kiln investment from regional manufacturers seeking tariff-advantaged export positioning.
Ceramic Wall Tiles Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with formulation and firing technology. The vendor base separates into three functional layers: captive raw-material holders, asset-light brand licensors, and distributed manufacturing enablers. Two strategic archetypes dominate—backward-integrated producers controlling vitrified body supply chains, and licensing-based expanders avoiding greenfield capital commitments. Competitive moves concentrate on waste-heat recovery integration and project-finance structures for distributed manufacturing footprints.
Among India-based integrated producers, Kajaria Ceramics Limited exemplifies backward integration into vitrified body formulation. UAE-origin RAK Ceramics occupies the asset-light licensing tier, extending brand presence without capital-heavy plant commitments. US-based Mohawk Industries, Inc. represents captive raw-material advantage through North American quarry network control. These three anchors illustrate how geographic resource access and capital structure choices define competitive positioning.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Porcelanosa Grupo |
| Kajaria Ceramics Limited |
| RAK Ceramics |
| Grupo Lamosa |
| Panariagroup Industrie Ceramiche S.p.A. |
| SCG Ceramics |
| China Ceramics Co., Ltd. |
| Pamesa Ceramica |
| Others |
Value Network & Pricing Analysis
Natural gas price volatility in kiln-intensive production determines both margin compression across porcelain tiers and the geographic reshaping of ceramic wall tile manufacturing toward electrified basins in China and India.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium, standard, and economy levels. Price differentiation separates specification-grade porcelain with sub-0.5% porosity from commodity glazed tiles with higher water absorption. Pricing pressure stems from MEE emission compliance costs in China, which compress margins for non-compliant producers. Residential developers in Southeast Asia exhibit highest price sensitivity, while hospitality specifiers in Italy and Spain absorb premiums for photorealistic digital decoration.
Supply Chain Analysis
Export-control restrictions on deNOx technology and electrified kiln components limit retrofit capacity flows from European engineering houses to Asian producers. Supply concentrates in China, India, and Italy, with raw material dependencies on refined kaolin, frit compositions, and natural gas feedstock. Single-source vulnerability runs through tunnel kiln engineering talent scarcity. Distribution runs through project-direct channels for commercial specification and distributor networks for residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic wall tile demand sits in early-cycle expansion as large format slab adoption penetrates Southeast Asian hospitality development and electrified kiln retrofits unlock cost advantages for compliant producers.
For Market Incumbents: Pre-empt margin erosion from fiber-cement panel substitution by deepening backward integration into vitrified body formulation and securing captive waste-heat recovery engineering capacity. Consolidate among Gujarat-Rajasthan cluster producers before BIS certification backlogs ease and new entrants gain testing access.
For New Entrants and Emerging Players: Build out asset-light licensing arrangements in Vietnam and Indonesia where tariff-advantaged export positioning attracts regional kiln investment. Target healthcare specification with antimicrobial glaze formulations as the most penetrable premium segment, leveraging direct coordination with hospital procurement committees bypassing stock-and-sell distributors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors backward-integrated producers with electrified kiln compliance and captive raw-material reserves. Long-term viability across the next decade hinges on MEE-aligned production capacity. Monitor carbon-border adjustment mechanism proposals as the signal to watch for export competitiveness inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Kiln Retrofit | MEE GB 25464 compliance locks in cost advantage for Chinese producers against gas-dependent competitors. |
| Waste-Heat Recovery Integration | Captive energy recapture aligns with dual carbon goals while lowering per-unit firing costs in Foshan clusters. |
| Large Format Slab Capacity Addition | CNC-enabled fabrication partnerships capture Southeast Asian hospitality specification demanding seamless vertical cladding. |
| Antimicrobial Glaze Formulation | Hygiene certification commands premium realizations in hospital and clinic verticals with stringent surface protocols. |
| Asset-Light Licensing Expansion | Brand extension through manufacturing partnerships enables emerging market presence without greenfield capital commitments. |
Research Methodology
Desk research of customs trade data, BIS certification records, and MEE emission filings preceded structured interviews with tunnel kiln engineering specialists, ceramic plant managers, hospitality procurement directors, and distributor channel heads. Primary fieldwork across Foshan, Morbi, and Sassuolo ceramic clusters combined with secondary validation from SEC filings of listed producers and EMA REACH compliance databases. Bottom-up volume estimates triangulated against top-down construction spending projections.
Assumptions held MEE emission enforcement timelines and natural gas price corridors within observed ranges while varying electrification adoption rates and carbon-border implementation scenarios across the analysis window. Segmentation modeling spanned product type, application environment, dimensional tier, and regional production hub. CAGRs derived from slope-intercept fitting to historical shipment volumes and elasticity-adjusted construction forecasts, with porcelain grade mix and large format share as key industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-subsidized Chinese producers or accelerated EU carbon-border adjustment would shift outcomes. Material shifts in MEE enforcement stringency or breakthroughs in thin-set mortar substitution technologies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Brick Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Europe Gypsum Board Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
South America Ready Mix Concrete Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
Welded Wire Mesh Market
Building & Construction Materials
Vinyl Windows Market