

Basalt Fiber Reinforced Polymer BFRP Market Size, Share, and Industry Trends Forecast 2026-2036
Basalt Fiber Reinforced Polymer BFRP Market Insights
Steel rebar substitution in coastal infrastructure is broadening the addressable base for basalt fiber composites. Kamenny Vek anchors Russian-origin supply through continuous filament technology. Technobasalt-Invest leverages Ukrainian manufacturing scale to compete across Eastern European civil projects. Basaltex specializes in woven fabric architectures for European construction firms seeking ISO-certified reinforcement solutions.
Basalt Fiber Reinforced Polymer denotes a thermoset or thermoplastic matrix reinforced with continuous or chopped basalt fibers derived from volcanic rock, typically exhibiting tensile strength exceeding 4,000 MPa and thermal stability up to 600°C, engineered primarily to replace corrosion-prone metal reinforcements in structural and electrical applications. Pultruded rods command the largest volume share where infrastructure budgets prioritize lifecycle cost over first cost, while prepregs within the form dimension capture expanding margin pools as electrical manufacturers adopt out-of-autoclave processing for transformer components and switchgear housings.
The EPA oversees embodied-carbon disclosure for federal construction in the United States, while REACH and the EU Green Deal restrict hazardous substance content in composite materials sold across Europe, collectively elevating basalt fiber's regulatory advantage over glass and carbon alternatives in public procurement. China's GB standards and MIIT industrial policy directives further codify basalt composite inclusion in transportation and energy infrastructure specifications. Stakeholders must track evolving national green public procurement criteria that increasingly weight corrosion resistance and recyclability in composite selection decisions.
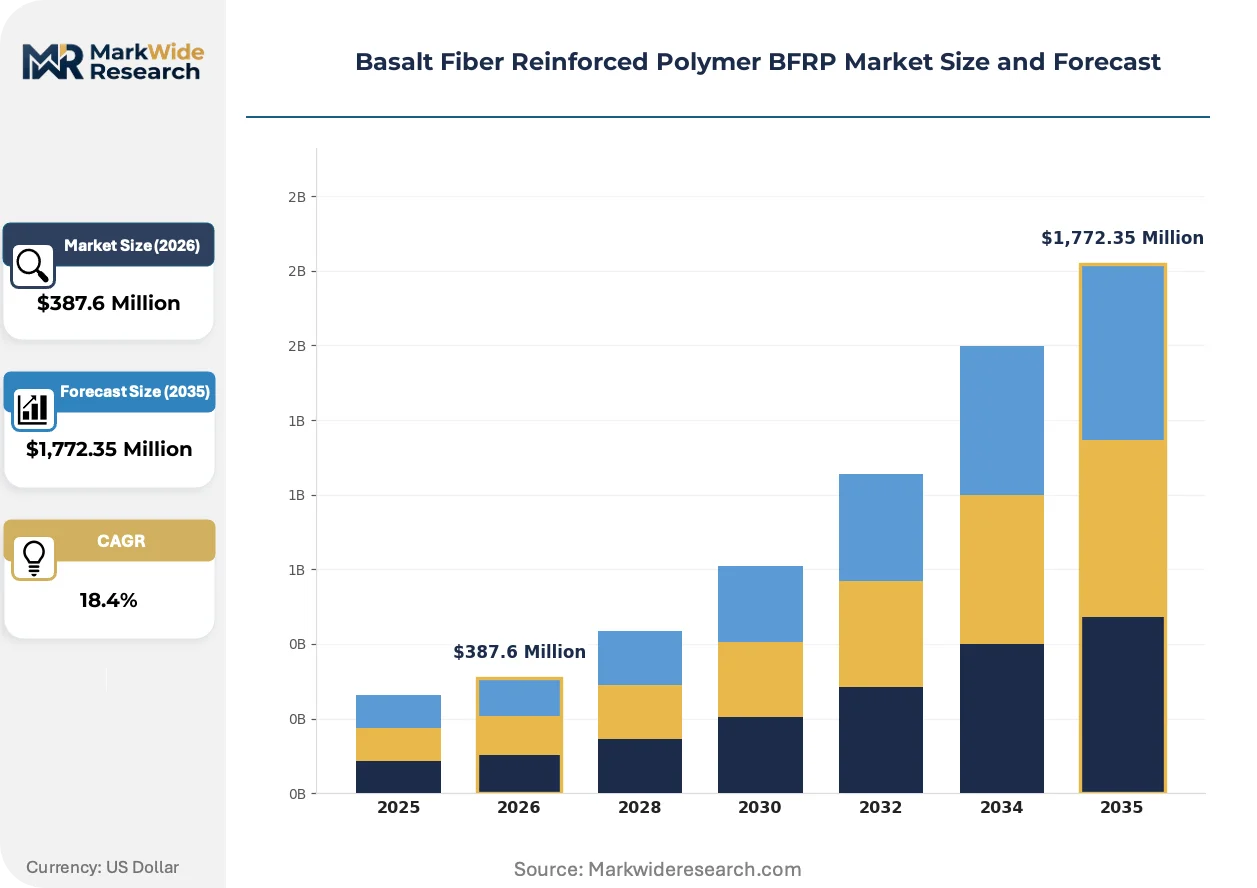
Market Dynamics
Corrosion-induced infrastructure failure across coastal zones is accelerating specification shifts toward basalt fiber reinforcement, as lifecycle cost accounting now dominates procurement criteria over first-cost bidding in public works tenders.
Growth Catalysts
- REACH compliance in Europe:Hazardous substance restrictions on conventional composites elevate basalt fiber's regulatory standing in Dutch and German civil engineering specifications.
- Continuous filament pultrusion:Automated rod manufacturing cuts unit costs for bridge deck reinforcement, enabling competitive parity with epoxy-coated steel in North American DOT contracts.
- China's MIIT industrial directives:State-mandated basalt composite inclusion in tunnel lining and railway infrastructure creates guaranteed offtake volumes for domestic producers.
Market Restraints
- Feedstock concentration:High-purity basalt ore deposits cluster in specific volcanic regions, exposing supply chains to geopolitical disruption and transport cost volatility.
- Resin price exposure:Vinyl ester and epoxy matrix costs fluctuate with petrochemical feedstock indices, compressing margins during crude oil spikes.
- Steel rebar incumbency:Established scrap recycling infrastructure and familiar installation protocols sustain contractor preference for conventional reinforcement in budget-constrained projects.
Strategic Opportunities
- India's coastal infrastructure buildout:Sagarmala port modernization and Mumbai-Ahmedabad high-speed rail corridors specify corrosion-resistant materials in saline environments.
- Transformer component miniaturization:Electrical manufacturers adopt basalt-epoxy prepregs for switchgear housings requiring thermal stability beyond glass fiber limits.
- EU Green Deal procurement criteria:Embodied-carbon scoring in public tenders creates preferential weighting for basalt over carbon fiber in civil applications.
Industry Challenges
- Fiber-matrix interface engineering:Sizing chemistry optimization for vinyl ester compatibility demands specialized polymer science talent scarce outside established composites clusters.
- ISO 10406 certification timelines:Full qualification for FRP reinforcement in structural concrete extends 18-24 months, delaying market entry for new product formulations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Basalt Fiber Reinforced Polymer BFRP Market Trends and Innovations
Out-of-autoclave manufacturing methods are compressing capital barriers for electrical component producers, while regulatory carbon accounting reweights material selection criteria across infrastructure procurement globally.
Modular pultrusion systems are decentralizing basalt rod production from centralized mega-facilities to regional job sites. Infrastructure contractors in Florida and Queensland now deploy containerized manufacturing units for bridge deck projects, cutting transport costs and enabling just-in-time reinforcement delivery. This distributed model is decentralizing supply chain risk and compressing project timelines for remote civil works.
The EU Green Deal's embodied-carbon disclosure mandates for public construction are forcing material specification changes across member state procurement frameworks. Contractors bidding on Dutch and Danish marine infrastructure must now submit lifecycle carbon inventories that penalize steel's production emissions. Basalt fiber suppliers with EPD-certified products capture preferential scoring in these tender evaluations.
Buyers are consolidating vendor relationships around full-service reinforcement packages that bundle design, material supply, and installation supervision. European construction firms increasingly reject commodity fiber sales in favor of integrated project partnerships that transfer liability for structural performance. This bundling trend concentrates procurement authority with engineering-procurement-construction contractors and marginalizes standalone material distributors in German and French markets.
Basalt Fiber Reinforced Polymer BFRP Market Segmentation
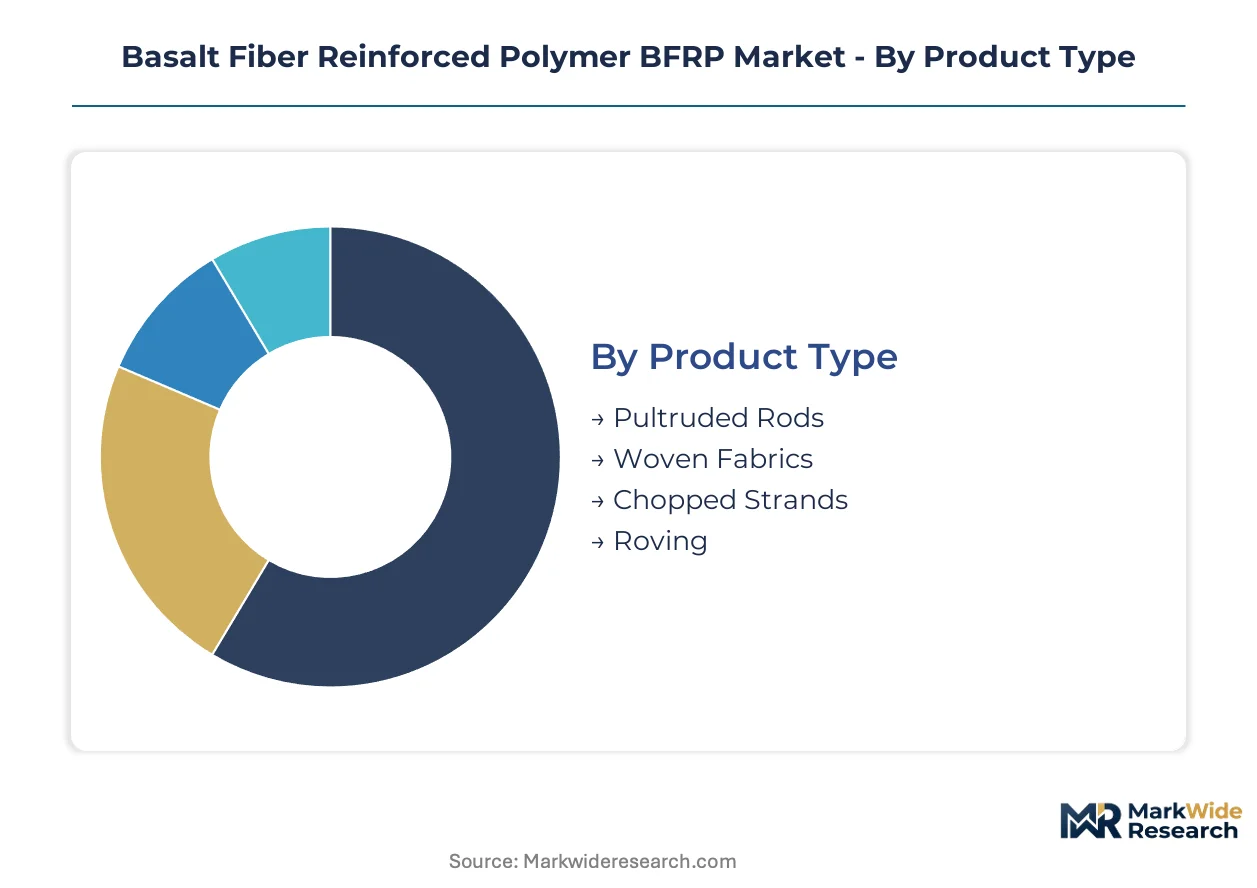
Segmentation in the BFRP market reveals distinct value capture patterns across manufacturing forms and integration depths. Product architecture determines whether suppliers compete on commodity fiber volumes or engineered composite premiums.
Product Type:
Continuous filament formats dominate structural reinforcement where load-bearing performance is non-negotiable, while discontinuous forms serve secondary applications demanding cost efficiency over mechanical precision.
- Pultruded Rods:These linear profiles combine unidirectional basalt fiber with thermoset resin matrices through automated pull-forming processes. Bridge deck contractors in Florida and Queensland specify pultruded rods for rebar substitution where chloride-induced corrosion threatens steel longevity.
- Woven Fabrics:Multiaxial or plain-weave architectures enable conformable reinforcement of complex geometries. European construction firms pursuing ISO-certified solutions specify woven basalt fabrics for tunnel lining repairs and seismic retrofit projects.
- Chopped Strands:Discontinuous fibers serve thermoplastic compounding and spray-up applications. Automotive underbody shields and industrial grating manufacturers incorporate chopped basalt for moderate strength-to-weight improvement.
- Roving:Untwisted continuous fiber bundles feed filament winding and pultrusion operations. Russian and Ukrainian producers ship roving to downstream composite fabricators serving Eastern European civil infrastructure.
Pultruded rods lead volumes today; woven fabrics are gaining share fastest in premium civil applications.
Application:
End-use segmentation tracks corrosion exposure severity and regulatory pressure intensity across built environments.
- Infrastructure:Bridge decks, tunnel linings, and seismic retrofit systems constitute the primary demand sink. China's MIIT directives mandate basalt composite inclusion in railway and transportation infrastructure, creating state-guaranteed offtake.
- Marine Construction:Offshore platforms, seawalls, and port facilities require salt-immune reinforcement. India's Sagarmala port modernization program specifies corrosion-resistant materials for saline environment durability.
- Electrical Insulation:Transformer housings, switchgear components, and busbar supports exploit basalt's thermal stability beyond glass fiber limits. Out-of-autoclave prepreg processing reduces capital barriers for electrical manufacturers.
- Sporting Goods:Bicycle frames, fishing rods, and athletic equipment leverage basalt's vibration damping and aesthetic dark weave. Niche positioning against carbon fiber competes on sustainability credentials rather than absolute performance.
Infrastructure commands the largest revenue pool; electrical insulation exhibits the steepest expansion trajectory as grid modernization accelerates.
End User Industry:
Customer segmentation distinguishes project-driven procurement from continuous manufacturing demand, with implications for sales cycle length and technical service intensity.
- Construction Firms:General and specialty contractors purchase reinforcement packages bundled with design validation and installation supervision. Dutch and Danish marine infrastructure tenders now weight embodied-carbon scoring, favoring basalt suppliers with EPD certification.
- Electrical Manufacturers:OEMs of transformers, switchgear, and power distribution equipment specify basalt-epoxy prepregs for thermal performance. Miniaturization trends in electrical components drive material substitution from traditional insulators.
- Marine Contractors:Port authorities and offshore construction specialists prioritize lifecycle cost over first cost in saline environments. Procurement criteria emphasize corrosion resistance warranties and installation protocol familiarity.
- Sports Equipment Makers:Premium bicycle and outdoor gear brands source basalt fiber for sustainability marketing differentiation. Batch-scale purchasing contrasts with infrastructure volume contracts.
Construction firms generate the highest absolute demand; electrical manufacturers are expanding procurement most aggressively.
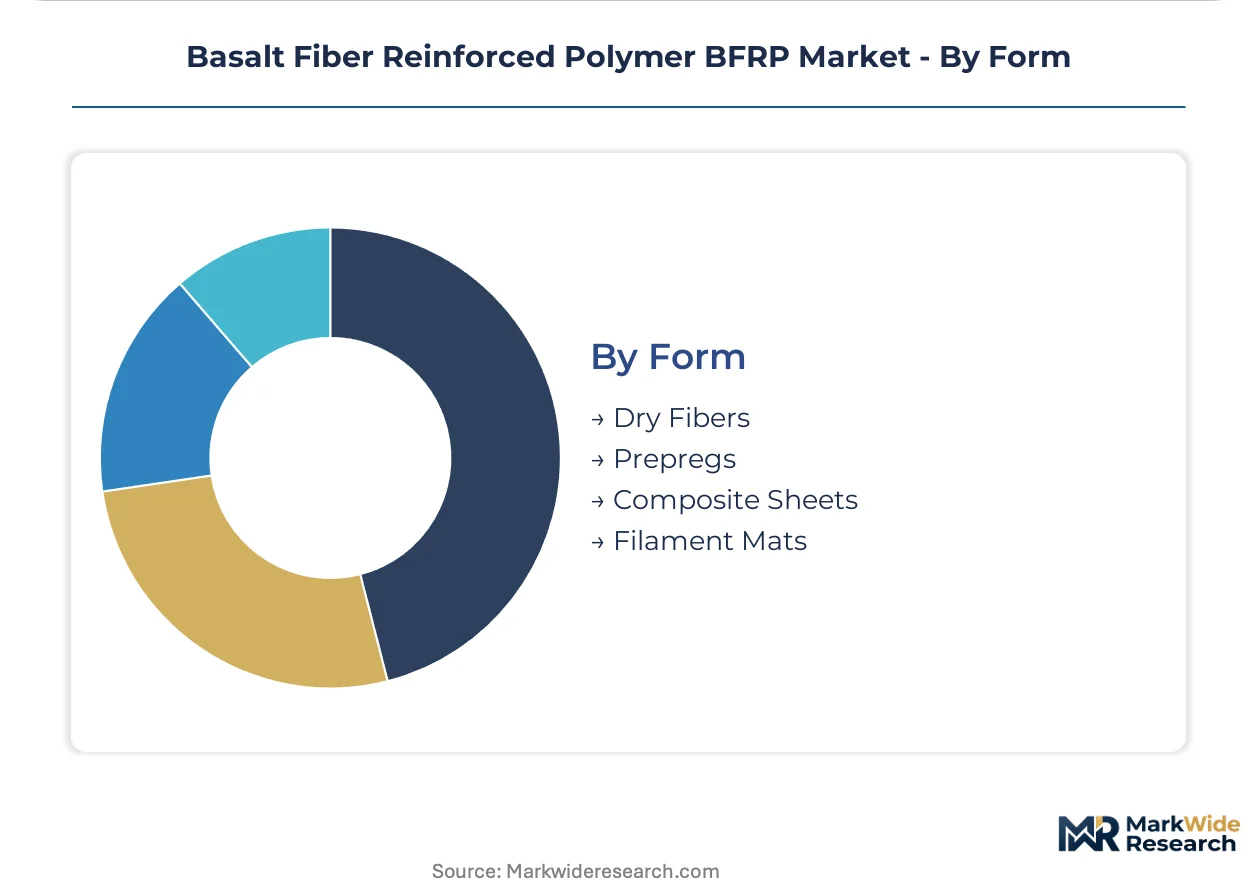
Form:
Processing state determines supply chain position and margin capture, from raw fiber to finished composite systems.
- Dry Fibers:Unimpregnated roving and chopped strand supply downstream fabricators and compounders. Volatile resin pricing exposes dry fiber buyers to margin compression when petrochemical indices spike.
- Prepregs:Resin-impregnated sheets and tapes enable out-of-autoclave manufacturing for electrical and aerospace-derivative applications. Prepregs capture expanding margin pools as manufacturers adopt lower-capital curing processes.
- Composite Sheets:Cured laminates and sandwich panels serve immediate fabrication without secondary resin infusion. Modular bridge decks and temporary roadway panels utilize pre-cured basalt sheet systems.
- Filament Mats:Random or oriented fiber webs facilitate hand lay-up and resin transfer molding. Secondary applications in industrial corrosion barriers and architectural cladding employ mat reinforcements.
Dry fibers dominate tonnage shipments; prepregs are climbing the fastest as electrical OEMs redesign component architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta industrial corridor anchors the dominant basalt fiber production cluster, with state-backed infrastructure programs driving concentrated demand for corrosion-resistant reinforcement materials across bridge and tunnel construction.
China
MIIT industrial directives mandate basalt composite inclusion in railway and transportation infrastructure, creating guaranteed offtake volumes for domestic producers. GB standards codify material specifications for tunnel linings and coastal structures. The Sichuan-Chongqing manufacturing belt houses continuous filament operations supplying civil engineering projects nationwide.
United States
Florida and California DOT contracts specify lifecycle cost accounting over first-cost bidding for bridge deck reinforcement in chloride-exposed environments. EPA embodied-carbon disclosure requirements for federal construction elevate basalt fiber's regulatory standing against conventional steel. Modular pultrusion systems now deploy containerized manufacturing units directly to remote civil works sites.
Germany
REACH hazardous substance restrictions and EU Green Deal procurement criteria penalize steel's production emissions in tender evaluations. Dutch and Danish marine infrastructure contractors must submit lifecycle carbon inventories favoring EPD-certified basalt suppliers. The North Rhine-Westphalia composites cluster specializes in ISO-certified woven fabric architectures for seismic retrofit applications.
India
Sagarmala port modernization and Mumbai-Ahmedabad high-speed rail corridors specify corrosion-resistant materials for saline environment durability. CEA grid modernization directives accelerate basalt-epoxy adoption in transformer component manufacturing. Gujarat and Maharashtra industrial zones host emerging prepreg fabrication capacity serving electrical OEMs.
Netherlands
EU Green Deal embodied-carbon scoring in public tenders creates preferential weighting for basalt over carbon fiber in marine infrastructure applications. Rotterdam port authority procurement now requires corrosion resistance warranties for seawall reinforcement systems. The Randstad engineering-procurement-construction corridor bundles design, material supply, and installation supervision contracts.
Basalt Fiber Reinforced Polymer BFRP Market Competitive Landscape
Capacity expansion dominates the current landscape as producers scale continuous filament operations to capture infrastructure procurement volumes. The vendor base clusters around three strategic tiers: integrated ore-to-fiber producers controlling basalt quarry access, regional pultrusion specialists serving DOT contracts, and electrical component fabricators leveraging out-of-autoclave processing. Geographic expansion and strategic partnerships represent the two dominant competitive moves, with producers establishing regional manufacturing presence to reduce transport costs and bundling design-validation services to transfer structural performance liability.
Within the integrated production tier, Kamenny Vek exemplifies Russian-origin supply chain control through captive basalt ore deposits, while Technobasalt-Invest occupies a position as a Ukrainian manufacturing scale anchor for Eastern European civil projects. Basaltex represents the premium-certified fabricator archetype, with its woven fabric architectures serving Dutch and German construction firms pursuing ISO-validated reinforcement solutions.
| Leading Market Players |
|---|
| Technobasalt-Invest |
| Kamenny Vek |
| Basaltex |
| Isomatex |
| Zhejiang GBF Basalt Fiber |
| Arab Basalt Fiber Company |
| Deutsche Basalt Faser |
| Pultrall |
| Neuvokas |
| Others |
Pricing and Supply Chain Analysis
Crude oil futures volatility cascades through vinyl ester and epoxy resin costs, compressing margins for dry fiber buyers when petrochemical indices spike while rewarding prepreg fabricators with captive resin blending capabilities. Infrastructure contractors in Florida and Queensland now demand lifecycle cost guarantees that shift pricing power toward integrated ore-to-fiber producers controlling captive basalt quarry access.
Pricing Analysis
Input-cost pass-through from volatile petrochemical feedstocks intensifies margin pressure on non-integrated dry fiber suppliers lacking captive resin production. Three-tier pricing structure across EPD-certified premium, ISO-compliant standard, and uncertified economy levels separates Kamenny Vek's Russian-origin supply from Ukrainian manufacturing scale and Chinese state-backed volume plays. Cost compression in the economy tier runs through spot-market resin exposure, while electrical manufacturers purchasing prepregs exhibit the lowest price sensitivity due to thermal performance premiums. Bridge deck contractors remain most price-sensitive, comparing basalt rod lifecycle costs against epoxy-coated steel in DOT tender evaluations.
Supply Chain Analysis
Regional distribution centers in the North Rhine-Westphalia composites cluster and China's Sichuan-Chongqing manufacturing belt coordinate hub-and-spoke fulfillment for European and Asian civil projects respectively. High-purity basalt ore deposits concentrate in Russia, Ukraine, and China's volcanic regions, exposing continuous filament supply to geopolitical disruption and trans-Eurasian rail cost volatility. Distribution runs through engineering-procurement-construction contractors bundling design validation with material supply, marginalizing standalone fiber distributors in German and French markets. Single-source vulnerability concentrates in roving supply from Kamenny Vek's captive deposits, while modular pultrusion systems decentralize finished rod production to Florida and Queensland job sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Basalt Fiber Reinforced Polymer market functions as a stable compounder anchored by state-mandated infrastructure procurement in China and corrosion-driven specification shifts in coastal economies. Regulatory carbon accounting and lifecycle cost dominance in public tenders create durable demand visibility.
For Market Incumbents: Lock in long-term offtake agreements with Chinese state-owned construction enterprises before MIIT directive compliance saturates domestic capacity. Defend margin position by securing EPD certification for European Green Deal procurement scoring while adding captive vinyl ester blending to offset petrochemical price volatility eroding dry fiber economics.
For New Entrants and Emerging Players: Electrical OEM channel partners offer the most penetrable entry vector given transformer miniaturization trends and out-of-autoclave processing adoption. Target India's Gujarat and Maharashtra industrial zones where CEA grid modernization directives accelerate basalt-epoxy prepreg demand without entrenched incumbent relationships. Lead with thermal performance validation against glass fiber limits rather than competing on commodity fiber tonnage.
For Investors and Strategic Acquirers: Asymmetric upside sits with integrated ore-to-fiber producers controlling volcanic deposit access and ISO-certified fabricators serving Dutch marine infrastructure tenders. Long-term viability hinges on regulatory carbon accounting persistence across EU and North American public procurement. Watch for MIIT directive expansion beyond railway infrastructure into coastal defense specifications as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Basalt Quarrying | Captive ore supply insulates Kamenny Vek and Technobasalt-Invest from geopolitical disruption risk. |
| EPD Certification Investment | Certified suppliers capture preferential scoring in Dutch and Danish marine infrastructure tenders. |
| Modular Pultrusion Deployment | Containerized manufacturing cuts transport costs for Florida and Queensland bridge contractors. |
| Out-of-Autoclave Prepreg Expansion | Lower capital barriers attract electrical OEMs redesigning transformer component architectures. |
| Engineering-Procurement-Construction Partnership | Integrated project bundles transfer structural performance liability from construction firms. |
Research Methodology
Bottom-up infrastructure and electrical insulation modeling reconciled against top-down continuous filament capacity tracking forms the analytical core of this study. Primary interviews with civil engineering procurement officers, composite plant managers, EPC contractor technical directors, and electrical OEM material scientists combined with secondary validation from MIIT directive filings, EPA embodied-carbon disclosure requirements, EU Green Deal procurement frameworks, and customs trade data for basalt fiber and resin imports. Triangulation across supply-side capacity announcements and demand-side project pipelines ensures segmentation integrity.
Input-output matrices map basalt ore extraction through roving, pultrusion, and prepreg conversion to end-use consumption across bridge decks, tunnel linings, transformer housings, and switchgear components over the projection horizon. Segmentation dimensions include product architecture, processing state, corrosion exposure severity, and regulatory pressure intensity. CAGRs derive from elasticity-adjusted substitution rates against steel rebar and glass fiber in chloride-exposed environments. Forecast inputs incorporate REACH compliance timelines, ISO 10406 certification completion rates, and modular pultrusion deployment velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical price volatility, geopolitical disruption of Russian and Ukrainian ore supply, and potential relaxation of EU Green Deal embodied-carbon scoring weights. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.