
 Prefabricated Construction Market | 2026-2036
Prefabricated Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Prefabricated Construction Market Analysis
Healthcare infrastructure procurement is redrawing competitive boundaries in prefabricated construction, with hospital systems replacing traditional general contractors for modular patient towers and clinical wings. Laing O'Rourke sustains manufacturing scale through its Explore Industrial Park facility, producing fully fitted bathroom pods and corridor modules for NHS trusts. Kingspan Group dominates insulated panel systems, leveraging its controlled-environment production lines to deliver thermal-bridge-free envelopes for temperature-sensitive medical environments. Clayton Homes anchors the residential modular segment, operating a vertically integrated network of manufacturing plants across the southeastern United States.
Prefabricated construction encompasses factory-manufactured building components and volumetric modules produced under controlled conditions, then transported to sites for assembly using crane-set installation with tolerances typically held to within two millimeters. The primary purpose is compressing construction schedules while standardizing quality outcomes across housing, commercial, and institutional applications. Modular Units command the deepest margin pools where full volumetric delivery eliminates multiple trade interfaces, while Wall Panels represent the highest-volume category driven by single-family and multi-family residential developers seeking incremental efficiency gains without full process overhaul. Metal and Concrete materials are gaining specification share in commercial and industrial end-user segments as fire-resistance ratings and structural span requirements intensify.
The EU Green Deal's embodied carbon thresholds and CE marking requirements under the Construction Products Regulation are reshaping material certification pathways and factory audit protocols for European producers. In the United States, OSHA workplace safety standards and ICC evaluation service listings govern module transport, crane lifting, and site-connection procedures, creating compliance cost differentiation between established and new market entrants. Stakeholders must monitor evolving building code equivalency determinations between factory and site-built assemblies, as these rulings determine market access breadth for modular solutions in jurisdictions with conservative inspection regimes.
Market Dynamics
Healthcare infrastructure procurement is compressing traditional construction timelines as NHS trusts and German hospital systems mandate modular patient towers with factory-controlled infection prevention specifications. This demand pattern is forcing general contractors to cede ground to manufacturing-led delivery models.
Growth Catalysts
- EU Green Deal embodied carbon thresholds:CE marking pathways under the Construction Products Regulation are accelerating factory audit standardization across European producers seeking low-carbon certification for cross-border hospital and residential contracts.
- Modular patient tower specifications:Hospital systems in Germany and the United Kingdom are embedding volumetric delivery clauses into procurement frameworks, eliminating multiple trade interfaces and compressing clinical commissioning timelines.
- Stuttgart-Dortmund supplier ecosystem density:Factory-built housing associations and municipal developers in these German clusters have achieved logistics optimization that reduces module transport costs for multi-story residential projects.
Market Restraints
- Steel and engineered timber input volatility:Structural frame material costs fluctuate with energy-intensive production cycles, compressing margin predictability for fixed-price modular contracts.
- Specialized transport carrier concentration:Crane-capable heavy haulage capacity concentrates with regional logistics providers, creating bottleneck risk for just-in-time module delivery to dense urban infill sites.
- Building code equivalency determination delays:Conservative inspection regimes in jurisdictions without modular-specific approval pathways extend permitting timelines and deter developer adoption.
Strategic Opportunities
- Clinical wing thermal envelope convergence:Integration of Kingspan-style insulated panel systems with HVAC smart controls creates premium positioning for temperature-sensitive medical environments requiring precise climate stability.
- OSHA crane-lifting certification expansion:Module transport and site-connection protocol standardization under ICC evaluation service listings opens market access for manufacturing entrants meeting established workplace safety benchmarks.
- Multi-family developer incremental efficiency capture:Wall panel systems offer single-family and multi-family residential developers schedule compression without requiring full volumetric process overhaul or capital-intensive factory investment.
Industry Challenges
- Digital twin integration skill scarcity:Factory-to-site coordination requires Building Information Modeling specialists capable of resolving tolerance conflicts between two-millimeter factory precision and field-adjusted foundation conditions.
- Fire-resistance rating certification timelines:Metal and concrete material specifications for commercial spans face extended testing protocols under evolving structural safety assessments.
- Site-connection trade interface management:Crane-set installation demands precise sequencing between factory-delivered modules and residual mechanical-electrical-plumbing rough-in work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prefabricated Construction Market |
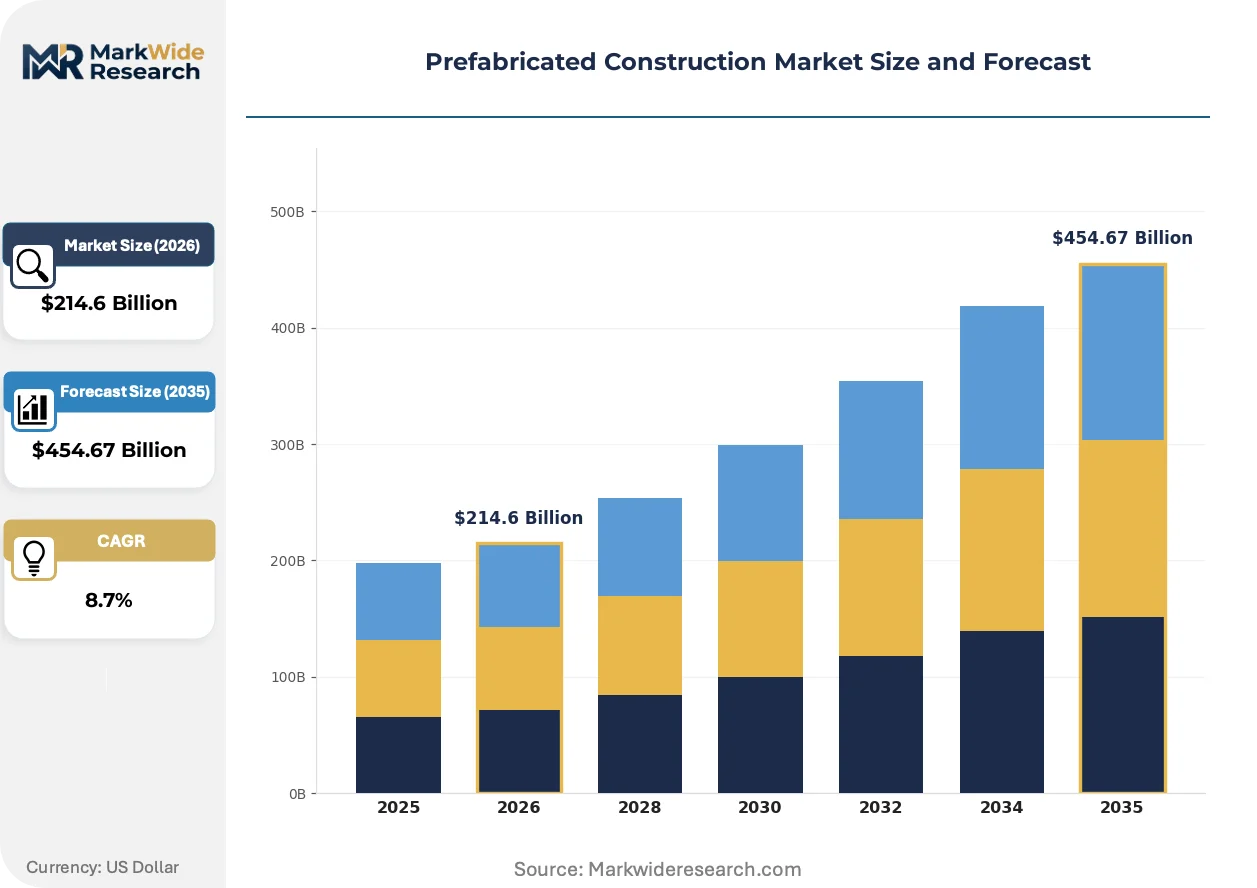
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $454.67 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Panels, Roofing Systems, Modular Units, Building Blocks Material: Wood, Metal, Concrete, Plastic End User: Residential, Commercial, Industrial, Educational Building Type: Single-Family Homes, Multi-Family Dwellings, Office Buildings, Retail Spaces |
| Companies Covered | Skyline Champion Corporation, Lindal Cedar Homes, Algeco Scotsman, Astron Buildings, Laing O’Rourke, Red Sea International, Clayton Homes, Kingspan Group, Larsen & Toubro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prefabricated Construction Market Emerging Trajectories
Factory-controlled production environments are enabling precision tolerances that site-built construction cannot replicate, while regulatory pressure on embodied carbon accelerates material substitution and process re-engineering across healthcare and residential verticals.
Cross-laminated timber (CLT) and mass timber hybrid systems are displacing conventional steel and concrete framing in mid-rise residential and commercial applications. German and Austrian developers are specifying these materials for six-to-twelve-story projects at accelerating pace. This shift is compressing structural carbon intensity while demanding new factory moisture-control protocols and transport protection systems.
REACH chemical compliance and the EU Green Deal's lifecycle assessment requirements are mandating environmental product declarations for all construction materials entering European markets. Factory producers must now document embodied carbon from raw extraction through module completion. Insulated panel and structural frame manufacturers serving hospital and municipal housing sectors are investing in supply chain traceability systems to maintain CE marking eligibility.
Hospital procurement officers are consolidating vendor relationships around single-source accountability for modular clinical wings, replacing fragmented general contractor management with direct manufacturing contracts. NHS trusts in England and university hospital systems in Germany are leading this consolidation. This pattern concentrates specification power with manufacturing entities capable of warranting full building envelope performance.
Prefabricated Construction Market Segmentation
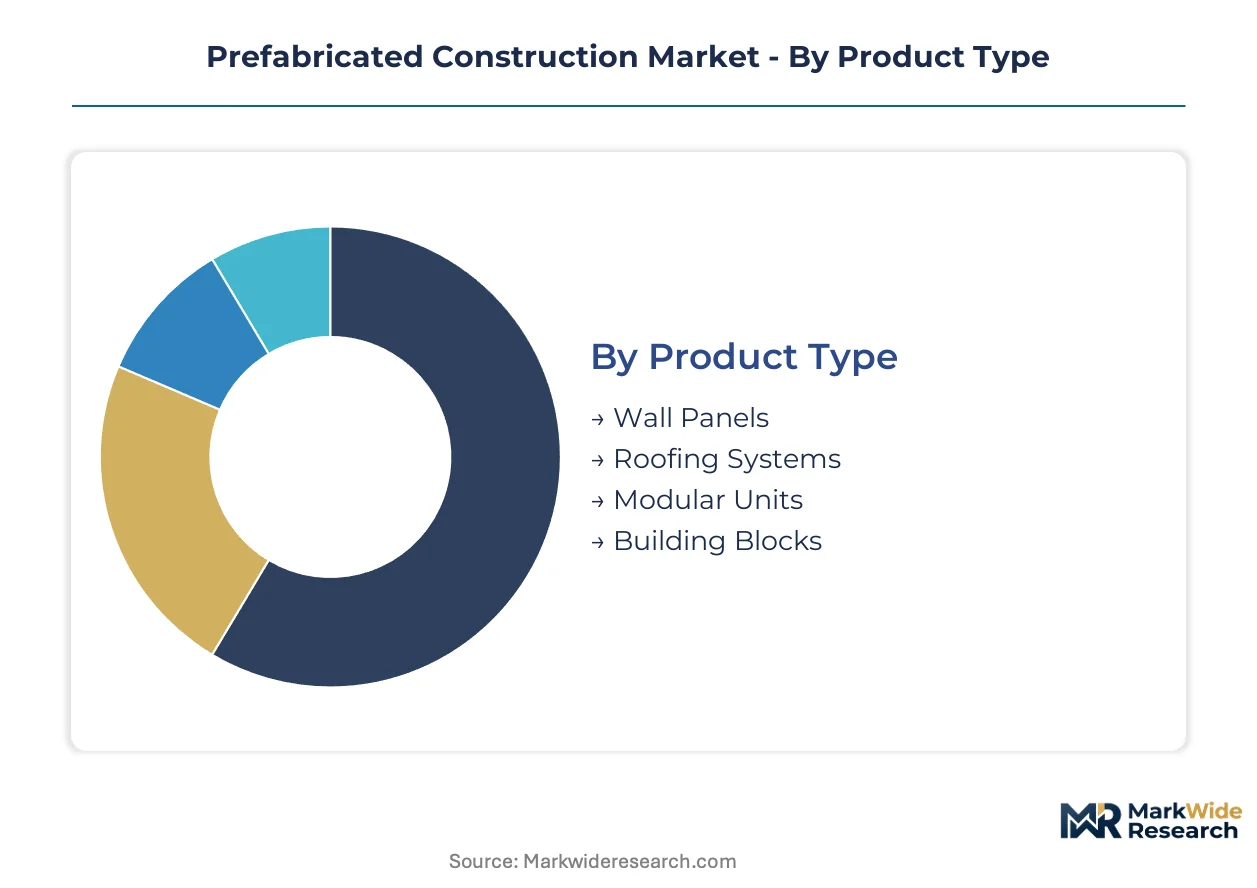
Segmentation in prefabricated construction reveals where capital efficiency concentrates and where regulatory pressure reshapes specification patterns. Product architecture, material chemistry, end-use requirements, and building typology each create distinct margin pools and compliance burdens.
Product Type:
Margin pools deepen where factory completion eliminates site trade interfaces, with volumetric solutions commanding premium positioning against panelized alternatives.
- Modular Units:Complete volumetric rooms or building sections manufactured with MEP rough-in, finishes, and fixtures installed under controlled conditions. Hospital procurement officers in Germany and the United Kingdom are embedding volumetric delivery clauses into clinical wing contracts, compressing commissioning timelines while factory-controlled infection prevention specifications meet NHS trust standards.
- Wall Panels:Structural or non-structural factory-built panels incorporating insulation, sheathing, and sometimes cladding. Single-family and multi-family residential developers across the southeastern United States specify these systems for schedule compression without requiring full process overhaul or capital-intensive factory investment.
- Roofing Systems:Pre-assembled trusses, cassettes, or complete roof modules craned into position. German municipal housing associations in the Stuttgart-Dortmund cluster leverage these for multi-story residential weathering speed.
- Building Blocks:Interlocking or mortarless masonry units produced with precision dimensional tolerance. These suit incremental commercial and industrial expansion projects where phased occupancy reduces capital lock-up.
Modular Units hold installed capacity. Wall Panels is rotating up the share rankings.
Material:
Specification share shifts track embodied carbon accounting intensity, with low-carbon alternatives gaining procurement preference under EU Green Deal benchmarks.
- Metal:Steel framing and structural elements offering superior fire-resistance ratings and long structural spans for commercial and industrial applications. CE marking pathways under the Construction Products Regulation now require environmental product declarations documenting extraction-to-completion carbon intensity.
- Wood:Cross-laminated timber and mass timber hybrid systems displacing conventional framing in mid-rise residential and commercial projects. German and Austrian developers specify these for six-to-twelve-story buildings, demanding new factory moisture-control protocols and transport protection systems.
- Concrete:Precast structural elements and insulated sandwich panels delivering thermal mass and acoustic separation. Extended fire-resistance rating certification timelines under evolving structural safety assessments create supply bottlenecks for complex commercial spans.
- Plastic:Composite and polymer-based components for non-structural applications including cladding, decking, and utility systems. REACH chemical compliance mandates restrict formulation options for European market access.
Metal dominates commercial specification. Wood is climbing the fastest under carbon accounting pressure.
End User:
Customer procurement sophistication varies sharply, with institutional buyers consolidating vendor relationships around single-source accountability while residential developers prioritize incremental efficiency capture.
- Healthcare:Hospital systems replacing traditional general contractors with direct manufacturing contracts for patient towers and clinical wings. NHS trusts and German university hospital systems lead this consolidation, concentrating specification power with entities capable of warranting full building envelope performance.
- Residential:Factory-built housing associations and municipal developers establishing dense supplier ecosystems. The Stuttgart-Dortmund cluster achieves logistics optimization that reduces module transport costs for multi-story projects.
- Commercial:Office and retail developers seeking speed-to-market through panelized or volumetric solutions. OSHA crane-lifting certification requirements and ICC evaluation service listings create compliance cost differentiation between established and new market entrants.
- Educational:School districts and university systems with summer construction windows demanding compressed schedules. Building code equivalency determination delays in jurisdictions without modular-specific approval pathways extend permitting timelines and deter adoption.
Healthcare commands specification power. Residential rotates up on volume scale.
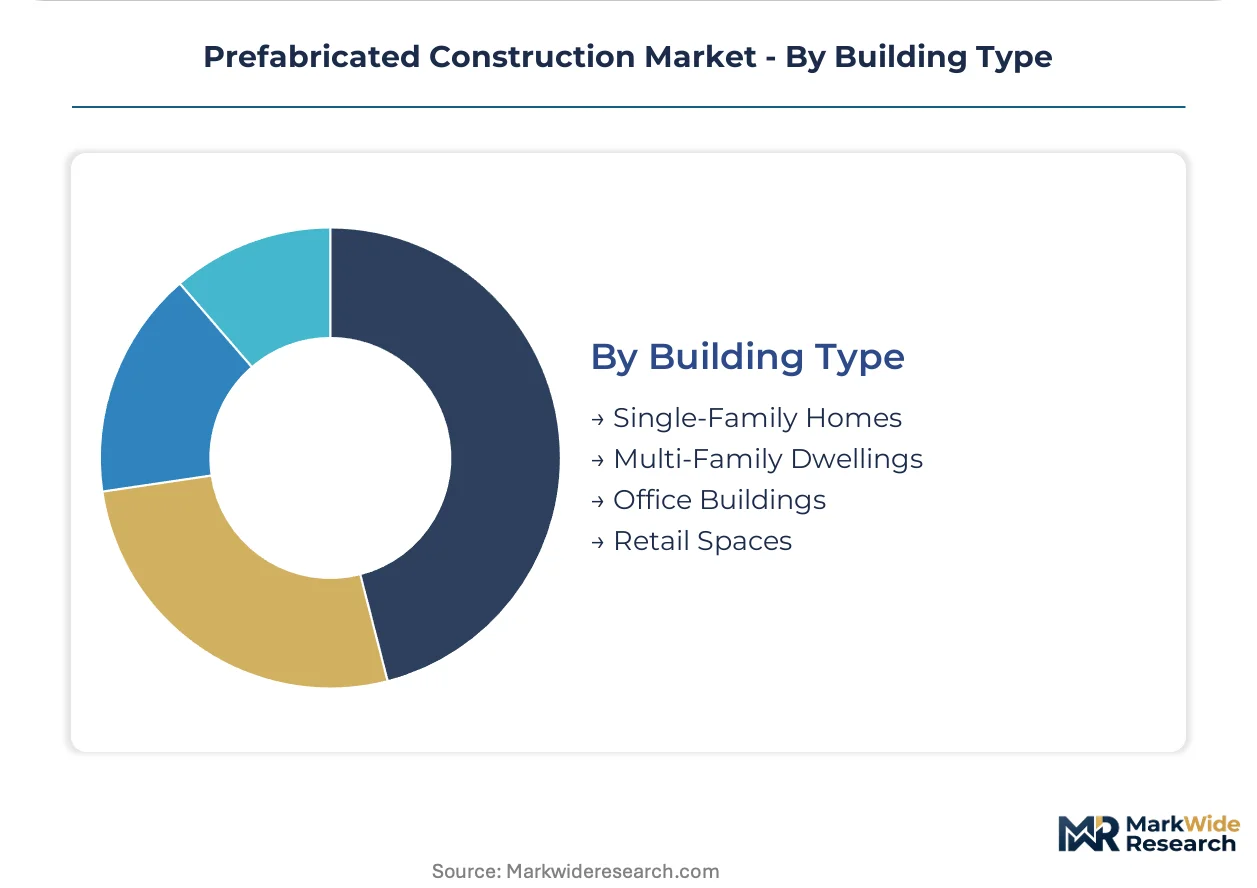
Building Type:
Structural complexity and regulatory scrutiny intensity determine factory investment requirements and margin sustainability across building typologies.
- Multi-Family Dwellings:Mid-rise and high-rise residential buildings where repetitive unit configurations reward factory standardization. German municipal developers achieve logistics optimization through supplier ecosystem density around manufacturing clusters.
- Office Buildings:Commercial workspaces demanding flexible floor plates and MEP distribution. Metal and concrete specifications intensify as fire-resistance ratings and structural span requirements tighten.
- Single-Family Homes:Detached and attached housing where Clayton Homes anchors the residential modular segment through vertically integrated manufacturing networks across the southeastern United States.
- Retail Spaces:Quick-service restaurants, big-box stores, and strip retail requiring rapid deployment. Specialized transport carrier concentration with regional logistics providers creates bottleneck risk for just-in-time module delivery to dense urban infill sites.
Multi-Family Dwellings hold installed capacity. Office Buildings is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export volumetric modules to NHS trusts in the United Kingdom, establishing a cross-border trade corridor that compresses delivery timelines for hospital infrastructure projects.
United States
OSHA crane-lifting certification requirements and ICC evaluation service listings govern module transport protocols across southeastern manufacturing networks. Factory-built housing associations in Georgia and Alabama leverage vertically integrated production to serve multi-family residential developers. Clayton Homes anchors this segment through captive supply networks spanning the Carolinas to Texas.
Germany
Factory-built housing associations and municipal developers in the Stuttgart-Dortmund corridor achieve logistics optimization that reduces transport costs for multi-story residential modules. EU Green Deal embodied carbon thresholds under the Construction Products Regulation mandate environmental product declarations for CE marking eligibility. Kingspan Group exemplifies insulated panel production serving temperature-sensitive medical environments across Baden-Württemberg and North Rhine-Westphalia.
United Kingdom
NHS trusts embed volumetric delivery clauses into procurement frameworks for modular patient towers and clinical wings. Laing O'Rourke sustains manufacturing scale through its Explore Industrial Park facility producing fully fitted bathroom pods for hospital contracts. Building code equivalency determinations between factory and site-built assemblies remain under review in jurisdictions with conservative inspection regimes.
China
GB standards and MIIT industrial policy directives accelerate factory-built component certification for mid-rise residential and commercial applications. Yangtze River Delta manufacturers supply structural steel modules to Southeast Asian infrastructure projects. Dual carbon goals under MEE oversight compress timelines for low-carbon material substitution in prefabricated concrete and metal framing systems.
United Arab Emirates
MOHAP procurement standards and Dubai Municipality building codes drive specification of fire-resistant modular units for healthcare and hospitality verticals. Red Sea International occupies a position among Gulf-based fabricators serving rapid-deployment retail and clinical infrastructure. NEOM Northwest development mandates factory-built solutions to compress construction schedules across its linear city corridor.
Prefabricated Construction Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and project delivery integration, creating a tiered structure where capital access separates volume players from regional fabricators. Consolidation concentrates around entities controlling factory networks and crane-capable logistics partnerships. Three archetypes dominate: vertically integrated housing manufacturers, insulated envelope specialists, and infrastructure-led construction conglomerates. Competitive moves center on backward integration into structural materials and strategic partnerships with healthcare procurement officers.
Within the infrastructure-led tier, Laing O'Rourke and Larsen & Toubro exemplify construction conglomerates that have captured manufacturing capabilities to serve hospital and municipal clients directly. Among residential specialists, Skyline Champion Corporation and Clayton Homes occupy positions that span factory production through retail distribution. Kingspan Group anchors the insulated envelope segment, representing the archetype of materials-science-driven manufacturers that warrant thermal performance for temperature-sensitive end uses.
| Leading Market Players |
|---|
| Skyline Champion Corporation |
| Lindal Cedar Homes |
| Algeco Scotsman |
| Astron Buildings |
| Laing O'Rourke |
| Red Sea International |
| Clayton Homes |
| Kingspan Group |
| Larsen & Toubro |
| Others |
Supply Flow & Price Mechanics
Fixed-price modular contracts with penalty clauses for schedule overruns lock in supply access for NHS trusts and German hospital systems while compressing margin visibility for manufacturers exposed to steel and engineered timber volatility. This structure transfers completion risk to factory operators who must absorb input cost swings without price adjustment mechanisms.
Pricing Analysis
Current-generation volumetric modules with full MEP integration command premium positioning against prior-generation panelized systems lacking factory-finished interiors. Three-tier pricing structure across premium, standard, and economy levels separates infection-control-certified clinical wings from basic residential modules from uninsulated structural shells. Price differentiation rests on CE marking tier and thermal-bridge-free certification grade. Cost compression in standard-tier residential contracts is intensifying because German municipal housing associations consolidate procurement volumes. Multi-family developers exhibit highest price sensitivity, while NHS trusts demonstrate lowest sensitivity given clinical commissioning timeline imperatives.
Supply Chain Analysis
Germany and the United Kingdom anchor precision manufacturing of volumetric clinical modules, while China supplies structural steel framing and precast concrete components at scale. Factory production draws from cross-laminated timber feedstock sourced from Austrian and Bavarian sawmills, engineered timber adhesives subject to REACH compliance verification, and crane-capable heavy haulage capacity concentrated with regional logistics providers. Single-source vulnerability concentrates in specialized transport carriers serving just-in-time delivery to dense urban infill sites. Distribution runs through manufacturing-led direct contracts with hospital procurement officers, bypassing traditional general contractor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Factory-to-site coordination capabilities are scarce relative to demand compression from healthcare procurement officers, creating asymmetric returns for entities controlling Building Information Modeling specialists and crane-certified logistics partnerships.
For Market Incumbents: Secure backward integration into structural materials to capture margin pools eroded by steel and engineered timber input volatility. Lock in long-term offtake agreements with NHS trusts and German university hospital systems before procurement consolidation hardens vendor selection criteria. Invest in CE marking pathway acceleration to maintain cross-border eligibility under EU Green Deal embodied carbon thresholds. For New Entrants and Emerging Players: Differentiate on digital twin integration services resolving tolerance conflicts between two-millimeter factory precision and field-adjusted foundation conditions. Target educational sector summer construction windows where building code equivalency determination delays have deterred established modular suppliers. Pursue direct manufacturing contracts with school districts bypassing general contractor intermediaries. For Investors and Strategic Acquirers: Manufacturing-led construction conglomerates with captive crane-capable logistics networks represent the most defensible acquisition archetype for exposure to healthcare infrastructure procurement consolidation. Long-term viability hinges on entities warranting full building envelope performance across temperature-sensitive medical environments. Watch for inflection signals in OSHA crane-lifting certification expansion rates indicating market access breadth for modular solutions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Structural Materials | Captures margin pools eroded by steel and timber input volatility facing fixed-price contracts. |
| CE Marking Pathway Acceleration | Secures EU Green Deal eligibility for cross-border hospital and municipal housing contracts. |
| Digital Twin Integration Services | Resolves tolerance conflicts between factory precision and field-adjusted foundation conditions. |
| Crane-Capable Logistics Partnerships | Eliminates bottleneck risk for just-in-time module delivery to dense urban infill sites. |
| Direct Hospital Procurement Contracts | Replaces fragmented general contractor management with single-source accountability for clinical wings. |
Methodological Framework
Initial hypotheses were tested against primary input from hospital procurement officers, modular manufacturing plant managers, crane-certified logistics operators, and building code equivalency determination officials and refined through secondary validation against Construction Products Regulation filings, NHS trust procurement databases, EU EPD registry entries, and ICC evaluation service listings. Bottom-up volume estimates from factory capacity utilization rates were triangulated against top-down healthcare infrastructure spending allocations.
Variance decomposition across product type, material chemistry, end-user procurement sophistication, and building typology structural complexity shaped analytical framework development over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated embodied carbon accounting intensity trajectories under EU Green Deal benchmarks and OSHA workplace safety standard evolution timelines.
Decision-makers should treat outputs as directional under assumptions of continued NHS trust procurement consolidation and stable German municipal housing association demand; material deviation in steel input costs or building code equivalency ruling velocity would warrant model refresh. Recalibration cycles align with material shifts in EU Green Deal enforcement intensity and healthcare infrastructure budget allocation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Middle East Building Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
Brazil Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
South Korea Data Center Construction Market
Building Construction
Precast Construction Market
Building Construction
Early Production Facility Market
Building Construction
Qatar Construction Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Kuwait Construction Market
Building Construction
Modular and Portable Building Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Germany Commercial Construction Market