
 Door System Market | 2026-2036
Door System Market Size, Share, and Industry Trends Forecast 2026-2036
Door System Market Analysis
Aftermarket service revenue is rewriting how door system manufacturers capture lifetime value from installed bases. Assa Abloy leverages its global service network to extend recurring maintenance contracts beyond hardware sales. Allegion Plc anchors its position through digital access-control integration that sustains higher-margin software attach rates. Masonite International Corporation specializes in residential fiberglass and steel door lines that dominate North American new construction channels.
A door system comprises the complete assembly of panels, frames, hardware, and operating mechanisms engineered to control ingress, egress, and environmental separation in buildings. These assemblies must meet specified fire ratings, acoustic dampening values, and air infiltration limits depending on application codes and climate zones. Aluminum and steel material segments lead commercial and industrial specifications where durability and security ratings command premium positioning. Electronic and automatic technology categories are expanding fastest as building automation retrofits accelerate across aging commercial stock in Europe and North America. Residential end-user demand remains the largest volume pool though margins compress amid commodity wood and fiberglass competition.
FDA guidelines for cleanroom and pharmaceutical facility doors, EPA energy-efficiency mandates for federal buildings, and EU Green Deal envelope-performance standards collectively reshape product specifications and certification requirements across major demand centers. Compliance with these frameworks now determines market access for suppliers serving healthcare, government, and commercial construction verticals. Stakeholders must monitor evolving energy codes and smart-building interoperability standards to align R&D investment with procurement criteria that facility operators will enforce.
Market Dynamics
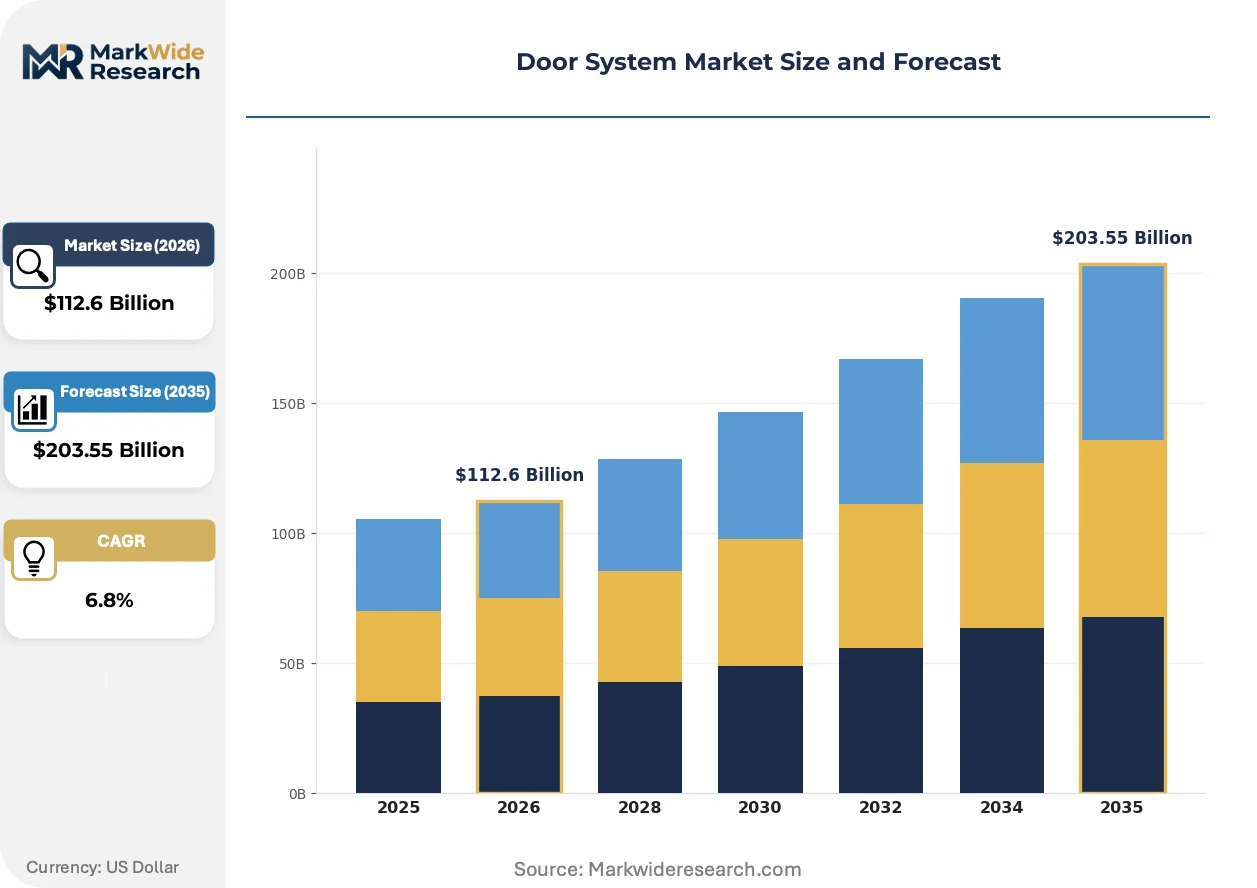
The Door System Market is restructuring around energy-performance mandates and building-automation integration. EU Green Deal envelope standards and US federal efficiency procurement rules are forcing specification upgrades across commercial and institutional channels.
Growth Catalysts
- EU Green Deal envelope-performance standards:These regulations mandate thermal-break aluminum frames and low-U-value glazing in new commercial construction across member states. Retrofit demand accelerates as existing stock must meet tightening energy codes.
- Hospital and pharmaceutical facility expansion:FDA cleanroom guidelines specify hermetically sealed door systems with positive-pressure integrity. Healthcare construction in the United States drives premium-specification volume for stainless steel and automated access assemblies.
- China's urban residential construction pipeline:Provincial governments in Jiangsu and Guangdong are mandating smart-entry systems in high-rise residential towers. Aluminum and biometric-enabled door systems capture volume from this concentrated demand pool.
Market Restraints
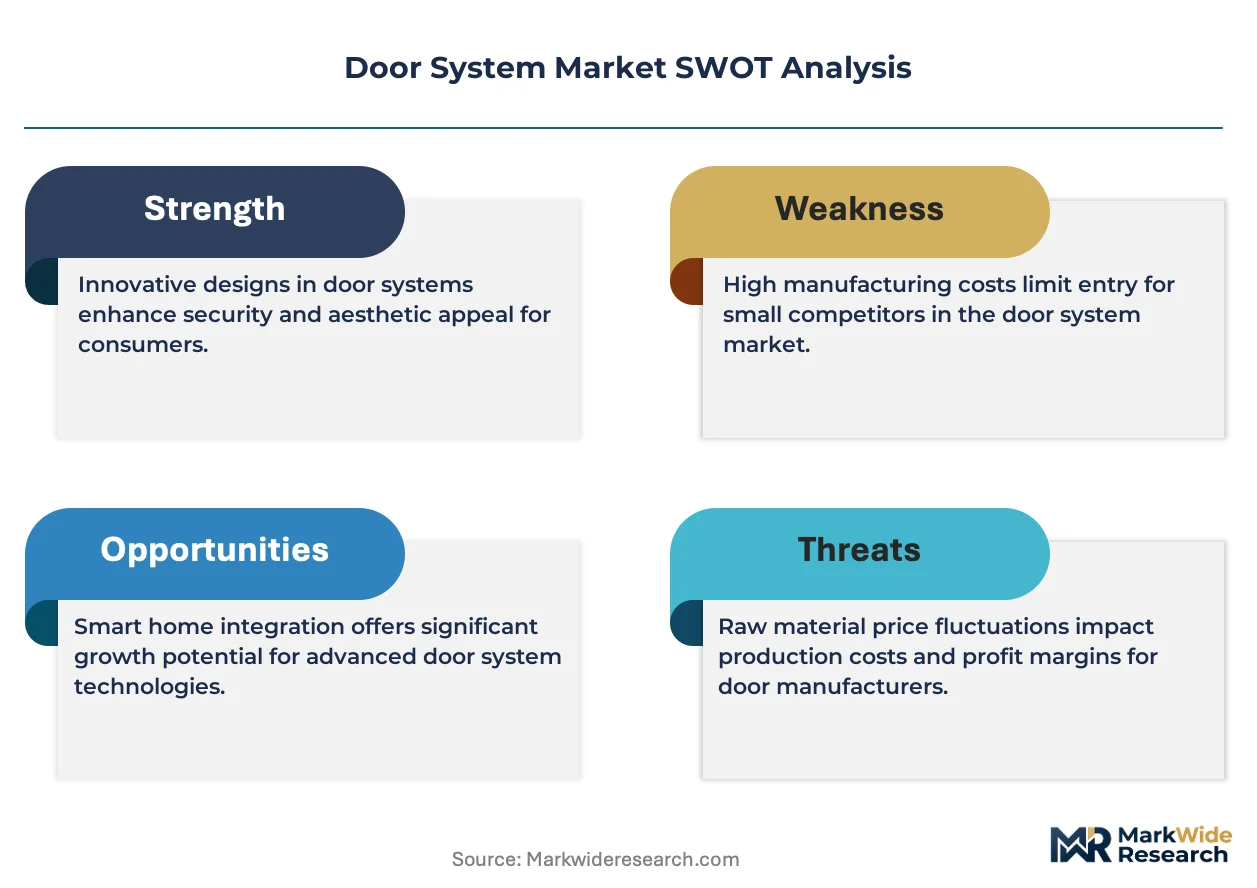
- Aluminum and steel input cost volatility:London Metal Exchange price swings for primary aluminum and hot-rolled steel compress margin predictability for frame and panel manufacturers. Long-delivery raw material contracts expose producers to margin squeeze when spot prices spike.
- Fire-rating certification timelines:UL 10C and NFPA 252 testing protocols require 6-12 month validation cycles for new door-core formulations. Product launch delays accumulate when retesting is triggered by material substitution.
- Wood-composite substitution in residential: Fiberglass and engineered wood door systems compete aggressively on first-cost in North American single-family construction. Steel and aluminum premium positioning loses share in price-sensitive builder-grade segments.
Strategic Opportunities
- India's affordable housing construction targets:The country's PLI scheme for building materials incentivizes domestic door-frame manufacturing. Local production partnerships can capture volume from the 20 million annual housing unit construction goal.
- Biometric-facial recognition convergence:Integration of thermal imaging and access-control software creates premium positioning for commercial entry systems. Financial services and data center end-uses in Singapore and South Korea are early adopters.
- Outcome-based maintenance contracts:Facility operators in Germany and the Netherlands are unbundling hardware procurement from lifecycle service agreements. Predictive uptime guarantees replace traditional break-fix service models.
Industry Challenges
- Building automation protocol fragmentation:BACnet, KNX, and proprietary smart-building systems require redundant hardware interfaces. Door system OEMs must maintain multiple firmware branches, inflating R&D overhead.
- Skilled installer scarcity for automated systems:Electromechanical integration and safety-sensor calibration demand certified technicians. Labor availability constrains deployment velocity for commercial retrofit projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Door System Market |
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $203.55 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Bi-Fold Doors, Revolving Doors, Pivot Doors Material: Wood, Aluminum, Glass, Steel End User: Residential, Commercial, Industrial, Institutional Technology: Manual, Electronic, Automatic, Hybrid |
| Companies Covered | Assa Abloy, Allegion Plc, Masonite International Corporation, Andersen Corporation, JELD-WEN Holding, Inc., Dorma Kaba, LIXIL Corporation, Cornerstone Building Brands, Pella Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Door System Market Emerging Trajectories
Digital access credentials and predictive maintenance algorithms are displacing mechanical keys and scheduled service intervals. Specification criteria now prioritize interoperability and lifecycle data transparency over standalone hardware performance.
Computer-vision access control is digitizing entry authentication across high-security commercial facilities. The technology replaces card readers and PIN pads with facial-recognition and behavioral-biometric verification. Corporate headquarters and government buildings in the United States and United Arab Emirates are deploying these systems at scale. Hardware margins compress as software licensing and cloud-connectivity fees capture recurring value.
REACH substance restrictions on flame retardants and plasticizers are reformulating door-core and sealant chemistries. Manufacturers must substitute halogenated compounds with phosphorus-based alternatives to maintain CE marking eligibility. Panel and frame producers serving European healthcare and education verticals face 18-month material qualification cycles. Supply chains are regionalizing to limit cross-border compliance friction.
Facility management procurement teams are consolidating vendor relationships around integrated envelope-performance contracts. Single-source accountability for doors, windows, and facade systems displaces fragmented component bidding. German and French commercial real estate operators are piloting total-cost-of-ownership frameworks that weight energy performance over first-cost. Specification influence is shifting from general contractors to owner-operators with long-hold asset strategies.
Door System Market Segmentation
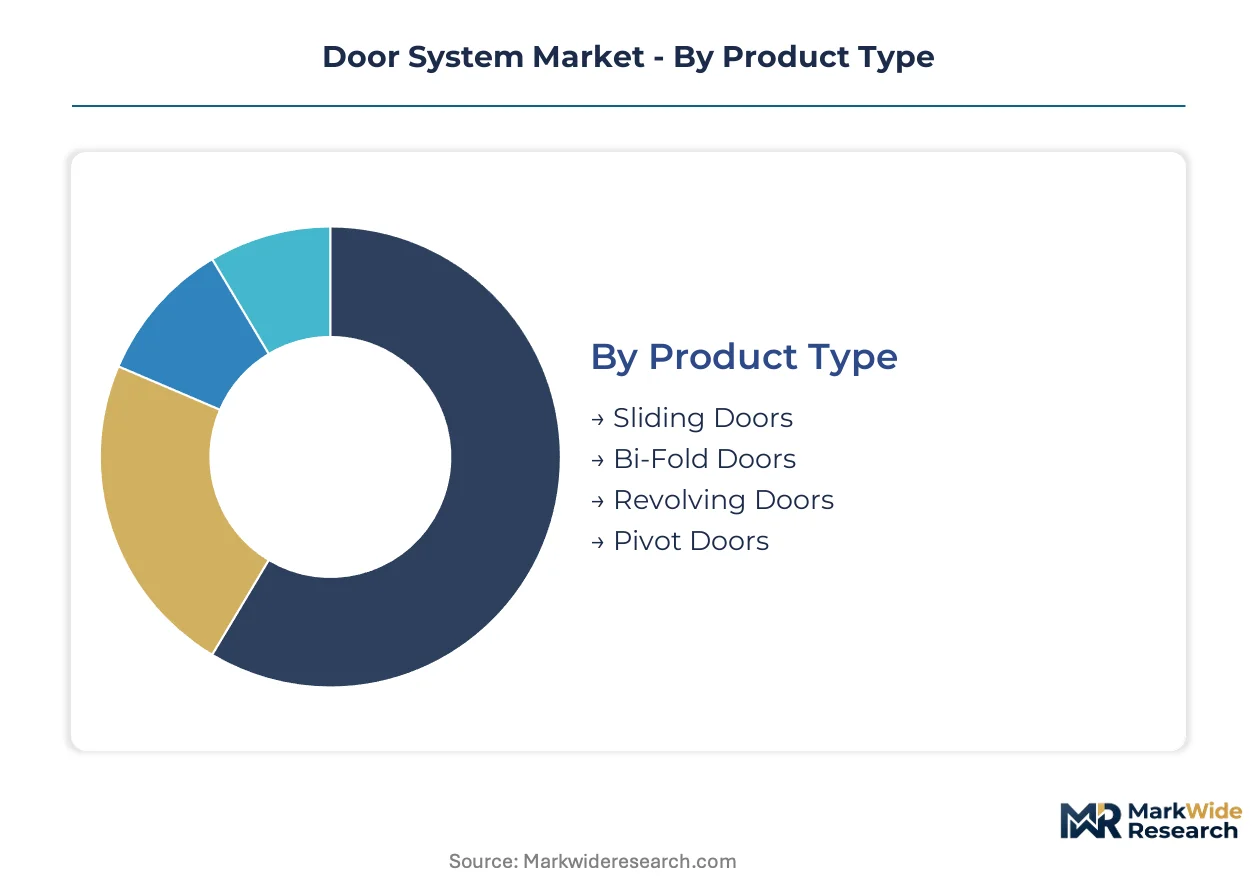
Door system procurement patterns diverge sharply across operating environments. Specification cycles range from decades for institutional infrastructure to under ten years for residential retrofits, creating distinct revenue rhythms for manufacturers serving each segment pool.
Product Type:
Replacement cycles stretch from five years for high-traffic automatic entries to thirty-plus years for structural pivot installations in heritage buildings. The turnover velocity determines aftermarket service attach rates and upgrade conversion opportunities.
- Sliding Doors:Aluminum-framed assemblies with thermal-break construction dominate commercial retrofits across Germany and the Netherlands. Airport terminals in Dubai and Singapore specify oversized glass-panel systems with integrated access control. These systems turn over fastest in high-traffic environments where rail wear and seal degradation demand scheduled replacement.
- Bi-Fold Doors:Multi-panel folding mechanisms maximize aperture width for residential indoor-outdoor living applications. California and Florida coastal construction drives demand for marine-grade hardware and impact-rated glazing. The segment expands most quickly in luxury single-family construction where wall-to-wall opening dimensions command premium positioning.
- Revolving Doors:Airlock configurations reduce HVAC load in high-rise commercial lobbies. CE marking and UL 10C fire ratings constrain supplier qualification to established OEMs with testing infrastructure.
- Pivot Doors:Offset hinge mechanisms support oversized panels in architectural statement entries. Custom fabrication cycles extend lead times beyond standard prehung assemblies.
Sliding doors dominate installed base across commercial channels. Bi-fold doors are where expansion concentrates in residential new construction.
Material:
Raw material cost exposure and fabrication complexity stratify margin profiles across the four primary substrates. Aluminum and steel command specification premiums where fire ratings and structural loads dictate performance minimums.
- Aluminum:Extruded thermal-break frames with polyamide strips meet EU Green Deal U-value mandates for commercial envelopes. German and French facade contractors specify these systems for energy retrofit contracts tied to CSRD disclosure requirements. The material captures the steepest specification climb as envelope-performance standards tighten across European member states.
- Steel:Hollow metal cores with mineral wool infill achieve three-hour fire ratings for hospital and data center applications. US federal buildings procurement under EPA mandates specifies domestic steel content for GSA schedule eligibility. Demand concentrates in institutional verticals where security ratings and blast resistance override first-cost considerations.
- Wood:Engineered stile-and-rail construction with MDF skins serves North American residential volume channels. Fiberglass skin substitution erodes share in exterior exposure applications.
- Glass:Structural glazing systems with low-iron substrates maximize daylight transmission in corporate headquarters. Laminated safety interlayers satisfy impact requirements for high-occupancy public buildings.
Steel dominates institutional specification where life-safety ratings apply. Aluminum is where specification upgrades concentrate under energy-code pressure.
End User:
Procurement authority and total-cost-of-ownership horizons reshape competitive dynamics across the four demand pools. Owner-operators with long-hold asset strategies weight lifecycle performance differently than speculative developers.
- Commercial:Office towers and retail complexes in the United States and United Arab Emirates specify integrated access-control compatibility. Facility management outsourcing drives outcome-based maintenance contract structures. The segment generates the highest service revenue attach rates through multi-year uptime guarantees.
- Residential:Single-family and multifamily construction in China and India drives volume for standard-grade fiberglass and steel entry systems. Provincial smart-entry mandates in Jiangsu and Guangdong accelerate technology penetration. Volume concentration here compresses hardware margins while creating software subscription opportunities.
- Industrial:Manufacturing facilities and warehouses require high-cycle durability for loading dock and interior process doors. Rapid-roll and sectional overhead configurations dominate this specification set.
- Institutional:Schools, government buildings, and cultural facilities prioritize vandal resistance and accessibility compliance. ADA and EN 16005 standards dictate automatic operator specifications.
Residential commands unit volume leadership. Commercial is where margin expansion concentrates through service bundling.
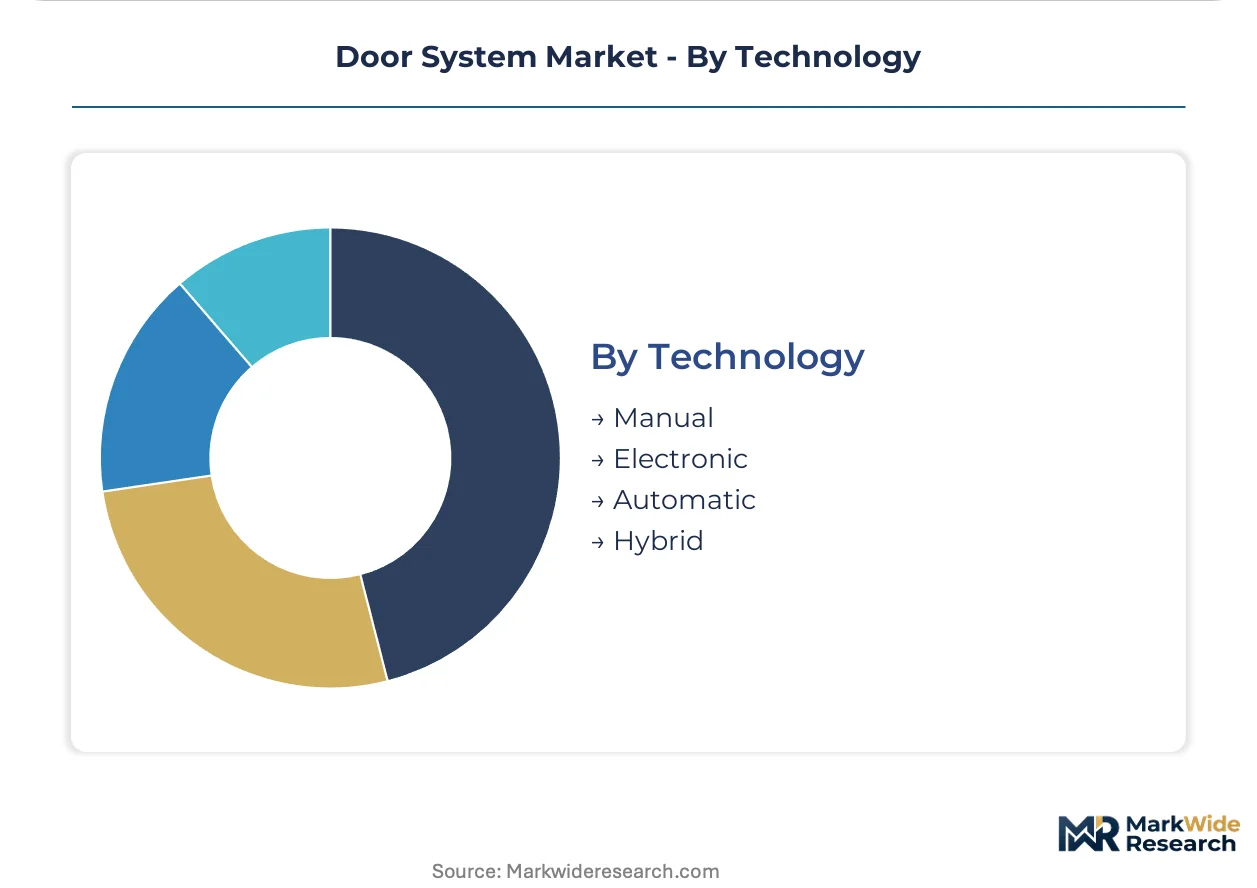
Technology:
Electromechanical complexity and connectivity requirements separate legacy hardware from next-generation building-automation integration. Firmware update capabilities and sensor fusion now enter specification criteria alongside mechanical durability.
- Automatic:Sensor-activated operators with microwave and infrared presence detection serve high-traffic healthcare and transportation facilities. BACnet and KNX protocol compatibility enables integration with building management systems. The category gains share fastest as aging commercial stock undergoes accessibility and efficiency retrofits across Europe and North America.
- Electronic:Credential-based access with RFID, NFC, and mobile token authentication replaces mechanical master key systems. Corporate campuses in South Korea and Singapore deploy facial-recognition convergence for contactless entry.
- Manual:Traditional hinged and sliding configurations persist in cost-sensitive residential and light commercial applications. Hardware-only specifications limit recurring revenue opportunities.
- Hybrid:Manual override capability with electronic monitoring bridges reliability and audit requirements. Critical infrastructure facilities specify these systems for fail-safe operation during power events.
Manual systems dominate legacy installed base. Automatic technology is where retrofit investment concentrates as building automation retrofits accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes door systems for high-rise residential volume, while Germany and the United States specify thermal-break aluminum and integrated access control for commercial envelopes. This consumption-mix differential creates divergent margin pools across geographies.
United States
Commercial real estate developers in Dallas and Atlanta are expanding automatic door installations for accessibility compliance. EPA energy-efficiency mandates for federal buildings specify domestic steel content and low-U-value assemblies. Hospital construction in Houston and Phoenix drives premium-specification volume for stainless steel and hermetically sealed access systems.
Germany
Facade contractors in Munich and Frankfurt specify thermal-break aluminum frames for energy retrofit contracts tied to CSRD disclosure requirements. EU Green Deal envelope-performance standards mandate polyamide strip construction across commercial new builds. Industrial clusters in North Rhine-Westphalia concentrate fabrication capacity for automated entry systems serving Dutch and Belgian export markets.
China
Provincial governments in Jiangsu and Guangdong mandate smart-entry systems in high-rise residential towers. GB standards for building energy efficiency tighten thermal performance requirements for aluminum frames in commercial construction. Manufacturing concentration in the Yangtze River Delta supplies aluminum and biometric-enabled door systems for domestic and Southeast Asian markets.
United Arab Emirates
Airport terminals in Dubai and Abu Dhabi specify oversized glass-panel sliding systems with integrated access control. MOHAP guidelines for healthcare facilities drive hermetic sealing requirements for hospital entries. Commercial tower construction in Dubai Marina concentrates demand for revolving airlock configurations that reduce HVAC load.
India
The PLI scheme for building materials incentivizes domestic door-frame manufacturing for affordable housing targets. BIS certification requirements for fire-rated assemblies reshape product specifications in commercial and institutional verticals. Construction activity in Maharashtra and Gujarat concentrates demand for steel and aluminum entry systems in high-rise residential and IT campus developments.
Door System Market Vendor Landscape
Capability concentration sits with premium-tier specialists commanding specification influence in institutional and healthcare verticals; scale advantage sits with volume manufacturers serving residential construction channels. The market structures around three tiers: integrated building-products conglomerates with envelope-system portfolios, electromechanical specialists with access-control software stacks, and regional fabricators competing on first-cost in commodity segments. Dominant competitive moves include backward integration into aluminum extrusion and mineral-wool core production, plus outcome-based service contract structures that unbundle hardware from lifecycle maintenance.
Among integrated access-control specialists, Assa Abloy and Allegion Plc exemplify the capability-driven tier, with the former representing global service-network scale and the latter occupying a position in digital credential convergence. Masonite International Corporation anchors the residential-volume segment among North American-oriented fabricators. These three names illustrate the strategic archetype spectrum: electromechanical integration, software attach-rate expansion, and channel dominance in new-construction supply chains.
| Leading Market Players |
|---|
| Assa Abloy |
| Allegion Plc |
| Masonite International Corporation |
| Andersen Corporation |
| JELD-WEN Holding, Inc. |
| Dorma Kaba |
| LIXIL Corporation |
| Cornerstone Building Brands |
| Pella Corporation |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster anchors aluminum extrusion and biometric hardware capacity that feeds downstream pricing power to door system OEMs serving Southeast Asian export markets. Contract structures and raw material cost pass-through mechanisms stratify margin predictability across premium specification tiers.
Pricing Analysis
Long-term offtake agreements with London Metal Exchange-linked aluminum pricing clauses dominate commercial frame procurement, insulating large OEMs from spot volatility that squeezes regional fabricators. Three-tier pricing structure across premium, standard, and economy levels separates UL 10C-certified institutional assemblies from builder-grade residential units. Cost compression in economy-tier fiberglass doors is intensifying because engineered wood substitution erodes steel entry system share. Single-family homebuilders exhibit acute price sensitivity, while hospital procurement committees weight lifecycle service costs over first-cost.
Supply Chain Analysis
Primary aluminum smelters in China, Russia, and Canada supply extrusion feedstock that door frame manufacturers draw from under annual volume contracts with quarterly price adjustments. Hot-rolled steel from domestic US mills and German integrated producers supports hollow metal core fabrication for fire-rated assemblies. Single-source vulnerability concentrates in polyamide thermal-break strip supply from specialized European chemical producers. Distribution runs through facade contractor networks in Germany and building materials distributors in North American residential channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent door system manufacturers face substitution pressure from integrated building envelope providers bundling doors with windows and facade systems under single-source accountability contracts.
For Market Incumbents: Harden specification influence by backward integration into aluminum extrusion capacity in Jiangsu province and mineral-wool core production for three-hour fire ratings. Invest in BACnet and KNX protocol certification to defend against electromechanical specialists capturing building automation retrofit contracts. For New Entrants and Emerging Players: India's Maharashtra and Gujarat affordable housing construction corridors offer underpenetrated volume for steel and aluminum entry systems serving PLI-subsidized domestic manufacturing. Target outcome-based maintenance contract structures for Dutch and German facility operators unbundling hardware from lifecycle service agreements. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because aftermarket service attach rates and software licensing fees displace transactional hardware margins across aging commercial building stock. Monitor biometric-facial recognition convergence adoption velocity in Singapore financial services and South Korean data center verticals as inflection indicator for premium technology penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captures thermal-break frame margin and secures supply for EU Green Deal retrofit contracts. |
| Biometric Access Control Platform Launch | Software licensing models displace hardware-only revenue in Singapore and UAE commercial towers. |
| Outcome-Based Maintenance Contract Structure | Predictive uptime guarantees align with German facility operator procurement consolidation trends. |
| Domestic Manufacturing Partnership in India | PLI scheme incentives support affordable housing volume capture in Maharashtra construction corridors. |
| REACH-Compliant Core Chemistry Reformulation | Phosphorus-based flame retardant substitution maintains CE marking eligibility for European healthcare verticals. |
Methodological Framework
Desk research of customs trade databases, SEC 10-K filings, and EU construction permit registries preceded structured interviews with facade contractors, hospital facility managers, residential homebuilder procurement leads, and aluminum extrusion plant engineers. Bottom-up volume triangulation across product type, material, and end-user segments was validated against top-down construction spending data from national statistics offices.
Assumptions held fixed include EU Green Deal envelope-performance standard enforcement timelines and China's provincial smart-entry mandate rollout pace across Jiangsu and Guangdong. Segmentation modeling incorporated technology tier, material substrate, and regional regulatory cluster dimensions. CAGRs were derived from fitted growth curves applied to construction pipeline data and replacement cycle velocity estimates.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by building-products conglomerates or rapid protocol standardization by BACnet and KNX alliances would shift outcomes. Cross-checking against national construction permit databases and GSA federal procurement schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Industrial Thermal Insulation Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Curtain Wall Market