
 Acoustic Ceiling Tiles Market | 2026-2036
Acoustic Ceiling Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Ceiling Tiles Market Analytics
Aftermarket service revenue for ceiling system refurbishment and acoustic performance auditing is reshaping how manufacturers capture lifetime value from installed bases. Armstrong World Industries leverages its national distribution network to sustain recurring specification relationships with healthcare and education contractors. ROCKWOOL anchors its position through backward integration into stone wool substrate production, controlling raw material quality and thermal-acoustic performance consistency. Hunter Douglas Architectural differentiates through metal ceiling system customization, competing on project-specific aesthetic and acoustic engineering rather than commodity volume.
Acoustic ceiling tiles are engineered panels designed to absorb sound energy and reduce reverberation, typically manufactured from mineral fiber, metal, or gypsum with Noise Reduction Coefficient ratings between 0.50 and 0.95 for commercial applications. Mineral fiber compositions dominate specification in open-plan offices and educational facilities where broadband sound absorption at speech frequencies remains critical. Metal ceiling systems command premium positioning in transportation hubs and corporate lobbies where durability and integrated lighting compatibility justify higher installed costs. Wood and gypsum segments occupy niche roles in heritage renovations and moisture-resistant healthcare environments respectively.
OSHA workplace noise exposure limits and the EPA's indoor air quality guidelines for commercial buildings shape product development priorities, particularly for low-emitting mineral fiber formulations. ASTM E1264 classification standards and ISO 11654 absorption ratings govern specification eligibility in federally funded institutional projects. Stakeholders must monitor evolving MEE and SAMR standards in China, where green building certification scope is expanding to include acoustic performance metrics for office and residential towers. Procurement teams face decisions about regional certification alignment versus global product platform standardization.
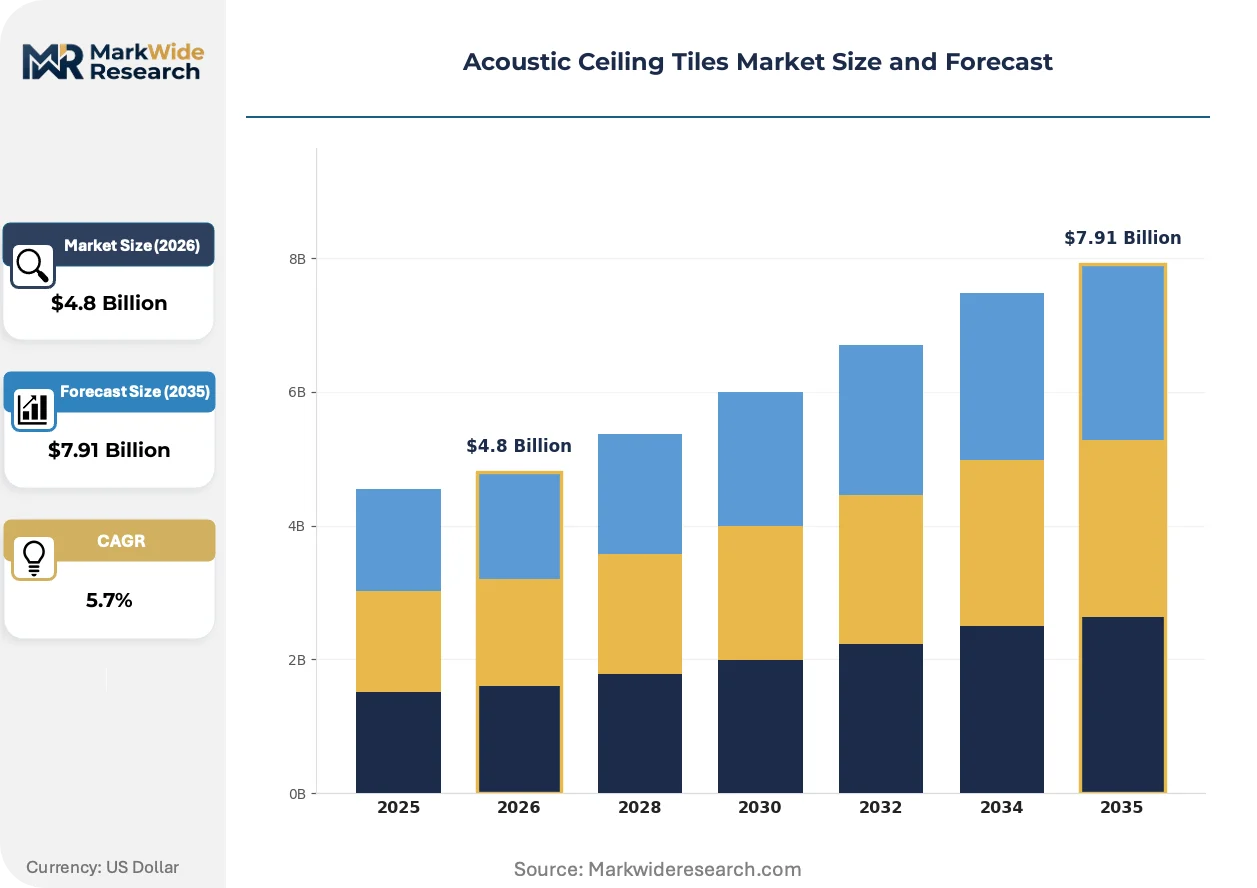
Market Dynamics
Healthcare construction in the United States is expanding acoustic tile procurement for patient-centered environments, while California's Title 24 energy code revisions push demand for thermally efficient ceiling assemblies. These dual pressures are compressing specification cycles and forcing manufacturers to integrate thermal-acoustic performance into single product platforms.
Growth Catalysts
- OSHA workplace noise exposure limits:Federal enforcement of permissible exposure limits in open-plan offices drives specification of high-NRC mineral fiber tiles. Facility managers face liability pressure to retrofit aging installations.
- LEED-equivalent building certifications:Germany's commercial renovation sector mandates acoustic performance as standard for office retrofits, accelerating replacement demand in Frankfurt and Munich commercial cores.
- Stone wool substrate technology:Backward integration into raw material production enables tighter control over thermal-acoustic consistency. Manufacturers capture margin through in-house supply of performance-critical inputs.
Market Restraints
- Mineral wool fiber cost volatility:Energy-intensive production of stone wool and fiberglass substrates exposes margins to natural gas price swings in European manufacturing clusters.
- Supply concentration in specialty coatings:Acoustic surface treatments for metal ceiling systems depend on a narrow base of chemical formulators, creating single-source vulnerability for premium finishes.
- ASTM E1264 classification friction:Stringent testing protocols for federal institutional projects extend product qualification timelines, freezing out smaller manufacturers lacking certification infrastructure.
Strategic Opportunities
- Aftermarket service revenue:Ceiling system refurbishment and acoustic performance auditing create recurring revenue streams from installed bases. Manufacturers monetize lifetime value through specification retention.
- China's green building certification expansion:MEE and SAMR standards now incorporate acoustic performance metrics for office and residential towers, opening specification pathways for compliant foreign suppliers.
- Integrated lighting-acoustic convergence:Metal ceiling systems with embedded LED modules capture specification in transportation hubs and corporate lobbies where aesthetic-engineering integration commands premium positioning.
Industry Challenges
- Acoustic engineering talent scarcity:Specialized expertise in room acoustics modeling and NRC optimization concentrates in a handful of consulting firms, constraining manufacturer R&D bandwidth.
- Dual certification timeline compression:Products must simultaneously satisfy ISO 11654 absorption ratings and regional thermal codes, multiplying testing cycles before market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Ceiling Tiles Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Fiber, Metal, Wood, Gypsum Application: Commercial, Residential, Institutional, Industrial Installation Type: Suspended, Direct Mount, Grid, Specialty End User: Hospitals, Offices, Schools, Retail |
| Companies Covered | Rockfon, Hunter Douglas Architectural, Armstrong World Industries, SAS International, OWA Ceiling Systems, USG Corporation, Knauf AMF, ROCKWOOL, CertainTeed Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Ceiling Tiles Market Evolving Landscape
Digital specification tools and performance-modeling software are compressing the traditional architect-manufacturer relationship. These platforms embed acoustic performance data directly into building information modeling workflows, shifting influence toward technical specification teams.
Microperforated metal ceiling systems with integrated acoustic backing layers are rendering obsolete conventional lay-in mineral fiber tiles in premium commercial segments. Corporate headquarters and flagship retail environments specify these systems for durability and aesthetic precision. The technology compresses installation labor and long-term maintenance costs while delivering equivalent NRC performance.
California's Title 24 energy code revisions mandate thermal performance standards for ceiling assemblies in new commercial construction. The regulation forces acoustic tile manufacturers to engineer mineral fiber formulations with reduced thermal bridging. Healthcare and education contractors in the state now prioritize assemblies satisfying both acoustic and thermal criteria in single specifications.
Specification decisions increasingly migrate from general contractors to specialized acoustic consultants and facility sustainability officers. These buyers demand project-specific acoustic engineering rather than commodity volume, fragmenting procurement across multiple decision nodes. Germany and the United States exhibit the most pronounced shift toward technical buyer influence in ceiling system selection.
Acoustic Ceiling Tiles Market Segmentation
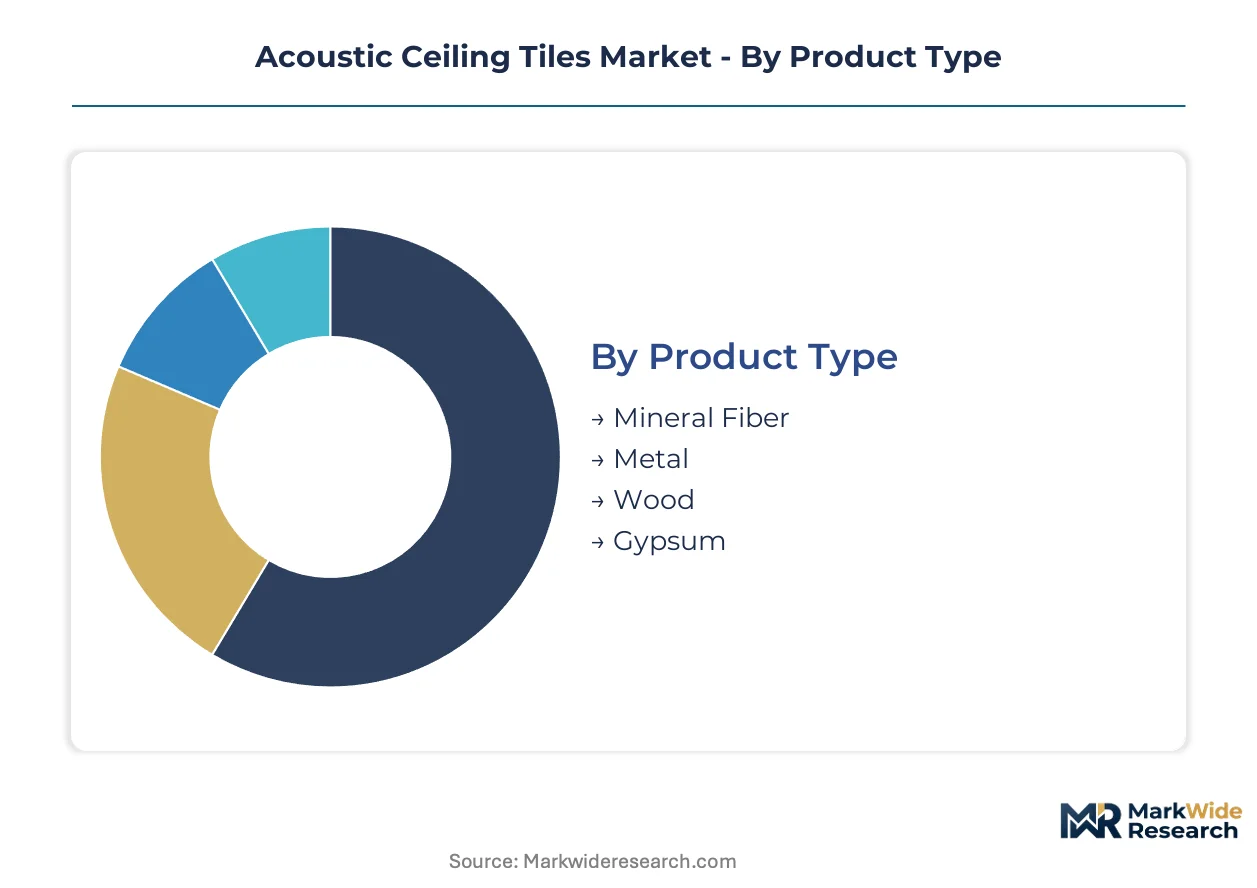
Segmentation in acoustic ceiling tiles reveals how specification power fragments across technical buyers, project types, and installation constraints. Manufacturers configure product platforms and service attach rates differently for each slice, with aftermarket intensity varying dramatically by segment.
Product Type:
Aftermarket service intensity concentrates in mineral fiber and metal systems, where refurbishment cycles and acoustic performance auditing generate recurring revenue streams from installed bases.
- Mineral Fiber:Engineered from compressed fiberglass or stone wool with bonded mineral binders, these panels achieve NRC ratings between 0.70 and 0.95 for open-plan offices and educational facilities. Specification in United States healthcare construction is accelerating as patient-centered environments demand broadband speech-frequency absorption. Mineral fiber holds the largest share; momentum sits with metal systems.
- Metal:Aluminum or steel substrates with perforated faces and acoustic backing layers deliver durability and integrated lighting compatibility. Demand concentrates in corporate lobbies and transportation hubs where aesthetic precision justifies premium installed costs and longer replacement cycles reduce lifetime service intensity.
- Wood:Solid or veneer-faced panels with concealed acoustic perforations serve heritage renovations and biophilic design specifications.
- Gypsum:Moisture-resistant formulations dominate hospital clean rooms and laboratory environments requiring washability and mold inhibition.
Mineral fiber commands specification volume; metal systems capture margin expansion through integrated engineering.
Application:
Cost tier differentiation separates specification cycles, with commercial and institutional projects demanding engineered solutions while residential and industrial segments prioritize standard-grade commodity procurement.
- Commercial:Office towers, retail flagships, and hospitality venues specify high-NRC assemblies with thermal performance integration. California Title 24 compliance is compressing specification timelines for thermally efficient ceiling assemblies in new construction.
- Institutional:Schools, government buildings, and cultural facilities require ASTM E1264 classification and federal procurement eligibility. Germany's commercial renovation sector is mandating LEED-equivalent acoustic performance for office retrofits, accelerating replacement demand.
- Residential:Multi-family housing and luxury single-family applications favor aesthetic customization over acoustic performance optimization.
- Industrial:Manufacturing plants and warehousing facilities specify impact-resistant, low-maintenance surfaces with minimal acoustic engineering.
Commercial applications dominate revenue concentration; institutional retrofit cycles are expanding most quickly.
Installation Type:
Volume concentration in suspended and grid systems creates economies of scale for component manufacturers, while specialty installations fragment procurement across project-specific engineering requirements.
- Suspended:T-bar grid systems supporting lay-in panels enable rapid installation and flexible reconfiguration. United States healthcare contractors prioritize these assemblies for phased renovation projects requiring minimal downtime.
- Grid:Exposed or concealed metal frameworks with standardized module dimensions dominate commercial specification for lighting and HVAC integration compatibility.
- Direct Mount:Adhesive or screw-fixed applications suit low-ceiling retrofits and seismic-sensitive structures with limited plenum depth.
- Specialty:Curved, acoustic baffle, and raft configurations serve atrium spaces and architectural statement ceilings with custom engineering requirements.
Suspended systems anchor volume; specialty installations are gaining share fastest through premium project capture.
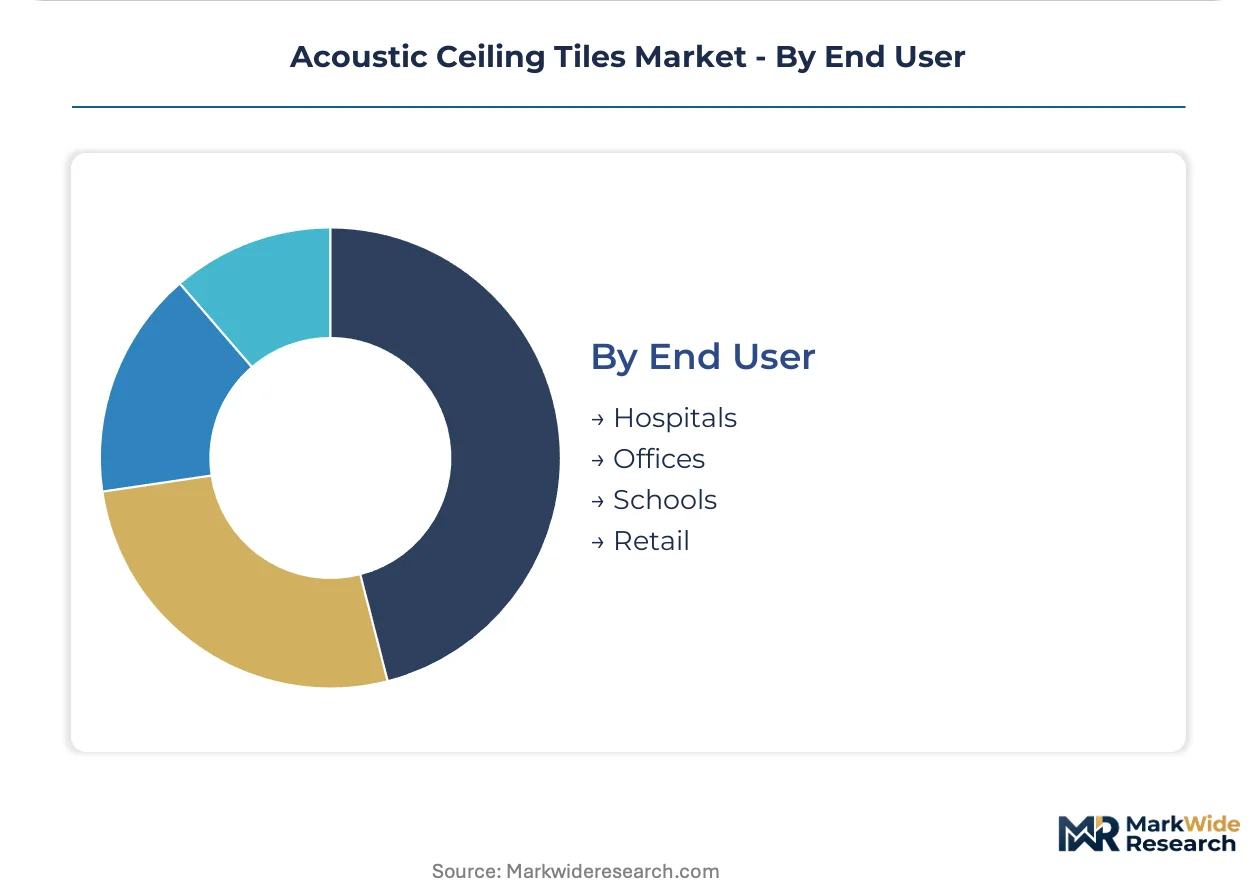
End User:
Customer type fragmentation shifts influence from general contractors to specialized acoustic consultants and facility sustainability officers, with specification authority varying sharply by end-use vertical.
- Hospitals:Infection control, moisture resistance, and patient privacy requirements drive specification of cleanable gypsum and high-NRC mineral fiber. OSHA workplace noise exposure limits are forcing retrofit of aging installations in United States medical facilities.
- Offices:Open-plan densification and video conferencing proliferation demand speech intelligibility optimization through broadband absorption. Germany's Frankfurt and Munich commercial cores are accelerating LEED-equivalent renovation specifications.
- Schools:Learning environment research links acoustic performance to student outcomes, driving specification of high-NRC ceilings in new construction and modernization programs.
- Retail:Brand environment consistency and durability for high-traffic zones prioritize metal systems with integrated lighting and graphic customization capabilities.
Hospitals command the highest service attach rates; office renovation cycles are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare construction intensity in the United States diverges from Germany's commercial renovation focus, while China integrates acoustic metrics into green building codes. Each geography applies ceiling systems to distinct regulatory and project-type priorities.
United States
Patient-centered healthcare environments and open-plan office retrofits dominate specification. OSHA workplace noise exposure limits force facility managers to replace aging mineral fiber installations. Healthcare contractors in Texas and California prioritize thermally efficient assemblies meeting Title 24 energy codes.
Germany
Frankfurt and Munich commercial cores accelerate LEED-equivalent office renovations mandating acoustic performance. ECHA REACH compliance shapes low-emitting mineral fiber formulations for indoor air quality. Stone wool substrate manufacturers in North Rhine-Westphalia control thermal-acoustic consistency through backward integration.
China
MEE and SAMR standards now embed acoustic performance metrics into green building certifications for office and residential towers. Dual carbon goals compress specification timelines for thermally efficient ceiling assemblies. Yangtze River Delta developers specify compliant foreign suppliers for premium commercial towers.
India
BIS standards and state-level urban development missions expand institutional construction in education and healthcare segments. CDSCO guidelines influence clean room specifications in pharmaceutical manufacturing clusters. Maharashtra and Karnataka contractors prioritize ASTM E1264-classified products for federally eligible projects.
United Arab Emirates
Transportation hub and corporate flagship developments specify metal ceiling systems with integrated lighting compatibility. MOHAP infection control standards shape hospital procurement for moisture-resistant gypsum formulations. Dubai-based contractors source premium finishes for aesthetic-engineering integration in hospitality venues.
Acoustic Ceiling Tiles Market Competitive Landscape
Capability concentration sits with integrated substrate producers; scale advantage sits with national distribution networks. The market structures around three tiers: backward-integrated mineral fiber specialists, metal system customizers, and regional refurbishment service providers. Dominant competitive moves include captive supply of stone wool raw materials and specification retention through acoustic performance auditing services.
Within the integrated substrate tier, ROCKWOOL exemplifies upstream control over thermal-acoustic consistency. Among metal system specialists, Hunter Douglas Architectural occupies a position emphasizing project-specific engineering over commodity volume. At the distribution-scale end, Armstrong World Industries represents specification retention through national contractor relationships in healthcare and education verticals.
| Leading Market Players |
|---|
| Rockfon |
| Hunter Douglas Architectural |
| Armstrong World Industries |
| SAS International |
| OWA Ceiling Systems |
| USG Corporation |
| Knauf AMF |
| ROCKWOOL |
| CertainTeed Corporation |
| Others |
Value Network & Pricing Analysis
Stone wool substrate production clusters in North Rhine-Westphalia and Denmark concentrate upstream thermal-acoustic consistency control, anchoring margin capture for integrated manufacturers while compressing pricing power for non-integrated assemblers dependent on spot mineral fiber procurement.
Pricing Analysis
Long-term offtake contracts dominate specification-grade mineral fiber procurement, insulating healthcare and education contractors from spot volatility in stone wool feedstock. Three-tier pricing structure across premium, standard, and economy levels separates ASTM E1264-certified institutional-grade tiles from commodity office specifications and basic industrial panels. Price differentiation hinges on NRC certification tier and thermal performance integration. Cost compression in standard-grade mineral fiber is intensifying because European natural gas exposure feeds directly into stone wool melting energy costs. Healthcare contractors exhibit lowest price sensitivity due to infection-control mandates; multi-family residential developers remain most price-elastic.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize distributor financing relationships with national contractor networks in the United States and Germany. Supply concentrates in Denmark, Germany, and the United States for stone wool substrate production; China and India for gypsum core processing; and Italy and Austria for specialty acoustic coatings. Raw material dependencies center on basalt and recycled slag for stone wool, aluminum coil for metal systems, and synthetic latex binders for surface treatments. Single-source vulnerability sits with acoustic coating formulators serving premium metal ceiling finishes. Distribution runs through national specification houses and direct contractor relationships in healthcare and education verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acoustic ceiling specification is shifting toward platform economics as building information modeling ecosystems embed performance data directly into architect workflows, creating interoperability moats around integrated product-digital service bundles.
For Market Incumbents: Harden specification retention through captive acoustic performance auditing services that lock facility managers into recurring refurbishment cycles. Deepen backward integration into stone wool substrate production to defend margin compression from European energy cost volatility. Prioritize certification investment in China's MEE and SAMR compliance pathways before green building acoustic mandates fully mature.
For New Entrants and Emerging Players: Establish a beachhead in India's institutional construction vertical where BIS standards and state urban development missions expand specification opportunity for ASTM-classified products. Target Maharashtra and Karnataka pharmaceutical manufacturing clusters where CDSCO clean room guidelines drive moisture-resistant gypsum demand. Pursue direct contractor relationships bypassing incumbent specification house networks.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mineral fiber specialists with captive stone wool supply and established healthcare specification relationships. Long-term viability over a five-to-ten year window favors manufacturers combining thermal-acoustic engineering with aftermarket service revenue streams. Monitor China's green building certification scope expansion as the inflection signal for premium foreign supplier penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stone Wool Substrate | Captive supply of performance-critical inputs insulates margins from European natural gas volatility. |
| Acoustic Performance Auditing Services | Recurring revenue from installed bases transforms transactional tile sales into lifetime value capture. |
| Digital Specification Platform Integration | BIM-embedded performance data shifts architect influence toward technically integrated manufacturers. |
| China Green Building Certification Compliance | MEE and SAMR acoustic metrics open specification pathways in Yangtze River Delta premium towers. |
| Integrated Lighting-Acoustic Convergence | Metal ceiling systems with embedded LED modules command premium positioning in transportation hubs. |
Research Methodology
The analysis maps mineral fiber, metal, wood, and gypsum ceiling systems, each validated through specification architects, healthcare facility managers, education procurement officers, and acoustic engineering consultants. Primary interviews with these stakeholders combined with secondary validation from ASTM classification databases, OSHA enforcement records, and state energy code filings. Bottom-up project pipeline analysis triangulates against top-down construction spending forecasts across commercial, institutional, and healthcare verticals.
Assumptions held fixed include continued enforcement of OSHA workplace noise exposure limits and progressive adoption of LEED-equivalent standards in European commercial renovation. The projection horizon models product type, application tier, installation method, and end-use vertical segmentation. CAGRs derive from installation volume trajectories and average selling price evolution across specification grades. Forecast inputs include healthcare construction permit data and commercial office retrofit cycle timing.
Stress conditions across European natural gas pricing, Chinese green building certification pace, and mineral wool fiber cost volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement continuity and specification buyer migration patterns. Macroeconomic construction cycle deviation, abrupt regulatory rollback, or breakthrough alternative acoustic treatments would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Precast Concrete Pile Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Door System Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Hygienic Cladding Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
Modular Commercial Building System Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
South Africa Wall Putty Market