
 Asia Pacific Construction Equipment Rental Market | 2026-2036
Asia Pacific Construction Equipment Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Construction Equipment Rental Market Analysis
Buyer concentration across Asia Pacific infrastructure developers is decoupling from traditional general contractor relationships as state-backed project companies direct larger rental volumes directly. Caterpillar Inc. leverages its dealer-service density across Japan and Australia to capture these consolidated procurement flows. Nishio Rent All Co. anchors its position through hyper-local fleet positioning in prefecture-level construction clusters. Kanamoto Co., Ltd. differentiates via telematics-integrated maintenance contracts that reduce idle-time penalties for project owners.
Asia Pacific construction equipment rental denotes the commercial provision of heavy machinery—including hydraulic excavators rated above 20 tons, all-terrain cranes with 50-500 ton lifting capacity, and crawler dozers with Tier 4/Stage V emissions compliance—on temporary contractual terms rather than outright purchase, serving civil engineering and resource extraction operations where capital flexibility outweighs ownership economics. Earthmoving equipment dominates rental revenue pools given universal site-preparation requirements across residential and commercial verticals, while crane rental commands premium daily rates reflecting certified operator bundling and transport complexity. Flexible deployment models are expanding fastest as contractors sequence multi-phase projects with uneven equipment intensity.
Japan's Ministry of Land, Infrastructure, Transport and Tourism enforces construction machinery emissions standards that accelerate fleet turnover toward rental pools with newer compliant assets. Australia's Work Health and Safety regulations mandate operator certification and equipment inspection protocols that rental providers integrate as bundled compliance services. India's Central Pollution Control Board implements diesel retrofit and idle-reduction directives affecting on-site equipment deployment. Stakeholders must monitor how carbon-border adjustments and local-content requirements reshape cross-border fleet mobility and sourcing economics across the region.
Market Dynamics
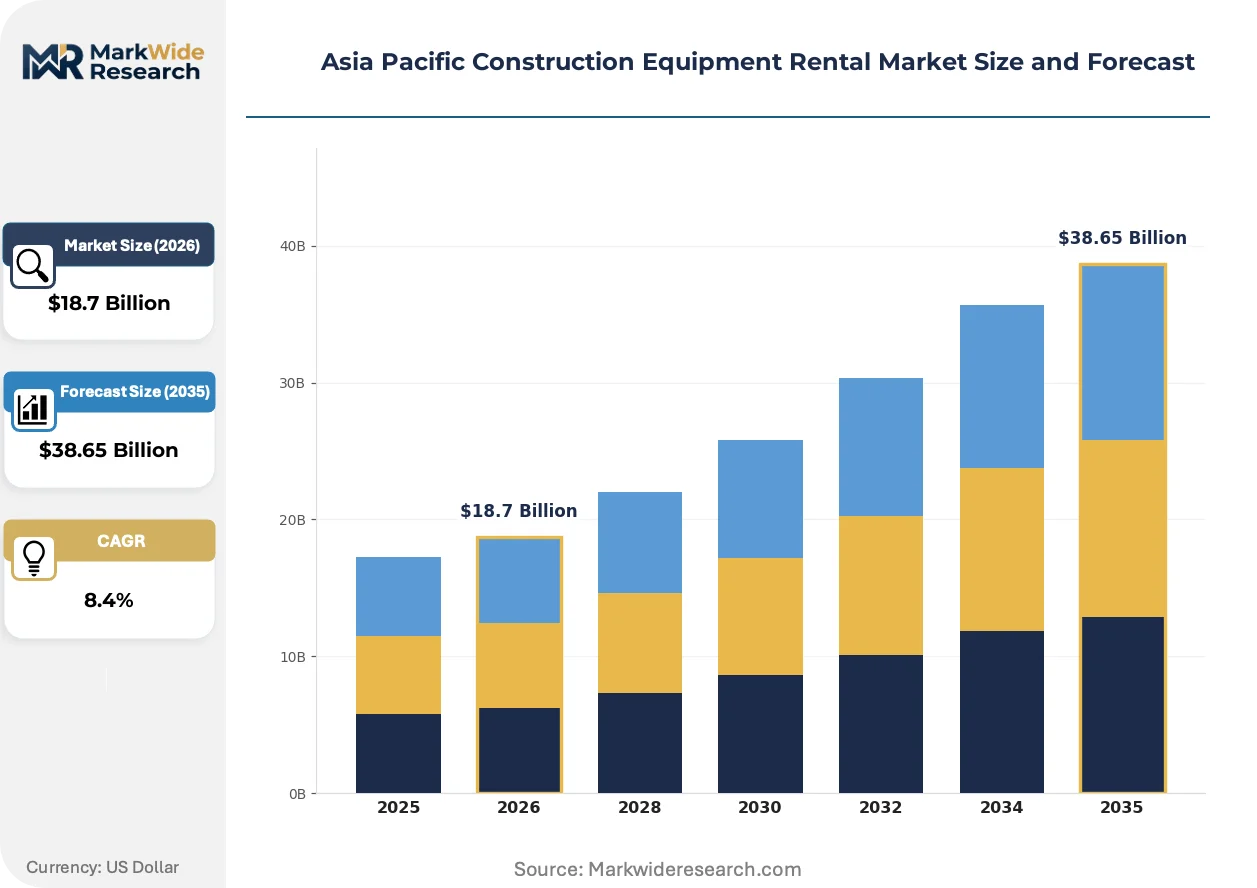
Fleet outsourcing across Asia Pacific infrastructure projects is accelerating as state-backed developers consolidate procurement authority and impose emissions compliance burdens on contractors. Rental providers capture this structural shift by embedding certified maintenance and telematics services into contract terms.
Growth Catalysts
- Japan's MLIT Emissions Standards:Construction machinery regulations mandate Tier 4/Stage V compliance, forcing contractors toward rental pools with newer certified assets rather than owned legacy fleets.
- Mining Rehabilitation in Australia:Environmental remediation obligations at decommissioned resource sites generate sustained demand for specialized earthmoving equipment on flexible terms.
- Telematics Integration:IoT-enabled idle-time monitoring allows project owners to reduce fuel penalties and optimize equipment utilization across multi-phase developments.
Market Restraints
- Diesel Price Volatility:Fuel constitutes 25-35% of operating costs for heavy equipment, exposing rental margins to energy market fluctuations without pass-through mechanisms.
- Concentrated OEM Supply:Critical components for hydraulic systems and powertrains originate from concentrated manufacturing bases in Japan and South Korea, creating vulnerability to supply interruptions.
- Cross-Border Fleet Mobility Friction:India's Central Pollution Control Board diesel retrofit directives and local-content requirements fragment regional asset deployment economics.
Strategic Opportunities
- Indonesia's Trans-Sumatra Highway:Underpenetrated rental penetration in Southeast Asia's largest infrastructure pipeline offers first-mover positioning for compliant fleet operators.
- Carbon Border Adjustments:Emerging trade mechanisms will favor rental providers with documented emissions profiles, creating competitive differentiation against owned-equipment competitors.
- Telematics-AI Convergence:Predictive maintenance algorithms layered on equipment sensor networks enable outcome-based pricing models that transfer downtime risk from contractors to rental firms.
Industry Challenges
- Certified Operator Scarcity:Australia's Work Health and Safety regulations mandate licensed crane operators, creating recruitment bottlenecks that constrain fleet utilization rates.
- Telematics-Legacy System Integration:Contractors operating mixed fleets face data fragmentation when integrating rental equipment telematics with proprietary project management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Construction Equipment Rental Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Loaders, Cranes, Bulldozers End User: Construction Companies, Contractors, Infrastructure Developers, Mining Firms Deployment Model: Onsite Rental, Offsite Rental, Flexible Rental, Long-Term Rental Rental Duration: Short-Term, Medium-Term, Long-Term, Project-Based |
| Companies Covered | Sumitomo Corporation, Nishio Rent All Co., Caterpillar Inc., Liebherr Group, Aktio Corporation, United Rentals Inc., Coates Hire, Finning International Inc., Kanamoto Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Construction Equipment Rental Market Emerging Trajectories
Digitalization of equipment performance data is compressing rental contract structures from fixed-term to utilization-based models. Providers invest in sensor infrastructure and analytics platforms to capture this operational intelligence advantage.
Telematics platforms are unifying equipment location tracking, fuel consumption monitoring, and predictive maintenance alerts into single-dashboard interfaces. Major contractors in Australia's mining sector are adopting these systems fastest, demanding API integration with their enterprise resource planning software. This unification is compressing rental pricing toward outcome-based metrics rather than daily rates.
India's Central Pollution Control Board diesel retrofit and idle-reduction directives are mandating emissions monitoring equipment on construction sites. Rental providers must retrofit legacy assets or acquire compliant new units to maintain contract eligibility. Earthmoving equipment segments face the steepest compliance cost absorption, with project owners increasingly specifying certified-only fleets in tender documents.
State-backed infrastructure developers in Southeast Asia are consolidating procurement authority away from general contractors toward direct rental relationships. Malaysia's Mass Rapid Transit Corporation and Indonesia's Waskita Karya now specify equipment providers in master contracts rather than delegating to subcontractors. This concentration is visible most acutely in urban rail and highway projects where equipment sequencing spans multiple construction phases.
Asia Pacific Construction Equipment Rental Market Segmentation
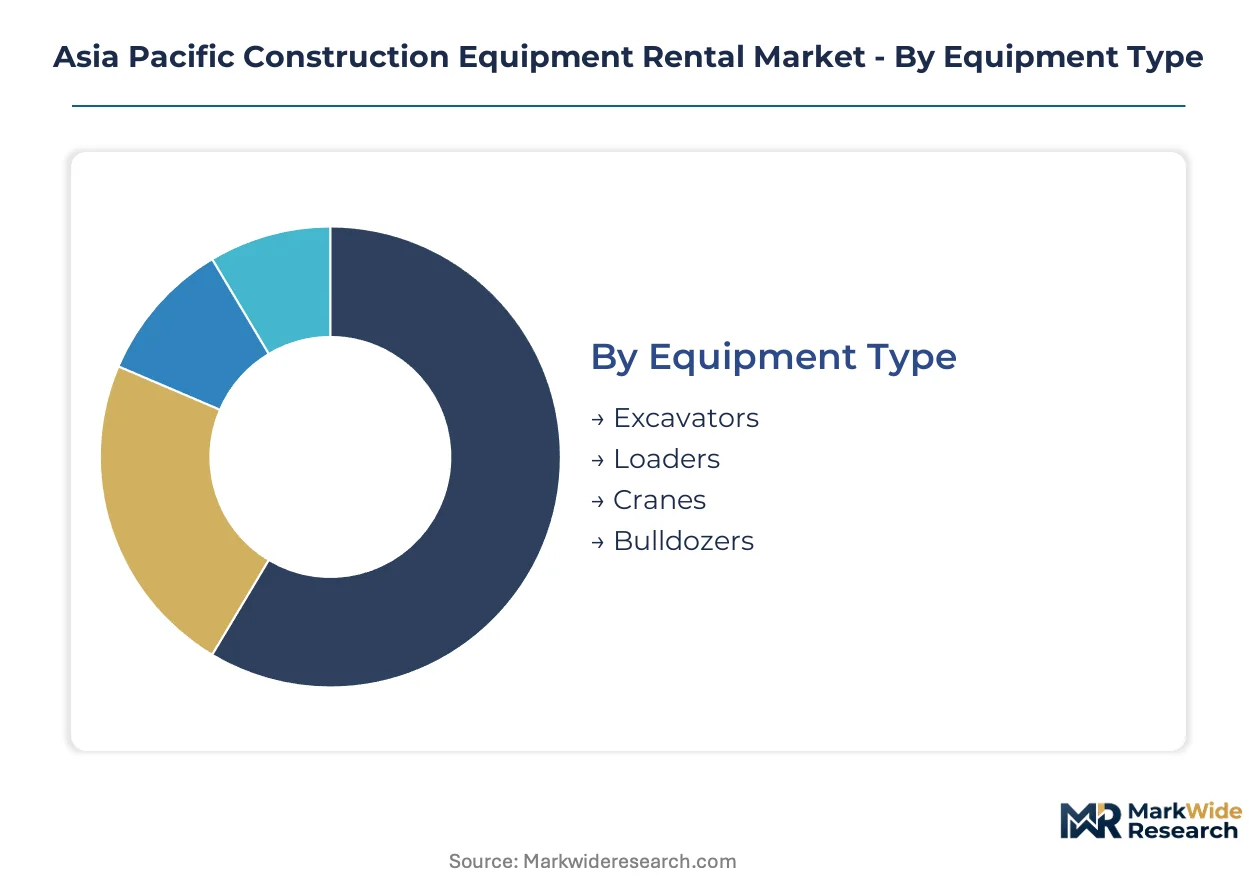
Equipment segmentation in Asia Pacific construction rental reveals how fleet composition aligns with emissions compliance cycles and project financing structures. Rental providers calibrate category mix against regulatory deadlines and infrastructure pipeline phasing.
Equipment Type:
Fleet replacement cycles dominate procurement decisions as Japan's MLIT Tier 4/Stage V deadlines force contractors toward newer rental assets rather than owned legacy equipment.
- Excavators:Hydraulic units rated above 20 tons constitute the revenue backbone, with demand concentrating in India's urban corridor projects where site preparation intensity drives continuous deployment. Japan's emissions standards accelerate turnover toward compliant rental pools.
- Cranes:All-terrain models with 50-500 ton lifting capacity command premium daily rates reflecting certified operator bundling and transport complexity. Australia's mining rehabilitation sites generate sustained demand for specialized lifting on flexible terms.
- Loaders:Wheel and track configurations serve material handling across residential and commercial verticals with universal site requirements.
- Bulldozers:Crawler dozers with Tier 4/Stage V compliance face steepest retrofit costs, pushing ownership economics toward rental structures.
Excavators sit at the top of the volume ranking, with cranes climbing the fastest.
End User:
Customer concentration patterns reflect procurement authority consolidation across state-backed infrastructure developers.
- Infrastructure Developers:State-backed project companies in Malaysia and Indonesia now direct larger rental volumes through master contracts rather than delegating to subcontractors, capturing emissions compliance burdens directly.
- Construction Companies:General contractors face margin compression as procurement authority shifts upward, forcing reliance on rental flexibility for multi-phase equipment sequencing.
- Contractors:Subcontractor tiers absorb idle-time risk through telematics-integrated rental contracts that transfer utilization optimization to providers.
- Mining Firms:Australia's environmental remediation obligations at decommissioned resource sites generate specialized earthmoving demand on project-based terms.
Infrastructure developers command the largest contract values, with mining firms expanding most quickly.
Deployment Model:
Contract structuring responds to uneven equipment intensity across multi-phase developments and carbon-border documentation requirements.
- Flexible Rental:Variable-duration contracts with telematics-enabled utilization tracking allow project owners to reduce fuel penalties and optimize deployment across construction phases. This model gains traction fastest in Australia's mining sector.
- Onsite Rental:Dedicated fleet positioning at single-location projects serves India's urban corridor developments with continuous equipment needs.
- Long-Term Rental:Extended contractual terms embed certified maintenance services for Tier 4/Stage V compliance across Japan's prefecture-level construction clusters.
- Offsite Rental:Centralized depot models with transport logistics suit sporadic equipment needs in underpenetrated Southeast Asian markets.
Onsite rental holds the volume lead, with flexible rental gaining share fastest.
Rental Duration:
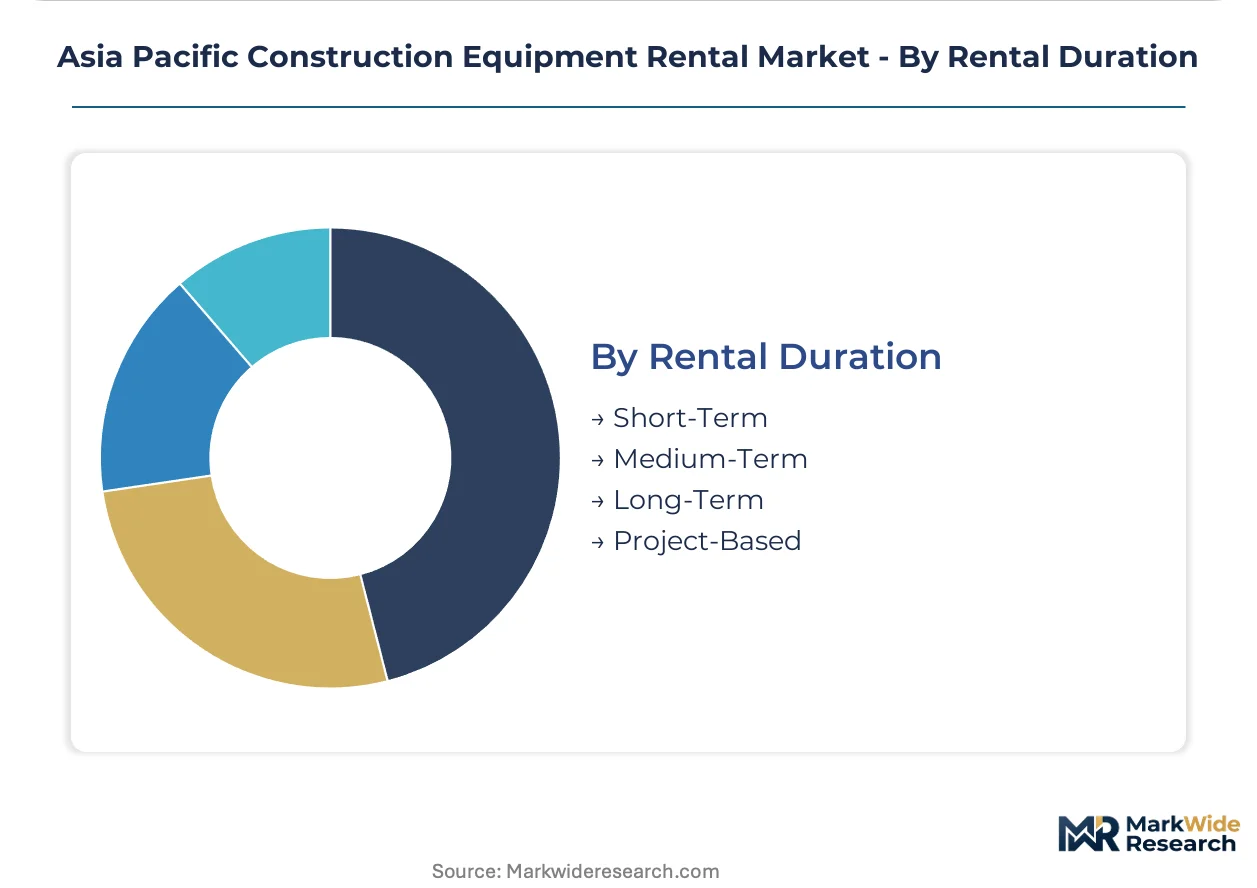
Duration segmentation tracks project financing structures and regulatory inspection intervals.
- Project-Based:Equipment provision tied to specific contract completion aligns with Indonesia's Trans-Sumatra Highway phasing and Australia's mining rehabilitation timelines.
- Short-Term:Daily and weekly rates serve peak construction intensity periods with maximum capital flexibility.
- Medium-Term:Monthly to quarterly structures balance utilization certainty against ownership economics for general contractors.
- Long-Term:Annual contracts dominate Japan's urban rail and highway developments where equipment sequencing spans multiple phases.
Long-term contracts anchor the revenue base, with project-based structures expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban corridor projects generate equipment rental volumes that exceed Australia's mining rehabilitation demand, yet both markets operate under divergent regulatory frameworks that reshape fleet deployment economics across the region.
Japan
Prefecture-level construction clusters in Kanto and Kansai drive excavator rental intensity for urban rail expansions. The Ministry of Land, Infrastructure, Transport and Tourism enforces Tier 4/Stage V emissions deadlines that accelerate contractor migration from owned legacy fleets to compliant rental pools. Tokyo-Osaka corridor developments concentrate demand for telematics-integrated maintenance contracts.
Australia
Mining rehabilitation obligations at decommissioned Queensland and Western Australia resource sites generate specialized earthmoving demand on flexible project terms. Work Health and Safety regulations mandate certified crane operators, creating recruitment constraints that rental providers address through bundled compliance services. Perth and Brisbane serve as fleet positioning hubs for remote site deployment.
India
Delhi-Mumbai industrial corridor and smart city initiatives sustain continuous excavator deployment across site preparation phases. The Central Pollution Control Board implements diesel retrofit and idle-reduction directives that disqualify non-compliant equipment from government tenders. Maharashtra and Gujarat construction clusters exhibit fastest adoption of emissions-certified rental fleets.
Indonesia
Trans-Sumatra Highway phasing creates underpenetrated demand for variable-duration rental structures across multi-phase developments. National infrastructure masterplans prioritize state-backed procurement consolidation that bypasses traditional general contractor intermediaries. Java-based project companies now specify equipment providers directly in master contracts for urban rail and toll road developments.
South Korea
Incheon Free Economic Zone and Busan port expansions drive crane rental demand with certified operator bundling requirements. Environmental ministry directives on construction machinery emissions align with broader East Asian compliance convergence. Seoul metropolitan area infrastructure densification concentrates medium-term rental contract structures for equipment sequencing across phased developments.
Asia Pacific Construction Equipment Rental Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across Asia Pacific equipment rental, creating a tiered structure where scale advantages clash with localization density. Japanese trading houses and global OEM-affiliated dealers anchor premium service tiers through maintenance integration and telematics platforms. Three archetypes dominate: dealer-networked multinationals leveraging manufacturer relationships, domestic pure-plays with prefecture-level fleet positioning, and mining-sector specialists with project-based flexibility. Consolidation pressure manifests through strategic partnerships for telematics deployment and selective fleet acquisitions in underpenetrated Southeast Asian corridors.
Among Japan-based rental specialists, Nishio Rent All Co. and Kanamoto Co., Ltd. exemplify the hyper-local density archetype through prefecture-cluster fleet positioning and telematics-integrated contract structures. Caterpillar Inc. represents the multinational dealer-network model, capturing consolidated procurement flows from state-backed developers across Australia and Japan through service density advantages. These three anchors illustrate how competitive positioning splits between geographic intimacy and scale-enabled service breadth.
| Leading Market Players |
|---|
| Sumitomo Corporation |
| Nishio Rent All Co. |
| Caterpillar Inc. |
| Liebherr Group |
| Aktio Corporation |
| United Rentals Inc. |
| Coates Hire |
| Finning International Inc. |
| Kanamoto Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Certified crane operator scarcity in Australia's mining corridors and Western Australia's remote site logistics compress labor-cost differentials into three-tier pricing spreads across premium bundled-service, standard telematics-enabled, and economy bare-rental tiers. Diesel price volatility and emissions compliance retrofit costs further stratify rate structures as rental providers absorb Tier 4/Stage V certification premiums.
Pricing Analysis
Capacity additions in Indonesia's Java-based fleet hubs are reshaping price floors for excavator rentals across Southeast Asia's underpenetrated highway corridors. Three-tier pricing structure across premium certified-operator bundles, standard telematics-maintenance packages, and economy bare-equipment tiers separates Australia's mining rehabilitation specialists from India's urban corridor contractors. Cost compression in the economy tier is intensifying because state-backed developers in Malaysia and Indonesia consolidate procurement authority into master contracts with volume-discount leverage. India's municipal contractors exhibit highest price sensitivity due to thin margins on government tenders, while Australia's mining firms show lowest sensitivity given bundled compliance service requirements.
Supply Chain Analysis
Welder and hydraulic technician availability constraints in Japan's prefecture-level manufacturing clusters and South Korea's industrial zones anchor component production schedules for powertrain and hydraulic system assemblies. Critical hydraulic pumps, electronic control modules, and high-strength steel castings draw from concentrated manufacturing bases in Japan, South Korea, and China, creating single-source vulnerability when geopolitical friction disrupts cross-border component flows. Distribution runs through OEM-affiliated dealer networks in developed markets and independent depot operators in Southeast Asia's emerging corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through telematics-enabled outcome-based pricing that transfers downtime risk to rental providers while capturing premium rates for certified emissions compliance.
For Market Incumbents: To counter procurement consolidation by state-backed infrastructure developers, embed predictive maintenance algorithms and API-integrated telematics platforms into long-term contracts. Deepen backward integration into Tier 4/Stage V powertrain refurbishment capabilities to capture circular-economy value from Japan's accelerated fleet turnover mandates. For New Entrants and Emerging Players: Digital marketplace platforms for spot crane rentals offer the lowest barrier-to-entry channel for penetrating Indonesia's Trans-Sumatra Highway contractor tiers. Target project-based flexible rental structures in Australia's mining rehabilitation corridors where incumbent coverage remains thin, leveraging telematics partnerships with established sensor-network providers rather than building proprietary infrastructure. For Investors and Strategic Acquirers: Japanese trading houses and construction conglomerates are the most active acquirers in this space, seeking telematics capabilities and prefecture-level fleet density. The long-term viability window favors targets with documented emissions compliance portfolios and established maintenance-contract recurring revenue. Monitor Indonesia's Waskita Karya and Malaysia's MRT Corporation tender specifications for early signals of telematics-mandatory procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Unifies idle-time monitoring and predictive maintenance for Australia's Work Health and Safety compliance bundling. |
| Backward Integration into Powertrain Refurbishment | Captures circular-economy value from Japan's MLIT-mandated Tier 4/Stage V fleet turnover deadlines. |
| Flexible Rental Model Expansion | Aligns contract structures with Indonesia's multi-phase Trans-Sumatra Highway equipment sequencing requirements. |
| Certified Operator Training Programs | Addresses Australia's licensed crane operator scarcity that constrains fleet utilization rates. |
| Carbon Border Adjustment Documentation | Creates competitive differentiation through emissions-profile transparency for cross-border fleet mobility. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet operations directors, maintenance contract managers, state-backed infrastructure procurement leads, and OEM aftermarket service heads with secondary validation against customs trade records, Ministry of Land Infrastructure Transport and Tourism emissions compliance filings, and Central Pollution Control Board diesel retrofit directives. Bottom-up equipment deployment tallies triangulated against top-down infrastructure pipeline value assessments.
Historical reference periods anchored the projection horizon to observed fleet turnover cycles, regulatory compliance deadlines, and multi-phase construction sequencing patterns across the analysis window. Modeled segmentation dimensions encompassed equipment type, deployment model flexibility, rental duration structure, and end-user procurement authority concentration. CAGRs derived from regression analysis against infrastructure investment flows and emissions standard implementation timelines, with diesel price volatility and certified operator supply constraints as key forecast sensitivity inputs.
Geopolitical supply disruption, regulatory enforcement variance across India's state-level pollution control boards, and telematics platform interoperability failures are the dominant revision risks to deployment assumptions. Practitioners should monitor Indonesia's Waskita Karya tender specifications, Australia's Work Health and Safety operator certification backlogs, and Japan's prefecture-level construction permit issuance for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Hydroforming Press Market
Construction Equipment
LAMEA Mini Excavators Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
North America Welding Equipment Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
China Metal Fabrication Equipment Market
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Europe Construction Equipment Rental Market
Construction Equipment
Rockbreakers Market