
 Laminated Veneer Lumber (LVL) Market | 2026-2036
Laminated Veneer Lumber (LVL) Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Veneer Lumber (LVL) Market Analytics
Modular prefabrication of wall and floor cassettes is consolidating buyer preference toward bundled LVL systems rather than commodity beam sales. Metsä Wood leverages its Nordic softwood supply base to anchor large-format LVL production for European modular builders. Weyerhaeuser competes through vertical control of Pacific Northwest timberlands and conversion capacity. Stora Enso differentiates via bioproduct integration, using residual streams from LVL peeling operations.
Laminated Veneer Lumber consists of peeled softwood veneers bonded under heat and pressure with exterior-grade adhesives, typically achieving 2.0 to 2.5 times the bending strength of equivalent solid sawn timber. Structural LVL dominates volume as builders substitute it for steel and concrete in residential floor systems and commercial headers. Premium LVL commands margin pools where architects specify exposed beam aesthetics in mass timber commercial projects. Specialty LVL segments serve niche infrastructure applications requiring preservative treatment or fire-rated lamination.
FDA and USDA biobased procurement guidelines, EPA formaldehyde emission standards under TSCA Title VI, and ISO 18765 structural performance benchmarks shape product certification and market access requirements. The EU Green Deal timber sourcing rules and CE marking under the Construction Products Regulation filter non-compliant imports from entering European projects. Stakeholders must monitor evolving building code amendments that expand LVL height limits and adhesive emission thresholds.
Market Dynamics
Modular prefabrication of wall and floor cassettes is consolidating buyer preference toward bundled LVL systems rather than commodity beam sales. Builders now specify integrated engineered wood packages where LVL beams arrive pre-cut for specific structural nodes.
Growth Catalysts
- EU Green Deal timber sourcing rules:CE marking under the Construction Products Regulation filters non-compliant imports and elevates certified LVL in European mid-rise projects.
- Mass timber commercial construction:Architects specify exposed LVL beams for aesthetic and carbon-sequestration credentials in Nordic and North American office buildings.
- Pacific Northwest veneer clusters:Softwood feedstock concentration and mill infrastructure in British Columbia and Oregon sustain cost-competitive structural LVL supply.
Market Restraints
- Phenol-formaldehyde resin cost volatility:Petrochemical input fluctuations compress margins on exterior-grade adhesive formulations essential for structural LVL.
- Nordic softwood supply concentration:Metsä Wood and Stora Enso control large-format veneer peeling capacity, creating bottleneck risk for European modular builders.
- Steel substitution in high-load headers:Engineered wood faces technical limits where commercial spans exceed LVL bending strength thresholds without steel reinforcement.
Strategic Opportunities
- Fire-rated lamination for infrastructure:Tunnel linings and transit platforms in Germany and Austria create specialty LVL demand beyond residential construction.
- Biobased procurement guidelines:USDA and EPA biobased purchasing mandates open institutional and federal project channels for certified engineered wood products.
- Digital fabrication integration:CNC-enabled mass customization allows LVL producers to supply precision-cut nodes directly to automated modular assembly lines.
Industry Challenges
- Adhesive emission compliance timeline:TSCA Title VI formaldehyde testing and ISO 18765 structural certification create multi-month product approval delays for new formulations.
- Peeling operator skill scarcity:Veneer lathe technicians with precision thickness control expertise are retiring faster than training programs replace them in Pacific Northwest mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Veneer Lumber (LVL) Market |
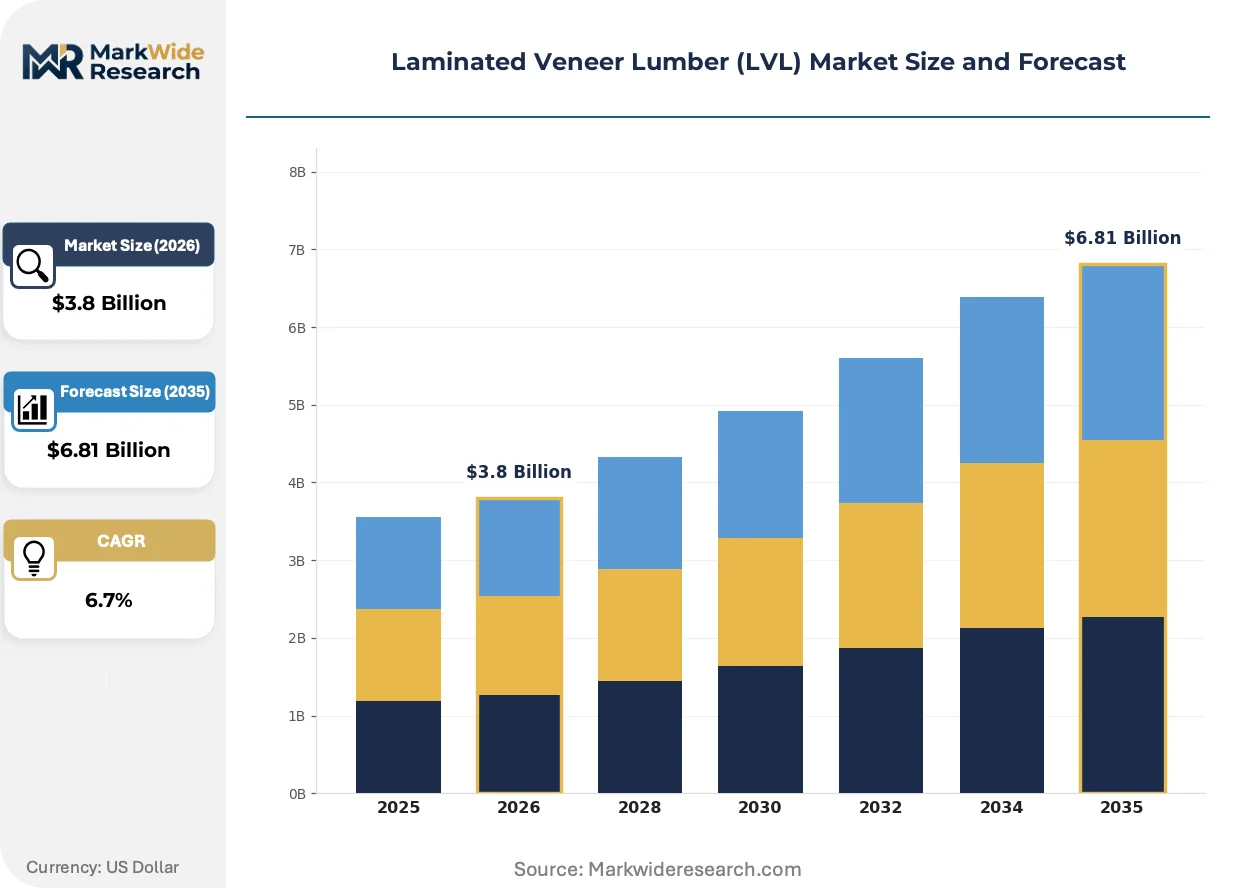
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural LVL, Premium LVL, Standard LVL, Specialty LVL Application: Residential Construction, Commercial Construction, Furniture Manufacturing, Flooring End User: Contractors, Architects, Builders, OEMs Distribution Channel: Direct Sales, Distributors, Retailers, Online Platforms |
| Companies Covered | Metsä Wood, Universal Forest Products, Boise Cascade, TimberHof, Louisiana-Pacific, Weyerhaeuser, MJB Wood Group, Stora Enso, Roseburg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Veneer Lumber (LVL) Market Evolving Landscape
Digital veneer grading and automated layup systems are compressing production variability and enabling just-in-time specification of custom LVL dimensions. Quality consistency improvements allow architects to specify exposed structural elements with confidence.
Machine vision veneer defect detection is automating real-time strength grading at peeling lines. Nordic producers deploy these systems to sort veneer by modulus of elasticity before layup. The technology is automating elimination of manual grading labor while improving batch-to-batch structural predictability for modular builders.
Updated International Building Code provisions are expanding permissible LVL height limits in mid-rise construction. US jurisdictions adopting the 2021 and 2024 code cycles now permit mass timber structures up to eighteen stories. Commercial developers in Oregon, Washington, and British Columbia are redesigning projects to capture these allowances.
Specification contracting is consolidating buyer power among modular prefabricators. Large-format wall and floor cassette producers now negotiate multi-year LVL supply agreements with volume-tier pricing. This pattern is most visible in Sweden, Finland, and the US Pacific Northwest where factory-built housing penetrates new residential construction.
Laminated Veneer Lumber (LVL) Market Segmentation
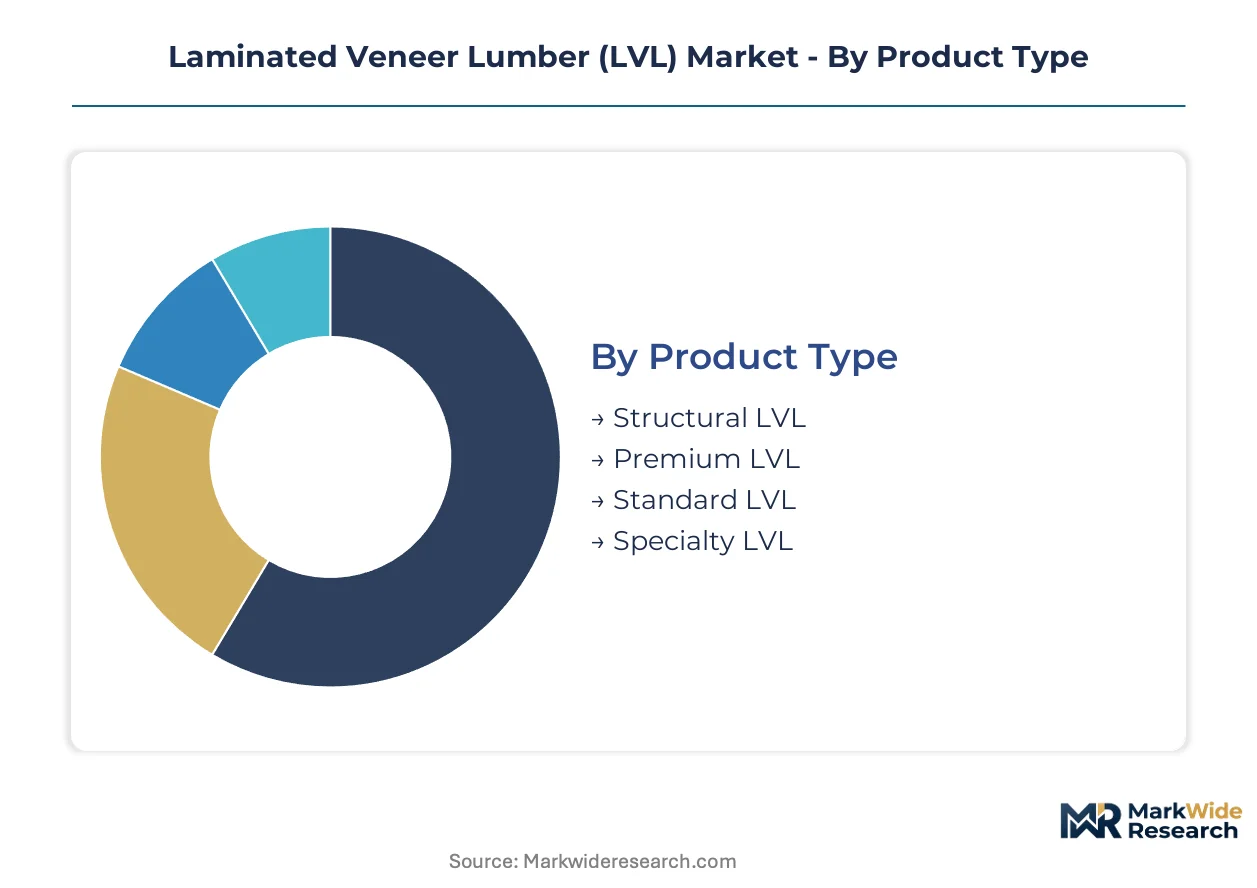
LVL buyers segment procurement by structural certification requirements and end-use performance thresholds. Product certification tiers determine which segments qualify for mass timber commercial projects versus residential floor systems. Specification contracting by modular prefabricators now bundles multiple segments into integrated engineered wood packages.
Product Type:
Structural LVL and Premium LVL carry the heaviest certification burden under ISO 18765 and TSCA Title VI, while Specialty LVL faces additional fire-rating and preservative treatment approvals for infrastructure applications.
- Structural LVL:Peeled softwood veneers bonded with exterior-grade phenol-formaldehyde adhesives achieve 2.0 to 2.5 times the bending strength of solid sawn timber. Demand concentrates in United States Pacific Northwest residential floor systems and commercial headers as builders substitute engineered wood for steel and concrete.
- Premium LVL:Architect-specified exposed beams for mass timber commercial projects require aesthetic-grade veneer selection and tight dimensional tolerances. Nordic office buildings in Sweden and Finland specify this grade for carbon-sequestration credentials and visual finish.
- Standard LVL:Commodity-grade product serving cost-sensitive residential rim board and short-span beam applications without exposure requirements.
- Specialty LVL:Preservative-treated or fire-rated lamination for tunnel linings, transit platforms, and infrastructure applications in Germany and Austria.
Leading the category by volume: Structural LVL. Growing fastest: Premium LVL.
Application:
Application segments diverge by load-bearing requirements and code compliance complexity, with commercial construction demanding higher-grade certification chains than residential.
- Residential Construction:Floor beams and rim boards in single-family and multi-family housing. British Columbia and Oregon builders specify LVL for its dimensional stability and reduced jobsite waste versus solid sawn lumber.
- Commercial Construction:Headers, beams, and columns in mass timber structures up to eighteen stories under updated International Building Code provisions. Exposed structural elements require Premium LVL grades with aesthetic certification.
- Furniture Manufacturing:Niche applications in high-load shelving and fixture components where strength-to-weight ratios outperform particleboard alternatives.
- Flooring:Subfloor and finished floor systems in modular prefabricated wall and floor cassettes, particularly in Swedish and Finnish factory-built housing.
Residential Construction commands the largest volume share. Commercial Construction is expanding most quickly as code amendments permit taller mass timber structures.
End User:
End user segments separate by specification authority and procurement scale, with architects controlling aesthetic-grade decisions and contractors driving structural volume.
- Contractors:Volume procurement of Structural LVL for residential floor systems and commercial headers. Pacific Northwest contractors negotiate multi-year supply agreements with volume-tier pricing.
- Architects:Specification authority over Premium LVL for exposed mass timber elements in Nordic and North American commercial projects.
- Builders:Integrated engineered wood package procurement for modular prefabrication, pre-cutting LVL beams for specific structural nodes.
- OEMs:Furniture and fixture manufacturers sourcing specialty grades for high-load components.
Contractors dominate procurement volume. Architects are gaining specification influence fastest as mass timber commercial construction expands.
Distribution Channel:
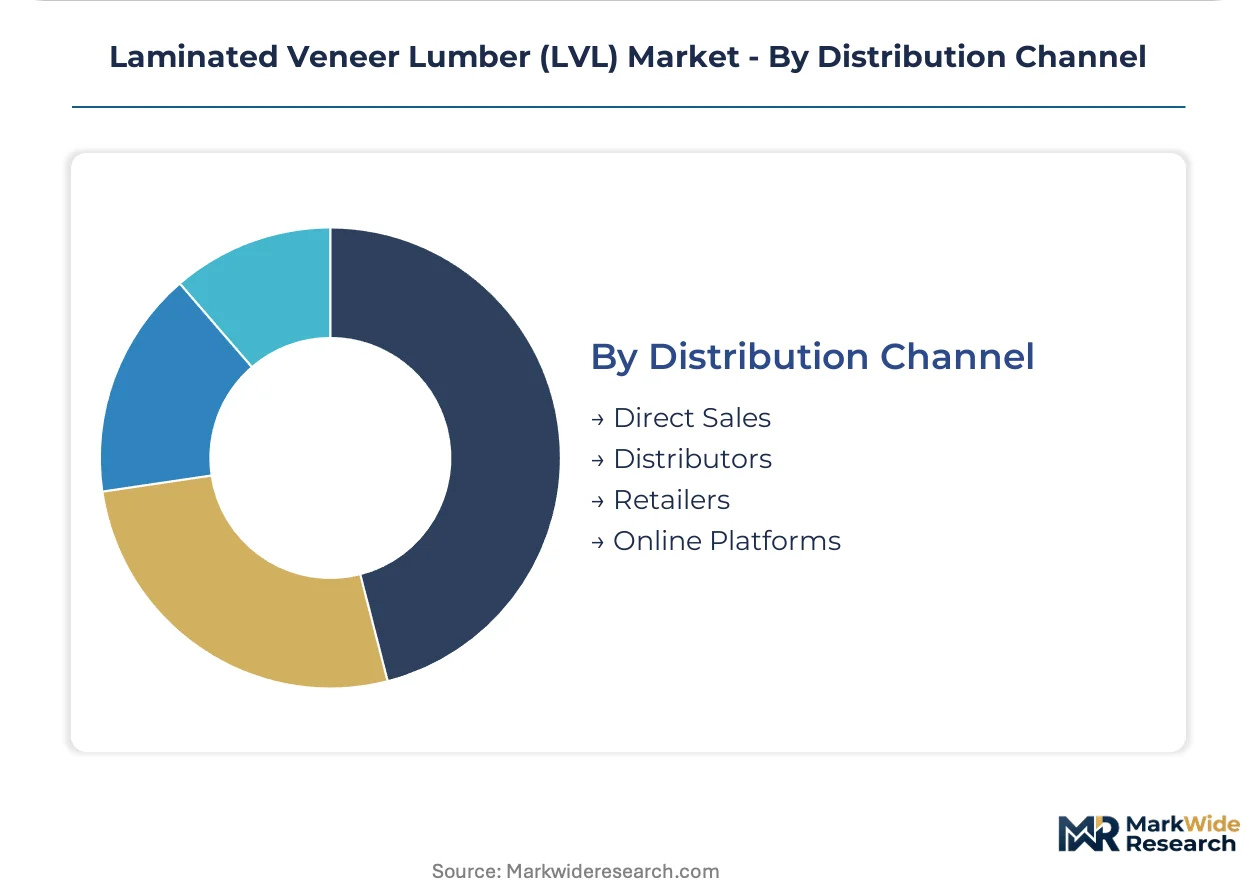
Channel selection tracks order size and customization requirements, with direct sales capturing bundled system contracts and distributors serving spot structural replacement demand.
- Direct Sales:Multi-year supply agreements between LVL producers and large-format modular prefabricators in Sweden, Finland, and the US Pacific Northwest. Pre-cut precision nodes ship directly to automated assembly lines.
- Distributors:Regional inventory holding for contractors requiring rapid structural replacement and residential builders with variable project timing.
- Retailers:Small-volume sales to renovation contractors and DIY segments for repair and extension projects.
- Online Platforms:Emerging channel for specification-grade product discovery and project bidding, particularly among architects researching certified options.
Direct Sales leads by revenue concentration. Online Platforms are climbing the fastest as digital specification tools penetrate commercial project planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in the Pacific Northwest and Nordic countries supply LVL to construction markets where demand outpaces domestic veneer peeling capacity. Consumption concentrates in mid-rise residential zones of North America and Europe where building codes now permit taller mass timber structures.
United States
Commercial developers in Oregon and Washington redesign projects to capture eighteen-story mass timber allowances under updated International Building Code cycles. EPA TSCA Title VI formaldehyde emission standards filter imported adhesive formulations from entering federal procurement channels. Pacific Northwest veneer mills around Portland and Eugene sustain cost-competitive structural beam supply for modular prefabricators.
Canada
British Columbia builders specify LVL floor systems for dimensional stability and reduced jobsite waste versus solid sawn lumber. Health Canada and PMRA coordinate biobased procurement guidelines that elevate certified engineered wood in institutional construction. Softwood veneer clusters in the BC Interior feed large-format production lines serving factory-built housing across Alberta and Ontario.
Sweden
Modular wall and floor cassette producers negotiate multi-year LVL supply agreements with volume-tier pricing for residential construction. EU Green Deal timber sourcing rules and CE marking under the Construction Products Regulation filter non-compliant imports. Veneer peeling operations in Värmland and Gävleborg anchor supply chains for Nordic and German prefabrication markets.
Finland
Architects specify exposed Premium LVL beams for carbon-sequestration credentials in Helsinki and Tampere office buildings. ECHA REACH compliance requirements shape adhesive formulation approvals for structural lamination. Metsä Wood leverages its softwood supply base in Central Finland to anchor European large-format production capacity.
Germany
Fire-rated Specialty LVL demand for tunnel linings and transit platforms in Bavaria and Baden-Württemberg extends applications beyond residential construction. KBA and federal building codes enforce strict structural performance benchmarks for infrastructure-grade engineered wood. Industrial clusters in the Black Forest region process preservative-treated lamination for rail and highway projects.
Laminated Veneer Lumber (LVL) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the LVL value chain. The market structure shows moderate consolidation where Nordic and North American producers control veneer peeling capacity and large-format press infrastructure. Three archetypes dominate: integrated forest products groups with captive timberland supply, standalone engineered wood specialists serving modular prefabricators, and diversified building materials conglomerates bundling LVL into structural systems. Capacity expansion and backward integration into veneer lathe operations represent the dominant competitive moves as producers defend margin position against resin cost volatility.
Among Nordic integrated producers, Metsä Wood and Stora Enso exemplify the timberland-to-engineered-wood archetype with control over softwood feedstock and peeling infrastructure. Weyerhaeuser occupies a position among North American forest products groups leveraging Pacific Northwest timberland bases. These three anchors demonstrate how geographic concentration of veneer resources shapes competitive positioning across regional supply zones.
| Leading Market Players |
|---|
| Metsä Wood |
| Universal Forest Products |
| Boise Cascade |
| TimberHof |
| Louisiana-Pacific |
| Weyerhaeuser |
| MJB Wood Group |
| Stora Enso |
| Roseburg |
| Others |
Value Network & Pricing Analysis
Captive control of Pacific Northwest and Nordic softwood timberlands anchors supply position for integrated producers while insulating pricing power against resin cost volatility. This upstream consolidation allows dominant players to buffer phenol-formaldehyde input fluctuations through internal veneer peeling capacity, whereas non-integrated competitors face margin compression without captive feedstock hedges.
Pricing Analysis
Margin tightening in Premium LVL reflects architect-specified aesthetic grading requirements and tight dimensional tolerances for exposed mass timber applications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification burden under ISO 18765 and TSCA Title VI, with volume-scale contracting by modular prefabricators commanding favorable tier placement. Cost-down pressure on Structural LVL accelerates because petrochemical resin formulations dominate adhesive input costs. Residential contractors exhibit highest price sensitivity due to commodity substitution options, while commercial developers specifying exposed beams demonstrate lowest sensitivity.
Supply Chain Analysis
Direct-to-modular-fabricator channels handle hyperscale buyer demand from Swedish and Finnish wall-and-floor cassette producers negotiating multi-year offtake agreements. Geographic supply concentrates in the United States, Canada, and Finland where softwood veneer clusters feed large-format press infrastructure. Raw material dependencies center on phenol-formaldehyde resin formulations, exterior-grade adhesive chemicals, and softwood peel feedstock. Single-source vulnerability in Nordic veneer peeling capacity creates bottleneck risk for European modular builders. Distribution runs through specification-contracting relationships with pre-cut precision nodes shipping directly to automated assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Veneer lathe operator scarcity in Pacific Northwest mills props pricing by constraining expansion-ready capacity, creating durable supply inelasticity against demand growth from eighteen-story mass timber code allowances.
For Market Incumbents: To counter phenol-formaldehyde resin cost volatility, secure captive adhesive formulation capacity or long-term chemical supply agreements with fixed-price mechanisms. Expand veneer peeling operations in British Columbia and Oregon to deepen upstream control over softwood feedstock quality and volume. For New Entrants and Emerging Players: Capture fire-rated Specialty LVL demand for German and Austrian tunnel infrastructure where incumbent capacity concentrates on residential grades. Target Austrian transit platform applications requiring preservative treatment approvals beyond standard structural certification. Enter through technical partnership with established adhesive formulators to accelerate TSCA Title VI compliance timelines. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated forest products groups seeking Pacific Northwest veneer capacity. Long-term viability favors producers with captive timberland supply and modular fabricator relationships. Monitor International Building Code adoption velocity across US jurisdictions as inflection indicator for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Veneer Peeling | Captive softwood supply from British Columbia timberlands secures feedstock cost predictability for large-format LVL presses. |
| Fire-Rated Lamination Certification | TSCA Title VI and ISO 18765 compliance opens German tunnel infrastructure contracts beyond residential construction. |
| Long-Term Supply Agreement with Modular Fabricators | Multi-year offtake contracts with Swedish cassette producers lock volume-tier pricing and capacity utilization. |
| Digital Veneer Grading Investment | Machine vision defect detection at Nordic peeling lines automates strength sorting for architect-specified Premium LVL. |
| Preservative Treatment Capacity Addition | Specialty LVL infrastructure qualification for Austrian rail platforms extends product mix beyond commodity structural beams. |
Research Methodology
Independent corroboration across veneer mill operations directors, modular prefabrication procurement leads, and adhesive formulation chemists underwrites the qualitative findings. Secondary validation draws from EPA TSCA Title VI certification databases, EU Construction Products Regulation CE marking records, and ISO 18765 structural performance documentation. Bottom-up triangulation of production capacity by mill and top-down demand estimation by construction application segment reconciles volume outputs.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in structural versus premium grades. Segmentation dimensions modeled include product certification tier, end-use application, buyer archetype, and regional production cluster. CAGRs derive from trend extrapolation of veneer peeling capacity expansion, code amendment adoption curves, and resin cost input trajectories. Forecast inputs incorporate modular prefabrication penetration rates and mass timber height limit regulatory amendments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to phenol-formaldehyde supply disruptions and peeling operator training program effectiveness. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Rubble Sacks Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Global Awning Market
Building & Construction Materials
Global Sandwich Panels Market
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Rebars Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
Global Wood Cement Boards Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Window Film Market
Building & Construction Materials
Ceiling Tiles Market