
 Bollard Market | 2026-2036
Bollard Market Size, Share, and Industry Trends Forecast 2026-2036
Bollard Market Analysis
Composite polymer reinforcement is expanding its share in bollard manufacturing as municipalities seek lighter alternatives to traditional steel and concrete. FAAC Group leverages its automation expertise to dominate retractable security bollard systems for critical infrastructure. MARSHALLS plc anchors the decorative and urban design segment through extensive stone and concrete product portfolios. Delta Scientific Corporation specializes in high-impact K-rated vehicle barrier systems for government and embassy applications.
A bollard is a short vertical post, typically manufactured from steel, concrete, aluminum, or engineered polymers, designed to control vehicle access, protect structures or pedestrians, and define spatial boundaries in urban and commercial environments. Steel bollards generally achieve ASTM F2656 crash ratings through reinforced core construction and deep foundation anchoring. The retractable type commands premium positioning due to integrated hydraulic or electromechanical drive systems and associated maintenance contracts. Decorative bollards represent a mature margin pool where aesthetic differentiation and material finishing determine supplier selection.
ASTM International publishes crash-test standards that shape product certification requirements for anti-ram bollards in US federal and commercial installations. The EU Machinery Directive and CE marking obligations govern automated retractable bollard safety systems across European member states. Stakeholders must monitor evolving perimeter security mandates from the Department of Homeland Security and corresponding European standard updates to align R&D roadmaps with compliance timelines.
Market Dynamics
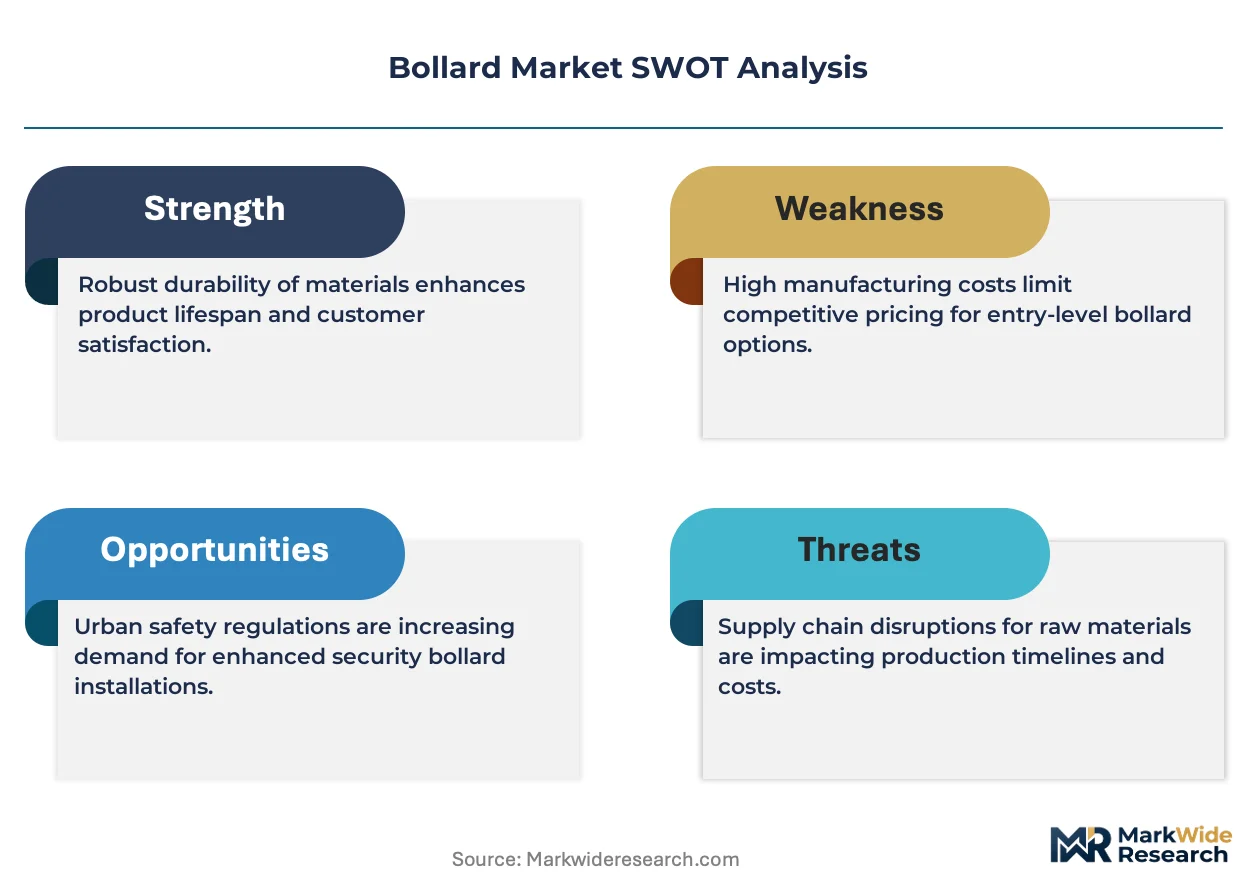
Crash-rating certification requirements from ASTM and the EU Machinery Directive are compressing supplier margins while elevating technical barriers to entry, forcing manufacturers to absorb testing costs or exit the anti-ram segment entirely.
Growth Catalysts
- Pedestrianization mandates:Dutch cycling infrastructure corridors and German urban zones drive specification volume for impact-rated bollards in dense European city centers.
- ASTM F2656 certification:US federal installation standards create recurring demand for K-rated vehicle barriers at embassies and critical infrastructure sites.
- Composite polymer adoption:Municipalities specify glass-fiber-reinforced nylon cores to reduce installation weight and foundation requirements versus steel alternatives.
Market Restraints
- Steel price volatility:Reinforced core construction depends on hot-rolled steel input costs that fluctuate with scrap metal and energy pricing cycles.
- Foundational anchoring complexity:Deep embedment requirements for crash-rated systems extend project timelines and increase civil engineering coordination costs.
- Retractable system substitution:Automated barrier gates compete for high-security vehicle access control budgets with faster cycle times and lower maintenance profiles.
Strategic Opportunities
- Smart city integration:Sensor-embedded bollards communicating traffic flow data to municipal IoT platforms open specification channels in Barcelona and Singapore pilot programs.
- CE marking tailwinds:The EU Machinery Directive's safety system obligations create recurring retrofit demand for electromechanical drive upgrades across aging European installations.
- Modular decorative systems:Stone-clad polymer cores allow architects to specify aesthetic continuity across historic districts without sacrificing impact resistance.
Industry Challenges
- Certification timeline compression:ASTM F2656 test scheduling at accredited facilities creates six-to-nine-month bottlenecks for new product introductions.
- Hydraulic maintenance skill scarcity:Retractable bollard service contracts require technicians certified in electromechanical and fluid power systems that few municipal workforces possess.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bollard Market |
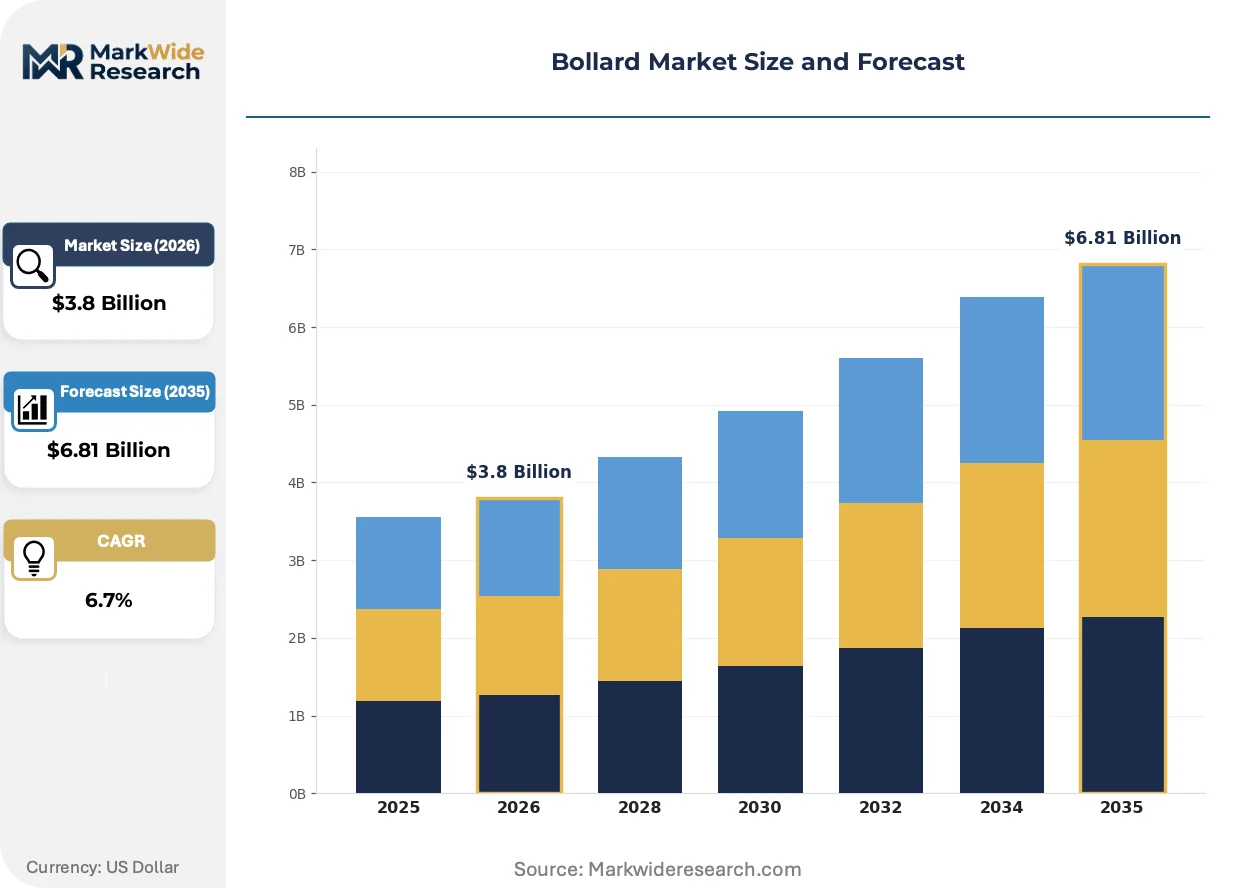
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Concrete, Steel, Plastic, Aluminum Type: Fixed, Removable, Retractable, Decorative Application: Traffic Management, Security, Urban Design, Parking Control End User: Government, Commercial, Residential, Infrastructure |
| Companies Covered | FAAC Group, MARSHALLS plc, Calpipe Industries, Avon Barrier Corporation Ltd, Automatic Systems, Delta Scientific Corporation, Schneider Electric, Magnetic Autocontrol GmbH, CAME Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bollard Market Emerging Trajectories
Material science advances and embedded connectivity are redefining bollard functionality beyond passive protection, creating specification competition between legacy steel fabricators and polymer-composite entrants.
Glass-fiber-reinforced polymer cores are consolidating market position in lightweight municipal applications. Parks departments and pedestrian plaza designers specify these systems to reduce crane rental costs and accelerate installation schedules. The technology is consolidating procurement decisions around total-project economics rather than unit material costs.
REACH substance restrictions on chromate conversion coatings are forcing European manufacturers to adopt zinc-nickel plating or powder-coat alternatives for corrosion protection. The regulation eliminates legacy surface treatment options for suppliers serving Germany and the Netherlands. Specifiers now demand coating warranty documentation that extends to fifteen-year performance guarantees.
Buying committees at transportation departments now bundle bollard specification with multi-year maintenance contracts rather than separating capital and operational budgets. Channel partners with in-house service capabilities capture specification authority from pure-product distributors. This pattern concentrates in UK and Scandinavian markets where public-private partnership frameworks dominate infrastructure procurement.
Bollard Market Segmentation
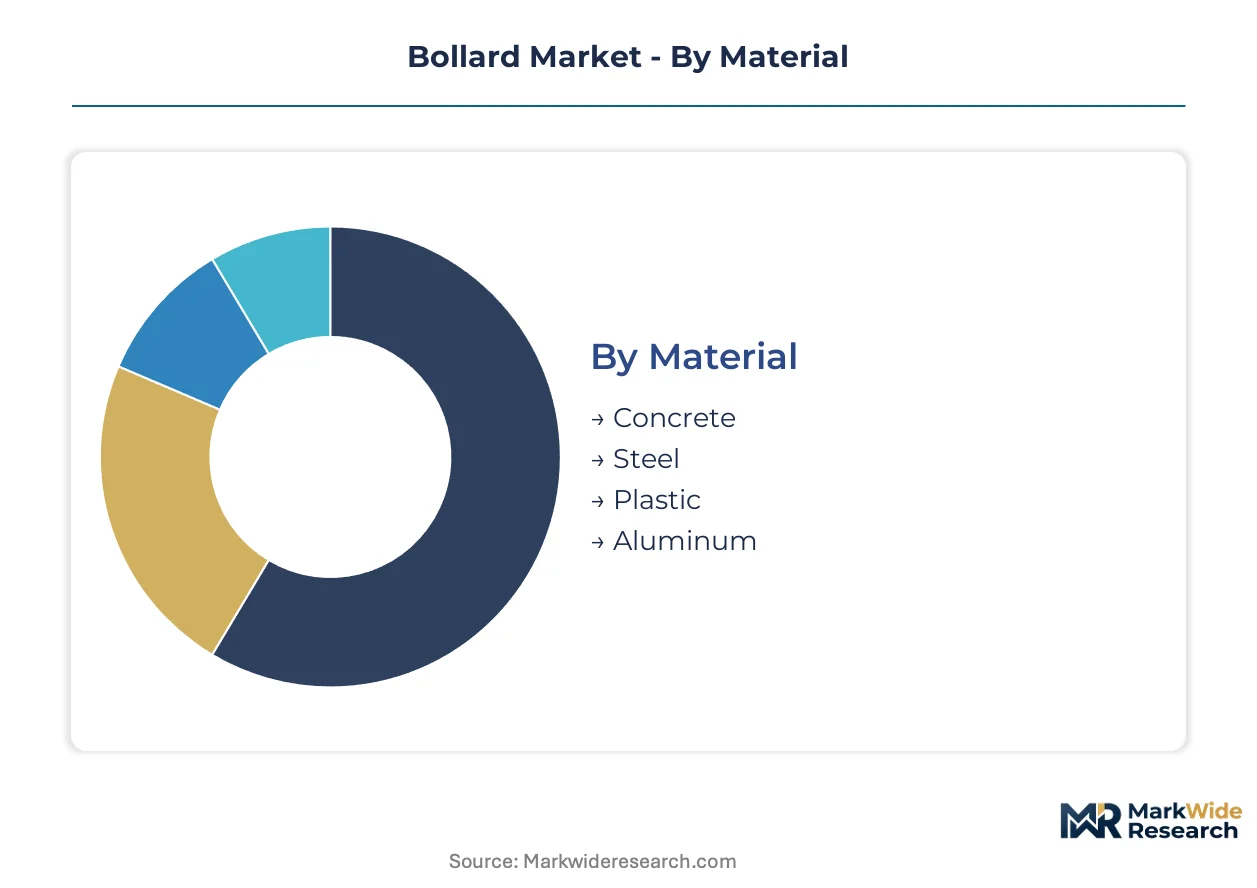
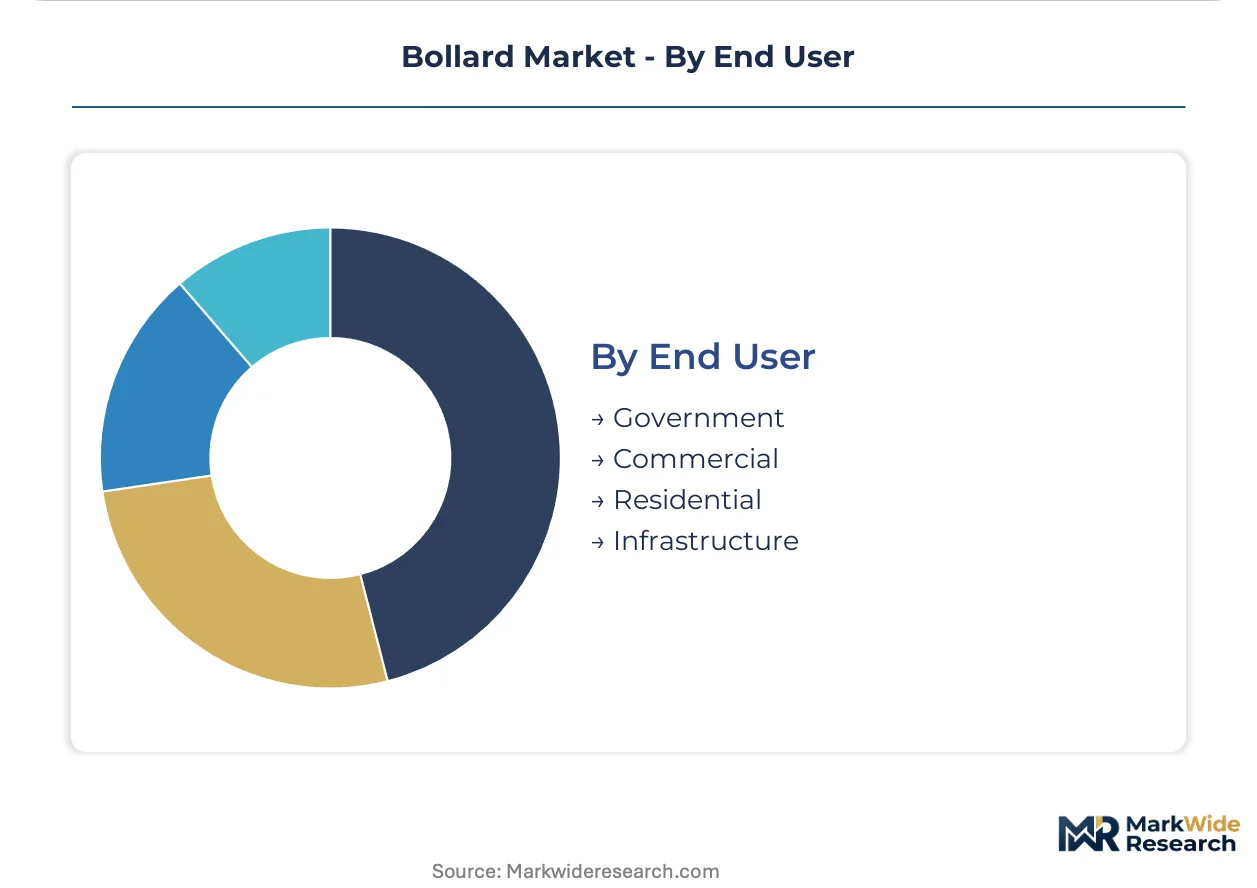
Specification committees in municipalities and transportation departments segment procurement across material performance, operational mobility, and aesthetic integration. Each axis carries distinct certification burdens and lifecycle cost profiles that determine supplier qualification.
Material:
Material selection pivots on impact-resistance certification against total installed weight and foundation requirements.
- Steel:Reinforced core construction achieves ASTM F2656 crash ratings through deep embedment anchoring. German pedestrianization programs and US embassy security specifications drive demand despite hot-rolled steel price volatility.
- Concrete:Pre-cast or poured-in-place systems dominate permanent anti-ram installations where weight itself provides stopping power. Dutch cycling infrastructure corridors specify concrete bollards for their vandal resistance and minimal maintenance profile.
- Plastic:Glass-fiber-reinforced polymer cores reduce crane rental costs and accelerate installation in parks departments and pedestrian plazas where crash ratings are secondary to visual demarcation.
- Aluminum:Anodized or powder-coated extrusions serve decorative urban design applications requiring corrosion resistance without steel's mass.
Mature deployment sits with Steel. Newer deployment is concentrated in Plastic.
Type:
Operational mobility determines capital expenditure tiers and recurring maintenance obligations across the installed base.
- Fixed:Permanent embedded posts constitute the volume base for traffic management and basic security perimeters. These systems require no moving parts but demand civil engineering coordination for deep foundation work.
- Removable:Locking pin or padlock-based systems allow temporary vehicle access for emergency services or event management. UK transportation departments specify these for historic districts requiring occasional service vehicle entry.
- Retractable:Hydraulic or electromechanical drive systems command premium positioning through integrated automation and multi-year service contracts. Barcelona and Singapore smart city pilots specify sensor-embedded retractable units for dynamic traffic flow management.
- Decorative:Aesthetic differentiation drives specification in urban design segments where stone cladding or custom finishing determines architect selection.
Fixed bollards retain the largest installed base. Retractable systems are climbing the fastest on smart city integration.
Application:
Functional purpose shapes crash-rating requirements and regulatory compliance intensity.
- Traffic Management:Lane delineation and speed calming in urban corridors. Municipal specifications prioritize visibility and durability over anti-ram performance.
- Security:K-rated vehicle barriers for critical infrastructure, government facilities, and embassy perimeters. ASTM F2656 certification creates six-to-nine-month testing bottlenecks that compress supplier margins.
- Urban Design:Pedestrian zone definition and historic district aesthetic continuity. Stone-clad polymer cores allow architects to match architectural heritage without sacrificing modular installation.
- Parking Control:Perimeter demarcation for commercial lots and residential developments. Specifications emphasize cost efficiency and rapid deployment over impact resistance.
Security applications carry the heaviest compliance burden. Urban Design is gaining share fastest on pedestrianization mandates.
End User:
Procurement authority and budget structure vary sharply across public and private deployment contexts.
- Government:Federal, state, and municipal installations subject to ASTM or EU Machinery Directive compliance. US Department of Homeland Security perimeter security mandates drive recurring specification volume.
- Commercial:Retail campuses, corporate headquarters, and hospitality venues. Buying committees bundle capital expenditure with multi-year maintenance contracts, favoring channel partners with in-house service capabilities.
- Residential:Gated communities and private property access control. Price sensitivity dominates, with plastic and aluminum systems preferred over steel or retractable alternatives.
- Infrastructure:Airports, seaports, utilities, and transportation hubs. Critical infrastructure designation triggers enhanced crash-rating requirements and extended coating warranty demands.
Government procurement maintains specification authority on certification standards. Commercial end users are expanding fastest on bundled service contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Guangdong Province and industrial parks near Rotterdam concentrate bollard manufacturing capacity. Government procurement programs in Germany and pedestrianization mandates in Dutch cities drive specification volume. Compliance requirements from ASTM and the EU Machinery Directive shape regional competitive positioning.
United States
Department of Homeland Security perimeter security mandates drive federal installation demand for ASTM F2656-certified barriers. The Infrastructure Investment and Jobs Act channels funding toward critical infrastructure hardening. Embassy clusters in Washington DC and consulate districts in New York specify K-rated vehicle protection systems.
Germany
Pedestrianization programs in Berlin, Munich, and Hamburg municipal zones generate sustained specification volume for impact-rated systems. The EU Machinery Directive and CE marking obligations govern automated retractable bollard safety compliance. Industrial fabricators in North Rhine-Westphalia and Bavaria anchor continental supply capacity.
Netherlands
Cycling infrastructure corridors in Amsterdam, Utrecht, and Rotterdam drive demand for crash-rated lane protection. REACH substance restrictions on chromate conversion coatings force coating specification shifts toward zinc-nickel plating. Randstad urban planners bundle bollard procurement with multi-year maintenance contracts.
China
Smart city pilot programs in Shenzhen and Hangzhou specify sensor-embedded retractable units for dynamic traffic management. GB standards and MIIT regulations shape product certification for domestic and export markets. Yangtze River Delta manufacturing clusters produce composite polymer cores for lightweight municipal applications.
United Kingdom
Transportation departments in London and Manchester specify removable systems for historic districts requiring occasional service vehicle access. Public-private partnership frameworks dominate infrastructure procurement across UK and Scandinavian markets. Stone-clad polymer cores allow architects to match architectural heritage without sacrificing modular installation.
Bollard Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with crash-rated security systems consolidating around certified fabricators while decorative applications fragment across regional stone and concrete suppliers. The retractable bollard segment exhibits tighter concentration due to electromechanical drive system complexity and maintenance contract bundling. Three archetypes dominate: automation-integrated security specialists, material-science polymer innovators, and heritage-focused urban design houses. Competitive moves center on strategic partnerships for smart city integration and backward integration into composite core manufacturing.
Within the automation-integrated tier, FAAC Group and Magnetic Autocontrol GmbH exemplify European specialists leveraging electromechanical expertise for retractable security systems. MARSHALLS plc anchors the heritage-design archetype through its UK-based stone and concrete portfolio. Delta Scientific Corporation occupies a position among North American fabricators focused on high-impact vehicle barrier certification.
| Leading Market Players |
|---|
| FAAC Group |
| MARSHALLS plc |
| Calpipe Industries |
| Avon Barrier Corporation Ltd |
| Automatic Systems |
| Delta Scientific Corporation |
| Schneider Electric |
| Magnetic Autocontrol GmbH |
| CAME Group |
| Others |
Supply Flow & Price Mechanics
Hot-rolled steel index volatility cascades through bollard manufacturing tiers, compressing margins on ASTM F2656-certified systems while elevating procurement premiums for glass-fiber-reinforced polymer alternatives in weight-sensitive municipal specifications.
Pricing Analysis
Lead-time premiums separate crash-rated steel bollards with six-to-nine-month ASTM certification queues from spot-available decorative polymer systems. Three-tier pricing structure across premium retractable, standard fixed, and economy plastic demarcation posts reflects certification burden and foundation complexity. Pricing pressure stems from REACH coating compliance costs forcing zinc-nickel plating adoption in EU-bound production. Residential end users exhibit highest price sensitivity, while infrastructure buyers absorb premium positioning for bundled maintenance contracts.
Supply Chain Analysis
Freight cost inflation from Yangtze River Delta manufacturing clusters to Rotterdam distribution hubs compresses landed margins on composite polymer cores. Supply concentrates in China's industrial parks, Germany's North Rhine-Westphalia fabricators, and Netherlands coating specialists. Raw material flows draw from hot-rolled steel mills, glass-fiber resin suppliers, and chromate-free plating chemical providers. Single-source vulnerability sits with accredited ASTM F2656 testing facilities creating certification bottlenecks. Distribution runs through transportation department procurement frameworks in European pedestrianization corridors and US federal security installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bollard market functions as a cost-of-compliance arena where ASTM F2656 and EU Machinery Directive certification burdens erect technical moats favoring incumbent fabricators with captive testing relationships and established electromechanical service networks.
For Market Incumbents: Lock in specification authority by acquiring accredited testing capacity to compress certification timelines below competitor reach, while embedding sensor-embedded connectivity into retractable portfolios to capture Barcelona and Singapore smart city pilot demand. Hydraulic maintenance skill scarcity threatens service contract renewal rates; address through apprenticeship pipelines with North Rhine-Westphalia technical institutes. For New Entrants and Emerging Players: Digital specification platforms targeting UK transportation departments offer route-around channels bypassing incumbent distributor relationships. Modular decorative systems with stone-clad polymer cores penetrate fastest in historic district pedestrianization programs where aesthetic compliance trumps crash-rating intensity. Lead with rapid-install lightweight offerings that reduce crane rental costs against steel-dependent competitors. For Investors and Strategic Acquirers: The window for entry favors automation-integrated security specialists with electromechanical drive expertise and existing CE marking compliance infrastructure. Long-term viability hinges on service contract bundling concentration in UK and Scandinavian public-private partnership markets. Watch for Department of Homeland Security perimeter security mandate expansion as inflection signal for federal specification volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Composite Core Manufacturing | Captive supply of glass-fiber-reinforced polymer reduces crane-dependent installation cost exposure for municipal buyers. |
| Accredited Testing Facility Acquisition | Ownership of ASTM F2656 certification capacity compresses six-to-nine-month bottlenecks constraining competitor product launches. |
| Smart City Sensor Integration Partnership | Traffic flow data connectivity aligns specification authority with Barcelona and Singapore pilot program procurement channels. |
| Multi-Year Maintenance Contract Bundling | Channel partners with in-house electromechanical service capabilities displace pure-product distributors in UK transportation departments. |
| REACH-Compliant Coating Process Transition | Zinc-nickel plating adoption preserves EU market access as chromate conversion coatings face substance restrictions. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with municipal procurement officers, transportation department engineers, perimeter security consultants, and retractable system service technicians provided demand-side validation. ASTM International certification databases, EU Machinery Directive compliance registries, and steel price index series supplied top-down market sizing inputs. Bottom-up triangulation crossed project-level specification data with channel shipment reports.
Data-stream reconciliation across material segmentation, operational mobility tiers, and end-user procurement frameworks shaped volume and value outputs across the analysis window. CAGRs derived from trajectory fitting against pedestrianization mandate implementation schedules and critical infrastructure hardening appropriation patterns. Modeled inputs included smart city pilot expansion rates, REACH coating transition timelines, and bundled service contract penetration curves in UK and Scandinavian markets.
The model holds under steady regulatory compliance burden and sustained steel price volatility; deviation in ASTM F2656 test facility capacity or EU Machinery Directive enforcement intensity would shift competitive positioning and forecast trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
North America Balustrade Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Ball Iron Rods Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Garage and Overhead Doors Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
North America Mineral Wool Ceiling Tiles Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
Non-Residential Polished Concrete Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Fiberglass Doors Market