
 North America Ready-Mix Concrete Market | 2026-2036
North America Ready-Mix Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
North America Ready-Mix Concrete Market Analytics
Modular batching and site-specific additive bundling is pivoting how contractors specify ready-mix concrete, shifting purchase decisions from commodity-grade volume to engineered performance packages. CEMEX leverages its integrated aggregates network across the US Southwest to control raw material flow into batch plants. Heidelberg Materials anchors its position through deep vertical integration into cement production, captive supply that insulates margin from clinker price swings. Vulcan Materials dominates regional aggregates-to-concrete logistics in the Southeast, extending its quarry-to-project pipeline into metropolitan Atlanta and Charlotte.
Ready-mix concrete consists of Portland cement, aggregates, water, and chemical admixtures batched at central plants and delivered in plastic condition for placement, typically specified by compressive strength at 28 days ranging from 3,000 to 10,000 psi depending on structural load requirements. Its primary purpose is to provide standardized, quality-controlled concrete for construction projects where on-site mixing is impractical or quality-inconsistent. Standard-grade product still occupies the largest volume share across residential foundations and basic pavements, though self-consolidating concrete is gaining fastest in complex commercial structures where reduced labor and improved surface finish command premium positioning. High-strength grades concentrate margin pools in infrastructure projects requiring extended service life under heavy dynamic loading.
The US EPA enforces National Ambient Air Quality Standards that constrain cement kiln emissions, while state regulators in California implement the Buy Clean California Act embedding carbon intensity thresholds into public procurement. ASTM C94 and ACI 318 standards govern material specifications and structural design, creating compliance barriers for non-conforming imports. Stakeholders must monitor how evolving federal infrastructure spending timelines interact with state-level environmental performance mandates to anticipate where specification premiums will emerge.
Market Dynamics
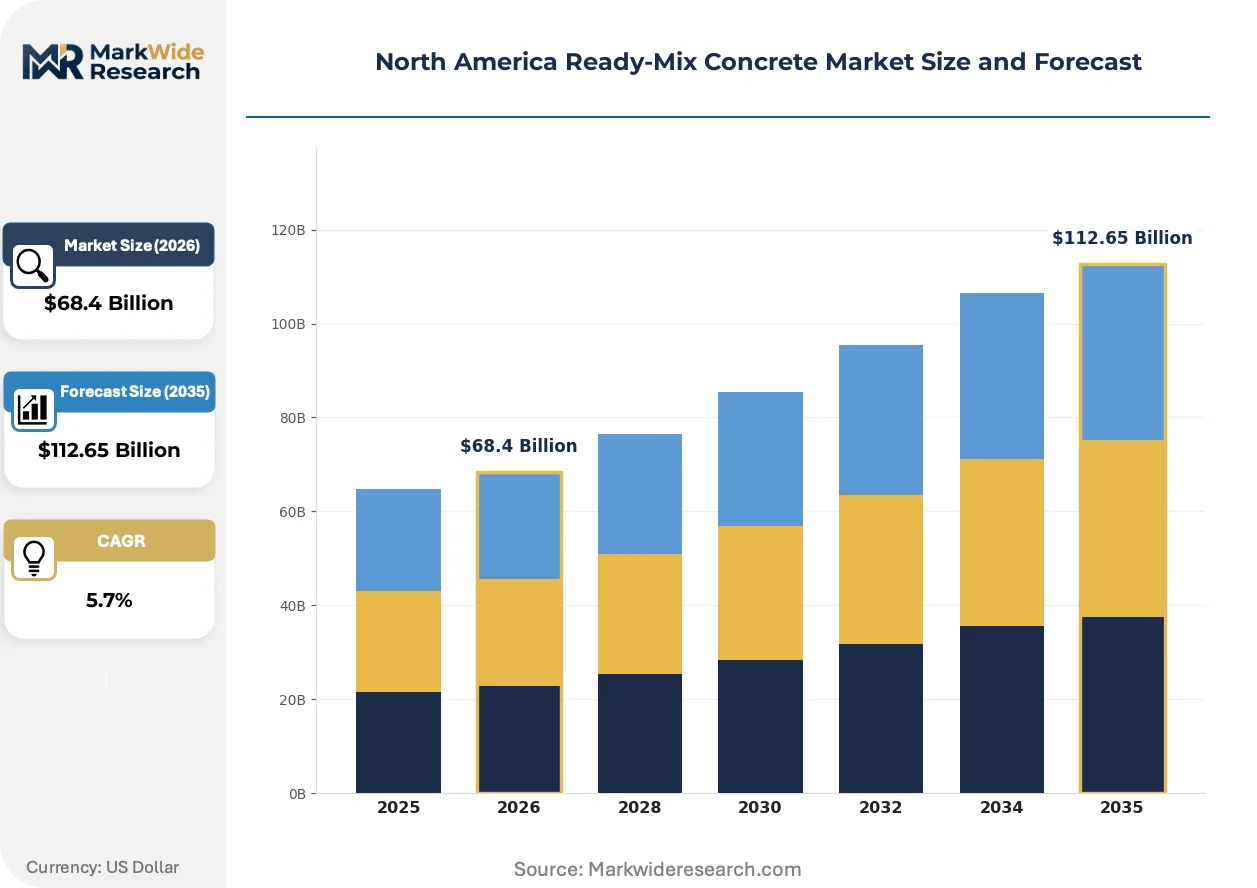
Federal infrastructure spending timelines and state-level carbon intensity mandates are creating divergent specification pressures across North American ready-mix concrete markets. The tension between volume-driven highway contracts and performance-grade commercial projects is fragmenting procurement patterns and margin structures.
Growth Catalysts
- Infrastructure Investment and Jobs Act disbursements:Federal transportation allocations across the United States are accelerating demand for high-performance concrete grades in bridge deck overlays and highway rehabilitation.
- Buy Clean California Act thresholds:Public procurement in California now embeds carbon intensity limits, pulling producers toward lower-clinker formulations and supplementary cementitious material blends.
- Urban density corridors:Metropolitan expansion in Texas, Ontario, and California is concentrating demand for self-consolidating concrete in complex commercial foundations and high-rise cores.
Market Restraints
- Clinker and cement supply concentration:Limited domestic kiln capacity and import dependence for specialty cement grades expose margins to energy price volatility and freight cost swings.
- EPA National Ambient Air Quality Standards:Emissions constraints on cement production are tightening feedstock availability for low-carbon concrete formulations in certain air quality non-attainment zones.
- Ready-mix concrete perishability:The ninety-minute placement window limits geographic radius from batch plants, constraining market expansion into exurban construction zones.
Strategic Opportunities
- Carbon capture integration at batch plants:Emerging mineralization technologies offer pathways to negative-emission concrete products qualifying for green procurement premiums.
- Modular additive bundling:Site-specific admixture packages for corrosion resistance or rapid strength gain command specification premiums in coastal infrastructure and cold-weather jurisdictions.
- Quebec and Ontario low-carbon mandates:Provincial environmental performance standards in Canada are creating first-mover advantages for producers with verified environmental product declarations.
Industry Challenges
- Certified concrete technician scarcity:ACI and NRMCA certification requirements for mix design and quality control are outpacing training pipeline capacity, constraining plant expansion timelines.
- Fleet electrification capex burden:Transitioning mixer trucks to electric or alternative fuel platforms demands substantial capital redeployment without immediate fuel cost parity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Ready-Mix Concrete Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $112.65 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, High-Strength, Self-Consolidating, Lightweight End Use: Residential Buildings, Commercial Structures, Infrastructure Projects, Industrial Facilities Delivery Mode: Truck Delivery, Rail Delivery, On-Site Mixing, Pre-Packed Application: Foundations, Pavements, Walls, Decorative Finishes |
| Companies Covered | CRH, CEMEX, Vulcan Materials, Lehigh Hanson, Holcim, Heidelberg Materials, Calportland, Eagle Materials, Ash Grove Cement, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Ready-Mix Concrete Market Evolving Landscape
Digital batching systems and connected logistics platforms are compressing the gap between specification and placement. These technologies are enabling real-time mix adjustment and reducing waste while tightening quality control loops.
Automated slump monitoring and IoT-enabled drum sensors are automating quality assurance throughout the delivery cycle. Infrastructure contractors across the United States are adopting these systems fastest, driven by federal project documentation requirements. The technology is automating compliance verification and reducing on-site testing labor while compressing project schedules.
The US EPA is tightening particulate matter standards for cement kiln operations, forcing upstream capacity reconfiguration. This regulatory pressure is constraining clinker availability for certain low-carbon blend targets. Producers in California and Texas are responding by accelerating supplementary cementitious material qualification programs.
Specification bundling is consolidating procurement decisions around performance outcomes rather than commodity unit pricing. Commercial contractors are displacing traditional volume-based contracts with warranty-backed durability agreements. This shift is most visible in Ontario and California, where green building certification requirements are embedding lifecycle performance criteria into concrete selection.
North America Ready-Mix Concrete Market Segmentation
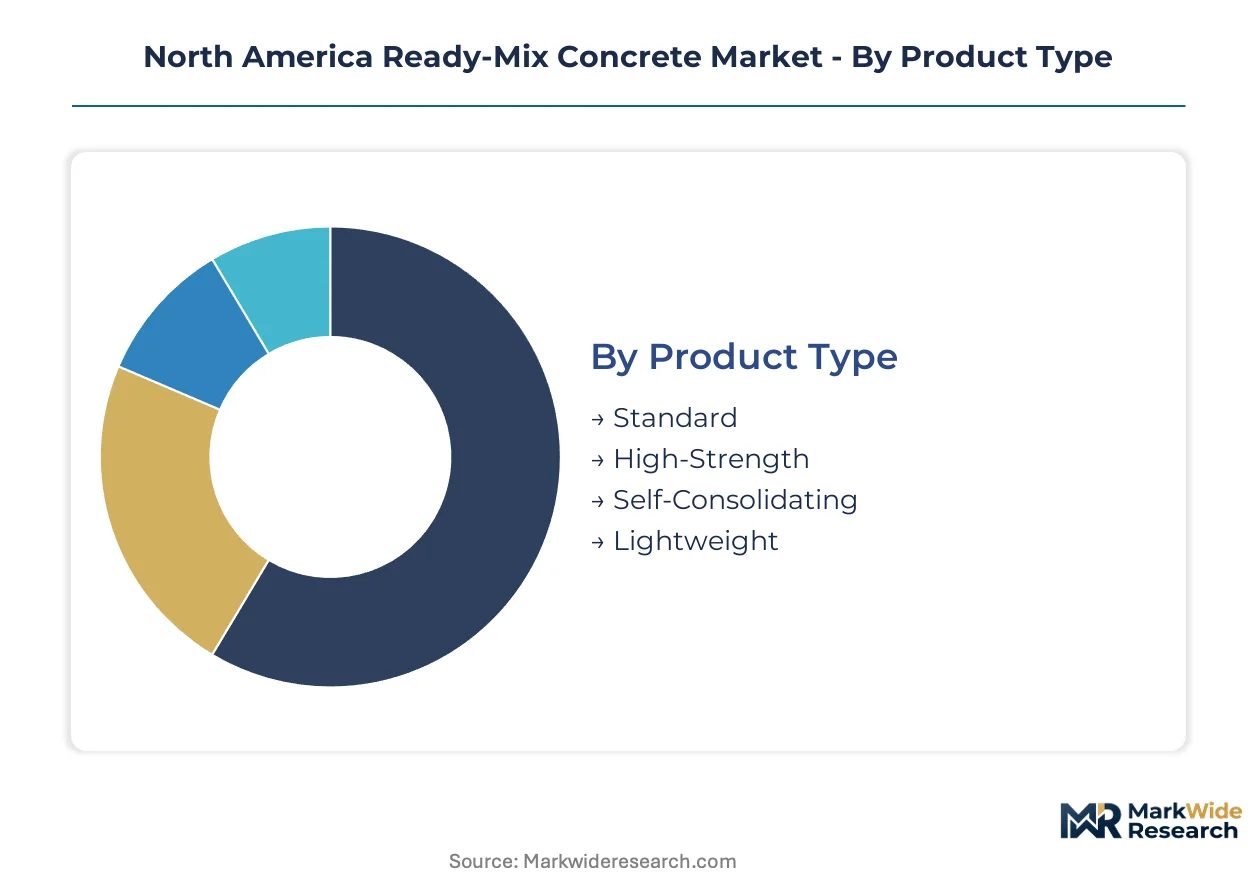
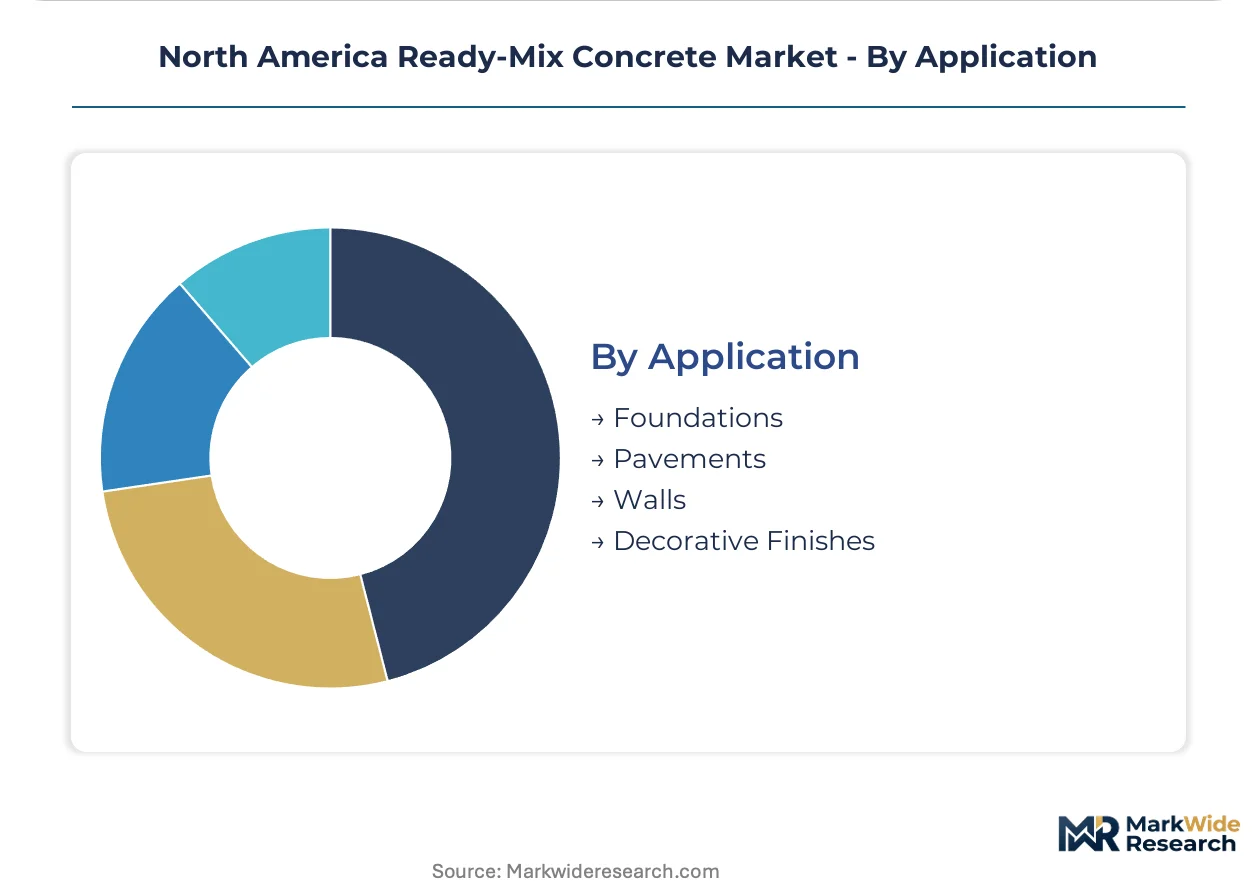
Segmentation in ready-mix concrete determines capital allocation across batch plant configurations, fleet composition, and quality control infrastructure. Each dimension—product grade, end-use vertical, delivery mechanism, and application type—carries distinct margin profiles and equipment requirements that reshape producer investment priorities.
Product Type:
Capital intensity varies sharply across formulation complexity, with specialized admixture systems demanding dedicated storage silos and precision metering equipment.
- Standard:Basic Portland cement formulations with compressive strength between 3,000 and 4,000 psi dominate residential foundation work across Texas and the US Southeast. Batch plants serving this segment require minimal admixture infrastructure, keeping upfront equipment costs lowest among all grades.
- High-Strength:Grades exceeding 6,000 psi incorporate silica fume and superplasticizer packages for bridge decks and high-rise cores in California and Ontario. These formulations command premium positioning but require laboratory-grade quality control systems and certified technician oversight at each plant.
- Self-Consolidating:Flowable mixes with viscosity-modifying admixtures reduce labor in complex commercial geometries across metropolitan Atlanta and Charlotte.
- Lightweight:Expanded shale or pumice aggregates cut dead loads in mid-rise construction throughout the US Southwest.
Most installed capacity flows through Standard grades. Expansion is steepest in Self-Consolidating formulations.
End Use:
Customer procurement patterns split between project-scale volume contracts and recurring maintenance agreements, reshaping sales force structure and credit terms.
- Infrastructure Projects:Federal highway rehabilitation programs in the United States absorb high-performance grades under multi-year supply agreements with performance warranties. The US Department of Transportation documentation requirements embed ASTM C94 compliance into contract terms, creating qualification barriers for smaller regional producers.
- Commercial Structures:Self-consolidating and high-early-strength specifications dominate high-rise cores and complex foundations in Toronto, Vancouver, and California metropolitan corridors. General contractors in these markets are consolidating procurement around engineered performance packages rather than commodity per-yard pricing.
- Residential Buildings:Single-family and low-rise multifamily construction across the US Sun Belt drives volume demand for standard-grade product with predictable seasonal patterns.
- Industrial Facilities:Heavy-duty pavements and equipment foundations in manufacturing zones require abrasion-resistant formulations with extended service life guarantees.
Volume concentrates in Residential Buildings. Specification premiums are climbing fastest in Commercial Structures.
Delivery Mode:
Logistics configuration dictates geographic radius and fleet investment, with perishability constraints limiting market reach from each production node.
- Truck Delivery:Rotating drum mixers maintain plasticity during transport for ninety-minute placement windows across urban construction corridors. The US EPA and state air quality boards are tightening emissions standards for diesel-powered fleets, forcing capital redeployment toward alternative fuel platforms without immediate operating cost parity.
- On-Site Mixing:Portable batch plants serve remote infrastructure sites in northern Canada and rural Texas where transit-mixed concrete would exceed placement time limits. Equipment mobility requirements elevate capital costs per cubic yard of installed capacity compared to fixed-plant operations.
- Rail Delivery:Bulk cement and pre-blended dry mixes feed large-scale dam and highway projects with dedicated siding infrastructure.
- Pre-Packed:Bagged concrete mixes address repair and small-volume applications through retail distribution channels.
Truck Delivery carries the heaviest fleet capital burden. On-Site Mixing is gaining share in exurban and remote project zones.
Application:
Technical specifications diverge across structural versus architectural uses, with surface finish requirements driving admixture selection and quality control intensity.
- Foundations:Mat slabs, pile caps, and grade beams in high-rise construction across Toronto and Vancouver demand self-consolidating concrete with minimal vibration. The Buy Clean California Act is embedding carbon intensity thresholds into public foundation contracts, pulling producers toward supplementary cementitious material blends.
- Pavements:Highway overlays and airport runways in Texas and California require air-entrainment for freeze-thaw durability and rapid strength gain for minimized traffic disruption. Federal Infrastructure Investment and Jobs Act disbursements are accelerating specification upgrades in this segment.
- Walls:Vertical structural elements in commercial and industrial construction use standard to high-strength grades depending on lateral load requirements.
- Decorative Finishes:Exposed aggregate, stamped, and colored concrete in commercial landscaping and architectural applications command specialty admixture and surface treatment premiums.
Pavements absorb the largest absolute volume of high-performance grades. Foundations are climbing fastest on green procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ready-mix concrete production in North America traces its modern scale to post-war highway construction across the United States, where centralized batching replaced on-site mixing for federal interstate projects. Canada followed with provincial infrastructure programs, while Mexico industrialized its concrete supply chain later through urbanization waves in the late twentieth century.
United States
Bridge deck overlays and highway rehabilitation across Texas and California absorb high-performance concrete grades under Infrastructure Investment and Jobs Act disbursements. The US EPA enforces National Ambient Air Quality Standards that constrain cement kiln emissions, tightening feedstock availability for low-carbon formulations. Metropolitan Atlanta and Charlotte concentrate self-consolidating concrete demand for complex commercial foundations.
Canada
Provincial transportation budgets in Ontario and Quebec are expanding highway rehabilitation programs that pull sustained volumes of ready-mix concrete. Health Canada and provincial environmental boards implement carbon intensity thresholds through environmental product declaration requirements in public procurement. Toronto and Vancouver anchor demand for high-rise core concrete with extended service life specifications.
Mexico
Urban density corridors in Mexico City and Monterrey are driving specification upgrades for commercial and residential foundations. The country's national environmental regulator tightens emissions standards for cement production, pushing producers toward supplementary cementitious material blends. Northern border states concentrate infrastructure-linked concrete demand from cross-border logistics and manufacturing facility construction.
North America Ready-Mix Concrete Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification intensity, with high-strength and self-consolidating grades commanding pricing power over standard residential foundations. The market structures around vertically integrated cement-to-concrete networks, regional aggregates specialists, and independent batch plant operators. Three archetypes dominate: captive cement producers with quarry-to-project pipelines, aggregates-led regional consolidators, and technology-focused admixture bundlers. Capacity expansion and backward integration into raw material supply represent the dominant competitive moves.
Among North American-based producers, CEMEX, Heidelberg Materials, and Vulcan Materials exemplify distinct strategic positions. CEMEX represents the multinational integrated archetype with cross-border cement and aggregates networks. Heidelberg Materials anchors the European-headquartered tier with captive clinker production and environmental product declaration capabilities. Vulcan Materials occupies the aggregates-led regional specialist position, extending quarry-to-concrete logistics into southeastern metropolitan corridors.
| Leading Market Players |
|---|
| CRH |
| CEMEX |
| Vulcan Materials |
| Lehigh Hanson |
| Holcim |
| Heidelberg Materials |
| Calportland |
| Eagle Materials |
| Ash Grove Cement |
| Others |
Value Network & Pricing Analysis
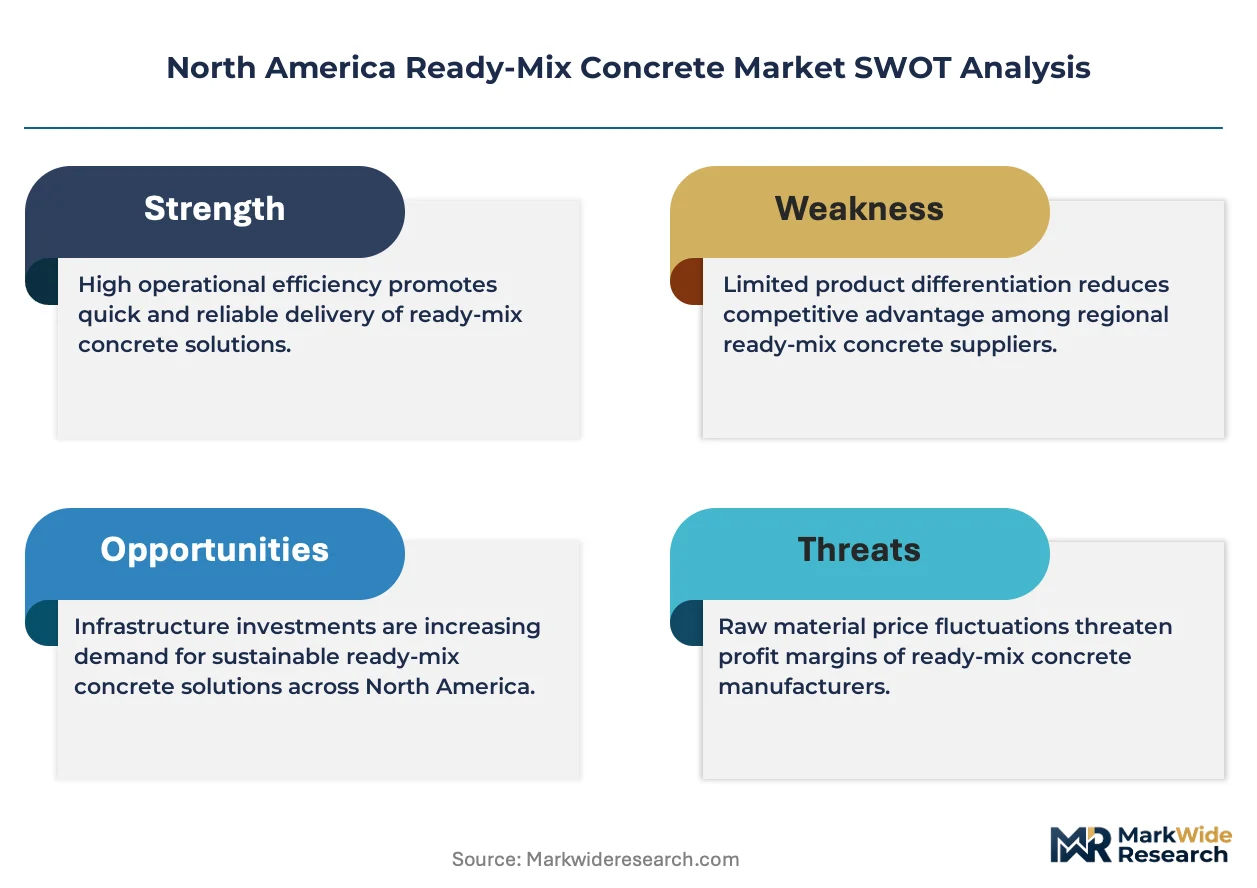
Performance-grade certification ladders separate premium self-consolidating and high-strength formulations from commodity standard grades, embedding this divergence into both margin structures and raw material procurement patterns across Texas, California, and Ontario batch plant networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs contractor procurement, with specification premiums for self-consolidating concrete in Toronto high-rise cores and highway rehabilitation grades in California reflecting ASTM C94 compliance intensity and certified technician oversight costs. Price differentiation hinges on admixture complexity and carbon intensity verification under Buy Clean California Act thresholds, with pricing pressure stemming from clinker supply constraints and energy cost volatility. Residential foundation contractors in the US Sun Belt exhibit highest price sensitivity, while infrastructure agencies absorb specification premiums for extended service life warranties.
Supply Chain Analysis
Returned concrete flows and washout water recovery systems create reverse-logistics infrastructure at batch plants, with mineralization technologies emerging to sequester carbon from residual material streams. Geographic supply concentration centers on the United States, Canada, and Mexico, with domestic clinker capacity constraints drawing from captive kiln networks and import channels. Raw material dependencies rest on Portland cement, supplementary cementitious materials, and regional aggregates. Supply chain risk manifests through single-source vulnerability for specialty cement grades and freight cost exposure. Distribution runs through rotating drum mixer fleets with ninety-minute placement radius constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between California's carbon-intensity procurement premiums and Texas volume-driven highway contracts, exploiting regulatory cost differentials across state jurisdictions.
For Market Incumbents: To counter fleet electrification capex burdens and certified technician scarcity, deepen backward integration into aggregates networks to insulate margin from raw material volatility, and anchor capacity expansion in Ontario and Quebec where provincial environmental product declaration requirements create first-mover qualification barriers. For New Entrants and Emerging Players: The mid-tier price-point gap between premium self-consolidating formulations and commodity standard grades offers white-space entry through modular on-site batching for exurban infrastructure corridors in northern Canada and rural Texas, penetrating remote project zones where transit-mixed concrete exceeds perishability windows. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented independent batch plant operators lack captive cement supply and environmental certification capabilities, positioning vertically integrated mid-cap specialists with verified environmental product declarations as viable acquisition targets over the medium-term horizon; monitor federal infrastructure disbursement acceleration and EPA emissions standard tightening as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration at Batch Plants | Mineralization technologies enable negative-emission concrete products qualifying for California and Ontario green procurement premiums. |
| Backward Integration into Aggregates Networks | CEMEX and Vulcan Materials demonstrate how quarry-to-project pipeline control insulates margin from clinker price swings. |
| Modular Additive Bundling Systems | Site-specific admixture packages for corrosion resistance command specification premiums in coastal infrastructure markets. |
| Fleet Electrification and Alternative Fuel Transition | EPA and state air quality board emissions standards force capital redeployment toward electric mixer platforms. |
| Environmental Product Declaration Certification | Buy Clean California Act and Quebec provincial mandates embed carbon intensity thresholds into public procurement eligibility. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study, combining primary interviews with batch plant managers, infrastructure procurement officers, commercial general contractors, and admixture technical directors with secondary validation through US EPA emissions filings, state transportation department contract databases, ASTM standards documentation, and industry association production surveys.
Historical trendline analysis across installed batch plant capacity, fleet composition shifts, and specification grade mix transitions informed the projection framework, with segmentation dimensions spanning product type, end-use vertical, delivery mechanism, and application type throughout the forecast period. CAGRs were derived from elasticity-adjusted demand modeling incorporating federal infrastructure disbursement timelines, state-level carbon intensity mandate phase-ins, and urban density corridor construction permit trajectories.
Caveats apply where clinker supply disruptions, EPA National Ambient Air Quality Standards enforcement variations, or certified technician training pipeline constraints could materially shift the outlook. Practitioners should monitor Infrastructure Investment and Jobs Act disbursement velocity and supplementary cementitious material qualification program progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Global Aluminum Cladding Panels Market
Building & Construction Materials
Wood Truss Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Concrete Aggregate Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
Asia-Pacific Ready-Mix Concrete Market
Building & Construction Materials
Insulated Concrete Form (ICF) Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Calcium Sulphate Board Raised Access Floor Market
Building & Construction Materials
UPVC Doors and Windows Market