
 Glue-Laminated Timber Market | 2026-2036
Glue-Laminated Timber Market Size, Share, and Industry Trends Forecast 2026-2036
Glue-Laminated Timber Market Intelligence
Commercial high-rise construction is rebalancing toward mass timber systems as developers pursue lower embodied-carbon footprints. Binderholz GmbH leverages vertical integration from forest holdings to engineered-wood finishing across Central European markets. Stora Enso Oyj anchors Nordic supply through large-scale spruce and pine processing infrastructure. Metsä Wood competes on prefabricated glulam component systems for fast-track building envelopes.
Glue-laminated timber consists of kiln-dried lumber boards bonded with moisture-resistant adhesives under controlled temperature and pressure, typically achieving bending strengths of 24–30 MPa in standard structural grades. The material primarily serves load-bearing applications in beams, columns, and arch forms where dimensional stability and high strength-to-weight ratios outperform solid sawn timber. Structural Glulam dominates volume throughput for commercial and institutional frameworks, while Architectural Glulam commands premium positioning in exposed interior applications where visual grade governs specification. Custom Glulam occupies project-specific niches with long lead times and higher margin pools tied to complex curvature or hybrid steel-timber connections.
CE marking under Europe's Construction Products Regulation mandates structural performance declarations for glulam used in permanent buildings. The US International Building Code, administered by the International Code Council, governs fire-resistance ratings and height allowances for Type IV heavy timber construction. Canada's National Building Code, enforced by the Canadian Commission on Building and Fire Codes, sets parallel standards for encapsulated mass timber assemblies. Stakeholders must track evolving height and area allowances in national building codes, as these provisions directly expand addressable market scope for multi-story glulam structures.
Market Dynamics
Europe's Ecodesign for Sustainable Products Regulation is compressing embodied-carbon thresholds for structural materials, forcing builders to substitute mass timber for steel and concrete in commercial high-rise construction. This regulatory pressure is redrawing competitive boundaries between engineered wood and conventional structural systems.
Growth Catalysts
- Commercial high-rise substitution:Developers in Austria, Canada, and the Pacific Northwest United States are specifying glulam columns and beams to meet stricter carbon-accounting requirements for Class A office towers.
- CE marking expansion:Europe's Construction Products Regulation mandates structural performance declarations that standardize glulam quality across member states, reducing specification friction for cross-border projects.
- Encapsulated mass timber codes:Canada's National Building Code and the US International Building Code are raising height allowances for Type IV heavy timber construction, directly enlarging addressable building envelopes.
Market Restraints
- Phenol-resorcinol formaldehyde cost volatility:Moisture-resistant adhesive chemistry depends on petrochemical feedstocks whose price swings compress margin predictability for engineered-wood producers.
- Nordic spruce supply concentration:Stora Enso and Metsä Wood anchor production around Baltic and Scandinavian forest holdings, creating geographic single-point vulnerability for European project pipelines.
- Steel-timber hybrid complexity:Custom Glulam requiring complex curvature or hybrid connections demands longer lead times and specialized fabrication capacity that limits scale economics.
Strategic Opportunities
- Prefabricated building envelopes:Fast-track construction methods in Germany and Austria favor factory-delivered glulam component systems that compress on-site assembly cycles.
- Architectural-grade exposed interiors:Visual-grade specification for atriums and lobbies commands premium positioning where aesthetic performance governs material selection over structural grade alone.
- US Pacific Northwest code liberalization:Oregon and Washington state amendments to the International Building Code are testing taller mass timber prototypes that could unlock mid-rise residential verticals.
Industry Challenges
- Certification timeline compression:CE marking and US ICC-ES evaluation report cycles for new adhesive formulations or species combinations extend product commercialization windows.
- Kiln-drying capacity constraints:Dimensional stability requirements for 24–30 MPa structural grades demand controlled moisture-content lumber that saturates available thermal-processing infrastructure.
- Fire-resistance rating validation:Encapsulated mass timber assemblies require large-scale furnace testing that strains third-party laboratory throughput and extends project permitting schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glue-Laminated Timber Market |
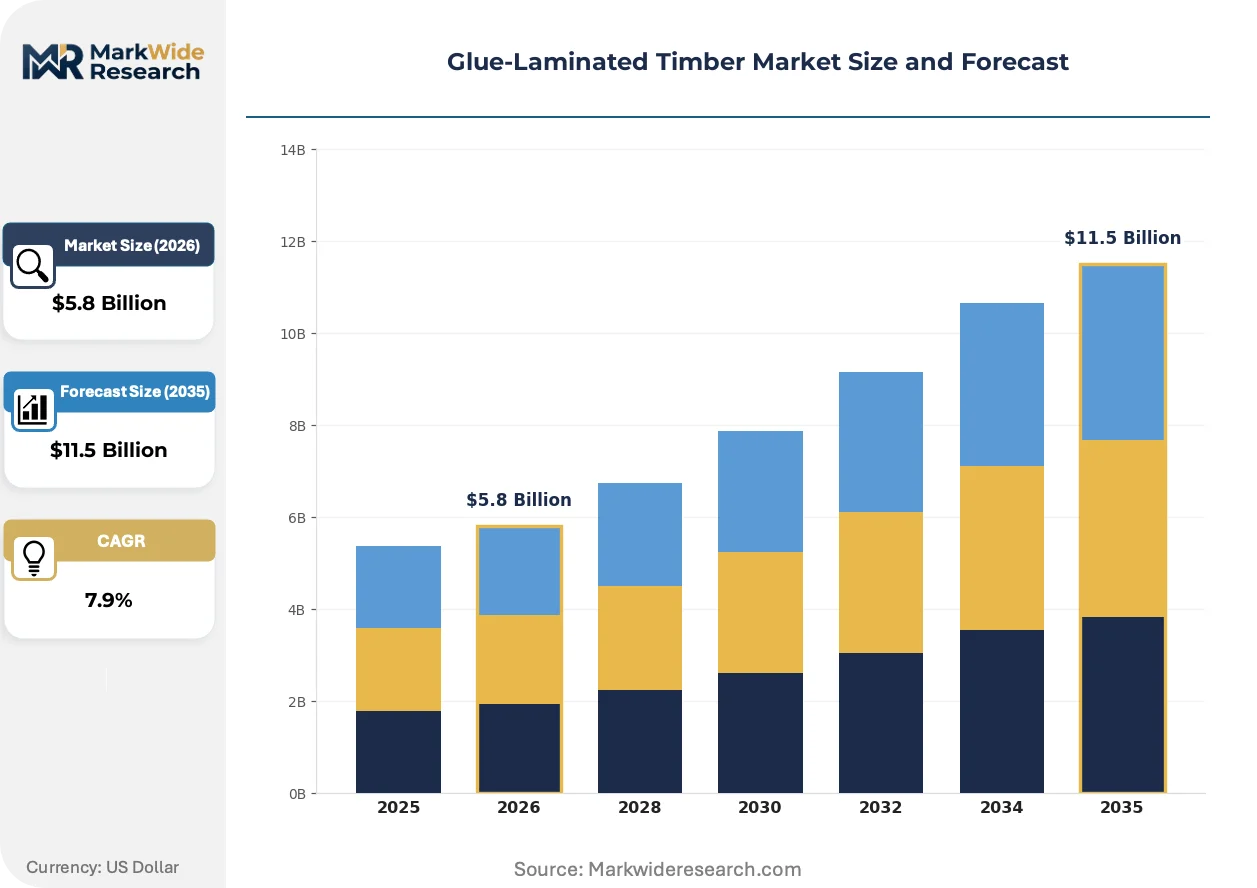
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Glulam, Architectural Glulam, Custom Glulam, LVL Application: Building Construction, Bridge Construction, Wood Manufacturing, Furniture Production End User: Contractors, Architects, Engineers, Manufacturers Alloy Type: Softwood, Hardwood, Composite, Reclaimed |
| Companies Covered | Structurlam Mass Timber Corporation, Binderholz GmbH, Canfor Corporation, Metsä Wood, Boise Cascade Company, Stora Enso Oyj, Setra Group AB, Mayr-Melnhof Holz Holding AG, Schilliger Holz AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glue-Laminated Timber Market Strategic Shifts & Innovations
Digital fabrication and automated adhesive application are compressing production cycle times for curved and tapered glulam members. These process innovations are enabling geometric complexity that was previously cost-prohibitive at scale.
Hybrid digital-twin modeling is expanding into structural engineering workflows for complex glulam assemblies. Engineering consultancies in Switzerland and Austria are adopting parametric design tools that optimize fiber orientation and lamella grading before CNC cutting. This technology is expanding into mid-rise commercial projects that previously defaulted to steel moment frames.
Europe's F-Gas Regulation is tightening restrictions on industrial refrigeration systems used in lumber kiln operations. Finnish and Swedish producers are retrofitting drying facilities with heat-pump recovery systems to maintain temperature control without hydrofluorocarbon refrigerants. The Nordic processing cluster is most affected, with capital reallocating toward thermal-efficiency upgrades ahead of 2027 phase-down deadlines.
Specification decisions are consolidating around embodied-carbon disclosure requirements. Institutional investors in German and Dutch real estate funds now mandate Environmental Product Declarations for structural materials, displacing informal supplier relationships with certified chain-of-custody documentation. This shift is most visible in Amsterdam and Frankfurt commercial development pipelines.
Glue-Laminated Timber Market Segmentation
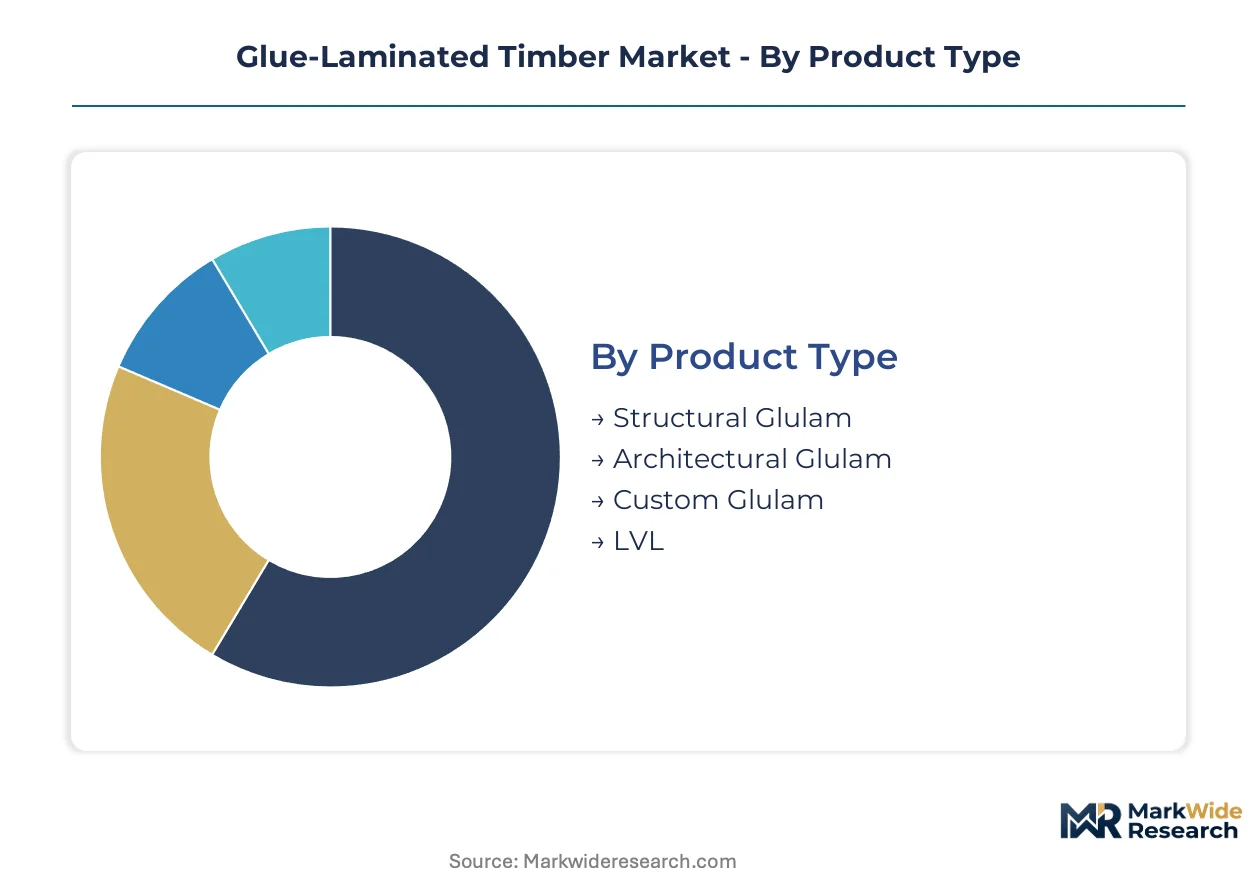
Segmentation in glue-laminated timber reveals how capital allocation, technical specifications, and procurement authority fragment across distinct value pools. Each dimension carries divergent margin profiles and certification burdens that reshape competitive positioning.
Product Type:
Capital intensity peaks in segments demanding specialized curing equipment and adhesive formulation R&D.
- Structural Glulam:Kiln-dried lumber boards bonded with moisture-resistant phenol-resorcinol formaldehyde achieve bending strengths of 24–30 MPa. Commercial high-rise construction in Austria and the Pacific Northwest United States specifies these members for load-bearing columns and beams under stricter carbon-accounting mandates. Most installed capacity flows through Structural Glulam. Expansion is steepest in Custom Glulam.
- Architectural Glulam:Visual-grade lamella selection governs exposed interior applications where aesthetic performance drives specification. Premium positioning in atriums and lobbies commands higher margins than structural grades alone.
- Custom Glulam:Project-specific curvature and hybrid steel-timber connections demand specialized fabrication capacity with extended lead times.
- LVL:Laminated veneer lumber serves parallel structural applications with uniform strength properties from thin veneer layups.
Structural grades dominate volume throughput. Architectural and custom variants capture disproportionate margin.
Application:
Demand concentration tracks building code liberalization and infrastructure renewal cycles.
- Building Construction:Encapsulated mass timber assemblies in mid-rise commercial and residential verticals exploit raised height allowances under Canada's National Building Code and the US International Building Code. Institutional investors in German and Dutch real estate funds now mandate Environmental Product Declarations for these structural systems.
- Bridge Construction:Prefabricated glulam deck systems serve pedestrian and light vehicular spans where high strength-to-weight ratios reduce foundation loads.
- Wood Manufacturing:Component feedstock for secondary engineered-wood products and millwork applications.
- Furniture Production:Curved and tapered members for high-end interior fixtures leveraging automated CNC fabrication.
Building construction absorbs the majority of production volume. Bridge applications are gaining share fastest where accelerated construction methods reduce traffic disruption.
End User:
Procurement authority determines specification control and price sensitivity.
- Contractors:Fast-track construction methods in Germany and Austria favor factory-delivered component systems that compress on-site assembly cycles and labor exposure.
- Architects:Visual-grade specification authority for exposed interior applications where aesthetic performance governs material selection independently of structural engineering.
- Engineers:Structural performance declarations under CE marking and US ICC-ES evaluation protocols constrain allowable stress grades and connection detailing.
- Manufacturers:Secondary processors of glulam into prefabricated building envelopes and hybrid assemblies.
Engineers and architects jointly control upstream specification. Contractors dominate procurement execution at volume.
Alloy Type:
Feedstock geography and certification chain-of-custody reshape supply security.
- Softwood:Nordic spruce and pine from Baltic and Scandinavian forest holdings anchor European production. Stora Enso and Metsä Wood processing infrastructure concentrates supply around this feedstock.
- Hardwood:Higher density species serve specialized applications requiring enhanced wear resistance or aesthetic grain patterns.
- Composite:Engineered combinations of species or recycled fiber content targeting specific performance-to-cost ratios.
- Reclaimed:Salvaged timber feedstocks meeting embodied-carbon disclosure requirements for institutional investors in Amsterdam and Frankfurt development pipelines.
Softwood commands installed capacity. Reclaimed and composite feedstocks are expanding most quickly under tightening sustainability disclosure mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting glulam production toward jurisdictions with lower embodied-carbon compliance costs. Austria, Canada, Germany, the United States, and Sweden concentrate the bulk of near-term capacity expansion as builders chase mass timber specifications.
Austria
Commercial high-rise developers in Vienna and Graz specify glulam columns to meet strict carbon-accounting thresholds for Class A office towers. The country's national building code aligns with CE marking requirements under Europe's Construction Products Regulation. Timber processing clusters in Upper Austria and Styria host prefabricated component factories serving German and Swiss export markets.
Canada
Encapsulated mass timber assemblies for mid-rise residential verticals exploit raised height allowances under the National Building Code. Health Canada and the Canadian Commission on Building and Fire Codes administer fire-resistance standards for Type IV construction. British Columbia's Pacific Northwest corridor anchors the densest concentration of glulam fabrication capacity serving Seattle and Portland project pipelines.
Germany
Institutional investors in Frankfurt and Amsterdam real estate funds mandate Environmental Product Declarations for structural materials in commercial developments. The Ecodesign for Sustainable Products Regulation tightens embodied-carbon thresholds that displace steel and concrete specifications. Bavarian and Baden-Württemberg manufacturing corridors supply factory-delivered glulam component systems for fast-track German and Austrian construction.
United States
Oregon and Washington state amendments to the International Building Code test taller mass timber prototypes for mid-rise residential expansion. The International Code Council governs fire-resistance ratings and height allowances that directly determine addressable building envelopes. Pacific Northwest metropolitan clusters from Seattle to Portland concentrate project development activity and fabrication capacity investment.
Sweden
Heat-pump recovery retrofits in lumber kiln operations respond to Europe's F-Gas Regulation phase-down deadlines for industrial refrigeration. Finnish and Swedish producers face concentrated pressure from 2027 refrigerant restrictions. Västra Götaland and Norrland processing regions anchor Nordic spruce supply chains feeding Central European glulam demand.
Glue-Laminated Timber Market Key Industry Players
Capacity expansion dominates the current landscape as producers scale kiln-drying and automated adhesive application infrastructure. Market structure tilts toward consolidated control among vertically integrated forest-products conglomerates with captive timber holdings. Three archetypes define competitive positioning: Nordic spruce-anchored processors, North American mass-timber specialists, and Central European prefabrication integrators. M&A activity and geographic expansion into code-liberalizing jurisdictions represent the dominant competitive moves reshaping supply allocation.
Within the Nordic processor archetype, Stora Enso Oyj and Metsä Wood exemplify scale-driven positioning around Baltic and Scandinavian forest holdings. Among Central European fabricators, Binderholz GmbH occupies a position reflecting vertical integration from forest management through engineered-wood finishing. Structurlam Mass Timber Corporation represents the North American specialist model focused on Pacific Northwest project pipelines and US-Canada cross-border specification flows.
| Leading Market Players |
|---|
| Structurlam Mass Timber Corporation |
| Binderholz GmbH |
| Canfor Corporation |
| Metsä Wood |
| Boise Cascade Company |
| Stora Enso Oyj |
| Setra Group AB |
| Mayr-Melnhof Holz Holding AG |
| Schilliger Holz AG |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between CE-marked structural members and commodity softwood beams manifests in both pricing premiums and supply chain routing decisions. Architectural-grade glulam commands substantial markups through controlled distribution channels serving atrium and lobby specifications, while standard structural grades flow through bulk procurement networks tied to commercial high-rise timelines in Austria and the Pacific Northwest.
Pricing Analysis
Distributor margins compress most severely at the commodity structural tier where phenol-resorcinol formaldehyde cost volatility feeds directly into landed pricing. Three-tier pricing structure across premium, standard, and economy levels separates visual-grade architectural specifications from structural grades and custom-curvature project work. Price differentiation hinges on CE marking tier and kiln-drying certification status. Pricing pressure stems from petrochemical adhesive feedstock swings. Contractors exhibit highest price sensitivity, while architects governing exposed interior specifications show minimal elasticity.
Supply Chain Analysis
Regional distribution centers in Upper Austria, British Columbia, and Västra Götaland anchor hub-and-spoke patterns feeding Central European and Pacific Northwest construction corridors. Supply concentrates in Austria, Canada, and Sweden where Nordic spruce and pine feedstock dominates. Raw material dependencies rest on phenol-resorcinol formaldehyde chemistry, kiln-dried lumber grades, and heat-pump recovery infrastructure. Single-source vulnerability concentrates around Baltic forest holdings. Distribution runs through prefabricated component factories serving fast-track German and Austrian assembly cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glue-laminated timber market functions as a stable compounder anchored by embodied-carbon disclosure mandates from institutional investors in German and Dutch real estate funds.
For Market Incumbents: Cement market position through captive spruce supply chains in Baltic and Scandinavian holdings against phenol-resorcinol formaldehyde cost volatility. Prioritize kiln-drying capacity expansion in Austria and Canada to capture commercial high-rise substitution demand. Defend specification control by deepening backward integration into forest management and automated adhesive application infrastructure. For New Entrants and Emerging Players: CE marking expansion under Europe's Construction Products Regulation opens a window for cross-border specification plays in German and Swiss export corridors. Target prefabricated building envelope segments in Austria where fast-track methods compress incumbent lead-time advantages. Pursue architectural-grade positioning through visual-grade lamella sourcing partnerships with Upper Austrian processors. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap fabricators controlling regional distribution networks and CE marking certification pathways. Long-term viability frames around 5-10 year carbon-accounting mandate expansion across European commercial real estate. Monitor Oregon and Washington state code amendments as inflection signals for North American mass timber height liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forest Holdings | Captive spruce supply from Baltic holdings insulates margin from Nordic concentration risk. |
| Kiln-Drying Capacity Expansion | Controlled moisture-content infrastructure locks in 24–30 MPa structural grade throughput for commercial high-rise. |
| Prefabricated Component Systems | Factory-delivered envelope assemblies compress on-site cycles for German and Austrian fast-track construction. |
| CE Marking Certification Investment | Structural performance declarations reduce specification friction for cross-border European project pipelines. |
| Heat-Pump Recovery Retrofit | F-Gas Regulation compliance in Swedish and Finnish drying facilities maintains temperature control without hydrofluorocarbon refrigerants. |
Research Approach
Multiple input streams — executive interviews with glulam fabricators, procurement manager surveys at German and Austrian contractors, and regulatory filing analysis — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged plant managers at Nordic spruce processors, structural engineers specifying mass timber assemblies, and distribution channel partners serving prefabricated building envelope markets. Secondary validation drew from CE marking databases, Canada's National Building Code amendment records, US International Code Council proceedings, and customs data tracking cross-border lumber flows.
Historical volume trajectories were cross-referenced against panel input from industry participants to anchor projections across the modeling period. Segmentation dimensions modeled include product type tier, application vertical, end-user procurement authority, and softwood feedstock geography. CAGRs were derived from installed capacity expansion announcements and commercial high-rise pipeline tracking. Forecast inputs incorporated embodied-carbon disclosure mandate adoption curves and building code height allowance liberalization timelines.
Revisions become necessary when petrochemical feedstock disruptions, F-Gas Regulation enforcement delays, or Pacific Northwest code amendment reversals materialize outside baseline assumptions. Forecasts reflect documented structural performance standards and regional regulatory trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Indonesia Ready-Mix Concrete Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Risers Market
Building & Construction Materials
US Prefabricated Steel Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Residential Non-metal Electrical Conduit Market
Building & Construction Materials
Railing Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
I-Joist Market
Building & Construction Materials
Global Aluminum Cladding Panels Market