
 Magnesium Oxide Boards Market | 2026-2036
Magnesium Oxide Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Magnesium Oxide Boards Market Intelligence
REACH compliance in Europe is consolidating the supplier base by raising the cost-of-entry for producers lacking certified supply chains. MagPanel leverages its captive magnesite sourcing to sustain margin stability under tightening chemical disclosure rules. GemtreeBoard Ltd. anchors its position through specialized fire-resistant formulations that dominate specification in Nordic passive-house projects. Hebei Optimum Construction Materials competes on manufacturing scale, operating one of the largest continuous MgO board lines serving Southeast Asian export markets.
Magnesium oxide boards are non-combustible building panels manufactured from magnesium oxide cement, reinforced with fiberglass mesh, typically offering fire ratings up to four hours and zero flame-spread indices. These panels serve as structural sheathing, interior wallboard, and tile backer in applications demanding moisture resistance, mold immunity, and dimensional stability under thermal cycling. Fire-resistant boards command the deepest specification pull in multi-family and institutional construction, while moisture-resistant grades are displacing traditional gypsum in coastal and flood-zone rebuilds. Specialty boards incorporating acoustic or thermal laminates occupy the highest margin tier but remain constrained by limited installer familiarity. Standard boards still dominate volume through wholesaler channels serving single-family and light commercial contractors.
The EPA regulates formaldehyde emissions from composite wood products in the United States, creating a specification tailwind for MgO boards as zero-emission substitutes in schools and healthcare facilities. China's GB standards for non-combustible building materials, enforced by MEE and local construction quality stations, mandate A-grade fire performance in buildings exceeding specified heights, directly privileging MgO board systems over organic alternatives. India's BIS certification requirements for cement-based panels are tightening test protocols for flexural strength and chloride content, filtering out marginal producers. Stakeholders must monitor how evolving carbon-accounting rules for embodied construction materials reshape procurement scoring in public infrastructure tenders.
Market Dynamics
Cladding fire-safety mandates following high-rise incidents are compressing specification timelines and privileging non-combustible MgO systems over organic alternatives in multi-family and institutional construction.
Growth Catalysts
- LEED and BREEAM certification thresholds:Green building programs in the United States and United Kingdom are embedding MgO boards into residential and commercial wall assemblies as low-carbon, zero-formaldehyde alternatives.
- China's GB A-grade fire performance mandates:MEE enforcement of non-combustible material requirements for buildings above specified heights directly advantages MgO board systems over plywood and OSB.
- Coastal flood-zone rebuild specifications:Moisture-resistant MgO grades are capturing specification share from traditional gypsum in hurricane and flood recovery projects across Florida and Gulf Coast states.
Market Restraints
- Magnesite ore supply concentration:Captive sourcing dominance by integrated producers in Liaoning Province and Quebec creates input cost volatility for non-integrated board manufacturers.
- REACH chemical disclosure compliance:ECHA registration requirements for magnesium oxide cement formulations raise cost-of-entry for producers lacking certified European supply chains.
- Installer familiarity gaps with specialty laminates:Acoustic and thermal laminated MgO boards face adoption friction due to limited contractor training and specification inertia.
Strategic Opportunities
- India's cement-based panel certification tightening:BIS flexural strength and chloride content protocol revisions are filtering marginal producers, creating consolidation openings for quality-compliant suppliers.
- Carbon-accounting procurement scoring:Evolving embodied carbon rules for public infrastructure tenders in Germany and France are reshaping material selection criteria toward low-emission MgO systems.
- Passive-house construction clusters:Nordic energy-efficient building standards are driving specification of fire-resistant MgO formulations in Denmark, Sweden, and Finland.
Industry Challenges
- Continuous production line capex intensity:Large-scale automated MgO board manufacturing requires substantial capital deployment for kiln and pressing equipment, constraining mid-scale market entry.
- Multi-jurisdiction certification timelines:Securing concurrent EPA, BIS, and GB standard compliance for export-oriented producers extends product launch cycles and raises compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Magnesium Oxide Boards Market |
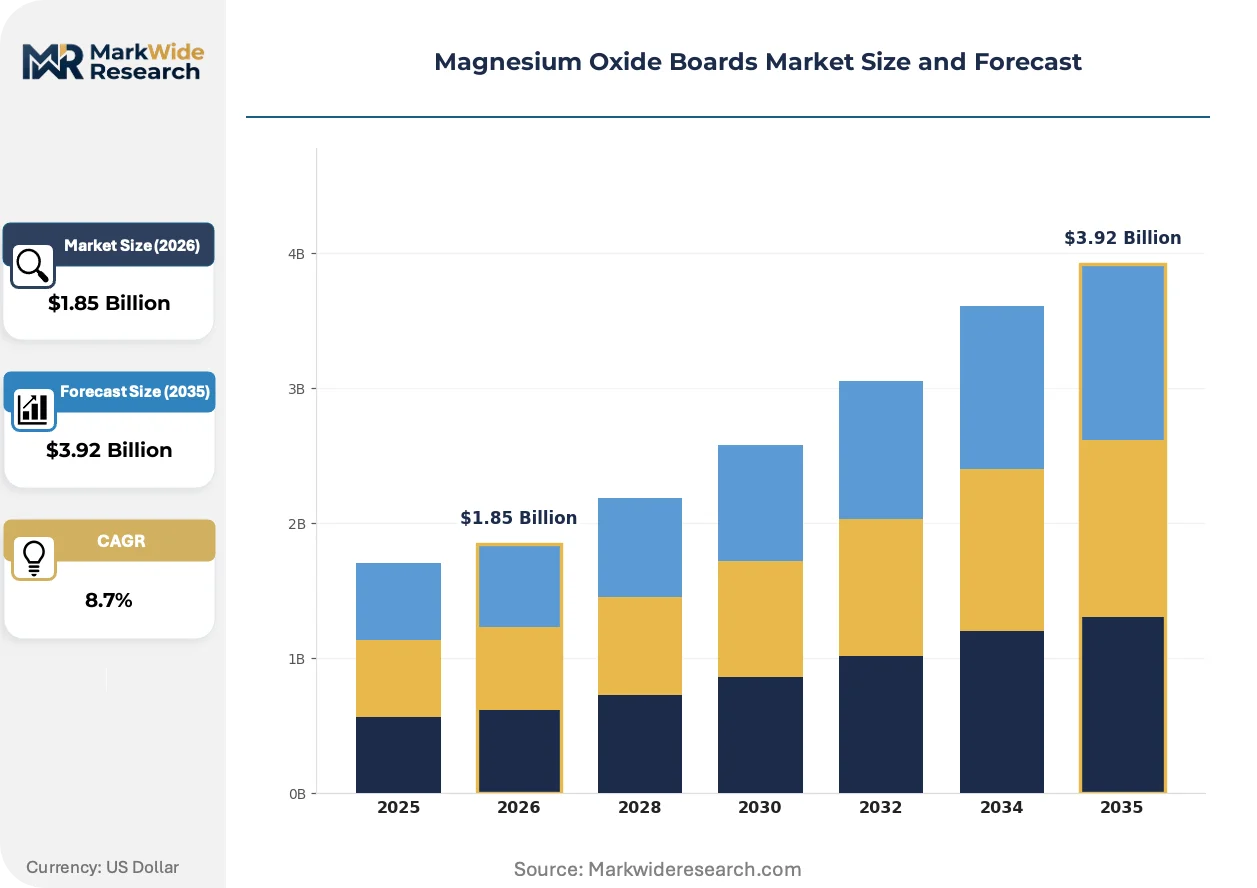
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Boards, Fire-Resistant Boards, Specialty Boards, Moisture-Resistant Boards End Use: Construction, Interior Design, Industrial Applications, Green Building Distribution Channel: Direct Sales, Retail, Online Sales, Wholesalers Thickness: Thin, Medium, Thick, Ultra-Thick |
| Companies Covered | MagPanel, GemtreeBoard Ltd., Sulfycor, Hebei Optimum Construction Materials, Trusus Building, DragonBoard, US MgO, BULU, MagBoard LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Magnesium Oxide Boards Market Strategic Shifts & Innovations
Product formulation advances and regulatory tightening are converging to elevate MgO boards from niche specification to mainstream structural sheathing in fire-critical and moisture-exposed applications.
Glass-fiber mesh reinforcement technology is integrating with modified magnesium oxide cement chemistries to produce thinner, lighter panels maintaining four-hour fire ratings. Multi-family developers in California and Texas are specifying these reduced-weight boards to cut structural steel requirements. The technology is integrating seismic and wind-load performance into a single panel system, compressing material layers in mid-rise construction.
REACH chemical disclosure requirements in Europe are forcing reformulation of traditional MgO cement additives to eliminate classified hazardous substances. ECHA enforcement is accelerating substitution of legacy chloride-based accelerators with sulfate-modified alternatives. Nordic passive-house projects are responding fastest, driving demand for certified clean-formulation boards in Sweden and Denmark.
Specification decisions are migrating from contractor-driven wholesaler channels to architect- and engineer-led design-build procurement. Fire-resistant MgO grades are displacing gypsum in school and healthcare construction through direct engagement with specifying engineers. This pattern is most visible in Germany and the United Kingdom, where public tender documentation now mandates non-combustible substrate disclosure.
Magnesium Oxide Boards Market Segmentation
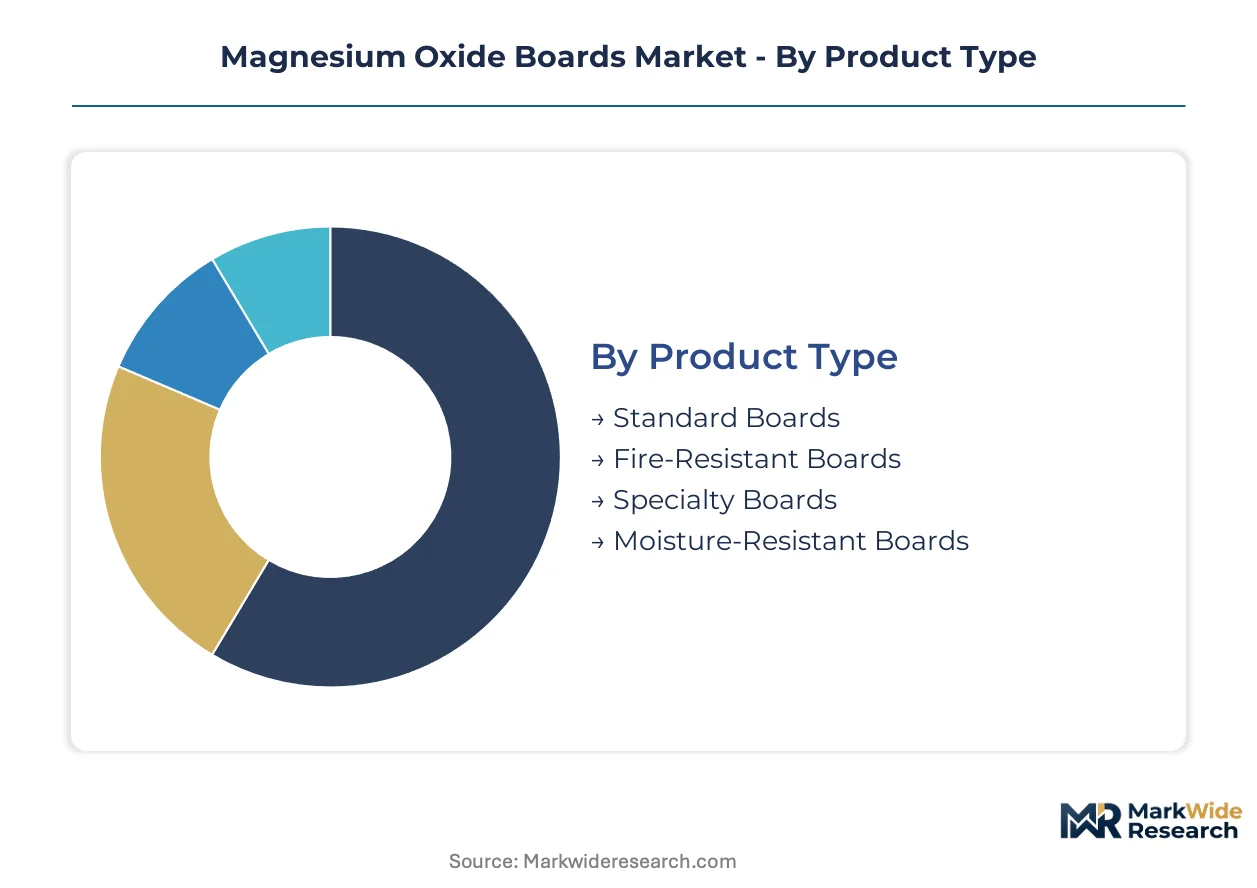
MgO board purchasing decisions pivot on fire-code compliance, moisture exposure risk, and installation labor economics. Specification patterns diverge sharply between multi-family developers seeking A-grade fire ratings and residential contractors prioritizing cost-per-square-foot.
Product Type:
Upgrade cycles from legacy gypsum and plywood substrates are accelerating as building codes tighten, with replacement demand concentrated in high-rise and coastal construction.
- Fire-Resistant Boards:Reinforced with fiberglass mesh and modified magnesium oxide cement, these panels achieve four-hour fire ratings and zero flame-spread indices. Demand concentrates in multi-family residential towers across Germany and China, where GB A-grade and EN 13501-1 mandates now prohibit organic cladding alternatives.
- Moisture-Resistant Boards:Hydrophobic surface treatments and dense cement matrices resist mold colonization and dimensional swelling. Florida and Gulf Coast rebuild specifications following hurricane damage are displacing traditional gypsum with these grades in flood-zone residential construction.
- Standard Boards:Unmodified MgO cement formulations serve as structural sheathing and interior wallboard in single-family construction where fire ratings below two hours suffice.
- Specialty Boards:Acoustic and thermal laminate configurations target passive-house and healthcare applications, constrained by limited installer training and premium pricing.
Fire-Resistant Boards sit at the top of the volume ranking, with Moisture-Resistant Boards climbing the fastest.
End Use:
Cost-tier segmentation separates specification-driven institutional projects from price-sensitive residential retrofits.
- Construction:Structural sheathing, subflooring, and exterior cladding in mid-rise and high-rise buildings. China's MEE enforcement of non-combustible material mandates above specified building heights privileges MgO systems over plywood and OSB in Shanghai and Shenzhen developments.
- Green Building:LEED and BREEAM certification pathways specify zero-formaldehyde, low-embodied-carbon panels for wall assemblies. Nordic passive-house clusters in Denmark and Sweden drive specification of clean-formulation boards with ECHA-compliant additive packages.
- Interior Design:Tile backer and decorative wallboard applications in residential bathrooms and kitchens where moisture immunity outweighs fire rating requirements.
- Industrial Applications:Equipment enclosures, cleanroom partitions, and chemical-resistant flooring in pharmaceutical and food processing facilities.
Construction commands the largest revenue share, with Green Building expanding most quickly.
Distribution Channel:
Volume flows through divergent pathways depending on project scale and specification complexity.
- Wholesalers:Bulk procurement channels serving single-family and light commercial contractors through regional building supply networks. These intermediaries dominate standard board movement in North American residential construction.
- Direct Sales:Manufacturer-to-developer relationships for large multi-family and institutional projects requiring certified fire-performance documentation and batch traceability.
- Retail:Big-box and specialty building material stores targeting DIY renovators and small residential contractors.
- Online Sales:E-commerce platforms gaining traction for specialty and thin-profile boards in remote or undersupplied geographies.
Wholesalers handle the greatest transaction volume, while Direct Sales delivers the steepest expansion trajectory.
Thickness:
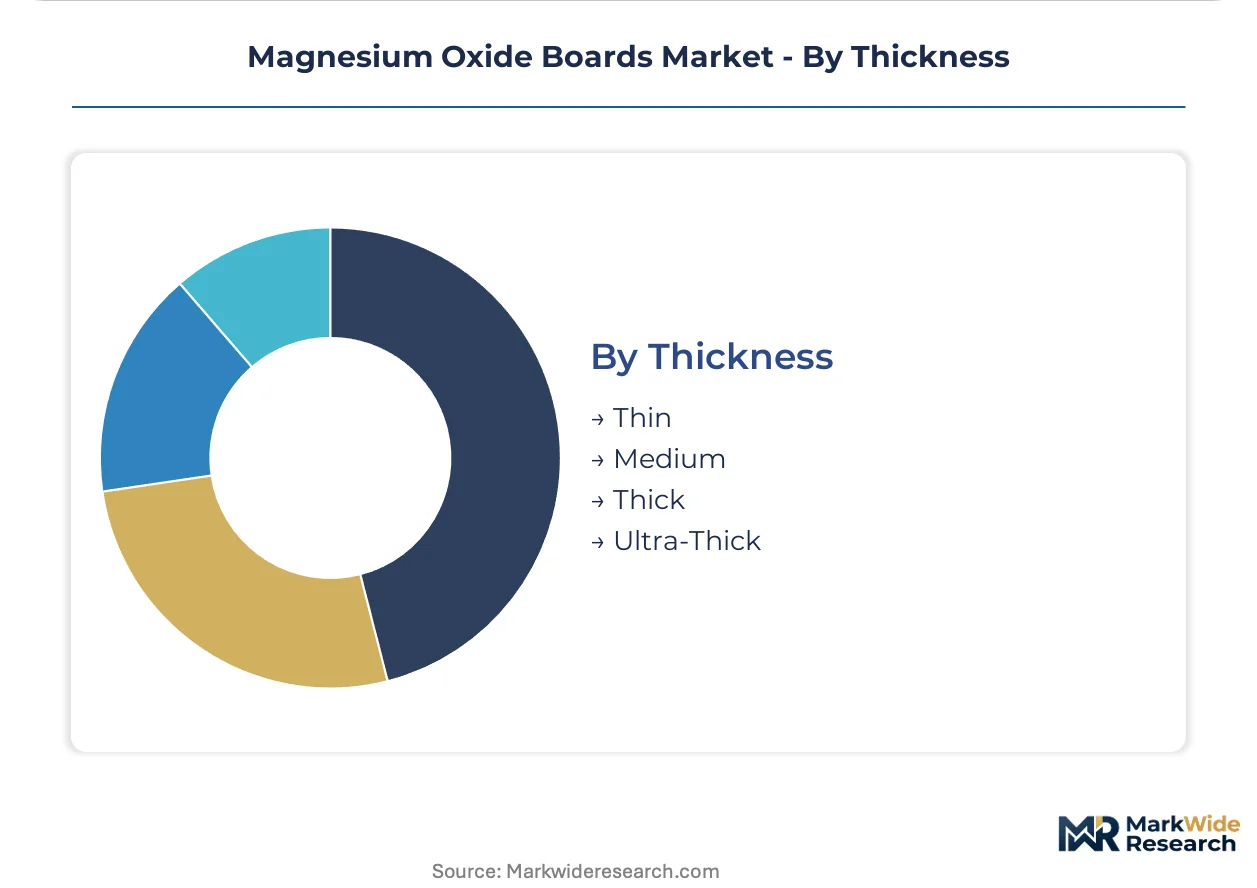
Application requirements and structural load calculations determine panel gauge selection across project types.
- Medium:8-12mm panels balancing fire rating performance with manageable weight for two-person installation crews. These specifications dominate interior wallboard and tile backer applications in residential and commercial construction.
- Thick:15-20mm configurations providing structural sheathing and subflooring for mid-rise buildings. California and Texas developers specify reduced-weight thick panels to cut structural steel requirements in seismic zones.
- Thin:3-6mm boards for overlay applications, curved surface forming, and furniture manufacturing where flexibility and low mass predominate.
- Ultra-Thick:25mm+ panels for blast-resistant and high-load industrial flooring in data centers and heavy manufacturing.
Medium thickness leads unit shipments, with Thick panels gaining share fastest in multi-family vertical construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized construction materials expertise clusters in Germany, China, and the United States, with regulatory enforcement capacity determining where specification-grade MgO board production concentrates.
China
Shanghai and Shenzhen developers face MEE enforcement of GB A-grade fire performance mandates for buildings exceeding specified heights. The Liaoning Province magnesite belt supplies captive ore to integrated board manufacturers. Qingdao and Dalian industrial zones host continuous production lines serving Southeast Asian export markets.
Germany
Passive-house construction clusters in Bavaria and Baden-Württemberg specify ECHA-compliant clean-formulation boards. The KBA and federal building codes privilege non-combustible substrates in multi-family towers. Hamburg and Berlin specification engineers now mandate embodied carbon disclosure in public tender documentation.
United States
Florida and Gulf Coast contractors specify moisture-resistant grades for flood-zone residential rebuilds following hurricane damage. EPA formaldehyde emission rules for schools and healthcare facilities create specification tailwinds. California and Texas developers deploy reduced-weight thick panels to cut structural steel requirements in seismic zones.
India
Maharashtra and Gujarat construction markets respond to BIS certification tightening for cement-based panels. BIS flexural strength and chloride content protocol revisions filter marginal producers. Mumbai and Ahmedabad developers specify fire-resistant grades for high-rise residential towers.
Sweden
Nordic passive-house standards in Stockholm and Malmö construction markets drive clean-formulation board specification. REACH chemical disclosure requirements accelerate substitution of legacy chloride-based accelerators. Gothenburg industrial zones host specialized laminators serving healthcare and acoustic applications.
Magnesium Oxide Boards Market Key Industry Players
The competitive structure tilts toward integrated magnesite processors with captive ore supply. Board manufacturing fragments between scale-driven continuous-line operators and specialized formulation developers. Three archetypes dominate: Liaoning-based integrated miners, European clean-formulation specialists, and North American moisture-resistant grade developers. Capacity expansion and REACH-compliant additive substitution represent the dominant competitive vectors.
Among integrated producers with captive magnesite sourcing, MagPanel and Hebei Optimum Construction Materials exemplify the scale-driven archetype. GemtreeBoard Ltd. occupies a position within the European specialist tier, representing clean-formulation capabilities for Nordic passive-house markets. US MgO anchors North American geographic positioning for moisture-resistant specification segments.
| Leading Market Players |
|---|
| MagPanel |
| GemtreeBoard Ltd. |
| Sulfycor |
| Hebei Optimum Construction Materials |
| Trusus Building |
| DragonBoard |
| US MgO |
| BULU |
| MagBoard LLC |
| Others |
Cost & Logistics Intelligence
Multi-family developers in China and Germany concentrate procurement volume for fire-resistant grades, anchoring contract-based pricing that privileges certified suppliers over spot-market alternatives. This buyer concentration reinforces tiered pricing stratification across certification levels.
Pricing Analysis
Project-based pricing dominates large multi-family and institutional contracts, separating ECHA-compliant clean-formulation boards from standard grades through certification premiums. Price differentiation hinges on GB A-grade fire ratings and REACH additive compliance. Cost compression in standard grades intensifies as Liaoning-integrated producers expand continuous-line capacity. Single-family contractors exhibit highest price sensitivity, while Nordic passive-house developers accept premiums for documented embodied-carbon performance.
Supply Chain Analysis
Freight costs from Liaoning Province to Southeast Asian export markets constrain margin structures for non-integrated manufacturers lacking coastal production assets. Captive magnesite sourcing draws from China, Russia, and Turkey, with chloride-based accelerator chemistry resting on sulfur and magnesium feedstock availability. Single-source vulnerability concentrates in Liaoning's magnesite belt. Distribution runs through regional building supply wholesalers serving contractor channels in North America and direct sales for certified projects in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratcheting, with China's MEE enforcement of GB A-grade mandates creating irreversible specification shifts in high-rise construction.
For Market Incumbents: Deploy captive ore sourcing as the primary lever to compress input volatility against non-integrated competitors. Secure concurrent EPA, BIS, and GB standard compliance to extend product launch cycles into defensive moats. Add continuous-line capacity in coastal China to capture Southeast Asian export growth. Threat: REACH-compliant additive substitution raises R&D overhead for legacy chloride formulations. For New Entrants and Emerging Players: Coastal flood-zone contractors in Florida and Gulf Coast states represent the most penetrable buyer archetype, with moisture-resistant grades displacing gypsum in hurricane rebuild specifications. Target BIS certification gaps in India as Maharashtra and Gujarat tighten flexural strength protocols. Pursue direct sales relationships with public school districts leveraging EPA formaldehyde rules. For Investors and Strategic Acquirers: Building materials conglomerates seeking fire-safety portfolio exposure are the most active acquirer in this space, particularly those lacking non-combustible substrate capabilities. Five-to-ten year viability rests on carbon-accounting integration into public infrastructure procurement. Acquisition targets: European clean-formulation specialists with ECHA-registered supply chains. Signal to monitor: embodied carbon disclosure mandates in German and French tender documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesite Mining | Captive ore supply from Liaoning or Quebec insulates margin stability against input volatility. |
| REACH-Compliant Additive Reformulation | ECHA-registered sulfate-modified chemistry opens Nordic passive-house specification channels. |
| Continuous Production Line Scale-Up | Automated kiln and pressing equipment in Qingdao or Dalian captures Southeast Asian export demand. |
| Multi-Jurisdiction Certification Investment | Concurrent EPA, BIS, and GB compliance compresses competitor launch timelines in institutional segments. |
| Carbon Accounting Documentation Development | Embodied carbon scoring alignment with German federal tender requirements reshapes procurement criteria. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at continuous-line facilities, procurement leads at multi-family developers, specification engineers in Germany and Sweden, and distribution channel partners in North American building supply networks. Secondary validation drew from MEE enforcement notices, ECHA registration databases, BIS certification protocols, and SEC filings of integrated building materials producers. Bottom-up shipment modeling and top-down construction spend analysis triangulated volume estimates.
Historical reference periods anchored the projection framework to pre- and post-pandemic construction cycles, with segmentation modeling across fire rating tier, moisture resistance specification, thickness gauge, and end-use vertical. CAGRs derived from regression analysis against construction permit flows and regulatory enforcement intensity. Industry-specific inputs included GB standard revision timelines and LEED certification adoption curves.
Underlying measurement precision varies by segment; fire-resistant boards carry tighter precision than specialty laminates given standardized test protocols. Forecasts reflect assumptions about MEE enforcement consistency and REACH implementation timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
US Plywood Market
Building & Construction Materials
Gulf Corporation Council Cement Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Plumbing Fixtures and Fittings Manufacturing Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
India Stainless Steel Plumbing Pipes and Fittings Market
Building & Construction Materials
Point Supported Glass Curtain Wall Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
North America Oriented Strand Board Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
India Luxury Vinyl Tile (LVT) Market