
 UPVC Doors and Windows Market | 2026-2036
UPVC Doors and Windows Market Size, Share, and Industry Trends Forecast 2026-2036
UPVC Doors and Windows Market Analysis
CE marking under the Construction Products Regulation is rotating as the primary gatekeeper for market access across European member states. Deceuninck leverages its compound extrusion capabilities to supply certified profile systems to fabricators in multiple jurisdictions. VEKA AG anchors its position through backward integration into PVC resin sourcing and tight quality control over its German manufacturing base. Koemmerling differentiates via specialized formulations for coastal and high-humidity climates where salt degradation tests exceed standard requirements.
UPVC doors and windows are unplasticized polyvinyl chloride framing systems manufactured through co-extrusion of rigid PVC with multi-chamber hollow profiles, typically reinforced with galvanized steel inserts and glazed with double or triple sealed units to achieve U-values below 1.0 W/m²K. These assemblies serve commercial and residential buildings by delivering thermal insulation, acoustic dampening, and minimal maintenance across multi-decade service lives. Casement windows and tilt-and-turn windows occupy the core of replacement demand where homeowners prioritize ventilation control and cleaning access in mid-rise structures. New construction installations compete most intensely on project-scale pricing, while thermal break frames command premium positioning in passive house and near-zero-energy building specifications where fabricators seek margin protection.
EMA's oversight of plasticizer migration in medical-adjacent buildings and REACH restrictions on lead-based stabilizers are forcing reformulation toward calcium-zinc and organic tin alternatives across the supply chain. The EU F-Gas Regulation indirectly shapes demand by restricting refrigerant-based climate control, pushing architects toward high-performance envelope solutions including UPVC glazing systems. Germany's KBA building energy codes and France's RE2020 environmental regulations are tightening U-value mandates that only multi-chamber UPVC frames with warm-edge spacers can satisfy cost-effectively. Stakeholders must monitor whether the EU AI Act's eventual extension into building automation creates certification requirements for smart-window-integrated sensor modules that current frame manufacturers lack competency to validate.
Market Dynamics
REACH restrictions on lead-based stabilizers and tightening EU Green Deal building renovation targets are forcing systemic reformulation across the UPVC value chain, compressing margins for non-compliant fabricators while rewarding certified profile suppliers.
Growth Catalysts
- EU Green Deal renovation mandates:France's social housing retrofit programs and Germany's KBA building energy codes are accelerating frame replacement cycles in existing building stock.
- Passive house certification expansion:The Benelux region's near-zero-energy building specifications are absorbing premium multi-chamber profiles with U-values below 1.0 W/m²K.
- Tilt-and-turn ventilation control:Residential builders in Poland and Germany are specifying these systems for thermal performance compliance in mid-rise construction.
Market Restraints
- PVC resin price volatility:Feedstock ethylene fluctuations tied to naphtha cracking economics compress fabricator margins during contract renegotiations.
- Substitution pressure from aluminum-wood composites:High-end residential segments in Austria and Switzerland are specifying these alternatives for aesthetic differentiation.
- REACH compliance timeline friction:Calcium-zinc stabilizer migration testing delays product recertification cycles by 8-14 months.
Strategic Opportunities
- Coastal climate specialization:Salt degradation-resistant formulations for high-humidity markets in Portugal and Ireland exceed standard EN 12608 requirements.
- Warm-edge spacer integration:Convergence of UPVC extrusion with TGI-Spacer or Swisspacer technology enables single-source supply for passive house fabricators.
- Social housing procurement consolidation:France's regional housing authorities are bundling window replacement into multi-year maintenance contracts.
Industry Challenges
- Compound formulation expertise scarcity:Calcium-zinc and organic tin stabilizer chemistry requires retraining legacy lead-stabilizer technicians.
- CE marking documentation burden:Construction Products Regulation test data compilation stretches smaller fabricators' technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UPVC Doors and Windows Market |
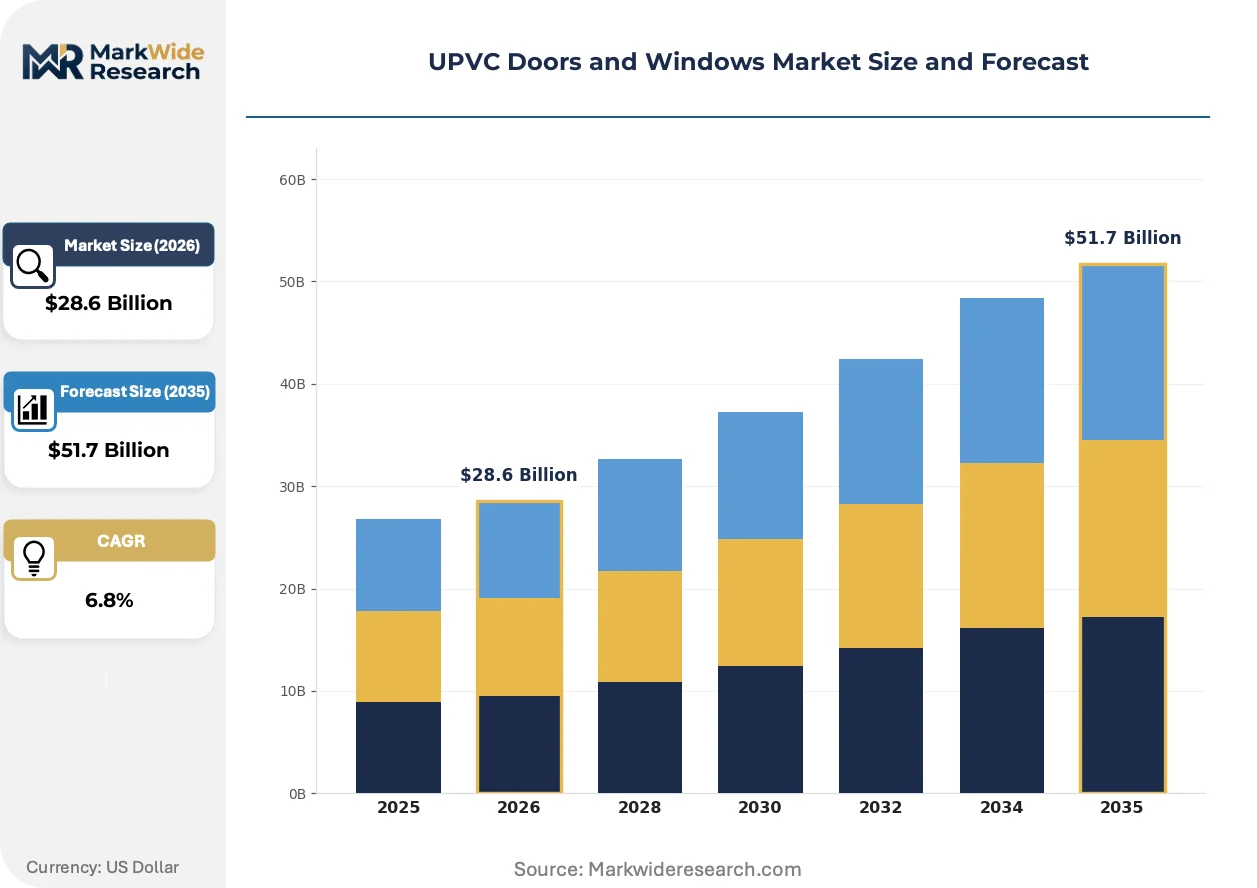
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casement Windows, Sliding Doors, Tilt and Turn Windows, French Windows Installation Type: New Construction, Replacement, Renovation, Retrofitting End User: Residential, Commercial, Industrial, Institutional Frame Design: Standard Frames, Custom Frames, Thermal Break Frames, Laminated Frames |
| Companies Covered | Andersen Corporation, Deceuninck, VEKA AG, LG Hausys, Aluplast, Rehau Group, Pella Corporation, Koemmerling, JELD-WEN Holding Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UPVC Doors and Windows Market Emerging Trajectories
Thermal performance thresholds are hardening faster than cost curves can absorb, forcing material science and manufacturing process innovation to outpace incremental efficiency gains.
Co-extruded multi-chamber hollow profiles with integrated thermal breaks are displacing standard three-chamber designs in German and Austrian new construction. Passive house certifiers specify these assemblies for projects targeting U-values of 0.85 W/m²K or lower. The technology is displacing conventional profile systems in premium residential segments where energy balance calculations determine mortgage eligibility.
EMA oversight of plasticizer migration in medical-adjacent buildings is extending REACH reformulation requirements beyond residential applications. Hospital and care facility procurement specifications now exclude legacy lead-stabilized frames from tender eligibility. German fabricators serving the healthcare vertical have accelerated calcium-zinc transition timelines by 18-24 months to maintain specification status.
Social housing authorities in France and the Netherlands are consolidating window replacement procurement into decade-scale energy performance contracts. These arrangements transfer technical specification authority from individual maintenance managers to centralized technical departments. The shift is most visible in France's Hauts-de-France and Île-de-France regions, where regional housing agencies bundle 5,000-15,000 unit replacement programs.
UPVC Doors and Windows Market Segmentation
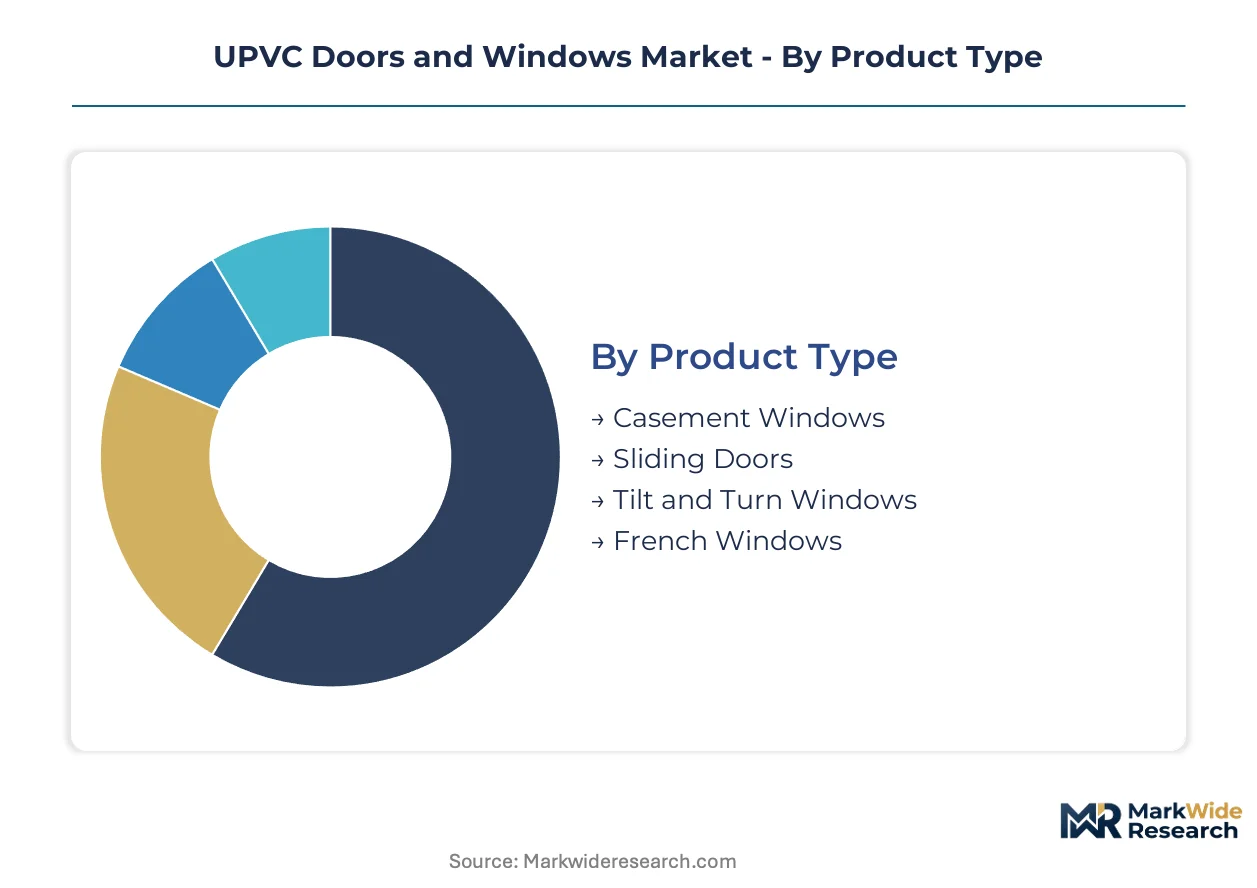
UPVC door and window manufacturers configure product portfolios across four intersecting dimensions. Each segmentation axis carries distinct margin profiles, certification requirements, and channel access rules that determine competitive positioning.
Product Type:
Margin pools concentrate in systems delivering both thermal performance and ventilation flexibility, where fabricators command specification premiums.
- Casement Windows:Side-hinged sashes with multi-point locking hardware and compression seals achieve U-values below 1.2 W/m²K in standard configurations. German residential retrofits absorb the highest volumes as KBA energy codes tighten replacement specifications.
- Tilt and Turn Windows:Dual-axis hardware enables both hopper ventilation and full inward opening for cleaning access. Polish and German mid-rise builders specify these systems for thermal compliance without sacrificing operability.
- Sliding Doors:Multi-track systems with tandem rollers support glazed panels up to 400kg for terrace access applications.
- French Windows:Center-mullion paired sashes with traditional sightlines serve heritage-sensitive renovations in France and Belgium.
The dominant share belongs to Casement Windows, while Tilt and Turn Windows is closing the gap fastest.
Installation Type:
Volume concentration varies sharply between project-scale new construction and fragmented replacement demand.
- Replacement:Existing stock upgrades in Germany and France account for the majority of unit volume, driven by Green Deal renovation targets and social housing retrofit programs. Lead times compress as regional fabricators maintain inventory of standard profile sizes.
- New Construction:Project-scale procurement in Poland and Benelux passive house developments rewards certified suppliers with multi-year framework agreements. Bulk pricing pressure squeezes margins unless warm-edge spacer integration differentiates the offering.
- Renovation:Partial envelope upgrades in older buildings require custom sizing and temporary weather protection coordination.
- Retrofitting:Secondary glazing additions to listed structures demand slimline profiles and specialized fixing systems.
Replacement captures the largest volume base, though New Construction delivers superior margin stability through contract duration.
End User:
Specification authority and procurement concentration diverge significantly across building use categories.
- Residential:Single-family and multi-family housing dominates unit demand, with homeowners prioritizing acoustic dampening and maintenance reduction. France's social housing agencies bundle window replacement into decade-scale energy performance contracts.
- Commercial:Office and retail specifications emphasize daylight optimization and HVAC load reduction. EMA plasticizer migration restrictions now extend to medical-adjacent commercial buildings.
- Industrial:Factory and warehouse applications prioritize durability over thermal performance, accepting higher U-values for cost containment.
- Institutional:School and hospital procurement follows extended tender cycles with extended warranty requirements.
Residential holds the installed base majority, with Commercial expanding most quickly on regulatory energy mandates.
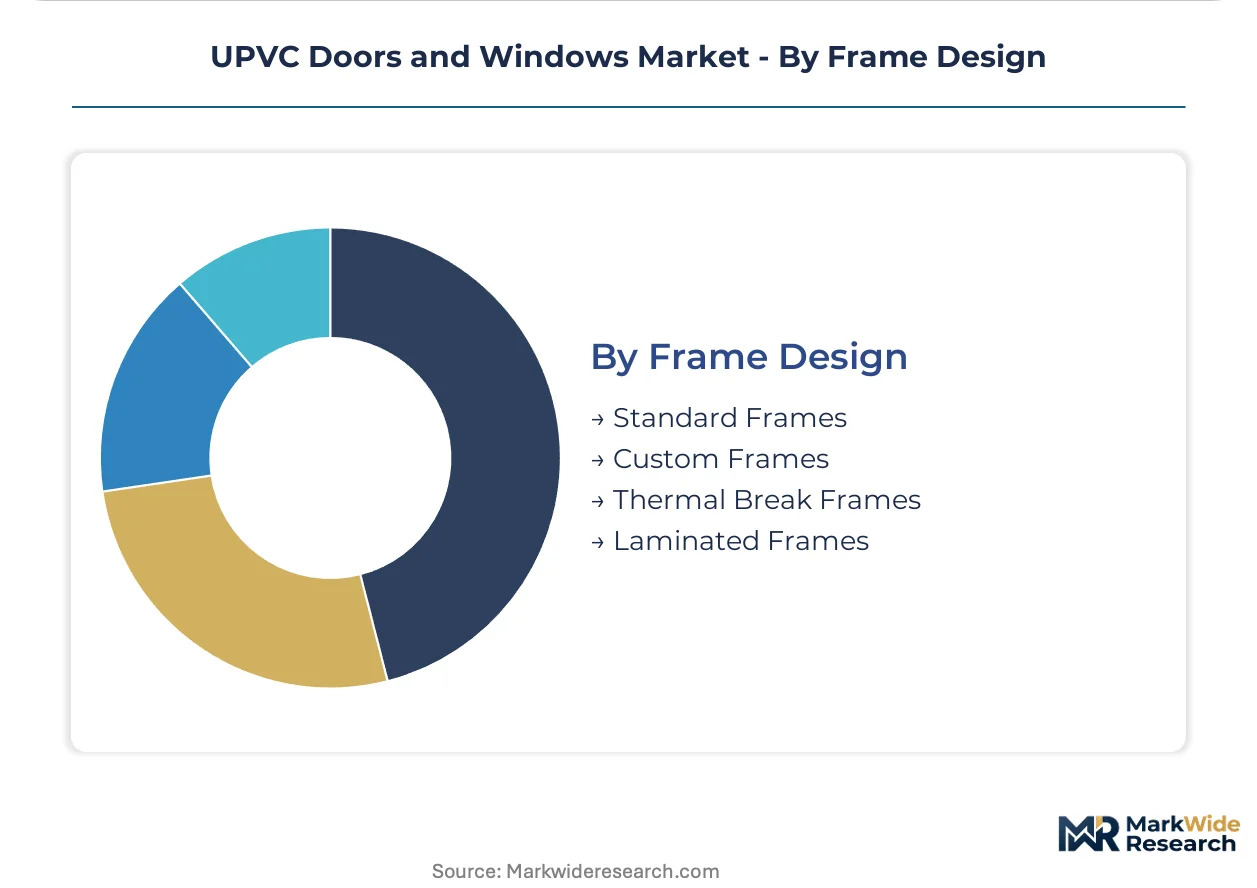
Frame Design:
Technology tiering separates commodity supply from premium positioning in certified building programs.
- Thermal Break Frames:Polyamide strips or glass-reinforced nylon bridges interrupt conductive paths through multi-chamber profiles, enabling U-values below 0.85 W/m²K. Passive house certifiers in Austria and Germany specify these assemblies for mortgage-eligible near-zero-energy projects.
- Standard Frames:Three-chamber extrusions with galvanized steel reinforcement serve cost-sensitive replacement markets. Calcium-zinc stabilizer reformulation is migrating through this segment fastest due to REACH compliance deadlines.
- Custom Frames:Non-standard dimensions and color matching for heritage or architect-specified projects.
- Laminated Frames:Wood-veneer or aluminum-clad exterior surfaces for aesthetic differentiation in high-end residential.
Thermal Break Frames commands the premium tier, while Standard Frames maintains volume leadership in replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Social housing authorities and passive house developers concentrate procurement power in Northern and Western Europe, while Central European builders absorb volume for thermal compliance in mid-rise residential construction.
Germany
KBA building energy codes tighten U-value mandates for replacement windows in existing stock. REACH compliance deadlines accelerate calcium-zinc stabilizer migration across fabricator supply chains. The Rhine-Ruhr metropolitan region hosts clustered extrusion operations serving renovation contractors in North Rhine-Westphalia.
France
Regional housing agencies bundle 5,000-15,000 unit replacement programs into decade-scale energy performance contracts. RE2020 environmental regulations tighten envelope specifications for new residential construction. The Hauts-de-France and Île-de-France regions concentrate social housing retrofit procurement authority.
Poland
Mid-rise residential builders specify tilt-and-turn systems for thermal performance compliance without sacrificing operability. EU Green Deal renovation targets accelerate frame replacement cycles in post-1989 building stock. Warsaw and Kraków construction clusters absorb premium multi-chamber profiles for certified developments.
Netherlands
Passive house certifiers specify thermal break frames with U-values below 0.85 W/m²K for mortgage-eligible near-zero-energy projects. The Benelux region's building codes outpace standard EN requirements for glazing assemblies. Eindhoven and Rotterdam fabrication hubs integrate warm-edge spacer technology for single-source supply.
Belgium
French window configurations serve heritage-sensitive renovations in Flanders and Wallonia where traditional sightlines constrain specification options. CE marking under the Construction Products Regulation gates market access for imported profile systems. The Brussels-Capital region concentrates institutional procurement for school and hospital window replacement tenders.
UPVC Doors and Windows Market Vendor Landscape
Player mix skews toward integrated profile extruders with captive compound formulation capabilities and regional fabricators dependent on certified system supply. Market structure concentrates around three to five vertically integrated suppliers controlling resin sourcing and multi-jurisdiction certification. Strategic archetypes separate compound specialists, system licensors, and scale fabricators. Dominant competitive moves include backward integration into PVC resin sourcing and geographic expansion through certified fabricator networks.
Among European-integrated profile suppliers, Deceuninck, VEKA AG, and Koemmerling occupy positions defined by compound extrusion depth and climate-specialized formulation expertise. Deceuninck exemplifies the multi-jurisdiction system licensor archetype. VEKA AG anchors the backward-integrated manufacturer tier through captive resin sourcing. Koemmerling represents coastal climate specialization where salt degradation resistance exceeds baseline certification requirements.
| Leading Market Players |
|---|
| Andersen Corporation |
| Deceuninck |
| VEKA AG |
| LG Hausys |
| Aluplast |
| Rehau Group |
| Pella Corporation |
| Koemmerling |
| JELD-WEN Holding Inc. |
| Others |
Supply Flow & Price Mechanics
CE marking under the Construction Products Regulation gates both supply qualification and price differentiation simultaneously, forcing fabricators to absorb certification costs while certified profile suppliers capture premium positioning in social housing tenders.
Pricing Analysis
Cost-plus contracts with naphtha-indexed PVC resin clauses dominate fabricator-procurement relationships, passing ethylene volatility through to project pricing while compressing margins during renegotiation cycles. Three-tier pricing structure across thermal break, multi-chamber standard, and economy-grade profiles reflects certification grade and volume scale differentiation. Cost compression in standard-frame replacement markets is intensifying because calcium-zinc reformulation adds 8-12% compound cost without commensurate price recovery. Social housing procurement authorities exhibit highest price sensitivity, while passive house developers accept premiums for U-value performance.
Supply Chain Analysis
Regional inventory buffers compress lead times for standard profile dimensions while custom thermal break assemblies extend to 6-10 weeks. Supply concentrates in Germany, Poland, and the Netherlands, with Rhine-Ruhr and Eindhoven serving as extrusion hubs. Raw material dependencies center on PVC resin from naphtha crackers, calcium-zinc stabilizer chemicals, and warm-edge spacer components. Single-source vulnerability in specialized compound formulation creates bottlenecks during REACH recertification waves. Distribution runs through certified fabricator networks serving local installation contractors and regional housing authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across climate-specialized formulations and certification tiers creates niche opportunities as EU Green Deal renovation mandates concentrate procurement authority in fewer buyer organizations.
For Market Incumbents: Secure calcium-zinc stabilizer supply agreements before REACH deadline compression accelerates raw material competition. Deepen backward integration into PVC resin sourcing to defend margin position against naphtha volatility. Acquire coastal-climate formulation expertise to counter Koemmerling's salt-degradation specialization in Portugal and Ireland markets. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany or the Netherlands enables specification access without legacy lead-stabilizer recertification burdens. Target Poland's tilt-and-turn mid-rise construction segment where thermal compliance requirements outpace local compound formulation capacity. Pursue warm-edge spacer integration partnerships with TGI-Spacer or Swisspacer to differentiate in passive house tenders. For Investors and Strategic Acquirers: REACH 2025 stabilizer deadline reshapes the acquisition landscape toward calcium-zinc-ready compound specialists with existing healthcare vertical approvals. Five-to-ten-year viability favors fabricators with social housing framework contracts in France's Hauts-de-France and Île-de-France regions. Monitor EMA plasticizer migration rule extensions into commercial building specifications as inflection signal for healthcare-adjacent building envelope demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVC Resin | Captive supply from naphtha crackers insulates margin from ethylene volatility in German manufacturing. |
| Coastal Climate Formulation Development | Salt degradation resistance exceeding EN 12608 secures specification in Portugal and Ireland markets. |
| Warm-Edge Spacer Technology Integration | Single-source passive house supply converges UPVC extrusion with TGI-Spacer certification requirements. |
| Social Housing Framework Contracting | Decade-scale energy performance contracts in France consolidate procurement authority with certified fabricators. |
| Calcium-Zinc Stabilizer Transition | REACH-compliant compound chemistry maintains specification eligibility in healthcare-adjacent building tenders. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with profile extrusion plant managers, procurement leads at window fabricators, technical R&D directors at compound suppliers, and social housing authority maintenance directors; alongside secondary validation through customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed building products companies, and national building energy code documentation. Bottom-up unit demand modeling triangulated against top-down construction spending forecasts.
Across the projection horizon, the analytical framework modeled volume and value outputs by product type, installation category, end-use sector, and frame design tier. CAGRs derived from regression analysis of historical replacement cycles against regulatory mandate timelines, incorporating KBA code stringency indices and EU Green Deal renovation target trajectories as demand drivers. Passive house certification adoption curves and social housing procurement consolidation patterns served as segment-specific forecast inputs.
Underlying assumptions cover REACH compliance timeline adherence and resin price index stability, with deviation risk concentrated in calcium-zinc stabilizer supply bottlenecks and EMA rule extensions beyond medical-adjacent buildings. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Reclaimed Lumber Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Garage Doors Market
Building & Construction Materials
Glass Curtain Wall Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Temporary Storage Buildings Market
Building & Construction Materials
Roof Coating Market
Building & Construction Materials
Noise Insulation Jackets Market
Building & Construction Materials
Europe Sandwich Panels Market
Building & Construction Materials
Concrete Densifier Market